
 Global Shotcrete/Sprayed Concrete Market | 2026-2036
Global Shotcrete/Sprayed Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shotcrete/Sprayed Concrete Market Foresight
The EU Green Deal is rebalancing material specifications across European infrastructure procurement, forcing contractors to document lifecycle carbon in sprayed concrete submissions. Sika AG leverages its admixture portfolio to serve low-carbon binder systems, while HeidelbergCement anchors supply through its integrated cement network across Alpine tunneling corridors. BASF SE competes on polymer-modified formulations that meet stricter durability clauses in German rail contracts.
Shotcrete, or sprayed concrete, is a pneumatically or hydraulically projected concrete mix applied at high velocity onto vertical or overhead surfaces, typically containing Portland cement, aggregates, and accelerators to achieve rapid early strength within minutes of placement. Its primary purpose is to provide immediate structural support, waterproofing, and ground stabilization in geometries where conventional formwork proves impractical. Wet-mix systems dominate high-volume tunneling for their consistency and reduced rebound, while fiber-reinforced formulations capture margin pools in mining applications where steel or synthetic macro-fibers replace traditional mesh reinforcement. Robotic spraying technology leads growth in hazardous environments, displacing manual nozzle operations where labor safety regulations tighten.
The European Committee for Standardization enforces EN 14487 for sprayed concrete performance, while the EPA oversees silica exposure limits affecting jobsite application protocols in the United States, and Australia's Work Health and Safety regulators mandate dust suppression systems in underground mining deployments. These frameworks elevate product certification costs but simultaneously lock out uncertified suppliers, concentrating procurement among tested manufacturers. Stakeholders must track how embodied carbon disclosure rules migrate from European public works into private mining contracts across Australia and North America.
Market Dynamics
The EU Green Deal's embodied carbon disclosure mandates are forcing procurement departments to requalify entire supplier bases, compressing certification timelines and elevating low-clinker formulation expertise from a niche capability to a table-stakes requirement for European tunneling contracts.
Growth Catalysts
- Alpine tunneling corridors:Germany's underground rail expansion programs specify wet-mix shotcrete for high-volume continuous placement, locking in decade-long material offtake agreements.
- REACH chemical compliance:Accelerated admixture registration under ECHA protocols is filtering out uncertified regional blenders, concentrating procurement among tested multinationals.
- Fiber-reinforced formulations:Australian iron ore operators deploy synthetic macro-fibers for rapid ground support in remote pit operations, displacing welded mesh and shortening re-entry cycles.
Market Restraints
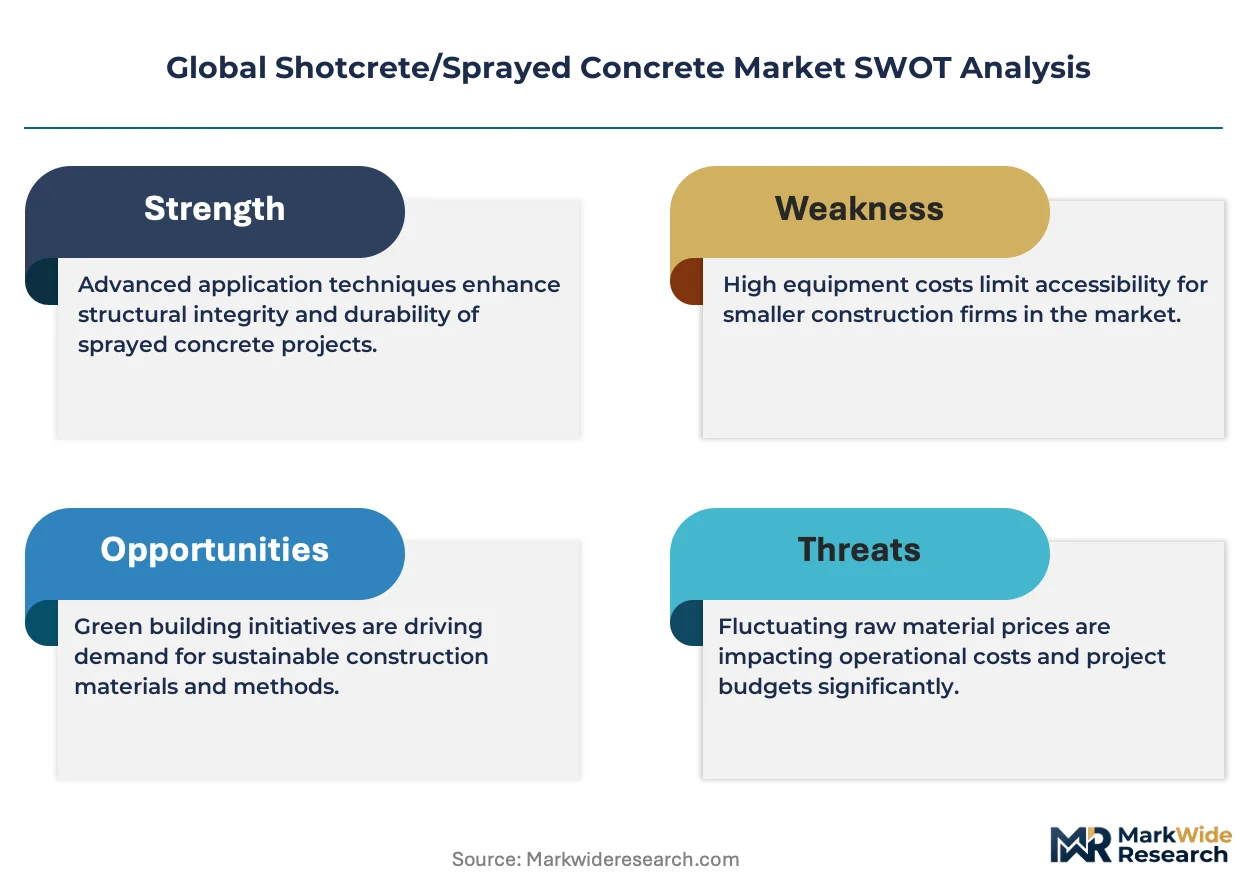
- Portland cement price volatility:Clinker energy costs and carbon border adjustments are squeezing wet-mix margins, particularly for contractors locked into fixed-price infrastructure contracts.
- Silica exposure liability:OSHA and EPA enforcement of respirable crystalline silica limits in the United States is driving up jobsite compliance costs and insurance premiums for manual spraying operations.
- Geographic supply concentration:Alpine cement capacity anchors European shotcrete supply, exposing contractors to single-source risk during peak tunneling seasons.
Strategic Opportunities
- Robotic spraying deployment:Labor safety tightening in Australian underground mining is creating first-mover advantage for autonomous nozzle systems that eliminate manual exposure.
- Carbon-capture binders:EU Green Deal innovation procurement windows are opening for shotcrete formulations with mineralized CO2 content, rewarding early pilot projects in Scandinavian infrastructure.
- Aftermarket service unbundling:Equipment manufacturers are separating robotic system sales from maintenance contracts, creating recurring revenue pools in Chilean copper belt operations.
Industry Challenges
- Nozzle operator skill scarcity:Wet-mix precision demands specialized training that outpaces vocational pipeline output in Germany and Austria, constraining project ramp rates.
- EN 14487 certification timelines:European Committee for Standardization testing protocols extend product approval cycles to 18-24 months, freezing formulation innovation in competitive bidding windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shotcrete/Sprayed Concrete Market |
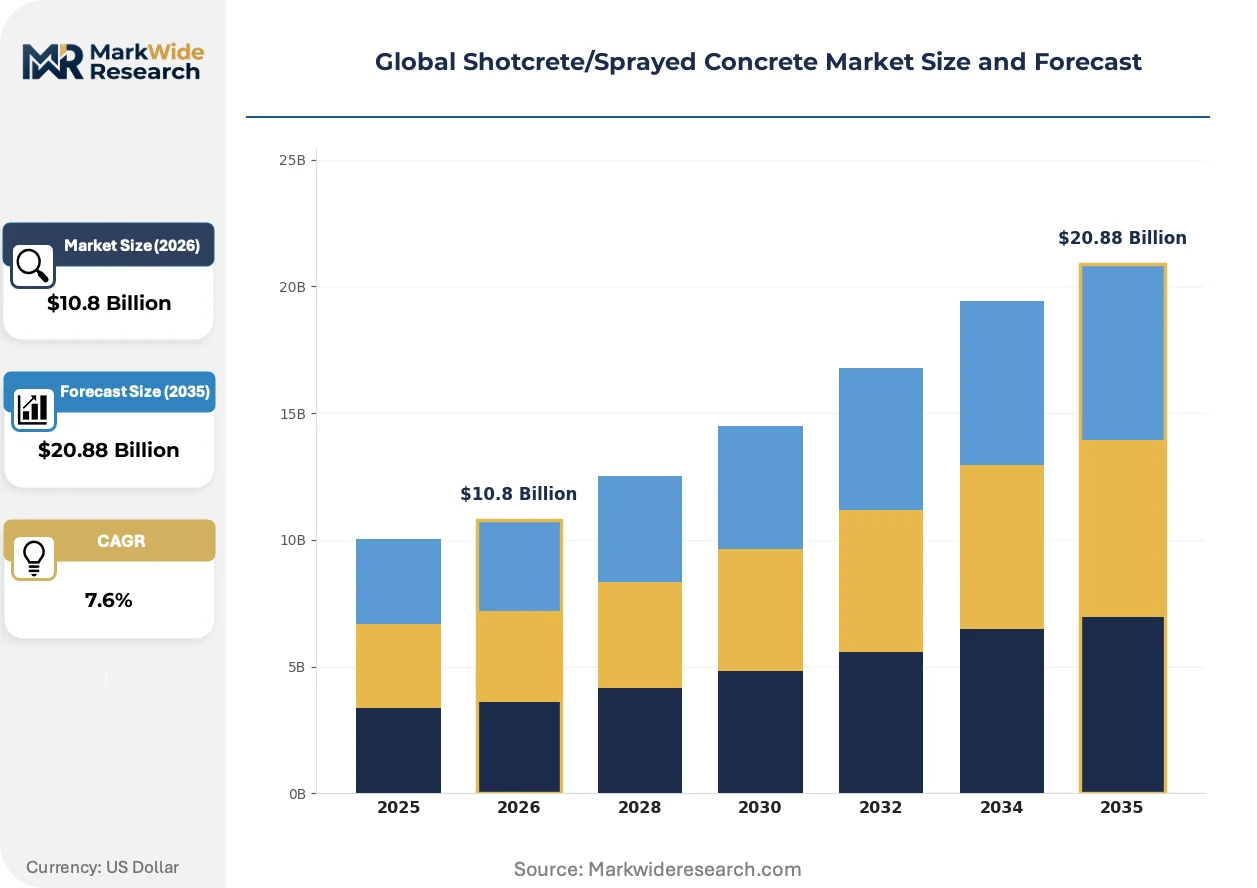
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $20.88 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Dry Mix, Wet Mix, Fiber-Reinforced, Polymer-Modified, Lightweight Application: Tunneling, Slope Stabilization, Structural Repair, Mining, Waterproofing End User: Civil Contractors, Mining Companies, Infrastructure Developers, Water & Wastewater Firms, Bridge Builders Technology: Pneumatic, Hydraulic, Robotic, Manual, Spray Nozzle Systems |
| Companies Covered | Sika AG, BASF SE, HeidelbergCement, CEMEX, Normet Group, Mapei S.p.A, The Euclid Chemical Company, GCP Applied Technologies, Putzmeister, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shotcrete/Sprayed Concrete Market Shifts & Advancements
Shotcrete application is bifurcating between high-automation tunneling workflows and remote mining deployments, with equipment makers and admixture suppliers racing to own the interface between material science and robotic placement.
Robotic spraying technology is consolidating control over hazardous environment applications. Mining operators in Australia and Chile are replacing manual nozzle crews with teleoperated systems to satisfy Work Health and Safety and OSHA exposure limits. This consolidation is compressing the addressable labor pool while elevating equipment utilization rates and technical service contracts.
REACH chemical registration and the EU Green Deal's embodied carbon benchmarks are tightening material specifications simultaneously. ECHA protocols now demand full supply chain disclosure for accelerators and polymers, while public works procurement requires lifecycle carbon documentation. German rail contractors are responding by pre-qualifying only suppliers with integrated low-clinker binder systems and verified environmental product declarations.
Buyer concentration in Australian iron ore and Chilean copper is compressing supplier negotiation leverage. Tier-one miners are unbundling shotcrete supply from ground support contracts, forcing material producers to compete directly on unit cost and technical service rather than packaged solutions. This disintermediation is most visible in Pilbara operations, where BHP and Rio Tinto have separated admixture procurement from application subcontracting.
Global Shotcrete/Sprayed Concrete Market Segmentation
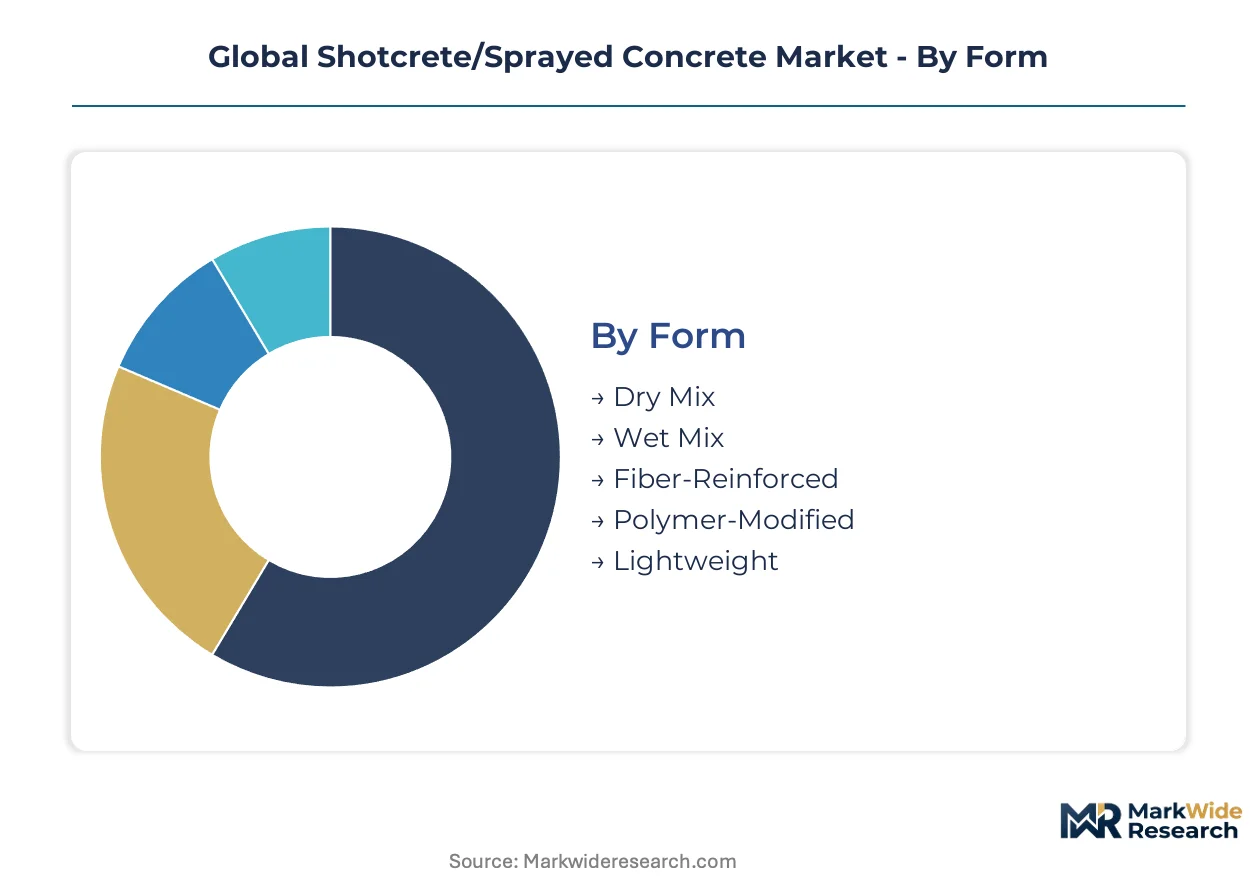
Shotcrete market segmentation reveals how material form, application context, and placement technology intersect to determine procurement patterns. Contractors select formulations based on structural load requirements, environmental exposure, and labor availability, while equipment choices reflect safety mandates and project scale.
Form:
Dry-mix systems operate as standalone batch operations at remote sites; wet-mix and fiber-reinforced variants embed into continuous tunneling workflows with integrated admixture dosing.
- Wet Mix:Pre-blended concrete with water added at the batch plant delivers consistent rheology and reduced rebound for high-volume Alpine tunneling. German rail contractors specify wet-mix for decade-long underground expansion programs requiring continuous placement.
- Fiber-Reinforced:Steel or synthetic macro-fibers displace welded mesh reinforcement to accelerate re-entry cycles in ground support applications. Australian iron ore operators in the Pilbara deploy synthetic fiber shotcrete for rapid stabilization of remote pit walls.
- Dry Mix:Cement and dry aggregates mixed at the nozzle suit small-scale repairs and remote locations lacking batch plant infrastructure.
- Polymer-Modified:Latex or epoxy additions enhance adhesion and waterproofing for structural repair and marine exposure zones.
- Lightweight:Expanded shale or perlite aggregates reduce dead loads for overhead repairs and seismic retrofit applications.
Wet mix leads volumes today; fiber-reinforced is gaining share fastest.
Application:
Cost tiering separates capital-intensive tunneling from maintenance-driven repair work, with mining and waterproofing occupying distinct margin bands.
- Tunneling:Primary ground support and final lining for underground transportation infrastructure demands EN 14487-certified performance grades. Alpine corridor projects lock in multi-year material offtake agreements.
- Mining:Rapid ground support in hard-rock extraction requires fiber-reinforced formulations with early strength development for re-entry safety. Chilean copper belt operators unbundle shotcrete supply from ground support contracts.
- Slope Stabilization:Rockfall protection and embankment reinforcement utilize mesh-anchored shotcrete for highway and railway cuttings.
- Structural Repair:Bridge soffits, parking garages, and building facades receive polymer-modified overlays for chloride protection and carbonation resistance.
- Waterproofing:Tunnel membranes and basement walls employ crystalline admixture systems for hydrostatic pressure resistance.
Tunneling commands the premium tier; mining is climbing the fastest.
End User:
Customer type determines procurement leverage, with tier-one miners consolidating volumes against fragmented civil contracting.
- Mining Companies:BHP and Rio Tinto in Australia separate admixture procurement from application subcontracting, forcing direct price competition on unit cost. Work Health and Safety regulations mandate dust suppression in underground deployments.
- Civil Contractors:German rail and highway specialists face EU Green Deal embodied carbon disclosure mandates that requalify supplier bases and compress certification timelines.
- Infrastructure Developers:Public-private partnerships for urban transit specify lifecycle performance warranties extending beyond construction completion.
- Water & Wastewater Firms:Sewage treatment structures and potable water reservoirs require low-permeability formulations resistant to biogenic sulfuric acid attack.
- Bridge Builders:Deck overlays and substructure repairs prioritize rapid return-to-service formulations for traffic management.
Mining companies concentrate procurement power; infrastructure developers are expanding specification scope.
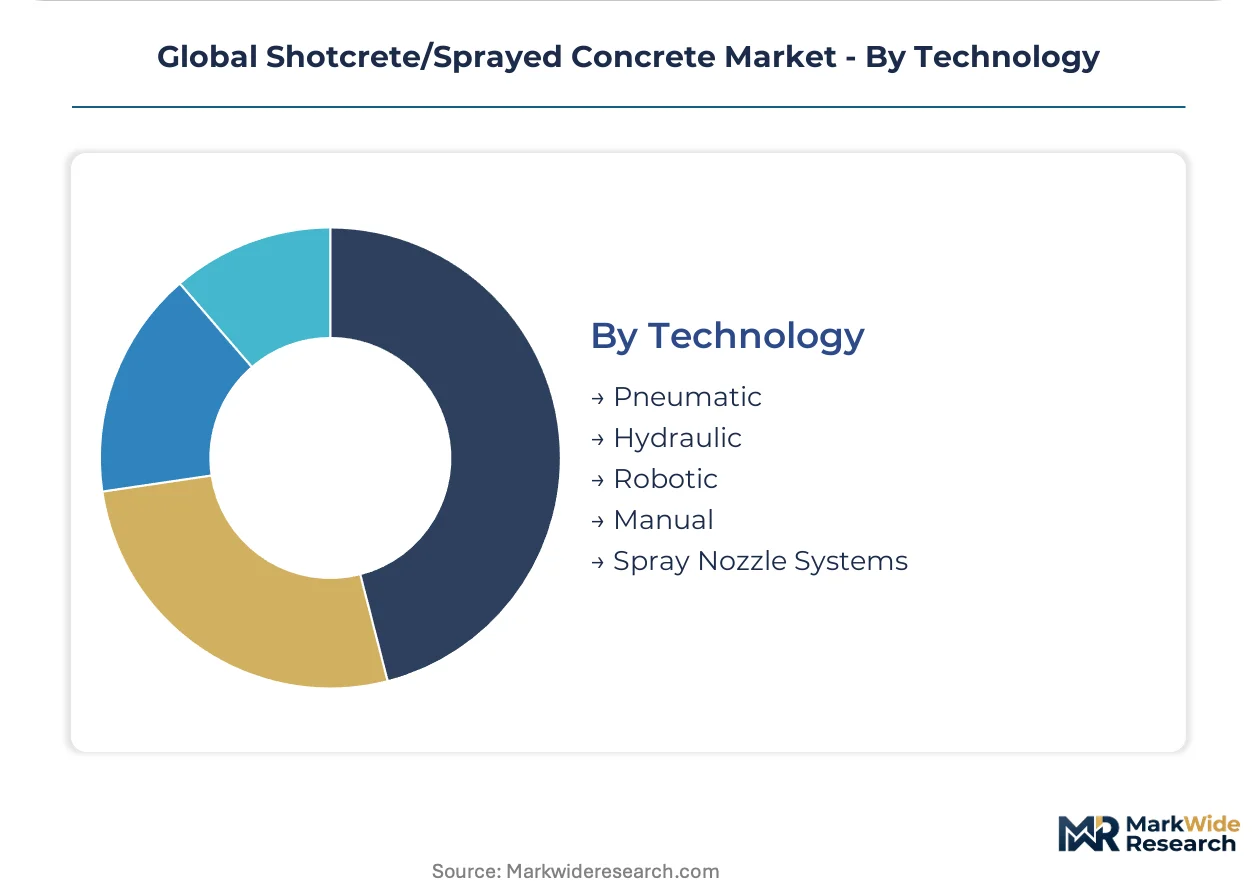
Technology:
Maturity gradients separate established pneumatic methods from emerging robotic systems, with regulatory pressure accelerating automation adoption.
- Robotic:Teleoperated nozzle systems eliminate manual exposure in hazardous underground environments. Australian and Chilean mining operators deploy autonomous spraying to satisfy tightening OSHA and Work Health and Safety silica limits.
- Pneumatic:Compressed air projection remains dominant for dry-mix applications in remote locations lacking hydraulic infrastructure.
- Hydraulic:Pump-driven wet-mix delivery achieves higher placement rates for continuous tunneling workflows.
- Manual:Hand-held nozzle operations persist in confined access repairs but face rising insurance premiums and labor scarcity.
- Spray Nozzle Systems:Specialized atomizing designs optimize particle distribution and reduce rebound for vertical and overhead surfaces.
Pneumatic and hydraulic systems anchor installed base; robotic is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shotcrete technology originated in Pennsylvania coal mines during the early 1900s, where Carl Akeley's cement gun first demonstrated pneumatic concrete placement. The technique migrated to European Alpine tunneling by mid-century, establishing the geographic pattern of innovation diffusion that persists today.
Germany
Alpine corridor rail expansions drive wet-mix demand through Bavaria and Baden-Württemberg. The EU Green Deal forces contractors to document embodied carbon in every sprayed concrete submission. Sika AG anchors supply from its Stuttgart-region admixture operations.
Australia
Pilbara iron ore operators deploy fiber-reinforced formulations for rapid ground support in remote pit operations. Work Health and Safety regulators mandate dust suppression systems underground. BHP and Rio Tinto have unbundled shotcrete procurement from application subcontracting.
United States
OSHA silica exposure enforcement elevates compliance costs for manual spraying operations across Appalachian mining and Western tunneling projects. EPA oversight extends to jobsite application protocols. Equipment utilization rates climb as contractors replace nozzle crews with teleoperated systems.
Chile
Copper belt mining concentrates procurement power among tier-one operators separating material supply from ground support contracts. ANVISA-equivalent mining safety frameworks tighten exposure limits. Antofagasta and Calama clusters see first-mover deployment of autonomous spraying technology.
China
Western infrastructure expansion and high-speed rail tunneling absorb wet-mix volumes through Sichuan-Chongqing and Shandong Peninsula construction corridors. GB standards govern sprayed concrete performance in transportation projects. State-owned cement networks anchor supply through integrated batch plant infrastructure.
Global Shotcrete/Sprayed Concrete Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification depth. The vendor base stratifies between integrated cement-admixture systems and standalone equipment fabricators. Three archetypes dominate: multinational chemical conglomerates with admixture portfolios, integrated cement producers with captive shotcrete supply, and specialized spraying equipment manufacturers. Competitive moves concentrate on robotic system deployment partnerships and low-carbon binder pre-qualification for EU procurement windows.
Among Swiss and German chemical specialists, Sika AG and BASF SE exemplify the premium-formulation tier, anchoring competitive positioning through integrated admixture capabilities. HeidelbergCement represents the integrated cement archetype, leveraging captive clinker supply across European tunneling corridors. These three occupy positions that bridge material science and placement technology, reflecting the industry convergence around carbon-disclosed, robotically applied systems.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| HeidelbergCement |
| CEMEX |
| Normet Group |
| Mapei S.p.A |
| The Euclid Chemical Company |
| GCP Applied Technologies |
| Putzmeister |
| Others |
Supply & Pricing Matrix
Clinker energy cost indices cascade through shotcrete supply chains, compressing wet-mix margins for contractors locked into fixed-price German rail contracts while elevating low-clinker formulation premiums. This input-price volatility stratifies procurement power between integrated cement networks and standalone blenders.
Pricing Analysis
Three-tier pricing structure across EN 14487-certified premium grades, standard wet-mix formulations, and economy dry-mix tiers separates procurement pools. Certification depth and fiber-reinforcement density drive price differentiation, with robotic application bundles commanding service premiums. Cost compression in standard wet-mix is intensifying because Portland cement price volatility and carbon border adjustments squeeze contractor margins. Mining companies in Australia exhibit lowest price sensitivity due to unbundled procurement and re-entry cycle economics, while civil contractors in Germany face acute sensitivity from fixed-price infrastructure commitments.
Supply Chain Analysis
Portland cement supply rests on integrated production clusters in Germany, China, and Australia, with specialty admixture production concentrated in Swiss and German chemical corridors. Synthetic macro-fibers draw from polymer supply chains anchored in European and Asian petrochemical networks, while accelerator chemicals hinge on ECHA-registered specialty producers. Single-source vulnerability concentrates in Alpine cement capacity during peak tunneling seasons. Distribution runs through project-site batch plant networks for wet-mix, with dry-mix penetrating remote mining locations via packaged material logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU carbon disclosure premiums and Australian mining procurement scale, with regulatory compliance cost differentials exceeding formulation cost gaps across corridors.
For Market Incumbents: Anchor defensive positioning through backward integration into low-clinker binder systems and captive EN 14487 certification pipelines, neutralizing emerging threats from ECHA-registered regional blenders and carbon border adjustment margin compression. Prioritize robotic spraying service contracts in Australian and Chilean mining clusters to lock in utilization-based recurring revenue against equipment commoditization. For New Entrants and Emerging Players: Capture white-space in aftermarket robotic maintenance unbundling for Chilean copper belt operations and carbon-capture binder pilot procurement under EU Green Deal innovation windows. The most penetrable entry point sits with Scandinavian infrastructure authorities soliciting mineralized CO2 content formulations, approached through technical partnership rather than direct material supply. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized spraying equipment manufacturers possessing autonomous nozzle IP and established mining safety compliance records. Long-term viability over the projection horizon favors targets with installed base density in Australian Work Health and Safety jurisdictions and technical service contract recurrence. Watch EN 14487 certification timeline compression as the inflection signal for formulation innovation lock-in versus commodity blending.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Clinker Binders | HeidelbergCement anchors supply security across Alpine tunneling corridors against carbon border exposure. |
| Robotic Spraying Deployment Partnerships | Normet Group captures Australian mining safety mandates through teleoperated system utilization contracts. |
| EN 14487 Certification Pipeline Investment | Sika AG locks out uncertified regional blenders from German rail procurement windows. |
| Carbon-Capture Binder Pilot Programs | EU Green Deal innovation procurement rewards early Scandinavian infrastructure project participation. |
| Aftermarket Service Unbundling | Equipment manufacturers separate robotic sales from maintenance to capture Chilean copper belt recurring revenue. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tunneling contractors, mining procurement leads, admixture technical directors, and robotic equipment service heads with secondary validation against ECHA registration databases, EU public procurement portals, SEC filings from listed cement producers, and Australian Work Health and Safety incident reports. Bottom-up volume modeling across wet-mix, fiber-reinforced, and dry-mix form categories triangulated against top-down cement consumption forecasts.
Segment-weighting applied form, application, end user, and technology dimensions across the modeling period, with tunneling and mining shares calibrated to infrastructure project pipelines and mineral extraction schedules. CAGRs derived from historical placement volume trends, project completion timelines, and regulatory adoption curves for robotic systems and low-carbon formulations. Forecast inputs incorporated EN 14487 certification lag effects and REACH chemical registration compliance thresholds.
Portland cement price volatility, ECHA regulatory timeline shifts, and mining safety mandate acceleration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on project pipeline conversion rates and technology adoption S-curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Chain Link Fencing Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Global Screw Piles Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
North America Balustrade Market