
 GCC Kitchen Hood Market | 2026-2036
GCC Kitchen Hood Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Kitchen Hood Market Foresight
Specialty kitchen retail channels across the Gulf Cooperation Council is reconfiguring how manufacturers reach end buyers, with showrooms and e-commerce platforms gaining share from traditional trade. Bosch leverages its appliance ecosystem to sustain premium positioning in Saudi Arabia, while Elica Group anchors its regional presence through Italian design credentials and localized distribution partnerships. Kitchen King competes aggressively on price across mid-tier residential projects in the UAE, differentiating through rapid installation services and after-sales coverage.
A kitchen hood is a mechanical ventilation device installed above cooking surfaces, typically featuring grease filters, blower motors rated between 200 and 1200 cubic meters per hour, and ducting or charcoal filtration systems designed to extract airborne contaminants, heat, and odors from food preparation zones. Wall-mounted units dominate GCC residential installations due to compatibility with standard kitchen layouts and established contractor preferences, while island hoods command higher margins in luxury developments where open-plan designs predominate. Ducted technology leads commercial and hospitality segments across Dubai and Riyadh because building codes mandate external exhaust for high-volume cooking operations, whereas recirculating systems occupy compact apartment kitchens where structural ducting proves impractical.
Gulf Standardization Organization (GSO) technical regulations govern electrical safety and energy efficiency labeling for kitchen hoods sold across member states, while Saudi Standards, Metrology and Quality Organization (SASO) enforces additional efficiency requirements that filter non-compliant imports from entering the Kingdom. Dubai Municipality's Green Building Regulations push hospitality developers toward perimeter extraction technologies that reduce HVAC load in commercial kitchens. Stakeholders must monitor evolving SASO efficiency tiers and Estidama material specifications before committing to regional manufacturing partnerships or product line investments.
Market Dynamics
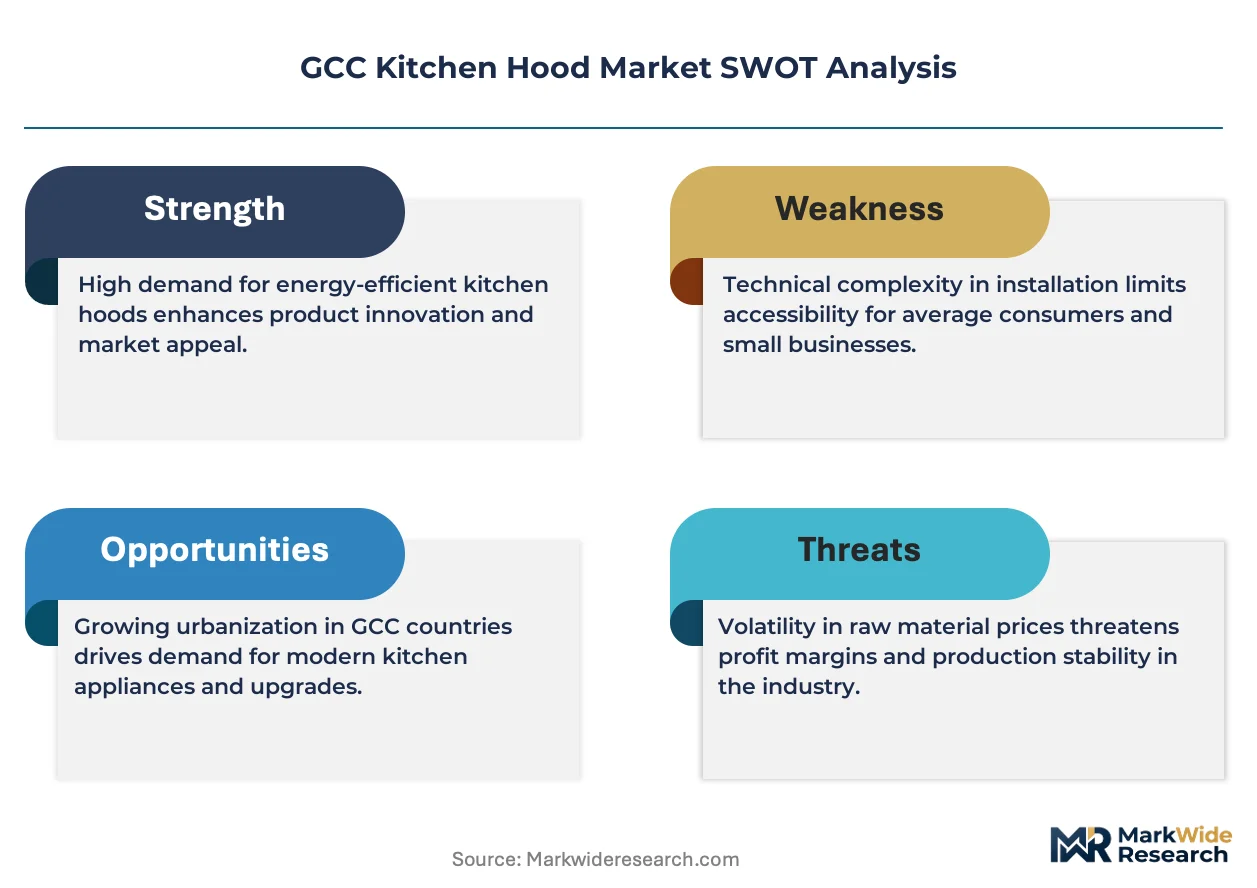
Saudi Arabia's luxury villa construction pipeline and the UAE's Estidama green building mandates are compressing procurement cycles for high-performance ducted systems across the Gulf Cooperation Council.
Growth Catalysts
- Estidama Pearl Rating System:Abu Dhabi's mandatory green building framework mandates energy-efficient kitchen ventilation in new hospitality developments, accelerating specification of perimeter extraction technologies that reduce HVAC loads.
- Qatar's hospitality expansion:FIFA World Cup legacy projects and new hotel developments in Doha require commercial-grade ducted hoods compliant with high-volume cooking exhaust codes.
- Smart filtration sensors:IoT-enabled grease saturation monitors are penetrating premium residential segments in Dubai, enabling predictive maintenance contracts and recurring revenue streams for installers.
Market Restraints
- Stainless steel price volatility:Input cost swings for 304-grade steel constrain margin stability for mid-tier manufacturers serving UAE residential contractors.
- Single-source blower motor supply:European motor suppliers dominate 800+ CFM commercial-grade components, creating vulnerability for Saudi-based assembly operations.
- Structural ducting limitations:Concrete core drilling restrictions in older Dubai high-rises block retrofit installations, capping addressable volume in established residential stock.
Strategic Opportunities
- Kuwait's underserved retail channel:Specialist kitchen showrooms remain underdeveloped in Kuwait City relative to Dubai and Riyadh, presenting first-mover positioning for organized distribution networks.
- SASO efficiency tier upgrades:Upcoming revisions to Saudi Standards, Metrology and Quality Organization energy labels will disqualify entry-level imports, opening share for compliant regional manufacturers.
- Voice-activated controls:Integration with home automation ecosystems is migrating from luxury to mainstream segments, enabling premium pricing in Bahrain's expatriate housing developments.
Industry Challenges
- Certified installation technician scarcity:Proper ducted system commissioning requires Gulf Standardization Organization electrical competency credentials that remain concentrated among Dubai and Riyadh contractor pools.
- Cross-border warranty fulfillment:Multi-country service coverage for GCC-wide project developers demands localized spare parts stocking that strains working capital for smaller distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Kitchen Hood Market |
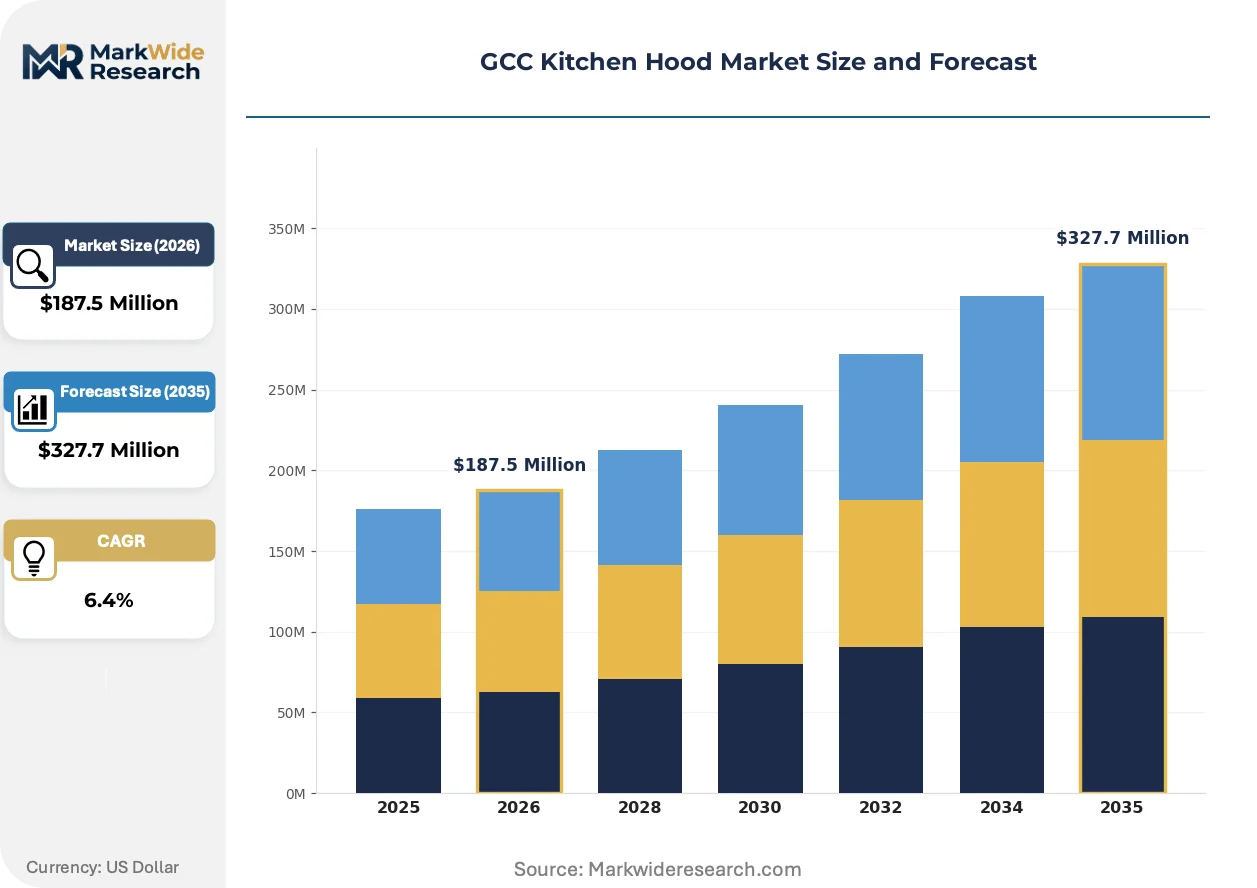
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $327.7 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Under-Cabinet, Island, Downdraft Technology: Recirculating, Ducted, Hybrid, Perimeter End User: Residential, Commercial, Hospitality, Industrial Material: Stainless Steel, Glass, Aluminium, Composite |
| Companies Covered | LG, Electrolux, Bosch, Kitchen Line, Hacker Kitchens, Hafele, Inter Ikea Group, Kitchen King, Elica Group, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Kitchen Hood Market Shifts & Advancements
Perimeter extraction architectures and sensor-enabled maintenance models are reconfiguring how ventilation systems integrate with broader building management infrastructure across Gulf hospitality and residential developments.
Brushless DC motor technology is migrating from premium island hoods to wall-mounted residential units, delivering 30-40% energy savings over AC alternatives. Saudi luxury villa developers are specifying these motors as standard to meet SASO efficiency thresholds. The technology is migrating from niche positioning to mid-tier product lines as Chinese motor suppliers achieve scale in 600-900 CFM outputs.
Dubai Municipality's Green Building Regulations now mandate heat recovery ventilation in commercial kitchen exhaust systems, forcing hospitality developers toward perimeter extraction designs that capture grease at source. Kitchen consultants in Riyadh are adopting similar specifications preemptively ahead of anticipated SASO alignment. This regulatory convergence is compressing demand for traditional canopy hoods in new-build projects.
Specialty kitchen showrooms are displacing general trade distributors as the primary specification channel for villa owners and interior designers. Bosch and Elica Group have invested in Dubai Design District and Riyadh showroom presence to intercept project decisions before contractor procurement. This channel migration concentrates margin capture with brands that control end-user touchpoints rather than wholesale relationships.
GCC Kitchen Hood Market Segmentation
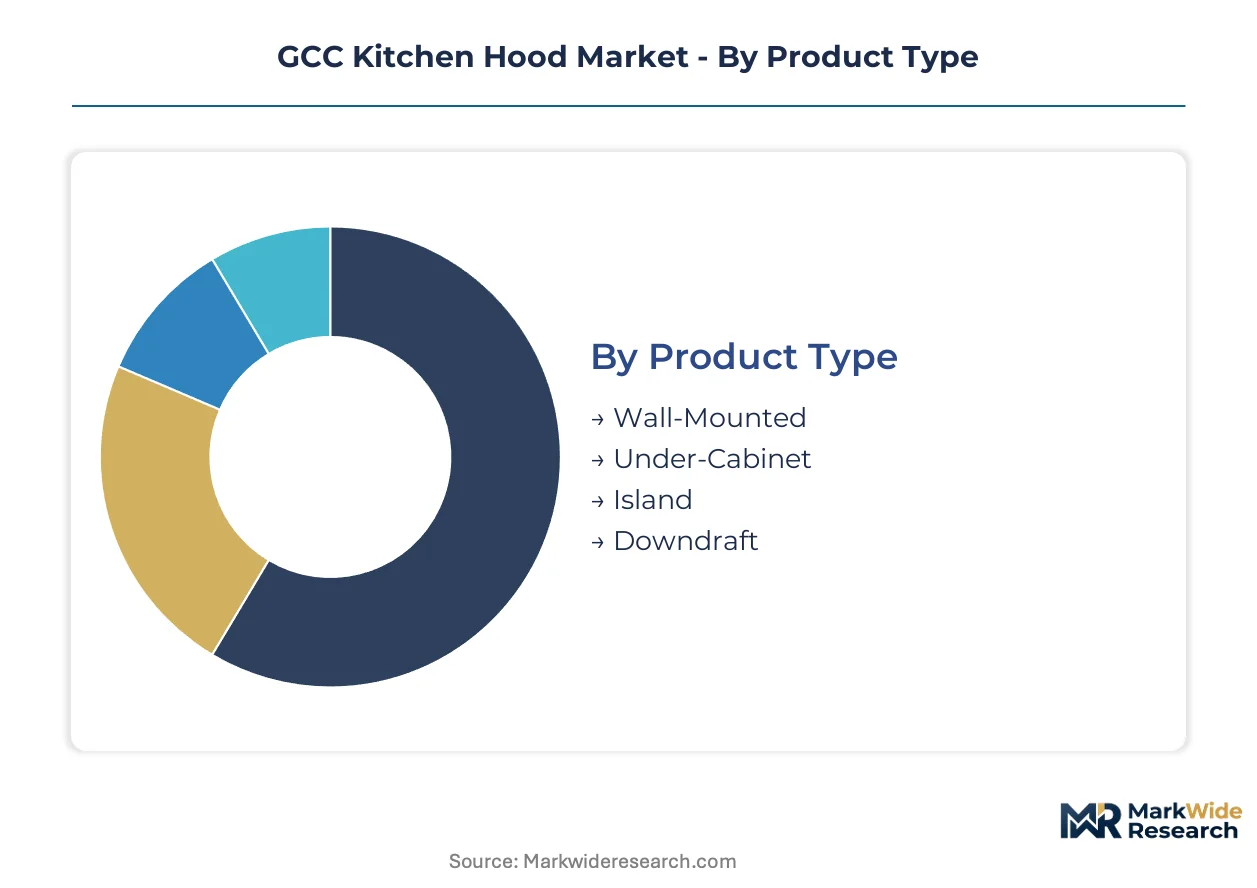
Segmentation in the GCC kitchen hood market reveals distinct after-sales service requirements across product tiers, with ducted systems demanding certified commissioning and recirculating units requiring filter replacement programs. Understanding these service intensity patterns helps manufacturers allocate technical support resources and design distribution partnerships that match segment-specific maintenance obligations.
Product Type:
After-sales service intensity varies sharply across installation configurations, with island hoods requiring specialized ceiling-mount technicians and under-cabinet units depending on general contractor labor pools.
- Wall-Mounted:These units attach directly to vertical kitchen surfaces and typically feature 600-900 CFM blower configurations with baffle or mesh filtration systems. Demand concentrates in Riyadh's luxury villa developments where Saudi contractors favor standardized layouts compatible with established installation protocols. The segment generates recurring filter replacement revenue through annual maintenance contracts.
- Island:Ceiling-suspended extraction systems designed for open-plan kitchens require structural engineering assessment and specialized mounting hardware. Dubai's high-end residential towers specify these units for penthouse layouts, with developers absorbing extended warranty costs to secure performance guarantees. Installation complexity drives 3-4x higher service call rates versus wall-mounted alternatives.
- Under-Cabinet:Compact units integrated into overhead cabinetry serve space-constrained apartments across Bahrain's expatriate housing stock.
- Downdraft:Retractable surface-integrated ventilation targets premium kitchen islands where overhead extraction conflicts with architectural sightlines.
By volume, Wall-Mounted leads. By growth pace, Island is ahead.
Technology:
Cost tier stratification separates basic recirculating systems from premium perimeter extraction, with mid-market ducted configurations capturing the largest addressable base across GCC residential renovations.
- Ducted:External exhaust systems channel grease-laden air through building infrastructure to outdoor termination points, requiring blower motors rated 800-1200 CFM for commercial compliance. Abu Dhabi's Estidama Pearl Rating System mandates these technologies for new hospitality developments, with perimeter variants reducing HVAC energy loads through source-capture architecture. Dubai Municipality green building codes reinforce specification dominance in commercial segments.
- Perimeter:Advanced extraction architectures position suction apertures at hood edges rather than center points, improving capture efficiency for high-volume cooking operations. Qatar's FIFA World Cup legacy hotel projects specified these systems preemptively to meet anticipated regulatory alignment with UAE standards. The technology commands 40-60% price premiums over conventional canopy designs.
- Recirculating:Charcoal filtration systems suit Kuwait's older residential stock where concrete core drilling restrictions block ducted retrofits.
- Hybrid:Convertible configurations allow field-switching between ducted and recirculating modes, appealing to UAE developers hedging against uncertain tenant fit-out requirements.
By volume, Ducted leads. By margin expansion, Perimeter is climbing the fastest.
End User:
Application-specific performance standards create divergent procurement cycles, with hospitality projects requiring 18-24 month specification lead times versus 4-8 week residential replacement cycles.
- Residential:Villa owners and apartment dwellers prioritize aesthetic integration and noise reduction over extraction capacity, typically specifying 400-700 CFM systems. Saudi Arabia's luxury construction pipeline drives specification of smart-enabled units with IoT grease saturation monitoring, particularly in Riyadh's diplomatic quarter developments. Post-installation service contracts remain underpenetrated relative to European benchmarks.
- Hospitality:Hotels, restaurants, and catering facilities require commercial-grade systems compliant with fire safety and ventilation codes governing high-temperature grease exhaust. Doha's post-World Cup hotel expansion created concentrated demand for 1200+ CFM perimeter extraction systems with automated wash-down cycles. Procurement decisions involve kitchen consultants and MEP engineers 12-18 months before equipment delivery.
- Commercial:Non-hospitality food service operations including corporate cafeterias and institutional kitchens represent a price-sensitive mid-tier segment.
- Industrial:Heavy-duty extraction for central production kitchens and food manufacturing facilities requires custom-engineered canopy systems.
By volume, Residential leads. By project value concentration, Hospitality is gaining share fastest.
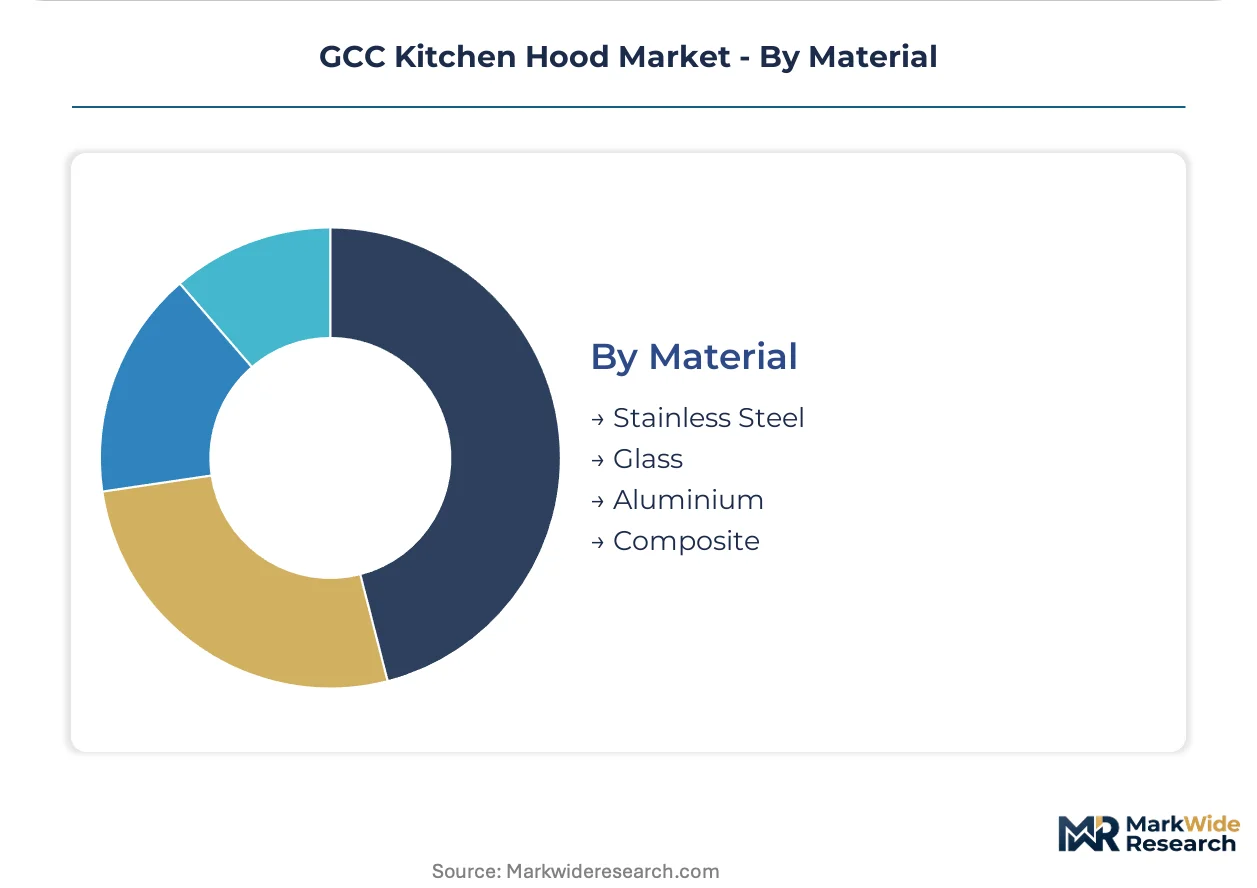
Material:
Supply concentration in stainless steel processing shapes regional manufacturing economics, with 304-grade sheet availability determining lead times for mid-tier product lines.
- Stainless Steel:304-grade and 430-grade alloys dominate GCC commercial installations due to corrosion resistance in high-humidity kitchen environments and compliance with Dubai Municipality surface finish requirements. Saudi assembly operations source processed sheet from UAE distributors, creating working capital intensity for inventory-heavy production models. Price volatility in nickel and chromium inputs constrains margin stability.
- Glass:Tempered and curved glass canopy surfaces enable aesthetic differentiation in Dubai's premium residential towers, where developers specify statement kitchen elements for marketing differentiation. Surface coating technologies resist grease adhesion and simplify cleaning protocols. The material commands 25-35% finished product premiums over steel equivalents.
- Aluminium:Lightweight extrusions serve cost-optimized residential segments across Kuwait's contractor-driven market.
- Composite:Engineered material blends combining thermal properties with design flexibility target niche architectural specifications.
By volume, Stainless Steel leads. By design premium capture, Glass shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Fahd Causeway connects Saudi Arabia and Bahrain, enabling cross-border logistics for kitchen appliance distribution across the eastern Gulf. Jebel Ali Port in Dubai anchors regional import flows for premium ventilation equipment serving hospitality and residential construction.
Saudi Arabia
Riyadh's luxury villa construction pipeline and NEOM giga-projects drive specification of high-CFM ducted systems. SASO enforces energy efficiency tiers that filter non-compliant imports. Eastern Province industrial zones host assembly operations sourcing processed steel from UAE distributors.
United Arab Emirates
Dubai's high-end residential towers and Abu Dhabi hospitality developments require perimeter extraction technologies. Estidama Pearl Rating System mandates energy-efficient ventilation in new builds. Dubai Design District clusters showroom investments from premium brands intercepting project decisions.
Qatar
Doha's post-World Cup hotel expansion sustains demand for commercial-grade hoods with automated wash-down cycles. Qatar General Organization for Standardization aligns with Gulf Standardization Organization technical regulations. Lusail City developments specify advanced extraction for high-volume catering operations.
Kuwait
Kuwait City's underdeveloped specialist kitchen retail channel presents distribution gaps relative to Dubai and Riyadh. Ministry of Commerce and Industry oversees import standards for electrical appliances. Older residential stock in Salmiya and Hawalli limits ducted retrofits due to concrete core drilling restrictions.
Bahrain
Expatriate housing developments in Manama and Riffa drive mid-tier demand for voice-activated smart controls. Bahrain Standards and Metrology Directorate enforces GSO electrical safety regulations. King Fahd Causeway logistics corridors enable Saudi suppliers to serve Bahraini contractors competitively.
GCC Kitchen Hood Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying motors, filtration media, and control modules. The GCC kitchen hood market structures around three tiers: global appliance conglomerates with regional subsidiaries, European design-led specialists with localized distribution, and regional assemblers competing on price and installation speed. Consolidation pressures concentrate among mid-tier players as efficiency regulations raise compliance costs. Dominant competitive moves include showroom network expansion in design districts and strategic partnerships with MEP contractors for hospitality project access.
Among global appliance conglomerates, Bosch and LG represent platform integrators leveraging ecosystem breadth for premium positioning. Elica Group exemplifies the European design-specialist archetype, anchoring regional presence through Italian manufacturing credentials and showroom investments. Kitchen King occupies the regional assembler tier, competing on rapid installation services and after-sales coverage across mid-tier UAE residential projects.
| Leading Market Players |
|---|
| LG |
| Electrolux |
| Bosch |
| Kitchen Line |
| Hacker Kitchens |
| Hafele |
| Inter Ikea Group |
| Kitchen King |
| Elica Group |
| Others |
Supply & Pricing Matrix
Single-source blower motor dependency on European suppliers for 800+ CFM commercial-grade components compresses margin stability for Saudi assembly operations while simultaneously widening price spreads between certified ducted systems and entry-level recirculating alternatives. This structural bottleneck forces regional manufacturers to absorb working capital intensity or surrender share to importers with established supplier relationships.
Pricing Analysis
Volume-discount tiering structures separate hospitality procurement at 1200+ CFM specifications from residential replacement cycles. Three-tier pricing stratification across premium perimeter extraction, standard ducted configurations, and economy recirculating units reflects SASO efficiency certification levels and after-sales bundling intensity. Pricing pressure stems from stainless steel input volatility, with 304-grade sheet fluctuations constraining mid-tier manufacturer margins. Residential contractors in Kuwait exhibit highest price sensitivity, while Dubai hospitality developers absorb premium positioning for Estidama compliance.
Supply Chain Analysis
Upstream feedstock flows for processed stainless steel sheet concentrate in UAE distributors serving Saudi assembly operations, while brushless DC motor technology draws from Chinese suppliers achieving scale in 600-900 CFM outputs. Raw material dependencies center on nickel and chromium inputs for 304-grade alloys, European blower motor components, and tempered glass canopy surfaces. Single-source vulnerability in commercial-grade motor supply creates procurement risk for Riyadh-based manufacturers. Distribution runs through Jebel Ali Port anchoring regional import flows, with specialty kitchen showrooms displacing wholesale channels for end-user specification capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC kitchen hood demand tracks construction cycle recovery, with Saudi luxury villa pipelines and Qatar hospitality expansion providing cyclical momentum through the analysis window.
For Market Incumbents: Harden supply chain resilience through backward integration into brushless DC motor sourcing or captive UAE steel processing partnerships. SASO efficiency tier upgrades threaten entry-level import share, creating defensive certification investment requirements. Channel control through Dubai Design District showroom expansion intercepts project specifications before contractor procurement cycles commence. For New Entrants and Emerging Players: Kuwait City's underdeveloped specialist kitchen retail channel presents first-mover distribution positioning against established Dubai and Riyadh networks. Voice-activated smart control integration targets Bahrain's expatriate housing developments with premium pricing acceptance. Rapid installation service capabilities differentiate against incumbent lead time structures in mid-tier UAE residential projects. For Investors and Strategic Acquirers: The market sits at a regulatory tightening phase that favors compliant regional manufacturers with SASO certification infrastructure already deployed. Long-term viability rests on perimeter extraction technology migration and IoT-enabled maintenance contract recurring revenue capture. Watch for Estidama alignment announcements from Saudi regulators as inflection signal for specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Showroom Network Expansion | Bosch and Elica Group investments in Dubai Design District intercept villa owner decisions before contractor involvement. |
| Perimeter Extraction Technology Licensing | Source-capture architectures reduce HVAC loads for Abu Dhabi hospitality developers under Estidama mandates. |
| Brushless DC Motor Supply Agreement | Chinese motor suppliers achieving 600-900 CFM scale enable SASO efficiency compliance at mid-tier price points. |
| Predictive Maintenance Platform Launch | IoT grease saturation monitors in Dubai premium residential segments generate recurring installer revenue streams. |
| Cross-Border Service Partnership | Multi-country warranty fulfillment addresses GCC-wide project developer requirements through localized spare parts stocking. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with kitchen consultants, MEP contractors, hospitality procurement managers, and specialty showroom operators; and secondary validation through GSO technical regulations, SASO efficiency tier documentation, Dubai Municipality green building filings, and customs import records. Bottom-up segmentation modeling triangulated against top-down construction pipeline assessments across Saudi Arabia, UAE, Qatar, Kuwait, and Bahrain.
Forecast inputs considered product type configurations, technology tiers, end-user application requirements, and material specifications across the projection horizon. CAGRs derived from weighted scenario analysis incorporating regulatory compliance timelines, hospitality project completion schedules, and residential renovation cycle patterns. Brushless DC motor adoption curves and perimeter extraction specification rates served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive showroom expansion or vertical integration moves by European design specialists would shift competitive outcomes. Material shifts in SASO efficiency tier implementation schedules or Estidama regulatory alignment across additional GCC states would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
US Residential Furnace Market
HVAC Equipment
Air Conditioning Systems Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Asia-Pacific Compressor Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
Centrifugal Fan Wheels Market