
 Building Downpipe Market | 2026-2036
Building Downpipe Market Size, Share, and Industry Trends Forecast 2026-2036
Building Downpipe Market Insights
Modular gutter-and-downpipe bundling is consolidating buyer choice across the Australian construction supply chain. Aliaxis leverages its polymer manufacturing depth to dominate standardized PVC configurations for volume residential projects. Stratco anchors the metal segment with galvanized steel and aluminum systems engineered for coastal corrosion resistance. Saint-Gobain competes through technical leadership in high-performance composite materials that extend product lifecycles in extreme weather zones.
Building downpipes are vertical drainage conduits, typically manufactured from PVC, aluminum, or galvanized steel in diameters ranging from 50mm to 150mm, engineered to channel rainwater from roof gutters to ground-level drainage or storage systems. Their primary purpose is to prevent structural water damage, soil erosion, and foundation deterioration in built environments. PVC downpipes occupy the largest volume share due to cost efficiency and ease of installation across residential end users, while aluminum systems command premium positioning in commercial complexes where aesthetic integration and longevity drive specification. Recessed and concealed installation types represent the fastest-growing configuration as architects prioritize clean facade lines in hospitality venues and high-density residential towers.
Australia's Building Code of Australia (BCA) and state-level plumbing regulations administered by the Victorian Building Authority and NSW Department of Customer Service mandate minimum hydraulic performance and material durability standards for stormwater systems. These frameworks directly shape product certification requirements and installer licensing, creating compliance barriers for uncertified imports. The EPA's stormwater quality guidelines in multiple states further tighten environmental discharge standards, pushing demand toward higher-capacity systems with integrated filtration. Stakeholders must monitor evolving state-level variations in plumbing codes and assess whether material portfolios align with impending bushfire resistance and cyclone rating amendments.
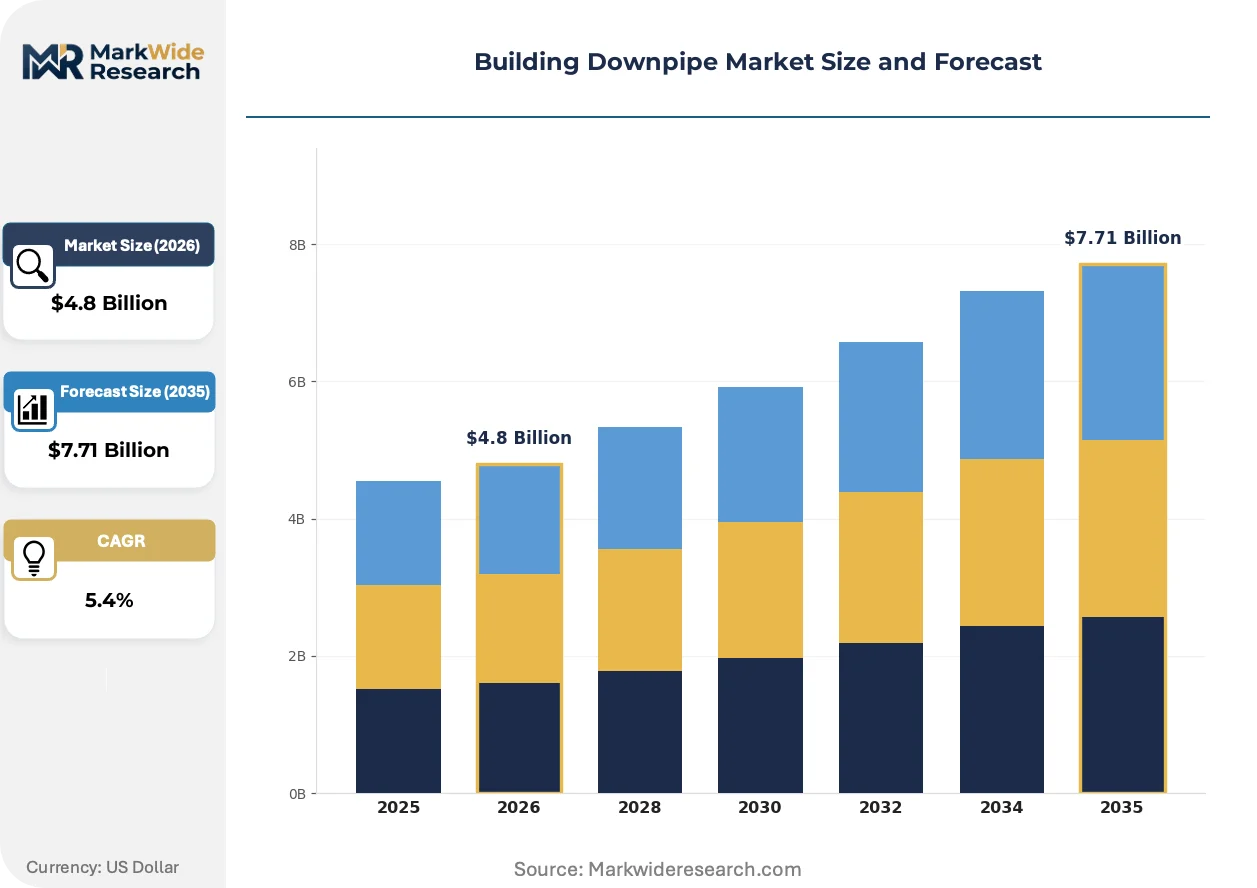
Market Dynamics
Residential construction volume in Victoria and New South Wales is compressing replacement cycles and forcing manufacturers to align production schedules with state-level building permit volatility. BASIX water efficiency standards now function as the primary gatekeeper for material specification, privileging high-performance PVC and aluminum systems over legacy galvanized steel in new housing developments.
Growth Catalysts
- Urban density mandates:Sydney and Melbourne planning authorities are tightening stormwater retention requirements for high-rise residential towers, accelerating specification of integrated gutter-downpipe systems with filtration capacity.
- BASIX compliance thresholds:The NSW water efficiency framework rewards developments that exceed minimum hydraulic performance standards, creating pull-through demand for larger-diameter PVC configurations in greenfield housing estates.
- Coastal corrosion exposure:Salt-laden air in Queensland and Western Australia is shortening product lifecycles for untreated metal systems, generating replacement demand for powder-coated aluminum and marine-grade alternatives.
Market Restraints
- Polymer resin cost volatility:PVC compound pricing tracks ethylene feedstock fluctuations, compressing margins for standardized residential products when oil markets spike.
- Import certification friction:The Victorian Building Authority and NSW Department of Customer Service maintain non-harmonized product marking requirements, creating compliance deadweight for interstate suppliers.
- Concrete drainage substitution:Large-scale commercial projects in Perth and Brisbane increasingly specify cast-in-place box culverts over conventional downpipe arrays for podium-level stormwater management.
Strategic Opportunities
- Tasmanian residential expansion:Hobart's housing construction pipeline remains undersupplied with certified stormwater contractors, creating first-mover advantage for BASIX-accredited product portfolios.
- Bushfire resistance amendments:Proposed updates to Australian Standard AS 3959 for construction in bushfire-prone zones will mandate non-combustible downpipe materials, favoring metal system suppliers.
- Smart water monitoring convergence:Integration of IoT flow sensors with downpipe infrastructure is converging with municipal stormwater billing systems, opening recurring-revenue service models in Sydney's high-density precincts.
Industry Challenges
- Licensed installer scarcity:Queensland and South Australia face acute shortages of plumbers certified for high-rise stormwater stack installation, extending project timelines for multi-residential developers.
- Product-to-system integration complexity:Architects specifying concealed downpipe configurations demand seamless coordination with facade engineering, requiring manufacturers to provide BIM-compatible technical documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Downpipe Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: PVC, Aluminum, Galvanized Steel, Copper, Cast Iron, HDPE Type: Square, Round, Rectangular, Rectangular Oval Installation: Surface Mounted, Recessed, Concealed, Suspended End User: Residential Buildings, Commercial Complexes, Educational Institutions, Hospitality Venues |
| Companies Covered | Aliaxis, Stratco, FloPlast, Marley Plumbing & Drainage, Saint-Gobain, Wavin Group, Polypipe Group, Ace Gutters, Georg Fischer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Downpipe Market Trends and Innovations
Material science advances and regulatory tightening around water quality are compressing traditional product lifecycles while opening premium positioning for performance-validated systems. Three developments are actively restructuring competitive advantage in specification and procurement.
Composite polymer formulations incorporating UV-stabilized additives are extending service life in extreme exposure zones. Commercial developers in coastal Queensland are specifying these systems for 50-year design-life buildings. The technology is converging with green building certification schemes that weight material durability in scoring algorithms, compressing market share for unvalidated PVC alternatives.
EPA stormwater quality guidelines in Victoria and New South Wales now mandate filtration integration for developments exceeding specified impervious surface thresholds. The regulatory tightening is disqualifying basic downpipe configurations from large-scale residential approvals. High-density towers in Melbourne's inner suburbs are responding by specifying pre-engineered gutter-downpipe-filtration bundles that streamline compliance documentation.
Builders are consolidating procurement around modular gutter-and-downpipe systems that reduce on-site assembly labor. Volume residential contractors in Sydney's growth corridors are shifting from component sourcing to pre-configured package purchasing. Western Australia's project home market exhibits the most pronounced consolidation, with top-ten builders standardizing on two supplier relationships to secure volume pricing and installation training support.
Building Downpipe Market Segmentation
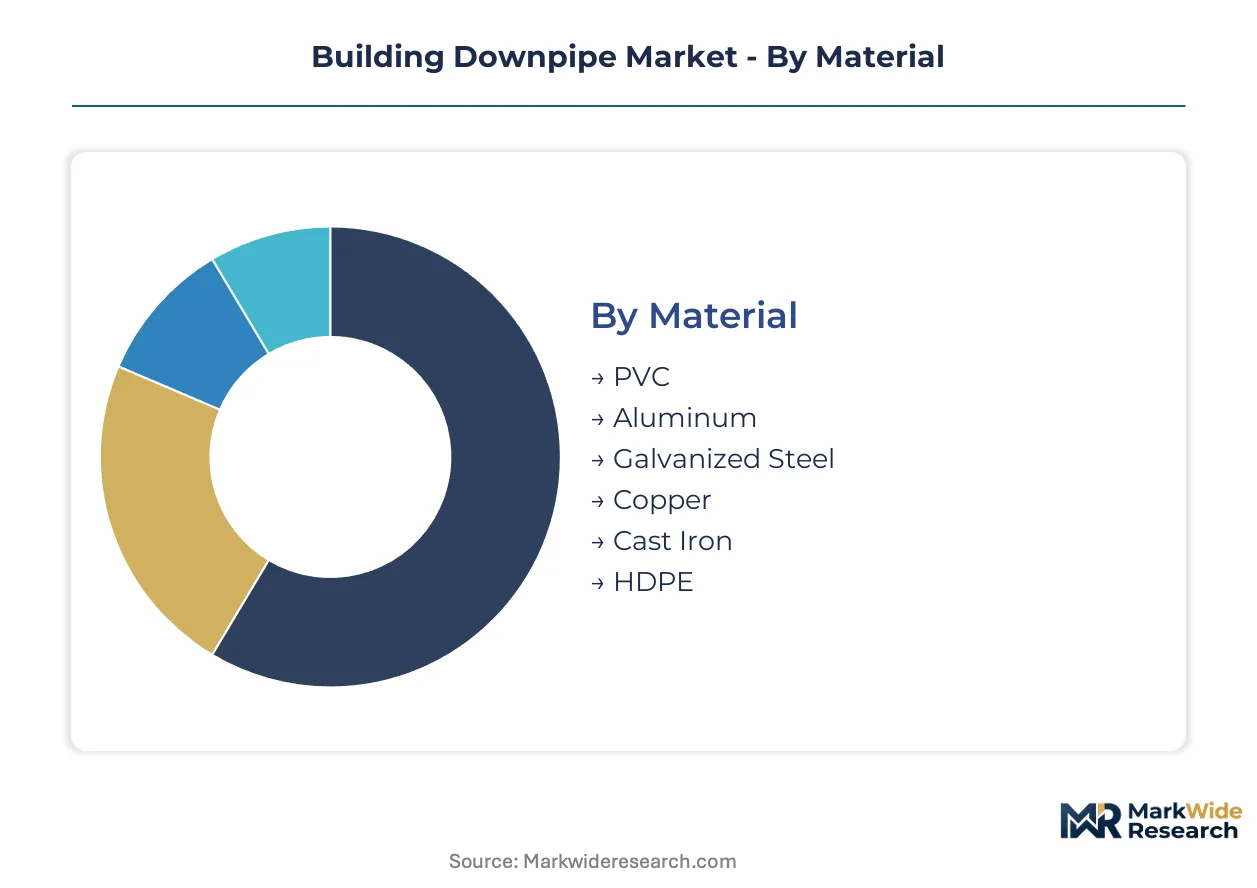
Material selection in the Australian building downpipe market hinges on regulatory compliance with BASIX water efficiency standards and localized environmental exposure. Specification patterns diver sharply between volume residential developers optimizing for cost and coastal commercial projects prioritizing corrosion resistance. Understanding these segment dynamics reveals where procurement consolidation and margin compression concentrate.
Material:
Supply concentration among polymer manufacturers shapes competitive positioning across material categories, with PVC compounders leveraging scale advantages against metal specialists serving premium niches.
- PVC:Formulated from UV-stabilized polymer compounds in diameters from 50mm to 150mm, PVC systems dominate volume residential construction through cost efficiency and rapid installation. Demand concentrates in Victoria and New South Wales greenfield housing estates where BASIX compliance rewards hydraulic performance per dollar spent.
- Aluminum:Extruded and powder-coated profiles deliver 30-50 year service life in salt-laden coastal environments, commanding specification in Queensland and Western Australia commercial developments. Sydney high-rise residential towers specify concealed aluminum configurations for facade integration where aesthetic requirements override material cost premiums.
- Galvanized Steel:Zinc-coated mild steel retains foothold in inland industrial applications where fire resistance and structural rigidity outweigh corrosion susceptibility.
- Copper:Heritage restoration projects and premium architectural specifications in Melbourne's inner suburbs specify copper for patina aesthetics and century-scale durability.
- Cast Iron:Acoustic-dampening properties drive specification in multi-storey hotels and apartment buildings where stack noise transmission requires mitigation.
- HDPE:High-density polyethylene systems gain traction in civil infrastructure and large-diameter commercial drainage where flexibility and joint integrity matter.
Today's leader: PVC. Tomorrow's challenger: Aluminum.
Type:
Geographic building codes and architectural fashion cycles drive type selection, with square profiles dominating volume housing and round configurations persisting in heritage-sensitive districts.
- Square:Sharp-edged profiles maximize hydraulic capacity per wall footprint, dominating project home construction across Sydney and Melbourne growth corridors where builders standardize on modular gutter-and-downpipe bundles.
- Round:Smooth bore geometry minimizes debris accumulation and simplifies maintenance access, preferred in Brisbane and Perth commercial retrofits where existing infrastructure favors traditional configurations.
- Rectangular:Flat-back designs enable tight wall mounting in narrow easements common in high-density infill developments.
- Rectangular Oval:Hybrid profiles combining aesthetic slimness with structural rigidity gain specification in architect-designed hospitality venues seeking distinctive facade elements.
Square profiles anchor current volume; rectangular oval configurations are climbing the fastest among premium specifications.
Installation:
Customer type stratification between volume builders and design-led developers creates divergent installation preferences, with procurement patterns consolidating around pre-engineered solutions.
- Surface Mounted:External bracket fixing dominates detached housing and low-rise commercial where accessibility for maintenance outweighs aesthetic considerations, standard across Perth and Adelaide residential markets.
- Recessed:Partial wall integration conceals downpipes within architectural cavities while preserving inspection access, specified in Melbourne mid-rise apartments where council planning guidelines mandate reduced visual clutter.
- Concealed:Full facade integration behind cladding or within structural voids commands premium positioning in Sydney and Brisbane luxury residential towers where uninterrupted glass curtain walls dominate design language.
- Suspended:Ceiling-hung configurations serve internal atrium drainage in shopping centres and airport terminals where external wall routing proves impractical.
Surface mounted retains volume leadership; concealed systems represent the steepest expansion trajectory as urban density intensifies.
End User:
Application-driven specification creates distinct procurement channels, with residential volume buyers consolidating supplier relationships while institutional clients demand extended performance warranties.
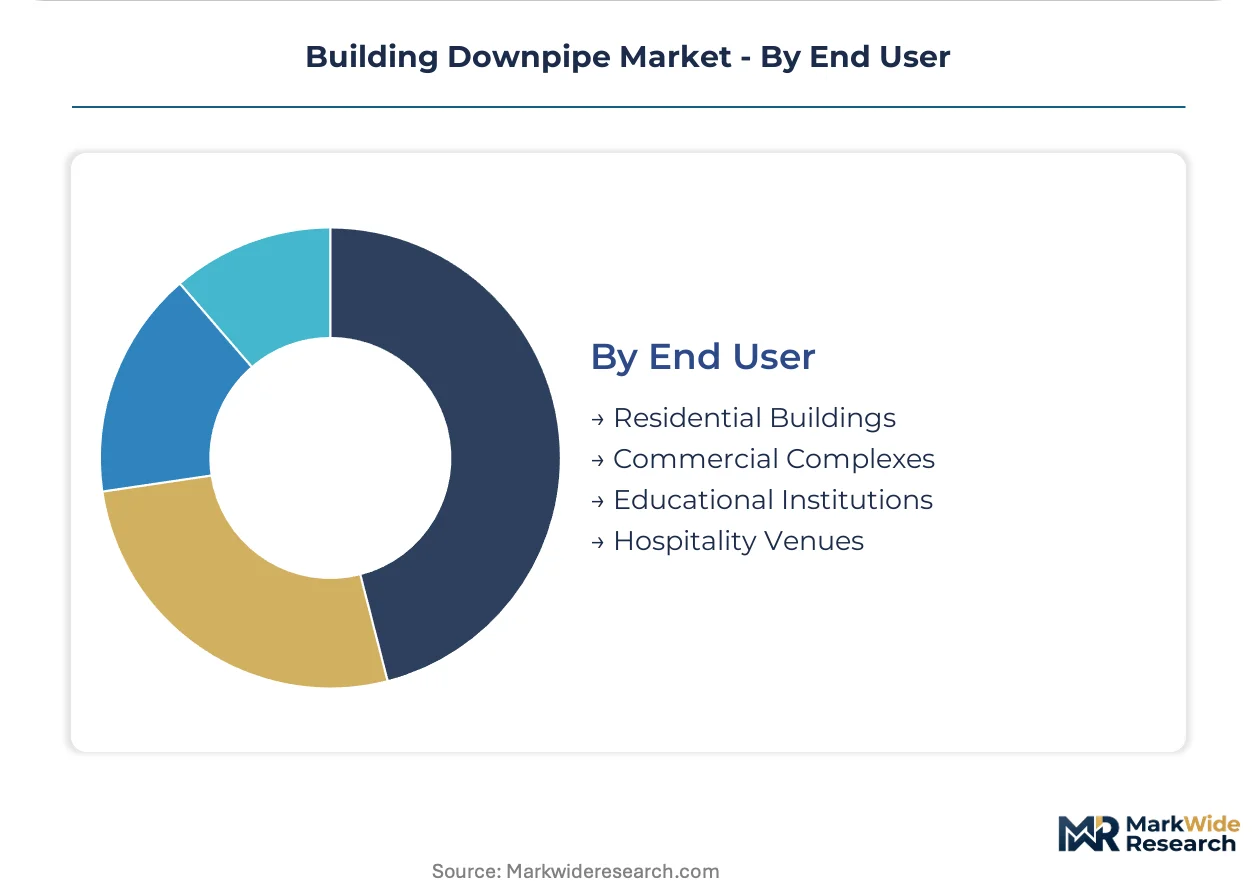
- Residential Buildings:Single-family detached homes, townhouses, and multi-unit developments constitute the dominant demand pool, with top-ten Australian builders standardizing on two-supplier strategies to secure volume pricing and installation training support.
- Commercial Complexes:Office towers, retail podiums, and mixed-use developments specify engineered systems with integrated filtration to meet EPA stormwater quality guidelines in Victoria and New South Wales.
- Educational Institutions:Schools and universities prioritize vandal-resistant configurations and extended maintenance intervals, with state education departments running centralized procurement frameworks.
- Hospitality Venues:Hotels and resorts demand aesthetic coordination with facade design and acoustic performance, often specifying custom-color powder coating and concealed routing.
Residential buildings dominate current procurement value; commercial complexes are gaining share fastest as stormwater retention mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The building downpipe industry traces its modern standardization to post-war Australia, where galvanized steel systems first dominated residential construction before polymer technologies displaced metal in volume applications during the 1980s and 1990s.
Australia
Victoria and New South Wales compress replacement cycles through BASIX water efficiency mandates that privilege high-performance PVC and aluminum configurations. The Victorian Building Authority enforces non-harmonized product marking requirements that create compliance friction for interstate suppliers. Melbourne's inner suburbs exhibit the steepest specification growth for concealed downpipe systems as urban density intensifies facade integration demands.
United States
Residential construction volume in Florida and Texas drives specification of vinyl and aluminum systems engineered for hurricane resistance and coastal corrosion exposure. The EPA administers stormwater discharge permits under the National Pollutant Discharge Elimination System, pushing commercial developers toward integrated filtration configurations. Miami-Dade County's stringent wind-borne debris codes accelerate replacement demand for impact-rated downpipe assemblies in high-velocity hurricane zones.
Germany
Energy-efficient building renovation programs concentrate demand for durable metal systems in multi-family housing stock across North Rhine-Westphalia and Bavaria. The country's national construction regulator enforces DIN standards for hydraulic performance and material durability that exceed baseline EU requirements. Stuttgart's dense urban core generates specification pull for recessed and concealed installation types that preserve historic facade integrity.
China
Urbanization in the Yangtze River Delta and Pearl River Delta sustains volume demand for PVC systems in high-rise residential towers. MIIT oversees GB standards for building drainage products that mandate minimum wall thickness and UV stabilization for polymer configurations. Shenzhen's green building pilot zones reward developments specifying rainwater harvesting-integrated downpipe systems with density bonuses and expedited permitting.
United Kingdom
Heritage conservation requirements in London and Southeast England sustain niche demand for cast iron and copper systems in restoration projects. The Environment Agency enforces Sustainable Drainage Systems regulations that mandate attenuation capacity for new commercial developments exceeding specified impervious surface thresholds. Manchester's urban regeneration corridors exhibit growing specification of powder-coated aluminum systems for aesthetic coordination with contemporary facade designs.
Building Downpipe Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specialization and installation complexity tiers. The vendor base stratifies between polymer compounders leveraging scale economies in standardized residential products and metal fabricators commanding specification premiums in coastal and high-rise applications. Three archetypes dominate: multinational building materials conglomerates with integrated polymer supply chains, regional metal specialists with powder-coating and marine-grade capabilities, and project-home builders consolidating procurement around pre-engineered system bundles. Competitive moves concentrate on backward integration into resin compounding and strategic partnerships with facade engineering firms for BIM-compatible documentation.
Within the multinational conglomerate tier, Aliaxis and Saint-Gobain occupy positions that exemplify divergent strategic emphases on polymer manufacturing depth versus high-performance composite material leadership. Among regional specialists, Stratco anchors the metal segment with coastal corrosion resistance capabilities. Wavin Group represents the scale-driven archetype across European and Asia-Pacific distribution networks.
| Leading Market Players |
|---|
| Aliaxis |
| Stratco |
| FloPlast |
| Marley Plumbing & Drainage |
| Saint-Gobain |
| Wavin Group |
| Polypipe Group |
| Ace Gutters |
| Georg Fischer |
| Others |
Pricing and Supply Chain Analysis
Polymer compounding automation across Australian PVC manufacturing simultaneously compresses per-unit production costs and consolidates supplier leverage toward Aliaxis and Wavin Group. This technology transition rewards scale players with BASIX-certified product portfolios while squeezing margin recovery for second-tier compounders serving price-sensitive volume residential contractors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, separating powder-coated aluminum systems from UV-stabilized PVC configurations from commodity-grade galvanized steel. Price differentiation hinges on BASIX certification tier and coastal corrosion resistance rating, with certified aluminum commanding substantial premiums in Queensland. Cost compression in standard-grade PVC is intensifying because ethylene feedstock volatility transmits directly into compounder margins. Volume residential developers in Sydney's growth corridors exhibit highest price sensitivity, while hospitality venue architects demonstrate lowest sensitivity due to aesthetic integration requirements.
Supply Chain Analysis
Freight cost differentials between Asian resin import routes and domestic compounding facilities in Victoria and New South Wales shape regional pricing spreads. Manufacturing concentrates in Australia, China, and Germany, with Australian producers drawing from Southeast Asian ethylene feedstock and Chinese masterbatch additives. Single-source vulnerability sits with specialized UV stabilizer formulations sourced from limited German chemical suppliers. Distribution runs through plumbing merchant networks and direct-to-builder procurement channels, with top-ten residential builders consolidating around pre-engineered system bundles to secure volume pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The building downpipe market compounds steadily through regulatory ratcheting of stormwater performance standards that mandate replacement cycles and premium material upgrades. BASIX compliance thresholds in New South Wales and Victoria function as durable demand drivers independent of construction cycle volatility.
For Market Incumbents: Extend backward integration into resin compounding to capture margin compression from ethylene volatility and defend against import substitution. Aliaxis and Stratco should deepen captive supply of UV-stabilized polymer formulations while accelerating BIM-compatible documentation partnerships with facade engineering firms to lock in concealed installation specifications before competitors replicate technical service capabilities.
For New Entrants and Emerging Players: Enter via Tasmanian residential expansion where certified stormwater contractor scarcity creates first-mover advantage for BASIX-accredited portfolios. The Hobart housing pipeline remains undersupplied with compliant installation capacity. Target smart water monitoring convergence in Sydney's high-density precincts, offering IoT-integrated downpipe systems with recurring-revenue municipal billing compatibility as the go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional metal fabricators with powder-coating capabilities and marine-grade aluminum expertise serving Queensland coastal exposure. Long-term viability centers on 5-10 year regulatory tightening around bushfire resistance amendments favoring non-combustible materials. Watch proposed updates to Australian Standard AS 3959 as the inflection signal indicating accelerated metal system substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin from ethylene volatility and insulates BASIX-certified production. |
| BIM-Compatible Documentation Partnership | Locks specification for concealed installations in Sydney and Melbourne high-rise towers. |
| Tasmanian Market Entry | Exploits contractor scarcity in Hobart's undersupplied housing construction pipeline. |
| Smart Water Monitoring Integration | Opens recurring-revenue models converging with Sydney municipal stormwater billing. |
| Marine-Grade Aluminum Capacity Expansion | Positions for Queensland coastal corrosion replacement demand and bushfire resistance amendments. |
Research Methodology
Multiple input streams — structured interviews with plumbing contractors and merchant procurement managers, regulatory filings with the Victorian Building Authority and NSW Department of Customer Service, and customs trade data on polymer resin imports — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured specification patterns from volume residential builders, commercial developers, and facade engineering consultants. Secondary validation drew from EPA stormwater quality guidelines, BASIX technical manuals, and Australian Standards documentation for material durability.
Historical volume trajectories were cross-referenced against panel input from state-level building permit databases and construction industry associations across the analysis window. Segmentation modeling incorporated material type, installation configuration, end-user category, and state-level regulatory cluster. CAGRs were derived from trend extrapolation adjusted for BASIX amendment schedules and urban density planning mandates. Forecast inputs included polymer feedstock price indices, coastal corrosion exposure mapping, and smart infrastructure investment pipelines.
Inputs from regulatory agencies and industry associations were available through the study window; gaps in real-time builder procurement data introduce uncertainty bands around volume residential segment projections. Forecasts reflect assumptions regarding BASIX threshold stability and ethylene supply chain continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Door Hinges Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Drainage System Market