
 India Manufacturing Market | 2026-2036
India Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
India Manufacturing Market Foresight
Aftermarket service revenue is fragmenting across India's manufacturing base as original equipment producers diversify beyond unit sales. Bharat Forge sustains its position through deep forging expertise for automotive and defense applications. Tata Hitachi Construction Machinery anchors the heavy equipment segment with localized production networks. JCB India leverages its dealer infrastructure to capture recurring maintenance contracts in mining and infrastructure end uses.
India manufacturing encompasses the physical transformation of raw materials into finished goods through processes including CNC machining, additive manufacturing, and industrial robotics integration, serving commercial and industrial buyers across fabricated metals, machinery, electronics, and textiles categories. Fabricated metals and machinery segments occupy mature margin pools tied to construction and automotive OEM demand. Electronics manufacturing is accelerating fastest under import substitution policies, while IoT Solutions and Industrial Robotics technologies reshape quality control and predictive maintenance capabilities across plant floors.
BIS certification requirements and the PLI scheme administered by DPIIT govern product standards and subsidy eligibility, directing investment toward domestic value addition. State-level industrial policies in Gujarat, Maharashtra, and Tamil Nadu compete for capital through land allocation and utility concessions, creating uneven regulatory terrain. Stakeholders must monitor how CDSCO medical device rules and evolving F-Gas regulations intersect with electronics and machinery export compliance obligations.
Market Dynamics
The PLI scheme is redirecting capital flows into component ecosystems while automotive OEMs expand domestic sourcing mandates for electric vehicle programs, compressing import dependence and reshaping supplier qualification timelines.
Growth Catalysts
- Production Linked Incentive scheme:DPIIT-administered subsidies for electronics and automotive components are accelerating greenfield investments in Gujarat and Tamil Nadu industrial corridors.
- Automotive electrification:Domestic EV production mandates are pulling battery pack assembly, motor winding, and power electronics manufacturing into Indian supplier networks.
- Industrial corridor infrastructure:Dedicated freight corridors and plug-and-play land parcels in Maharashtra are reducing time-to-operations for capital-intensive fabrication facilities.
Market Restraints
- Specialty steel import dependence:High-grade alloy and tool steel requirements for precision machining remain concentrated in East Asian supplier bases, exposing margins to freight and currency volatility.
- BIS certification timelines:Bureau of Indian Standards testing queues for industrial machinery and electrical equipment extend product launch windows by four to eight months versus comparable ASEAN markets.
- Capital equipment financing gaps:Indian commercial banks apply heavy provisioning requirements against manufacturing term loans, elevating effective borrowing costs for SME toolroom investments.
Strategic Opportunities
- Medical device component localization:CDSCO rule harmonization with MDR frameworks is creating demand for precision-machined surgical instruments and diagnostic housing assemblies in Pune and Bengaluru clusters.
- Industrial IoT convergence:Edge computing hardware married with vibration sensors is opening predictive maintenance service contracts among cement and steel plant operators.
- Defense indigenization mandates:Offset obligations under DAP procurement policies are channeling forging, casting, and electronics integration work into domestic vendor bases.
Industry Challenges
- CNC programming talent scarcity:Multi-axis machining and CAM software proficiency gaps constrain output scaling in precision component segments serving aerospace and medical device buyers.
- Legacy ERP integration friction:Shop-floor digitalization initiatives collide with decades-old MRP systems, delaying real-time production visibility deployments.
- F-Gas transition complexity:Refrigeration and HVAC equipment manufacturers face reformulation and retooling costs as India aligns with Kigali Amendment phase-down schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Manufacturing Market |
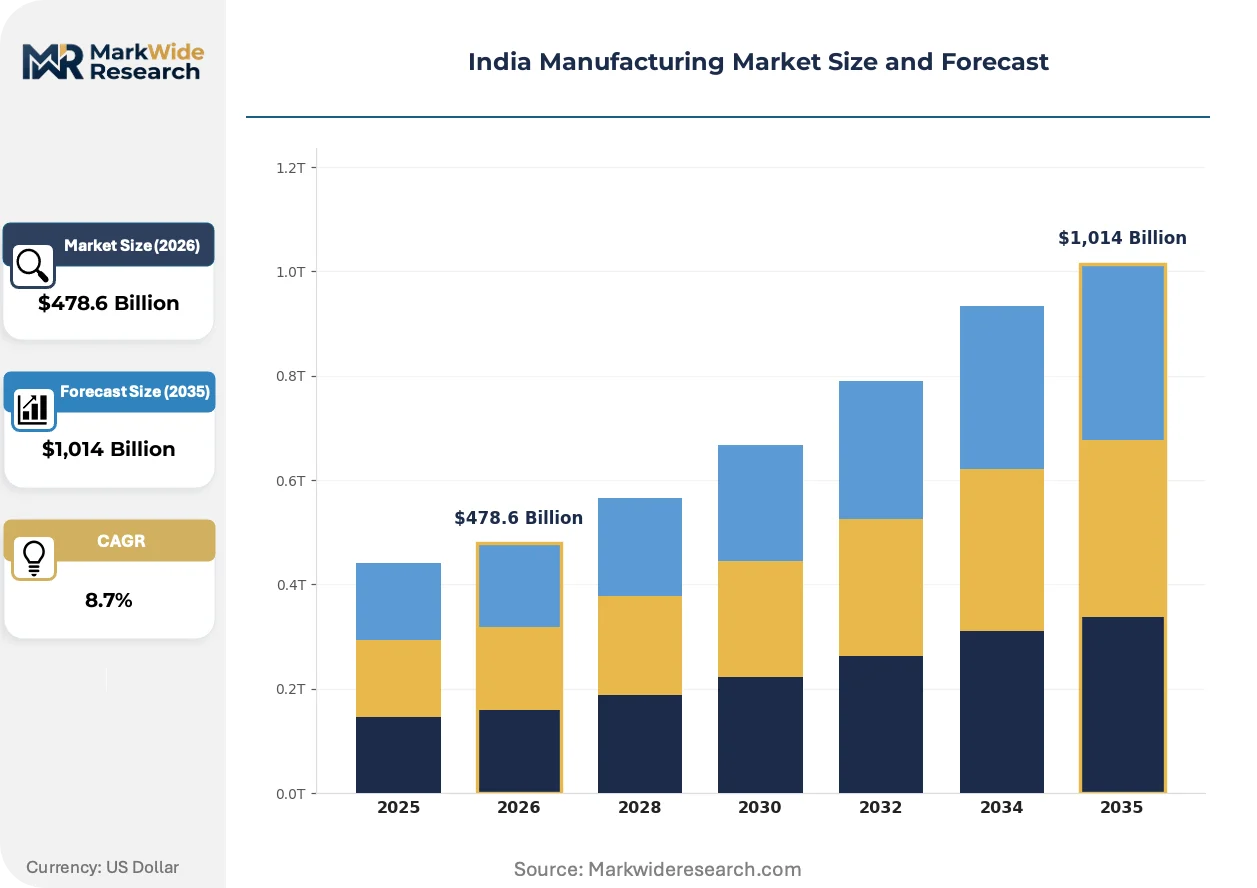
| Market Size in 2026 | $478.6 Billion |
| Market Size in 2035 | $1,014 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabricated Metals, Machinery, Electronics, Textiles End User: Aerospace, Automotive OEMs, Consumer Goods, Heavy Equipment Technology: Additive Manufacturing, CNC Machining, Industrial Robotics, IoT Solutions Distribution Channel: Direct Sales, E-Commerce, Distributors, Wholesalers |
| Companies Covered | Nuvoco Vistas, Kia India, Tata Hitachi Construction Machinery, JCB India, Bharat Forge, Godrej Material Handling, UNO Minda, Schaeffler India, Kirby Building Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Manufacturing Market Shifts & Advancements
Additive manufacturing and industrial robotics are compressing batch economics and quality variance while regulatory pressure on carbon intensity forces process reengineering across heat-treatment and surface finishing operations.
Metal binder jetting is collapsing minimum order quantities for complex geometries in pump housings and turbine blades. Automotive and aerospace tier-1 suppliers in Tamil Nadu are adopting these systems for bridge production and aftermarket spare fulfillment. Traditional sand casting and investment casting lead times are compressing from weeks to days for qualified part families.
BIS mandatory certification expansion into lithium-ion battery cells and battery management systems is forcing electronics assemblers to establish captive testing facilities or partner with NABL-accredited laboratories. CDSCO alignment with IMDRF technical documentation standards is accelerating for Class C and D medical devices. Gujarat-based contract manufacturers are absorbing compliance costs to lock in long-term OEM supply agreements.
Aftermarket service unbundling is fragmenting revenue streams across construction equipment and machine tool segments. Mining contractors in Odisha and Chhattisgarh now procure maintenance contracts separately from original equipment, favoring dealers with spare parts warehousing and field service density. JCB India and Tata Hitachi are restructuring sales organizations to capture recurring revenue from uptime guarantees rather than unit shipments alone.
India Manufacturing Market Segmentation
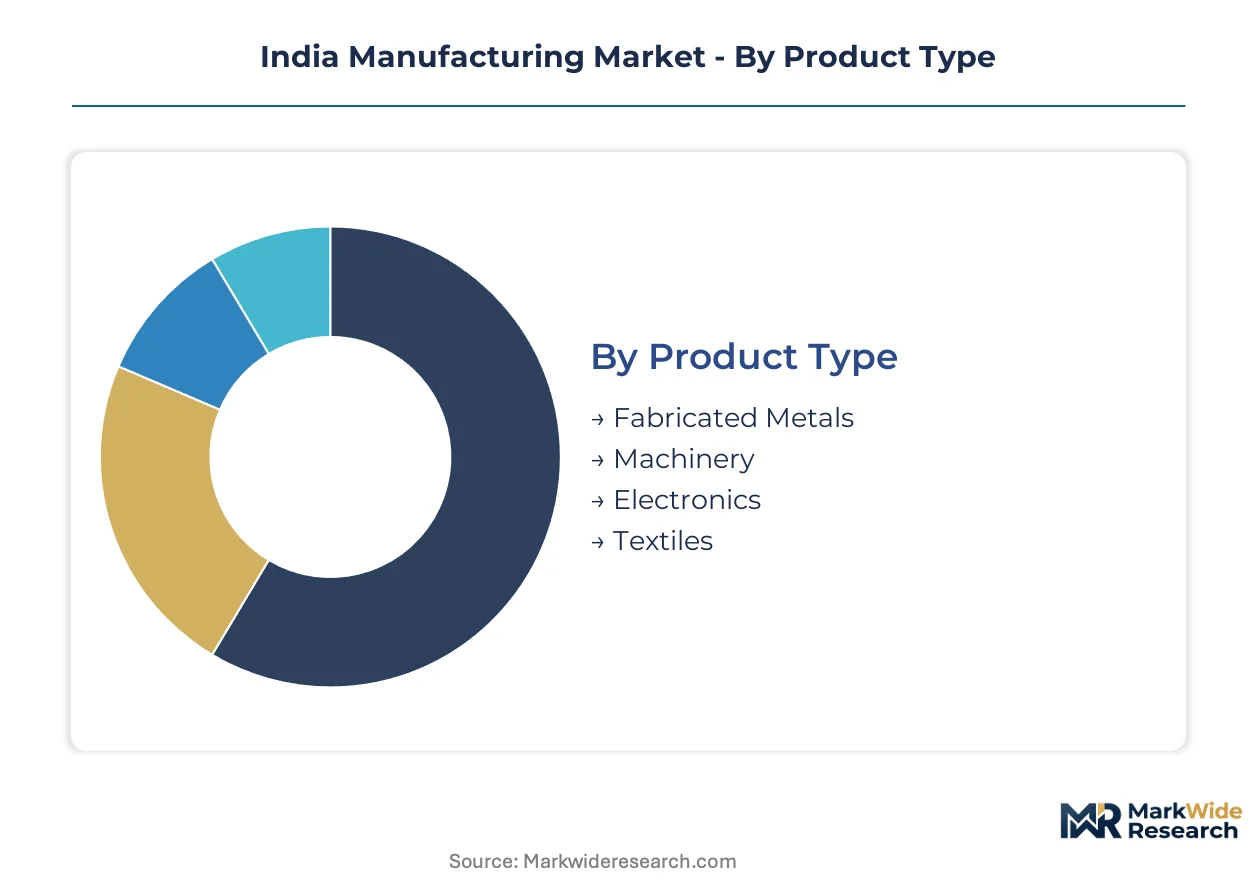
Segmentation in Indian manufacturing reveals how capital intensity and regulatory exposure vary sharply across product categories. Cycle times, certification burdens, and customer concentration create divergent margin profiles that suppliers must navigate.
Product Type:
Fabricated metals turn inventory fastest with standardized specifications, while electronics faces longest validation cycles due to BIS certification queues and import substitution compliance.
- Fabricated Metals:Structural steel, aluminum extrusions, and precision stampings form the feedstock for construction and automotive body-in-white assemblies. Demand concentrates in Gujarat and Maharashtra industrial corridors where dedicated freight infrastructure reduces inbound material costs.
- Machinery:Capital equipment including presses, injection molding systems, and material handling rigs carry 18-36 month sales cycles tied to industrial credit availability. Tamil Nadu and Pune clusters absorb the highest deployment volumes as automotive OEMs expand domestic tooling capacity.
- Electronics:PCBA, power modules, and connector assemblies.
- Textiles:Technical fabrics and synthetic fiber processing equipment.
Fabricated metals anchors the volume base while electronics gains share at the steepest rate.
End User:
Margin tiers separate defense-aerospace qualification-heavy buyers from high-volume consumer goods producers with compressed payment terms.
- Automotive OEMs:Passenger vehicle and commercial truck manufacturers drive precision component demand through electric vehicle program localization mandates. Battery pack assembly, motor winding, and power electronics sourcing requirements are pulling tier-2 suppliers into Tamil Nadu and Maharashtra supplier parks.
- Aerospace:Airframe structures and engine components require AS9100 certification and NADCAP-accredited special processes. Bangalore and Hyderabad maintenance, repair, and overhaul clusters generate aftermarket machining demand for legacy platform spares.
- Consumer Goods:Appliance and electronics finished goods producers.
- Heavy Equipment:Mining and construction machinery operators.
Automotive OEMs anchors the volume base while aerospace climbs the fastest on per-unit value.
Technology:
Adoption velocity splits between legacy CNC infrastructure and emerging digital manufacturing stacks requiring software integration investments.
- CNC Machining:Multi-axis milling and turning centers remain the dominant production modality for precision components across medical device and aerospace applications. Talent scarcity in CAM programming and multi-axis setup constrains output scaling in Pune and Bengaluru precision clusters.
- Industrial Robotics:Articulated arms and collaborative robots are displacing manual welding and material handling in automotive body shops. Gujarat-based automotive tier-1 suppliers are deploying fleet-scale installations to meet OEM quality consistency requirements.
- Additive Manufacturing:Metal binder jetting and polymer powder bed fusion systems.
- IoT Solutions:Edge computing hardware and predictive analytics platforms.
CNC machining anchors the volume base while industrial robotics expands most quickly on installed base growth.
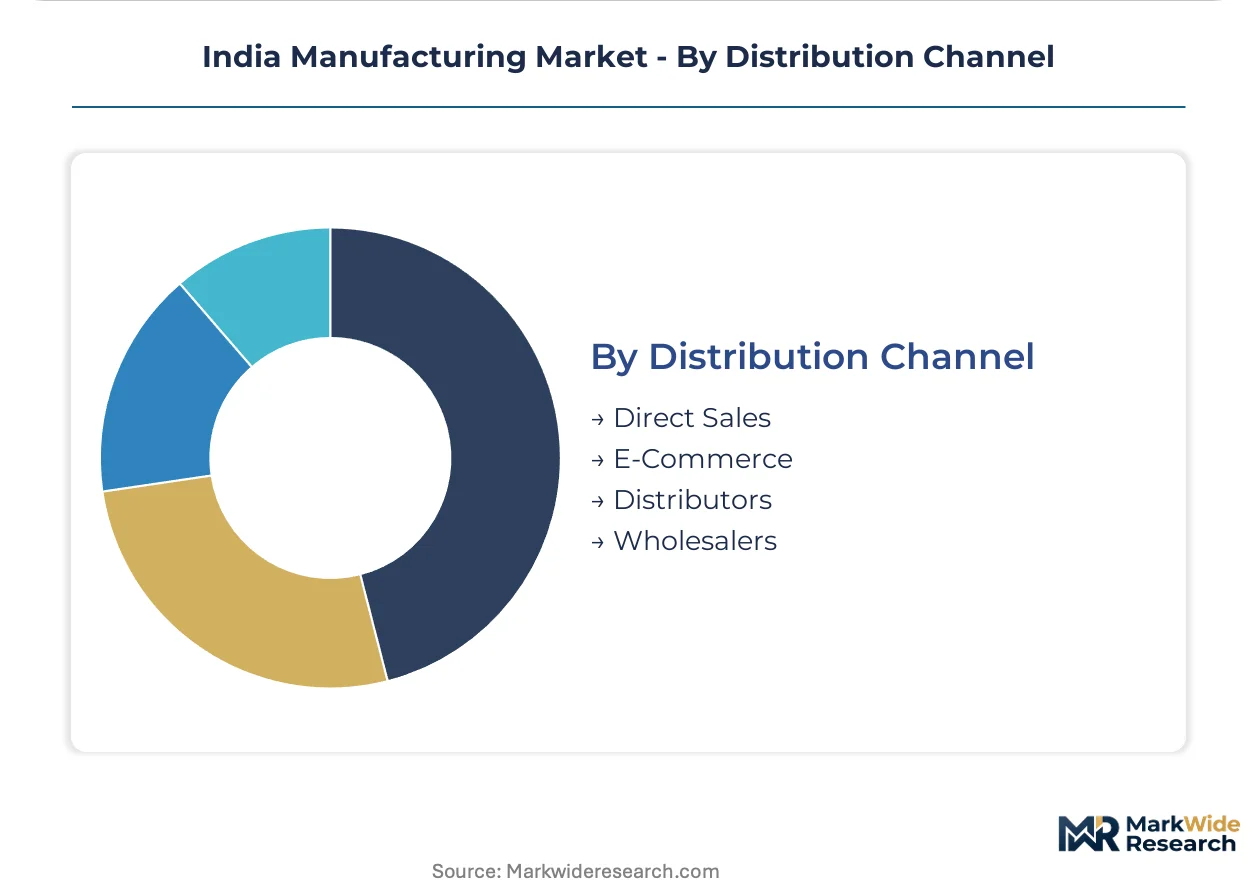
Distribution Channel:
Channel economics vary by customer scale, with project-based direct sales carrying highest customer acquisition costs and e-commerce capturing fragmented maintenance, repair, and operations demand.
- Distributors:Authorized dealer networks with field service capabilities dominate construction equipment and machine tool segments. JCB India and Tata Hitachi leverage this infrastructure to unbundle aftermarket service contracts from original equipment sales.
- Direct Sales:Large-volume automotive and aerospace contracts bypass intermediaries for vendor-managed inventory arrangements. OEM engineering teams co-locate with tier-1 suppliers in Tamil Nadu and Maharashtra to compress design iteration cycles.
- E-Commerce:B2B platforms for cutting tools, fasteners, and maintenance consumables.
- Wholesalers:Bulk commodity metal and polymer distributors serving SME fabricators.
Distributors anchors the volume base while direct sales gains share fastest on strategic account consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat, Maharashtra, and Tamil Nadu concentrate manufacturing demand differently from northern and eastern states, with western corridors prioritizing automotive and chemical processing while southern clusters anchor electronics and precision engineering.
Maharashtra
Automotive OEMs and heavy machinery producers drive component demand through EV localization mandates. The state industrial policy offers land allocation concessions and utility subsidies to anchor tier-1 suppliers. Pune and Chakan industrial zones absorb the highest precision machining volumes as OEM engineering teams co-locate with vendors.
Gujarat
Petrochemical feedstock access and port infrastructure attract fabricated metals and specialty chemical processors. The DPIIT-administered PLI scheme for electronics components accelerates greenfield investments in Sanand and Halol corridors. Dahej and Mundra ports reduce inbound raw material costs for export-oriented fabricators.
Tamil Nadu
Electronics manufacturing services and automotive tier-1 suppliers cluster around Sriperumbudur and Oragadam industrial parks. BIS certification requirements for lithium-ion battery cells force assemblers to establish captive testing facilities or partner with NABL-accredited laboratories. Chennai's electronics hardware park anchors power module and connector assembly lines.
Karnataka
Aerospace MRO clusters and medical device precision machining concentrate in Bangalore and Hyderabad corridors. CDSCO alignment with IMDRF technical documentation standards accelerates for Class C and D device components. Bengaluru's precision engineering parks generate aftermarket machining demand for legacy platform spares.
Haryana
Auto component ancillaries and construction equipment assembly serve Delhi-NCR demand anchors. State-level industrial policies compete through freight corridor access and plug-and-play land parcels. Manesar and Bawal industrial areas host stamping, forging, and welding operations for northern automotive OEMs.
India Manufacturing Market Competitive Landscape
Capability concentration sits with specialized forging and precision machining specialists; scale advantage sits with diversified conglomerates with captive distribution networks. The market structures around three tiers: integrated metal-forming specialists, construction equipment assemblers with dealer infrastructure, and diversified industrials with multi-sector exposure. M&A activity targets component technology access, while capacity expansion concentrates in Gujarat and Tamil Nadu industrial corridors.
Among integrated metal-forming specialists, Bharat Forge exemplifies deep forging expertise for defense and automotive applications. Tata Hitachi Construction Machinery occupies a position within heavy equipment assembly, leveraging localized production networks. JCB India anchors the construction equipment tier through dealer infrastructure that captures recurring maintenance contracts.
| Leading Market Players |
|---|
| Nuvoco Vistas |
| Kia India |
| Tata Hitachi Construction Machinery |
| JCB India |
| Bharat Forge |
| Godrej Material Handling |
| UNO Minda |
| Schaeffler India |
| Kirby Building Systems |
| Others |
Supply & Pricing Matrix
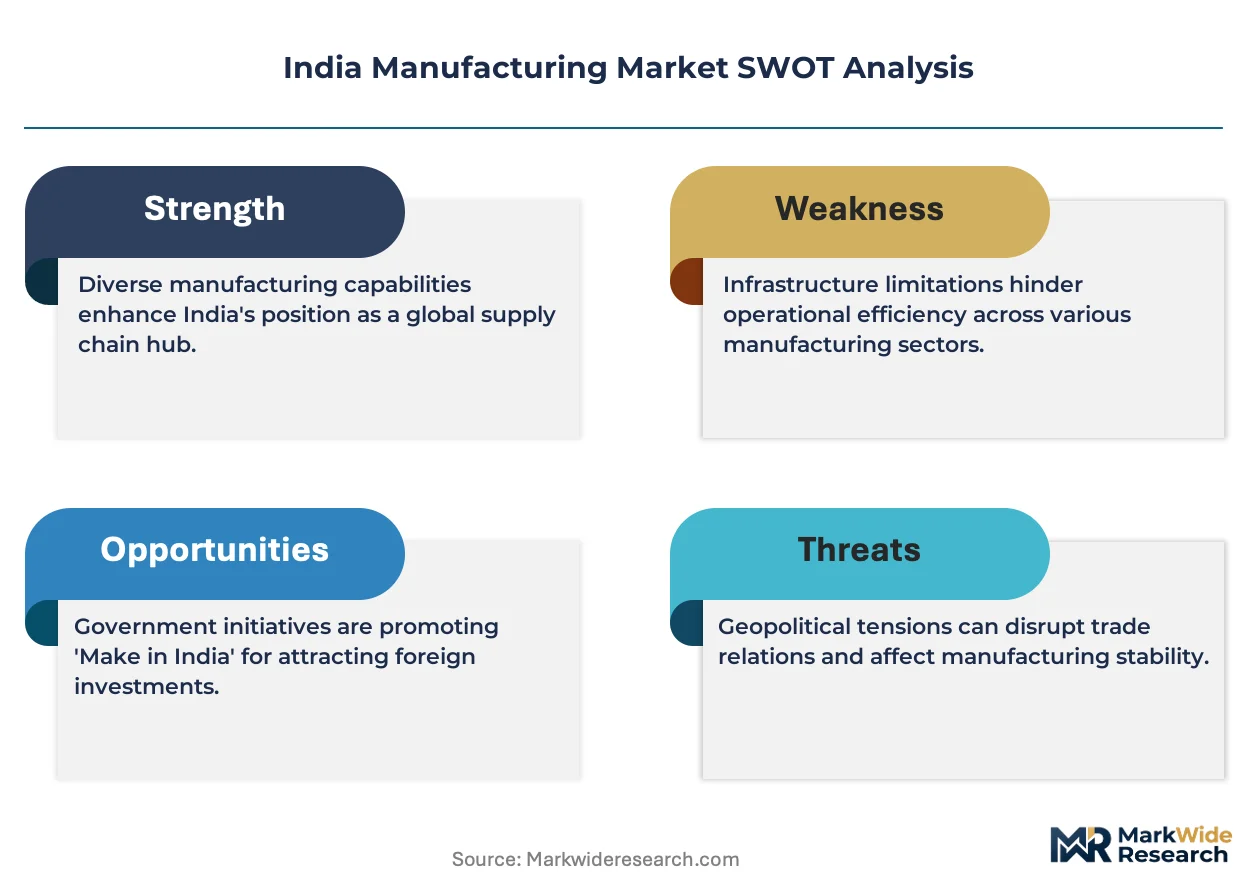
Dedicated freight corridors connecting Gujarat's Mundra and Dahej ports to northern industrial zones compress logistics costs for specialty steel and precision component flows, concentrating supply power among corridor-adjacent fabricators while forcing price differentiation between freight-integrated and hinterland suppliers.
Pricing Analysis
Long-term offtake contracts dominate automotive and electronics component procurement, insulating tier-1 suppliers from spot volatility while compressing margins for non-contracted SME toolrooms. Price differentiation separates AS9100-certified aerospace suppliers from commodity fabricators serving construction demand. Cost compression in battery pack assembly is intensifying because BIS certification requirements force captive testing investments. Construction equipment buyers show highest price sensitivity, mining operators least.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan and South Korea-based electronics assemblers and Japanese precision equipment OEMs operating through Indian joint ventures. High-grade alloy steel, lithium-ion cells, and CNC machine tool spindles anchor critical import dependencies. Single-source vulnerability in East Asian specialty steel exposes margins to currency volatility. Distribution runs through authorized dealer networks with field service density in mining and infrastructure corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts now expand faster than original equipment shipments across construction machinery and precision tool segments, transforming hardware vendors into recurring-revenue platforms.
For Market Incumbents: Pre-empt dealer network fragmentation by consolidating spare parts warehousing and field service density in Odisha and Chhattisgarh mining belts. Absorb BIS certification costs to lock tier-1 supplier status under PLI scheme eligibility. Backward integration into captive forging capacity defends margin position against specialty steel import volatility.
For New Entrants and Emerging Players: Establish a beachhead in medical device component machining where CDSCO-IMDRF alignment creates qualification barriers for incumbent metal-formers. Target Pune and Bengaluru precision clusters for Class C and D surgical instrument contracts. Lead with NABL-accredited testing partnerships to compress OEM qualification timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors industrial IoT hardware vendors with cement and steel plant predictive maintenance deployments. Five-to-ten year viability hinges on software service attach rates exceeding hardware depreciation cycles. Monitor edge computing adoption curves at Tamil Nadu automotive tier-1 facilities as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Forging | Captive alloy steel processing insulates margins from East Asian import volatility under DGFT duty structures. |
| NABL Laboratory Partnership | Accelerated BIS testing access compresses product launch windows versus queue-dependent competitors. |
| Dealer Network Consolidation | Field service density in mining corridors captures unbundled maintenance contracts from JCB India and Tata Hitachi. |
| Industrial IoT Platform Deployment | Vibration sensor and edge hardware bundles open recurring service revenue at cement and steel plants. |
| CDSCO Certification Investment | IMDRF-aligned technical documentation unlocks Class C and D medical device component supply agreements. |
Research Methodology
Desk research of DPIIT PLI scheme filings, BIS certification databases, and CDSCO medical device registration records preceded structured interviews with automotive OEM procurement teams, precision machining plant managers, aftermarket service heads at construction equipment distributors, and NABL-accredited laboratory technical directors. Secondary validation drew from customs trade data, state industrial policy circulars, and industrial corridor development authority disclosures. Bottom-up capacity and demand estimates were triangulated against top-down sectoral GDP contribution figures.
Assumptions around PLI subsidy disbursement velocity, BIS testing queue durations, and freight corridor utilization rates were held fixed across baseline scenarios while EV localization mandates and F-Gas phase-down schedules were stress-tested. Segmentation modeling incorporated product type, end-use industry, technology adoption tier, and distribution channel structure. CAGRs were derived from production capacity buildout trajectories and import substitution elasticity estimates across the analysis window.
Stress conditions across specialty steel tariff exposure, CDSCO regulatory timeline compression, and industrial credit availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors. Quarterly review of PLI disbursement velocity, BIS queue lengths, and EV program localization ratios is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
Mexican Insulated Panels Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market