
 USA and Canada Pre-Painted Steel Roofing and Cladding Market | 2026-2036
USA and Canada Pre-Painted Steel Roofing and Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
USA and Canada Pre-Painted Steel Roofing and Cladding Market Analytics
ASTM A755 qualification for pre-painted sheet metal is collapsing the supplier base to mills with certified coil-coating lines and in-house substrate control. ArcelorMittal leverages its integrated North American steelmaking network to secure prime hot-rolled substrate for coil-coated architectural products. ATAS specializes in standing-seam profiles engineered for high-velocity wind zones along the Atlantic and Gulf coasts. Western States Metal Roofing dominates direct-to-contractor distribution through regional stocking locations across the western United States.
Pre-painted steel roofing and cladding comprises hot-dipped galvanized or Galvalume substrate coil coated with fluoropolymer or silicone-modified polyester resin systems, then formed into panels with baked finish thicknesses typically ranging 0.7 to 1.2 mil. The material serves primarily as a weathering envelope for low-slope and steep-slope commercial, institutional, and residential structures requiring 20- to 40-year finish warranties. Residential applications lead volume but carry thinner margins due to commodity specification, while commercial projects increasingly demand cool-roof-rated PVDF coatings that command premium positioning. Agricultural and industrial end-uses remain mature segments with price-sensitive procurement patterns and longer replacement cycles.
FEMA building codes in hurricane-prone counties and the Inflation Reduction Act's efficiency incentives shape product specification and market access across the United States. Canada's National Building Code and provincial energy step codes in British Columbia and Ontario drive comparable demand for thermally reflective cladding assemblies. Stakeholders must monitor evolving metal roofing eligibility under federal and provincial rebate programs as policymakers tighten performance thresholds for thermal emissivity and solar reflectance index.
Market Dynamics
ASTM A755 qualification requirements are compressing the supplier base to certified coil-coating operations with integrated substrate control, fundamentally restructuring competitive access in architectural steel.
Growth Catalysts
- Inflation Reduction Act energy efficiency tax credits:Commercial builders across Texas and Virginia now specify cool-roof-rated PVDF coatings to capture federal incentives, redirecting material selection toward premium pre-painted steel.
- Data center construction clusters:Hyperscale facility development in northern Virginia and Dallas-Fort Worth is accelerating specification of high-reflectance coil-coated roofing for thermal load management.
- FEMA hurricane-resistant building codes:Counties along the Atlantic and Gulf coasts mandate enhanced wind-uplift performance, driving adoption of standing-seam profiles with superior fastener retention.
Market Restraints
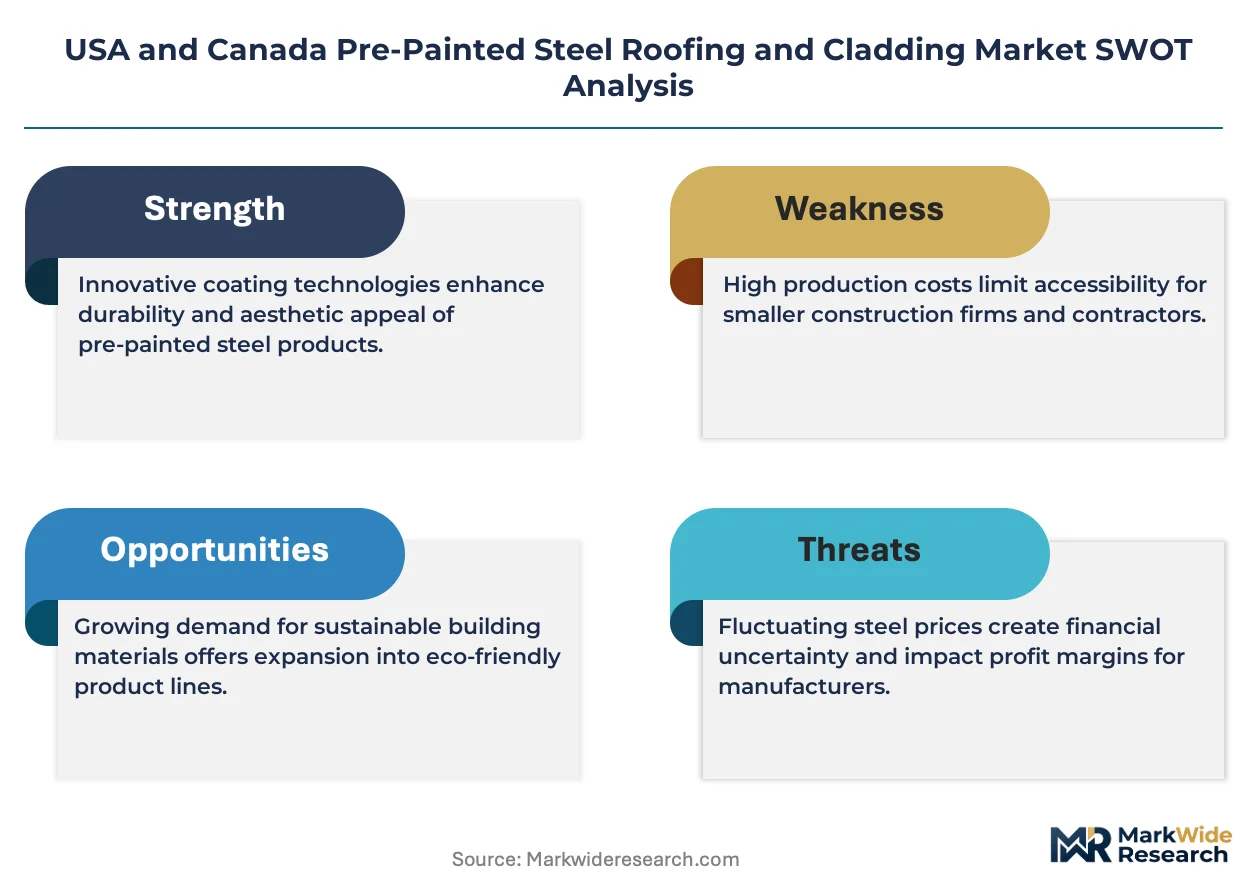
- Zinc and aluminum input cost volatility:Hot-dipped galvanized and Galvalume substrate pricing fluctuates with London Metal Exchange commodity movements, compressing margin predictability for coil coaters.
- Mill-level supply concentration:Prime hot-rolled coil availability tightens around integrated steelmaking operations in Indiana and Ohio, constraining independent coil-coating line throughput.
- Silicone-modified polyester performance ceiling:SMP resin systems max out at 20-year warranty coverage, blocking penetration into institutional segments demanding 40-year fluoropolymer alternatives.
Strategic Opportunities
- Western Canadian provincial energy step codes:British Columbia and Ontario thermal performance mandates create demand for thermally broken cladding assemblies with reflective pre-painted steel surfaces.
- Agricultural building retrofit cycles:Aging metal building stock across the US Corn Belt approaches replacement windows, opening specification pathways for next-generation coil-coated panels with extended warranty terms.
- Direct-to-contractor digital platforms:Regional distributors are deploying configuration tools that bypass traditional two-step distribution, capturing margin and order flow from independent roofing contractors.
Industry Challenges
- Certified coil-coating technician scarcity:ASTM A755 audit requirements and resin system chemistry complexity constrain qualified labor pools, extending line qualification timelines.
- Cool-roof rating verification bottlenecks:CRRC (Cool Roof Rating Council) third-party certification for solar reflectance index and thermal emissivity creates 90-120 day approval delays, slowing project bid cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA and Canada Pre-Painted Steel Roofing and Cladding Market |
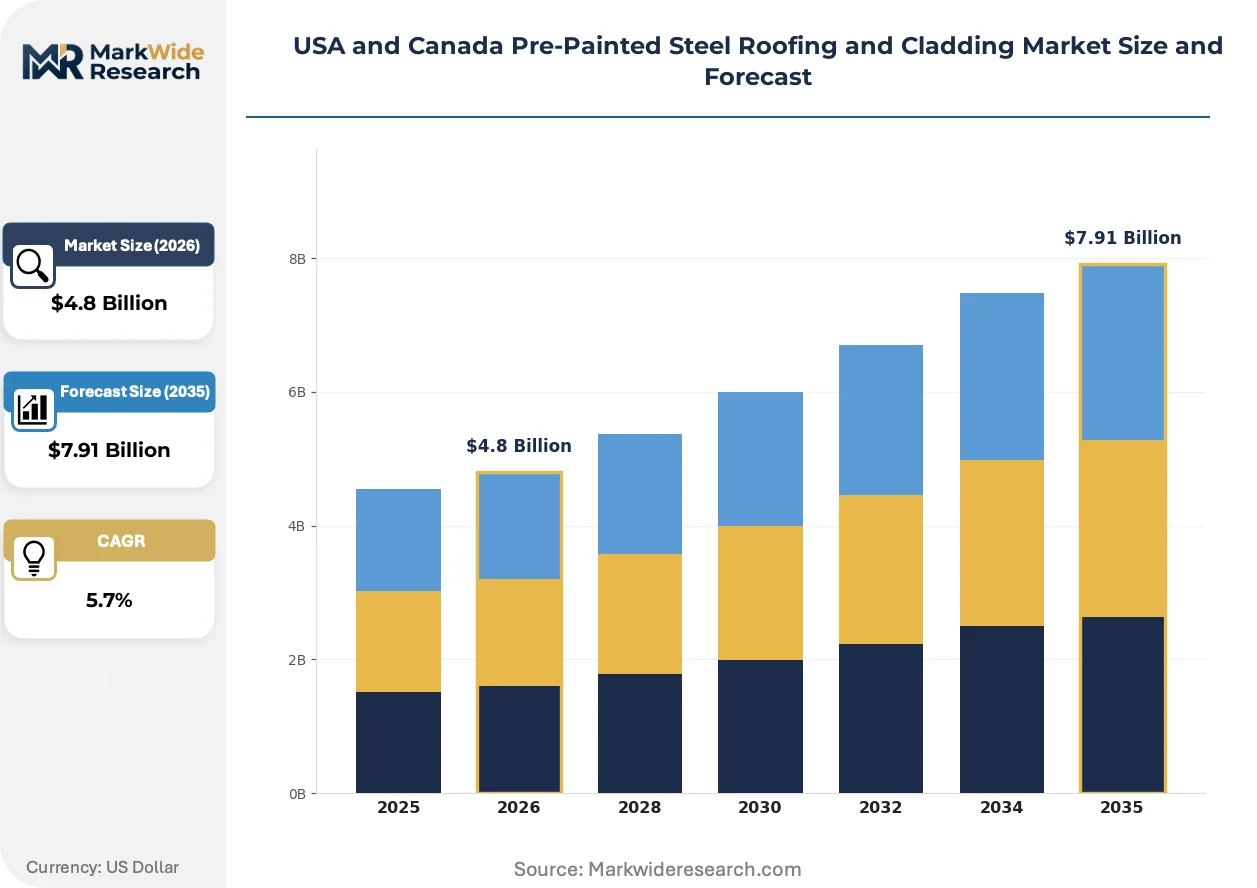
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Agricultural, Industrial Material: Steel, Aluminum, Copper, Zinc Coating Type: PVC, Polyurethane, Polyester, Epoxy Application: Roofs, Walls, Canopies, Sheds |
| Companies Covered | ArcelorMittal, ATAS, Englert Inc., Tata BlueScope Steel, Western States Metal Roofing, Flexospan Steel Buildings, Inc., ExSteel, Coastal Metal Service, Westman Steel Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA and Canada Pre-Painted Steel Roofing and Cladding Market Evolving Landscape
Cool-roof chemistry advances and procurement digitization are reconfiguring how architectural steel reaches end-users across North American construction markets.
PVDF resin systems with enhanced ceramic pigment loadings are decomposing the traditional warranty tiering between commercial and residential segments. Institutional buyers in Texas and Florida now specify these formulations for 40-year performance guarantees previously reserved for monumental architecture. The technology is compressing price premiums and enabling specification upgrades across mid-market commercial projects.
The Inflation Reduction Act's 179D commercial building deduction is reshaping energy modeling requirements for roofing assemblies. Property developers in Virginia and Georgia now integrate pre-painted steel solar reflectance index values into whole-building performance simulations. Cool-roof-rated coil-coated products capture disproportionate specification share in LEED-targeted and BREEAM-registered developments.
Configuration-based ordering platforms are displacing traditional catalog-based procurement for standing-seam and concealed-fastener profiles. Independent roofing contractors in Colorado and Arizona now specify panel geometry, substrate gauge, and finish chemistry through distributor web interfaces with real-time mill availability. The shift concentrates order flow toward regional stocking locations with integrated slitting and forming capabilities.
USA and Canada Pre-Painted Steel Roofing and Cladding Market Segmentation
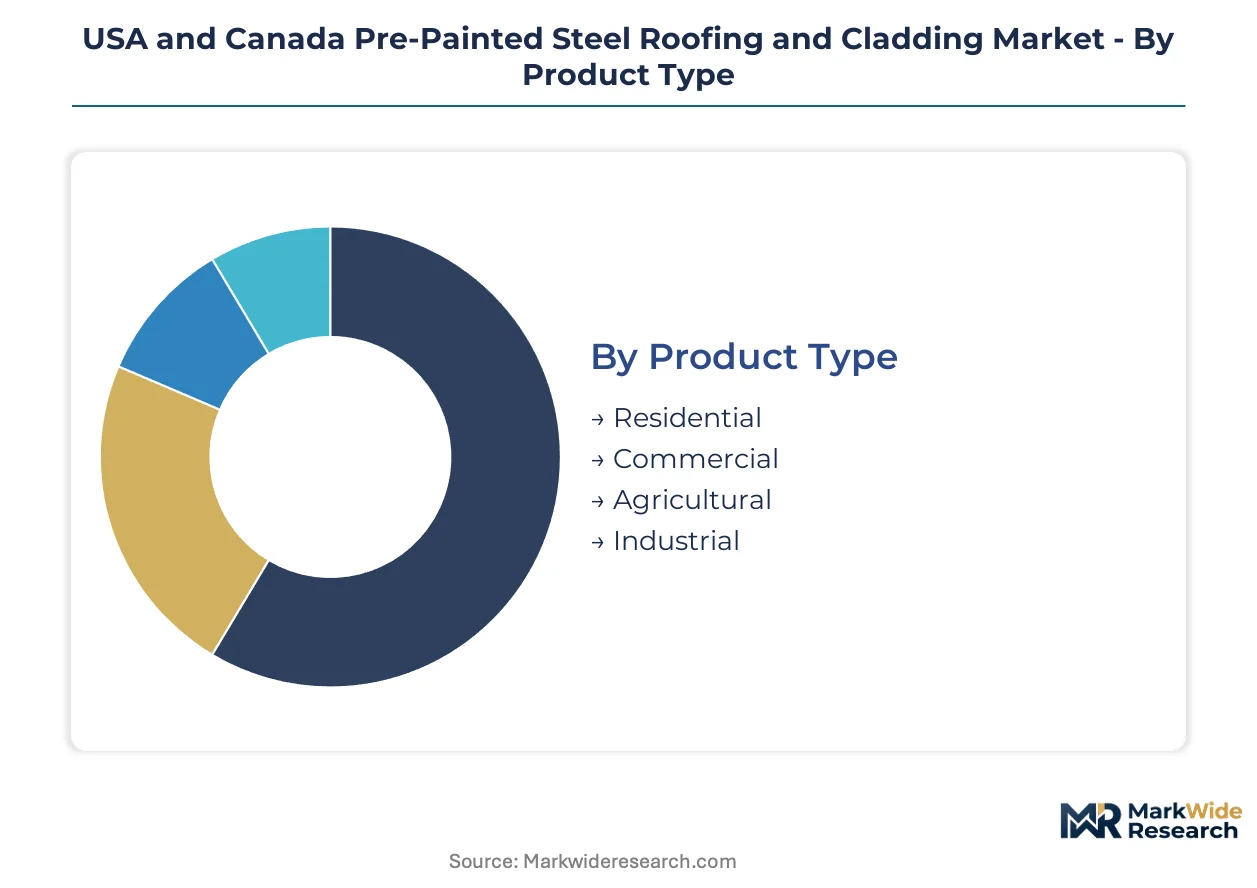
Segmentation in pre-painted steel roofing reveals how specification requirements fragment across construction verticals, with coating chemistry and substrate selection driving channel access and margin structure. Understanding these divides exposes where ASTM A755 certification creates competitive moats versus commodity exposure.
Product Type:
Residential volumes move through big-box retailers and regional distributors, while commercial and agricultural segments route through contractor-direct channels with specification engineering support.
- Residential:Gable and hip roof configurations dominate specification, with thinner-gauge coil-coated panels meeting 20-year warranty thresholds. Demand clusters in southeastern United States counties where FEMA wind-uplift codes trigger standing-seam upgrades over screw-down profiles.
- Commercial:Low-slope membrane replacement and cool-roof-rated PVDF assemblies command premium positioning. Hyperscale data centers in northern Virginia and Dallas-Fort Worth specify high-reflectance coatings for thermal load management, capturing Inflation Reduction Act 179D deductions.
- Agricultural:Post-frame buildings and equipment shelters prioritize cost efficiency over extended warranties, with silicone-modified polyester resin systems dominating procurement.
- Industrial:Manufacturing facilities and warehouses specify heavier substrate gauges for structural spanning, with coating selection driven by chemical resistance requirements rather than aesthetic performance.
By volume, residential leads. By growth pace, commercial is climbing the fastest.
Material:
Substrate selection maps directly to cost tier and corrosion environment, with coastal and high-humidity applications demanding premium metallurgy.
- Steel:Hot-dipped galvanized and Galvalume substrates comprise the architectural standard, with coil-coating lines in Indiana and Ohio controlling prime hot-rolled supply. Specification splits between commodity-grade residential panels and certified ASTM A755 commercial products with traceable substrate origin.
- Aluminum:Coastal Florida and Gulf Coast counties specify aluminum for salt-air corrosion resistance, with standing-seam profiles achieving enhanced wind-uplift ratings through lighter panel weight and superior fastener retention.
- Copper:Institutional and monumental architecture in Washington DC and Ottawa deploys copper for patina aesthetics and century-scale service life, with pre-painted variants rare due to natural weathering preference.
- Zinc:High-end residential and commercial facades in British Columbia and Pacific Northwest markets specify zinc for self-healing corrosion performance and matte aesthetic, with titanium-zinc alloys commanding substantial premiums over steel alternatives.
Steel dominates volume shipment. Zinc delivers the steepest margin expansion.
Coating Type:
Resin chemistry determines warranty tier and end-use eligibility, with fluoropolymer formulations capturing specification in incentive-qualifying commercial projects.
- PVC:Plastisol coatings dominate agricultural and industrial segments for impact resistance and chemical durability, with thick-film application compensating for lower UV stability versus fluoropolymer alternatives.
- Polyurethane:Modified formulations bridge residential and light-commercial applications, offering color retention and flexibility at mid-tier pricing between polyester and PVDF systems.
- Polyester:Standard polyester and silicone-modified polyester resin systems serve price-sensitive residential and agricultural markets. SMP formulations max out at 20-year warranties, blocking penetration into institutional segments demanding 40-year fluoropolymer alternatives.
- Epoxy:Interior and low-exposure applications specify epoxy primers and topcoats for chemical resistance, with limited exterior architectural use due to chalking and color fade under UV exposure.
Polyester leads shipment volume. Polyurethane is gaining specification share fastest in mid-market commercial retrofits.
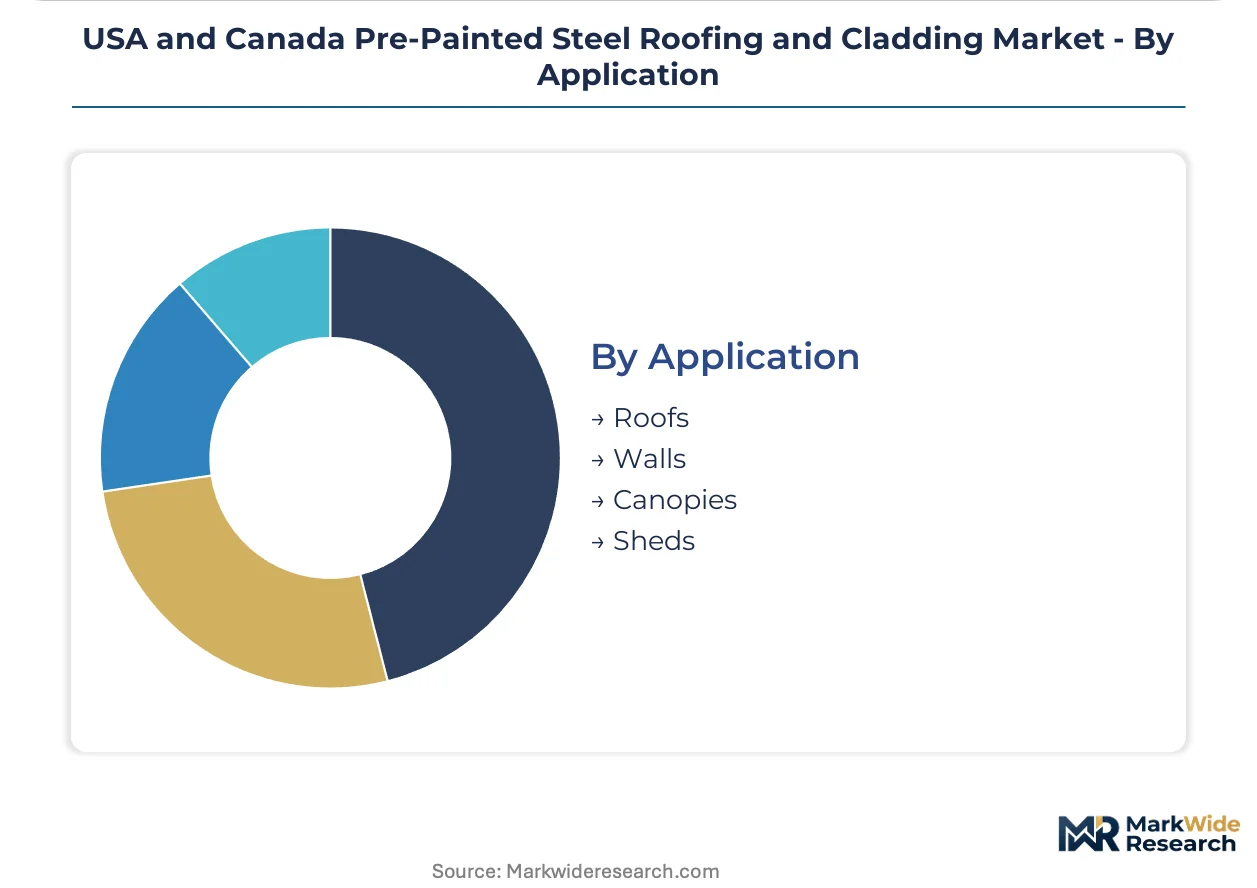
Application:
Roofing assemblies concentrate value capture through cool-roof certification requirements, while wall cladding specification fragments across aesthetic and thermal performance drivers.
- Roofs:Steep-slope and low-slope configurations drive the majority of coil-coated steel consumption, with CRRC-rated products capturing disproportionate share in LEED-targeted developments. Standing-seam profiles with concealed fasteners dominate hurricane-prone counties for wind-uplift performance.
- Walls:Rainscreen and insulated metal panel assemblies specify pre-painted steel for both aesthetic and thermal envelope performance. British Columbia and Ontario energy step codes drive demand for thermally broken cladding with reflective surfaces.
- Canopies:Entrance and walkway coverings prioritize architectural expression through custom color matching and special effect finishes, with shorter structural spans permitting lighter gauge substrates.
- Sheds:Utility and storage structures represent the most price-sensitive application segment, with screw-down profiles and commodity-grade coatings dominating procurement through retail channels.
Roofs lead by installed square footage. Walls show the steepest specification upgrade trajectory as energy codes tighten across both countries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's energy efficiency tax credits and FEMA hurricane-resistant building codes are redistributing demand across North American construction markets. Specification patterns now cluster around incentive-qualifying commercial developments and wind-uplift-rated coastal zones.
Southeastern United States
Data center construction in northern Virginia and Dallas-Fort Worth accelerates cool-roof-rated PVDF specification for thermal load management. FEMA building codes in Atlantic and Gulf Coast counties mandate standing-seam profiles with enhanced fastener retention. Atlanta and Miami contractors report 40-year warranty upgrades displacing 20-year silicone-modified polyester systems in mid-market commercial projects.
Western United States
Direct-to-contractor digital platforms concentrate order flow toward regional stocking locations with integrated slitting and forming capabilities. Colorado and Arizona contractors now configure panel geometry through distributor web interfaces with real-time mill availability. California's Title 24 energy code drives thermally broken cladding assemblies with reflective pre-painted steel surfaces in Sacramento and Los Angeles metro construction.
Texas
Hyperscale facility development in Dallas-Fort Worth specifies high-reflectance coil-coated roofing to capture 179D commercial building deductions. ERCOT grid reliability concerns amplify thermal envelope performance requirements for mission-critical infrastructure. Houston and San Antonio markets show accelerated standing-seam adoption as hurricane-resistant codes expand inland from coastal counties.
Ontario
Provincial energy step codes in Toronto and Ottawa drive demand for thermally reflective cladding assemblies with extended warranty terms. Canada's National Building Code harmonization with federal rebate programs tightens solar reflectance index thresholds for commercial eligibility. Hamilton and Kitchener-Waterloo industrial corridors specify heavier substrate gauges for manufacturing facility expansions.
British Columbia
Vancouver and Victoria municipal energy mandates accelerate specification of cool-roof-rated assemblies in LEED-targeted developments. Pacific Northwest salt-air corrosion resistance favors aluminum standing-seam profiles in coastal Vancouver Island applications. Interior British Columbia agricultural retrofit cycles open specification pathways for next-generation coil-coated panels as aging metal building stock approaches replacement windows.
USA and Canada Pre-Painted Steel Roofing and Cladding Market Competitive Landscape
Player mix skews toward integrated steelmakers and specialized regional fabricators. The supplier base compresses around ASTM A755-certified coil-coating operations with captive hot-rolled substrate supply. Two strategic archetypes dominate: integrated mills controlling upstream metallurgy and regional formulators with hurricane-zone engineering specialization. Competitive moves concentrate on capacity consolidation in Indiana and Ohio steel corridors and digital platform deployment for contractor-direct order capture.
Among integrated North American steelmakers, ArcelorMittal anchors the upstream-controlled archetype with captive hot-rolled coil supply for architectural products. ATAS and Western States Metal Roofing exemplify regional specialists with standing-seam profile engineering and direct-to-contractor distribution models respectively. These three occupy positions across the value chain from substrate metallurgy through specification engineering to last-mile contractor access.
| Leading Market Players |
|---|
| ArcelorMittal |
| ATAS |
| Englert Inc. |
| Tata BlueScope Steel |
| Western States Metal Roofing |
| Flexospan Steel Buildings, Inc. |
| ExSteel |
| Coastal Metal Service |
| Westman Steel Industries |
| Others |
Value Network & Pricing Analysis
Galvalume substrate substitution for hot-dipped galvanized steel is redrawing procurement geography across Indiana and Ohio mill corridors while compressing margin structures for independent coil-coaters lacking captive metallurgical supply. This metallurgical shift simultaneously concentrates pricing power among integrated steelmakers and exposes non-integrated fabricators to London Metal Exchange volatility in aluminum and zinc inputs.
Pricing Analysis
Certification level creates the primary spread across ASTM A755-qualified commercial products and uncertified residential commodity panels. Three-tier pricing structure across premium PVDF, standard polyurethane, and economy silicone-modified polyester resin systems dominates transactional patterns. Pricing pressure stems from zinc and aluminum input cost volatility transmitted through Galvalume substrate contracts. Agricultural buyers exhibit highest price sensitivity while data center developers absorb premium positioning for cool-roof-rated assemblies.
Supply Chain Analysis
Inbound logistics costs through Great Lakes port congestion and Chicago rail hub bottlenecks amplify working capital requirements for regional stocking distributors. Geographic supply concentrates in the United States, Canada, and Mexico under USMCA trade frameworks. Raw material dependencies center on prime hot-rolled coil, fluoropolymer resin systems, and ceramic pigment loadings. Single-source vulnerability sits with integrated steelmaking operations in Indiana and Ohio controlling substrate metallurgy. Distribution runs through two-step distributor networks with direct-to-contractor digital platforms gaining specification influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in warranty administration and cool-roof certification consulting are expanding faster than panel fabrication revenue as commercial buyers demand performance guarantees spanning 40-year horizons. Recurring revenue from specification engineering and CRRC compliance support now commands margin premiums exceeding commodity panel production.
For Market Incumbents: Compound ASTM A755 certification advantages by acquiring independent coil-coating lines in hurricane-prone southeastern counties where FEMA codes accelerate standing-seam specification. Defend against digital distributor disintermediation through captive contractor portal deployment with real-time mill availability. Prioritize backward integration into resin system blending to offset fluoropolymer raw material volatility. For New Entrants and Emerging Players: Differentiate on CRRC certification speed by building pre-submitted cool-roof rating libraries that bypass 90-120 day approval bottlenecks. Target agricultural retrofit cycles across the US Corn Belt where aging metal building stock approaches replacement windows with limited incumbent specification engineering presence. Pursue direct-to-contractor digital configuration tools as primary go-to-market architecture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional fabricators holding hurricane-zone engineering expertise but lacking integrated substrate supply. Long-term viability hinges on ASTM A755 certification moats and digital platform deployment within a decade horizon. Monitor Inflation Reduction Act incentive threshold adjustments as inflection signal for cool-roof-rated product demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM A755 Certification Investment | Certified coil-coating lines in Indiana and Ohio secure specification access to commercial data center projects. |
| Backward Integration into Resin Blending | In-house fluoropolymer formulation reduces exposure to specialty chemical supplier pricing volatility. |
| Direct-to-Contractor Digital Platform | Configuration tools with real-time mill availability capture margin from traditional two-step distribution. |
| CRRC Pre-Certification Library Buildout | Pre-submitted cool-roof ratings compress project bid cycles for LEED-targeted developments. |
| Hurricane-Zone Regional Capacity Addition | Standing-seam forming capabilities in Gulf Coast counties address FEMA wind-uplift code mandates. |
Research Methodology
A spread of perspectives from coil-coating line operators, commercial roofing contractors, distributor procurement managers, and CRRC certification specialists converged on the working assumptions driving volume and value estimates. Primary interviews with ASTM A755 audit participants and FEMA code enforcement officers in Atlantic and Gulf Coast counties supplemented secondary validation through SEC filings of integrated steelmakers, US Census construction spending data, and Cool Roof Rating Council product directories. Bottom-up panel shipment triangulation against top-down construction square footage analysis anchored the analytical framework.
Segmentation dimensions modeled include coating chemistry tier, substrate metallurgy type, end-use application, and regional regulatory cluster across the analysis window. CAGRs derived from historical shipment correlations with construction permit data and forward projections of data center development pipelines. Forecast inputs incorporated Inflation Reduction Act incentive qualification thresholds and provincial energy step code adoption trajectories in British Columbia and Ontario.
Material uncertainties — zinc and aluminum commodity price swings, CRRC certification timeline extensions, and FEMA code expansion beyond coastal counties — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued federal energy efficiency incentive continuity and stable USMCA trade framework access. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Concrete Sealer Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Central & South America Iron Casting Market