
 Italy Prefab Wood Buildings Market | 2026-2036
Italy Prefab Wood Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Prefab Wood Buildings Market Foresight
Italian carpentry and timber engineering talent is rotating toward factory-based prefabrication, pulling skilled labor from traditional on-site construction. Wolf Haus leverages its manufacturing scale to dominate northern Italy's panelized home segment. Marlegno S.r.l. anchors its position through specialization in engineered wood systems for alpine climates. X-LAM DOLOMITI SPA competes by controlling cross-laminated timber supply chains from forestry through fabrication.
Prefab wood buildings are structural enclosures manufactured off-site using engineered timber products such as cross-laminated timber panels measuring up to 3.5 meters in width, then transported for rapid on-site assembly to reduce construction duration and material waste. Panelized homes lead volume due to established supply chains and builder familiarity, while modular homes represent the fastest-growing category as homeowners seek turnkey solutions with shorter completion timelines. Cross-laminated timber construction commands premium positioning among architects pursuing biogenic carbon storage and seismic performance certification.
Italy's National Recovery and Resilience Plan (PNRR) and the EU Green Deal's building performance standards are tightening energy efficiency requirements for residential construction, directly expanding addressable demand for high-performance prefab wood envelopes. BIS and CE marking compliance for structural timber products shapes factory investment decisions and market access protocols. Stakeholders must monitor how Superbonus incentive modifications and EU taxonomy alignment rules reshape project economics for factory versus site-built alternatives.
Market Dynamics
Italy's prefab wood buildings sector is undergoing a labor-market reconfiguration as skilled carpenters migrate from traditional construction sites to factory-based production facilities, fundamentally altering how building envelopes are manufactured and assembled.
Growth Catalysts
- Superbonus 110% Tax Incentive:Italy's fiscal mechanism for deep energy retrofits is channeling homeowner capital toward high-performance wood envelopes that qualify for full cost recovery.
- EU Green Deal Building Performance Standards:The tightening regulatory framework for carbon-neutral construction is mandating biogenic materials in public procurement tenders.
- Cross-Laminated Timber Expertise Clustering:Trentino-Alto Adige's concentration of forestry-to-fabrication capabilities is generating specialized labor pools and supplier networks.
Market Restraints
- Softwood Input Cost Volatility:Nordic and Baltic timber supply disruptions are compressing margins for panelized home manufacturers dependent on imported structural-grade lumber.
- CE Marking Compliance Burden:Factory investment requirements for structural timber product certification are creating capital barriers for small-scale fabricators.
- Concrete-Steel Substitution Threat:Traditional masonry construction retains builder familiarity and financing institution collateral valuation preferences in southern Italy.
Strategic Opportunities
- Seismic Zone Applications:High-risk earthquake regions across central Italy present underpenetrated demand for lightweight timber frames with ductile connection systems.
- PNRR Public Housing Allocation:Italy's National Recovery and Resilience Plan is earmarking funds for social housing projects with sustainability performance thresholds.
- Digital Fabrication Convergence:Integration of CNC machining with BIM workflows is enabling mass-customization at panelized production scales previously reserved for modular systems.
Industry Challenges
- On-Site to Factory Skill Translation:Traditional carpentry expertise requires retraining for precision manufacturing tolerances and automated equipment operation.
- Multi-Trade Coordination Complexity:Prefab envelope installation demands synchronized scheduling with MEP contractors unaccustomed to compressed assembly timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Prefab Wood Buildings Market |
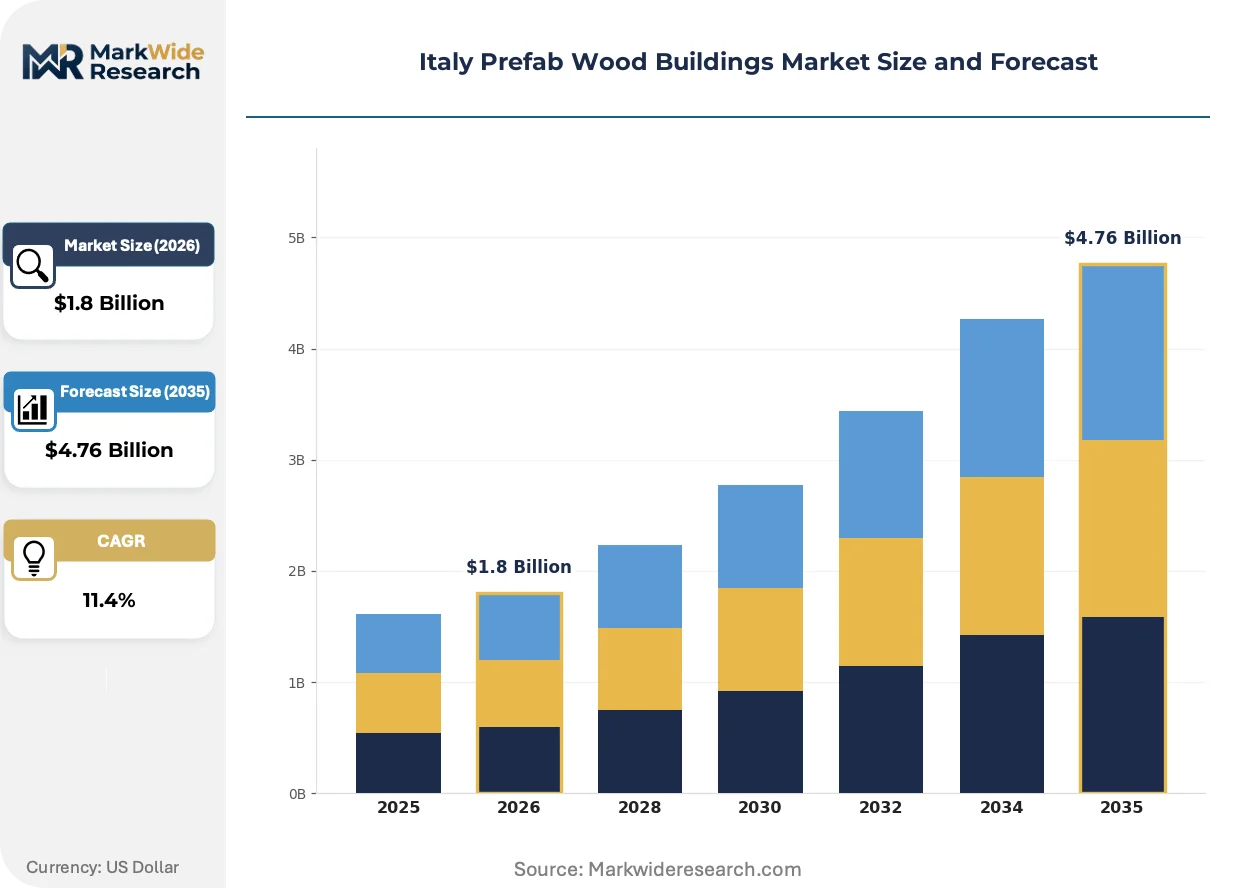
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Prefabricated Components, Hybrid Structures Application: Residential, Commercial, Educational, Recreational Construction Method: Stick-Built, Pre-Cut, Truss Systems, Cross-Laminated Timber End User: Homeowners, Builders, Contractors, Architects |
| Companies Covered | Pagin Srl, Wood System International S.r.l., Leap Factory srl, CO.RI.MEC. Italiana S.p.A., Greenbuild Srl, X-LAM DOLOMITI SPA, Wolf Haus, WOODBETON SPA, Marlegno S.r.l., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Prefab Wood Buildings Market Shifts & Advancements
Digital design-to-fabrication workflows are collapsing traditional construction timelines while regulatory pressure on embodied carbon intensifies material specification scrutiny across Italian residential development.
Cross-laminated timber is decomposing conventional multi-story construction sequencing by enabling load-bearing wall panels to serve as finished interior surfaces. Alpine hospitality developers are specifying exposed CLT ceilings to reduce interior fit-out duration. This technology is compressing project schedules from structural frame to weather-tight envelope.
Italy's Superbonus incentive modifications are tightening technical eligibility criteria for prefab wood systems seeking 110% tax recovery. The industrial consequence is factory investment in blower-door testing capabilities and thermal bridge modeling software. Northern Italian manufacturers with established certification protocols are capturing disproportionate share of qualifying projects.
Homeowner specification behavior is migrating from contractor-driven selection toward architect-mediated material choices. Design studios in Milan and Turin are establishing direct procurement relationships with CLT fabricators, bypassing traditional general contractor intermediaries. This channel disintermediation is most pronounced in custom single-family residential segments above 300,000 euro construction value.
Italy Prefab Wood Buildings Market Segmentation
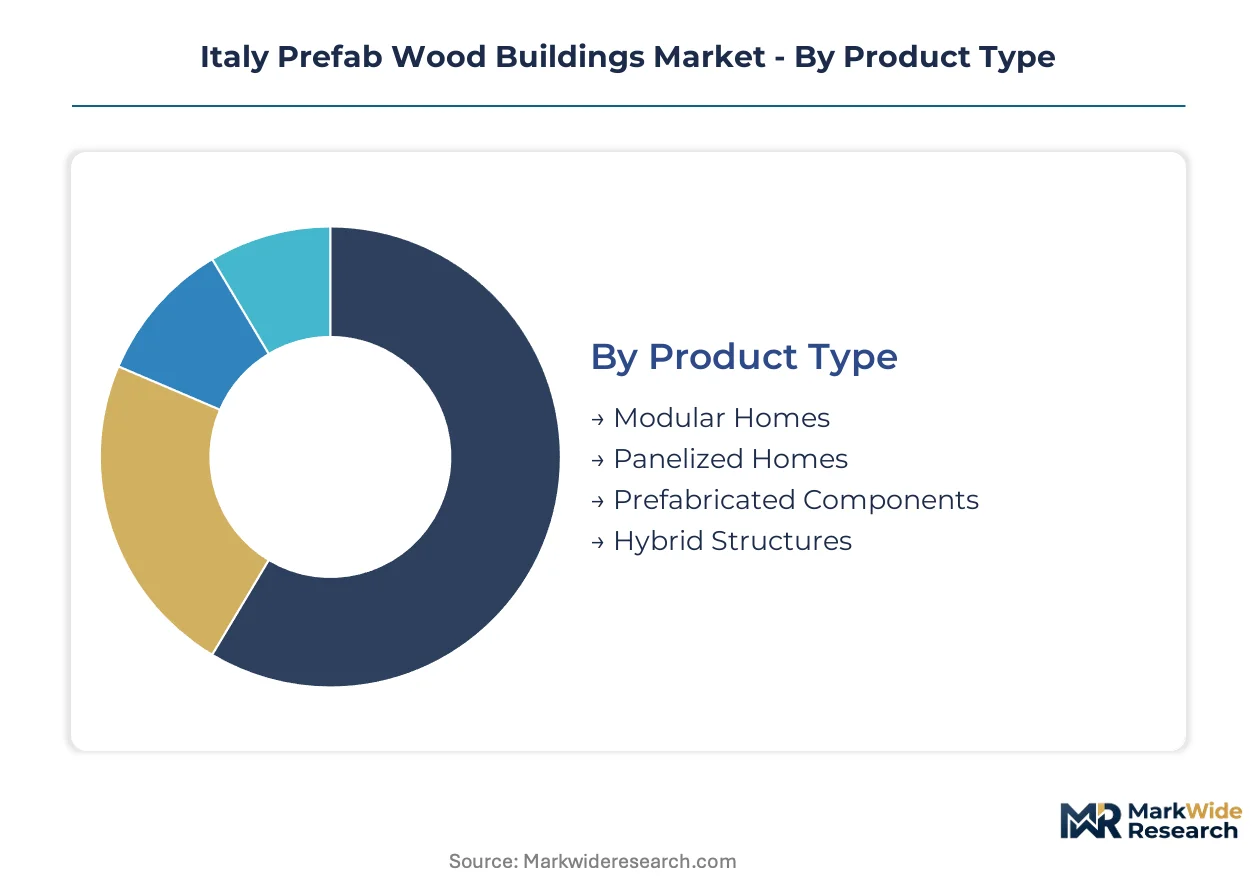
Italy's prefab wood buildings market fragments across four distinct dimensions that determine factory investment priorities and project qualification pathways. Superbonus 110% incentive eligibility varies sharply by construction method and product type, reshaping manufacturer specialization strategies.
Product Type:
CE marking requirements under the EU Construction Products Regulation create divergent compliance burdens across factory production models, with modular systems facing the most intensive type-testing protocols for complete building system certification.
- Panelized Homes:Structural wall and roof panels manufactured in climate-controlled facilities using oriented strand board sheathing and engineered lumber framing, then transported flat-packed for on-site crane assembly. Northern Italy's Alpine provinces concentrate demand from developers pursuing rapid envelope closure in seismic zones, constrained by truck transport dimensional limits for rural mountain access roads.
- Modular Homes:Three-dimensional volumetric units produced to near-completion in factory conditions including MEP rough-ins and interior finishes, then module-stacked on prepared foundations. Milan and Turin metropolitan areas generate specification from homeowners seeking turnkey solutions with compressed completion timelines, though highway transport restrictions on module width constrain design flexibility.
- Prefabricated Components:Discrete structural elements including prefabricated floor cassettes, roof trusses, and wall panels sold as kit packages to traditional builders. Demand concentrates among small-scale contractors in central Italy adapting existing masonry construction workflows.
- Hybrid Structures:Mixed-material systems combining timber frames with steel moment connections or concrete cores for multi-story applications. Commercial developers in Bologna and Florence specify these for mid-rise office buildings seeking biogenic carbon accounting benefits.
Panelized homes handle the majority of throughput; modular homes are gaining share fastest as architect-procurement relationships bypass traditional contractor channels.
Application:
Project financing availability and collateral valuation practices vary substantially across end-use categories, with residential applications commanding preferential terms from Italian banking institutions familiar with single-family home lending protocols.
- Residential:Single-family detached homes and multi-family housing units manufactured to homeowner or developer specifications. Trentino-Alto Adige and Lombardy lead volume as Superbonus incentives channel capital toward deep energy retrofits and new high-performance construction.
- Commercial:Office buildings, retail structures, and hospitality facilities utilizing exposed timber aesthetics for brand differentiation. Alpine tourism operators specify cross-laminated timber for reduced interior fit-out duration in seasonal construction windows.
- Educational:Schools and university buildings procured through public tender processes with sustainability performance thresholds. Italy's PNRR social infrastructure allocation is expanding this segment through performance-based contracting.
- Recreational:Ski resort facilities, mountain refuges, and agritourism structures requiring rapid seasonal assembly. Seismic performance certification drives specification in central Apennine locations.
Residential applications dominate factory output volumes; commercial projects are expanding most quickly as EU Green Deal public procurement mandates tighten.
Construction Method:
Material input costs and skilled labor requirements diverge substantially across fabrication approaches, with automated cross-laminated timber pressing demanding capital investment levels that consolidate production among scaled manufacturers.
- Cross-Laminated Timber:Orthogonally layered solid-sawn lumber panels bonded with structural adhesives, serving as load-bearing walls, floors, and roofs with exposed interior finish potential. X-LAM DOLOMITI SPA and similar Trentino-based fabricators control regional supply chains from certified forestry through CNC machining.
- Stick-Built:Traditional dimensional lumber framing prefabricated into wall panels in factory conditions. Smaller fabricators in Veneto and Friuli-Venezia Giulia specialize in this method for cost-sensitive market tiers.
- Pre-Cut:Computer-numerically-controlled cutting of individual framing members delivered as numbered kit packages for on-site assembly. This method minimizes factory footprint requirements and serves remote project locations with limited crane access.
- Truss Systems:Prefabricated roof and floor trusses using metal plate connections for long-span applications without intermediate support. Agricultural and industrial building adaptations in Emilia-Romagna utilize this approach for wide clear spans.
Cross-laminated timber commands the premium tier on margin contribution; pre-cut systems are climbing the fastest as digital fabrication reduces engineering overhead for custom geometries.
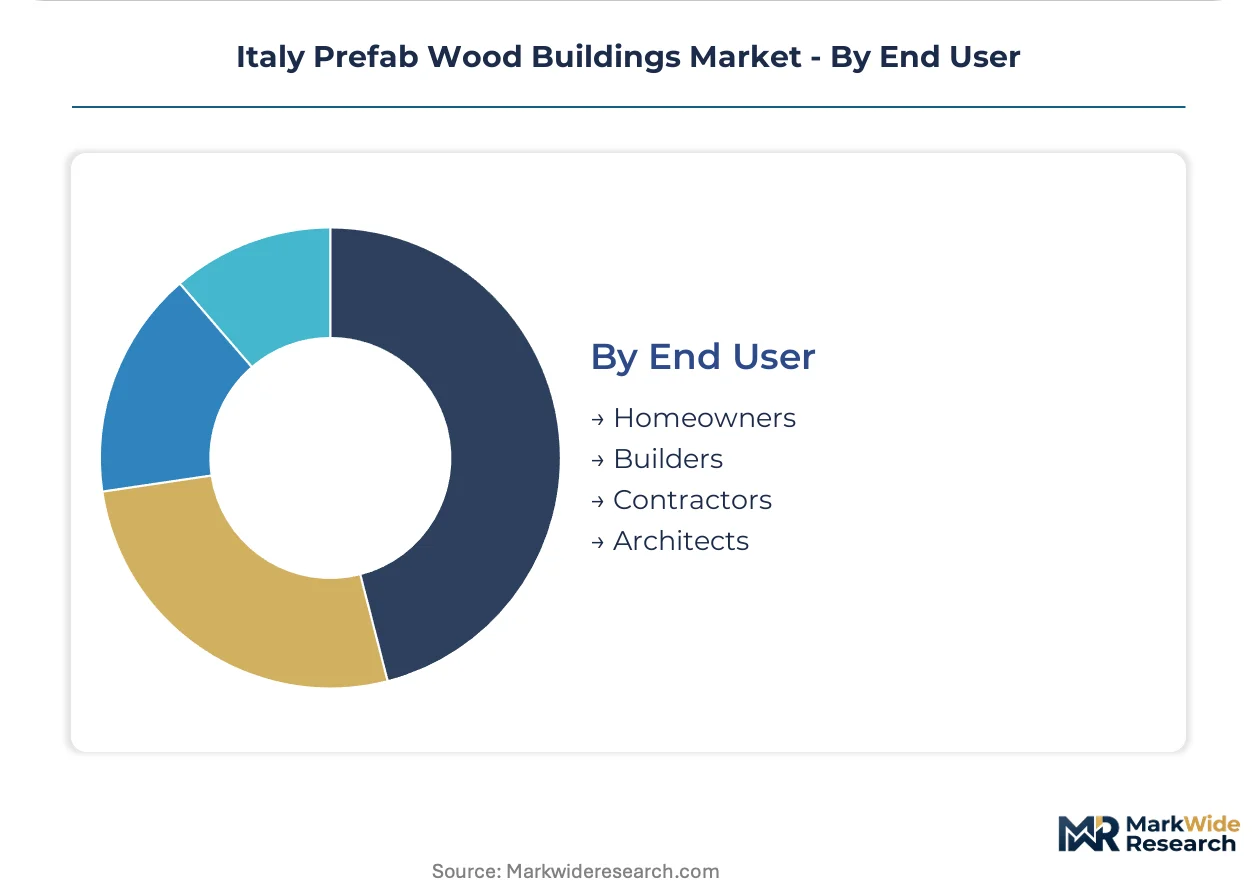
End User:
Procurement authority and technical specification capability vary dramatically across customer types, with architects increasingly displacing general contractors as the primary decision-makers in high-value residential segments.
- Architects:Design studios in Milan and Turin establishing direct procurement relationships with CLT fabricators, specifying material systems based on embodied carbon performance and aesthetic outcomes. This channel is most pronounced above 300,000 euro construction value.
- Homeowners:Individual clients navigating Superbonus incentive qualification requirements and contractor selection for single-family construction. Northern Italy's affluent provinces generate demand for turnkey modular solutions.
- Builders:Regional construction firms integrating prefab envelope systems into traditional project delivery models. These stakeholders prioritize panelized solutions compatible with existing masonry subcontractor relationships.
- Contractors:Large-scale infrastructure and commercial general contractors procuring hybrid structural systems for public and private developments. PNRR-funded social housing projects are expanding this customer base.
Builders currently account for the largest order volumes; architects are expanding their procurement influence fastest as design-to-fabrication workflows compress traditional construction timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's building performance standards anchor demand concentration across northern Italy, where Trentino-Alto Adige's forestry-to-fabrication clusters supply cross-laminated timber expertise to Alpine construction markets. Superbonus 110% tax incentives channel homeowner capital toward high-performance envelopes in Lombardy and Piedmont.
Lombardy
Milan's metropolitan construction boom drives specification for turnkey modular solutions with compressed completion timelines. The Superbonus incentive program qualifies prefab wood systems for full cost recovery when thermal performance thresholds are met. Bergamo and Brescia host panelized home manufacturers serving Alpine foothill developments.
Piedmont
Turin-based design studios establish direct procurement relationships with CLT fabricators, bypassing traditional contractor channels. The National Recovery and Resilience Plan allocates social housing funds with sustainability performance thresholds. The province of Cuneo concentrates pre-cut timber kit production for cost-sensitive market tiers.
Trentino-Alto Adige
Autonomous provincial forestry regulations sustain certified timber supply chains from mountain harvesting through CNC machining. Cross-laminated timber pressing facilities cluster around Bolzano and Trento, generating specialized labor pools. Alpine hospitality developers specify exposed CLT ceilings to compress interior fit-out duration.
Veneto
Stick-built prefabrication specialists serve mid-market residential segments with dimensional lumber framing systems. CE marking compliance requirements under the EU Construction Products Regulation shape factory investment decisions. The province of Belluno channels demand from seismic zone retrofits in central Dolomite valleys.
Emilia-Romagna
Bologna and Florence commercial developers specify hybrid timber-steel systems for mid-rise office buildings seeking biogenic carbon accounting. The region's agricultural building segment utilizes prefabricated truss systems for wide clear spans. PNRR infrastructure allocations expand public tender opportunities for educational and recreational structures.
Italy Prefab Wood Buildings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Italy's prefab wood buildings sector. Scaled manufacturers with automated CLT pressing capabilities command premium positioning among architect-specified projects, while regional stick-built specialists compete on price for contractor-driven residential segments. The market structure fragments across three strategic archetypes: forestry-integrated fabricators controlling supply chains from harvesting through fabrication, design-forward studios leveraging BIM-to-CNC workflows for mass customization, and volume panelized home producers optimizing transport logistics for northern Alpine access. Dominant competitive moves include backward integration into certified forestry operations and capacity expansion in blower-door testing capabilities to qualify for tightening Superbonus technical criteria.
Among Trentino-based forestry-integrated fabricators, X-LAM DOLOMITI SPA occupies a position exemplifying supply chain control from certified timber through precision machining. Wolf Haus represents the scale-driven archetype with manufacturing footprint optimized for panelized home throughput across northern provinces. Marlegno S.r.l. anchors the design-specialist tier through positioning in engineered wood systems for alpine climate performance.
| Leading Market Players |
|---|
| Pagin Srl |
| Wood System International S.r.l. |
| Leap Factory srl |
| CO.RI.MEC. Italiana S.p.A. |
| Greenbuild Srl |
| X-LAM DOLOMITI SPA |
| Wolf Haus |
| WOODBETON SPA |
| Marlegno S.r.l. |
| Others |
Supply & Pricing Matrix
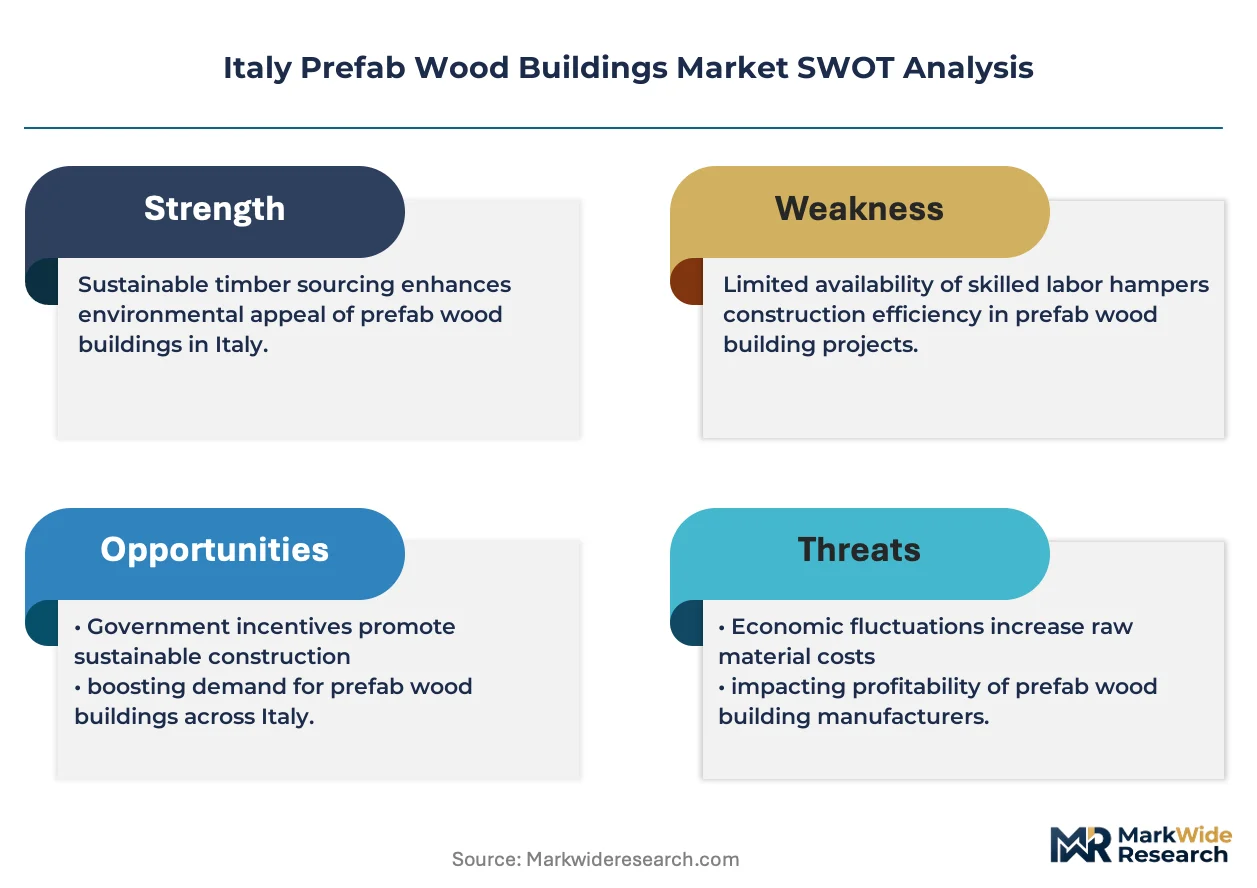
Cross-laminated timber substitution for concrete-steel hybrid cores is redrawing procurement geography toward Nordic and Baltic softwood suppliers while compressing margin structures for Italian panelized home manufacturers dependent on imported structural-grade lumber. This input shift simultaneously elevates transport cost sensitivity and amplifies pricing power for Trentino-Alto Adige fabricators with captive forestry holdings.
Pricing Analysis
Price spreads between northern Alpine provinces and southern Italian markets reflect Superbonus qualification premiums and CE marking compliance tiers. Three-tier pricing structure across premium certified CLT, standard panelized systems, and economy stick-built kits separates architect-specified projects from contractor-driven residential segments. Cost compression in the standard tier intensifies as Nordic timber supply disruptions elevate raw material exposure. Small-scale Veneto fabricators exhibit highest price sensitivity; Milan design studios procuring direct from CLT presses show lowest.
Supply Chain Analysis
Just-in-time inventory strategies dominate among Lombardy modular manufacturers synchronizing factory output with crane-scheduled site deliveries, while strategic softwood stockpiling persists among Trentino-Alto Adige forestry-integrated operators hedging Baltic supply volatility. Geographic supply concentration draws from Sweden, Finland, and Estonia for structural-grade spruce. Raw material dependencies rest on phenolic resin adhesives, CNC machining equipment, and blower-door testing apparatus. Single-source vulnerability runs through Nordic timber channels exposed to energy cost-driven curtailments. Distribution feeds from factory direct to architect-procured projects or through regional builder networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-based blower-door testing and thermal bridge modeling services are expanding faster than structural panel hardware as Superbonus technical eligibility tightens, creating recurring revenue attachments that outpace envelope component sales.
For Market Incumbents: Secure backward integration into certified forestry operations in Trentino-Alto Adige to defend against Baltic softwood cost volatility and cement supply chain control. Expand blower-door testing capacity to capture disproportionate Superbonus-qualified project share as technical criteria tighten. Channel control through direct architect relationships in Milan and Turin remains the priority lever against emerging design-forward competitors. For New Entrants and Emerging Players: CE marking fast-track investment unlocks modular home market access previously blocked by type-testing capital barriers. Central Italy seismic zone applications represent the most penetrable white-space, with lightweight timber frames for ductile connection systems underserved by incumbent Alpine specialists. Go-to-market positioning through PNRR social housing tender participation bypasses established contractor channel gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional panelized home producers in Veneto and Emilia-Romagna lacking CLT pressing capabilities or forestry integration. Long-term viability favors scaled manufacturers with BIM-to-CNC workflows and mass-customization infrastructure. The signal to watch is Superbonus incentive modification announcements that would abruptly reallocate project economics toward certified high-performance envelope specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Forestry | Trentino-Alto Adige timber holdings insulate margin structures from Nordic supply volatility. |
| Blower-Door Testing Capacity Expansion | Superbonus technical eligibility requires factory-integrated air-tightness verification protocols. |
| BIM-to-CNC Workflow Deployment | Milan design studios demand mass-customization at panelized production scales. |
| Seismic Zone Product Certification | Central Italy Apennine applications require ductile connection system validation. |
| PNRR Tender Participation Infrastructure | Social housing allocation channels public procurement toward sustainability-qualified fabricators. |
Research Methodology
Initial hypotheses were tested against primary input from CLT fabricator operations directors, architect studio principals, regional builder procurement managers, and Superbonus incentive consultants, then refined through secondary validation against EU Construction Products Regulation filings, Italian National Recovery and Resilience Plan allocation disclosures, and Trentino-Alto Adige provincial forestry harvest data. Bottom-up project pipeline triangulation with top-down regional construction permit analysis anchored volume estimates.
Variance decomposition across product type, construction method, application, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs derived from segment-level buildups incorporating Superbonus modification scenarios, EU Green Deal implementation timelines, and Nordic softwood supply elasticity assumptions. Industry-specific forecast inputs included CLT pressing capacity expansion schedules and architect-procurement relationship penetration rates.
Decision-makers should treat outputs as directional under sustained Superbonus incentive continuity and Nordic timber supply normalization; material deviation would warrant model refresh. Revision becomes warranted when EU taxonomy alignment rules or seismic certification requirements cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Wood Shingles Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Plastic Door and Window Market
Building & Construction Materials
India UPVC Doors and Windows Market