
 Magnesium Alloys Market | 2026-2036
Magnesium Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Alloys Market Intelligence
A significant shift from traditional aerospace applications toward high-volume automotive structural components is repositioning the Magnesium Alloys Market. This change favors producers capable of large-scale, cost-effective manufacturing for demanding automotive supply chains. Meridian Lightweight Technologies specializes in complex, high-performance die-cast parts for global automakers. Nanjing Yunhai Special Metals Co., Ltd. anchors a substantial portion of the world's primary magnesium supply, influencing raw material pricing. Norsk Hydro ASA leverages its extensive metallurgical expertise to develop new alloys for electric vehicle platforms.
Magnesium alloys are metallic materials primarily composed of magnesium, the lightest structural metal, alloyed with elements such as aluminum, zinc, silicon, or rare earths to enhance specific properties. These alloys offer superior strength-to-weight ratios and excellent machinability, making them ideal for applications requiring significant mass reduction. Cast alloys for automotive structural components constitute the largest and fastest-growing application segment. While wrought alloys for niche aerospace and consumer electronics applications hold a smaller share, they often command higher price points due to stringent performance and finishing requirements.
Regulatory frameworks are a critical factor shaping market direction. In Europe, vehicle CO2 emission standards under the EU Green Deal compel automakers to adopt lightweighting strategies. Similarly, Corporate Average Fuel Economy (CAFE) standards in the United States indirectly promote the use of lighter materials like magnesium. On the supply side, environmental regulations from China's MEE on energy-intensive magnesium smelting impact global production volumes and costs. Future success will require alloy producers to secure stable raw material sources while innovating to meet evolving automotive performance mandates.
Market Dynamics
The primary force shaping the magnesium alloys market is the structural pivot from specialized, low-volume aerospace components to mass-produced automotive parts. This transition, driven by electric vehicle lightweighting, favors producers with scalable, cost-efficient manufacturing capabilities.
Growth Catalysts
- Automotive Lightweighting Mandates:Stringent CO2 emission standards under the EU Green Deal and US CAFE regulations compel automakers to adopt lightweight materials for improved efficiency.
- Process Technology Advancement:Innovations in high-pressure die-casting enable production of larger, intricate structural components, displacing multi-part steel assemblies.
- Electric Vehicle Growth:The rapid expansion of electric vehicle manufacturing creates specific, high-volume demand for magnesium alloys in battery enclosures, motor housings, and body structures.
Market Restraints
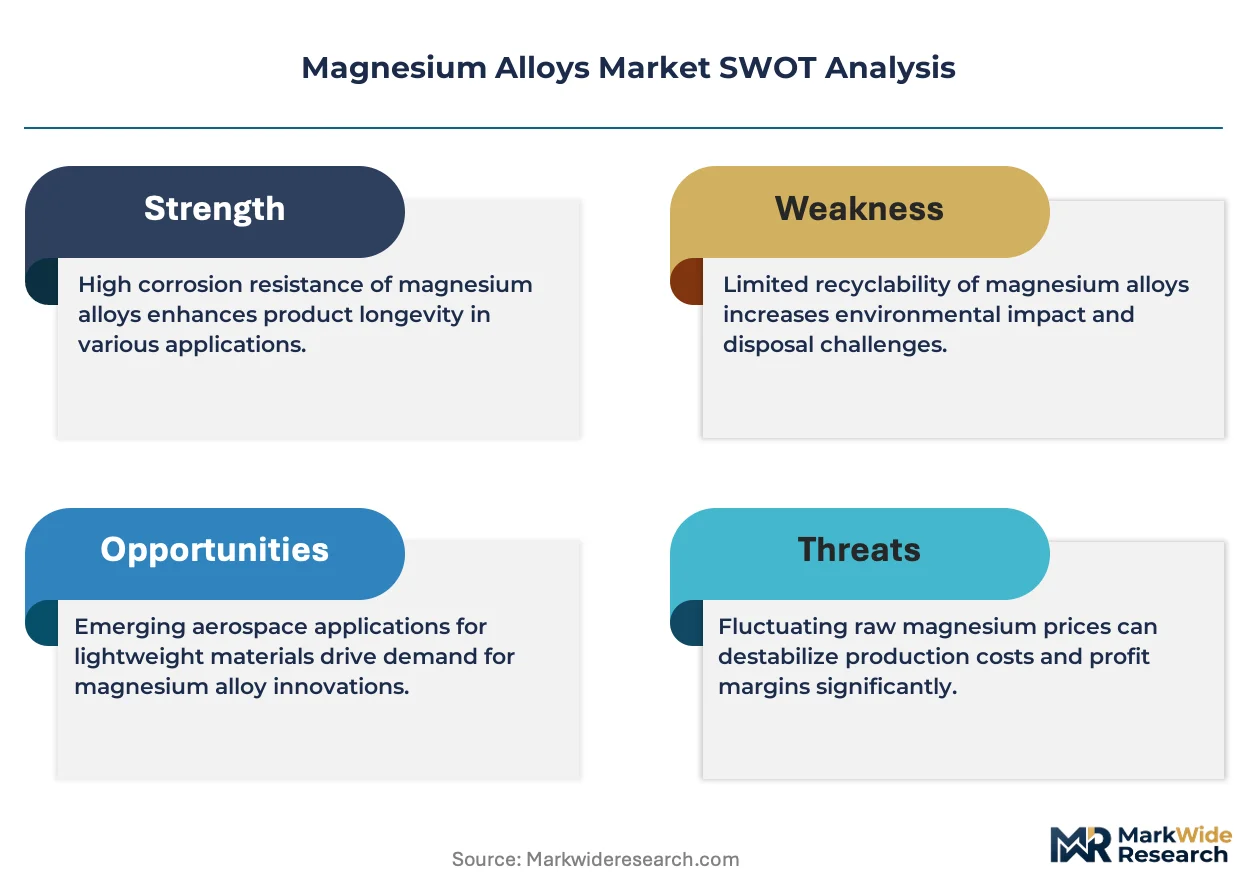
- Input Cost Volatility:The energy-intensive Pidgeon process in China links magnesium prices to volatile coal and electricity costs, creating input cost instability.
- Geopolitical Supply Risk:Heavy reliance on China for primary magnesium exposes North American and European users to significant geopolitical and logistical supply chain risks.
- Corrosion Management:The need for costly coatings to manage galvanic corrosion limits magnesium's use in multi-material assemblies, especially in exposed vehicle parts.
Strategic Opportunities
- New Alloy Formulations:Developing creep-resistant alloys for high-temperature automotive powertrain components opens a new value-added application segment beyond current structural uses.
- Secondary Material Markets:Establishing regional recycling infrastructure in Europe and North America for scrap creates a stable, low-carbon alternative to primary material imports.
- Biomedical Applications:Biodegradable magnesium alloys for temporary medical implants like screws and plates represent a high-margin niche outside of industrial markets.
Industry Challenges
- Production Decarbonization:Producers face high capital costs to decarbonize smelting operations, particularly under pressure from environmental regulators like China's MEE.
- Complex Assembly Integration:Integrating magnesium with steel or aluminum bodies requires specialized joining techniques that complicate high-volume automotive assembly.
- Design Expertise Shortage:A shortage of designers with expertise in magnesium's properties slows adoption and can lead to suboptimal component performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Alloys Market |
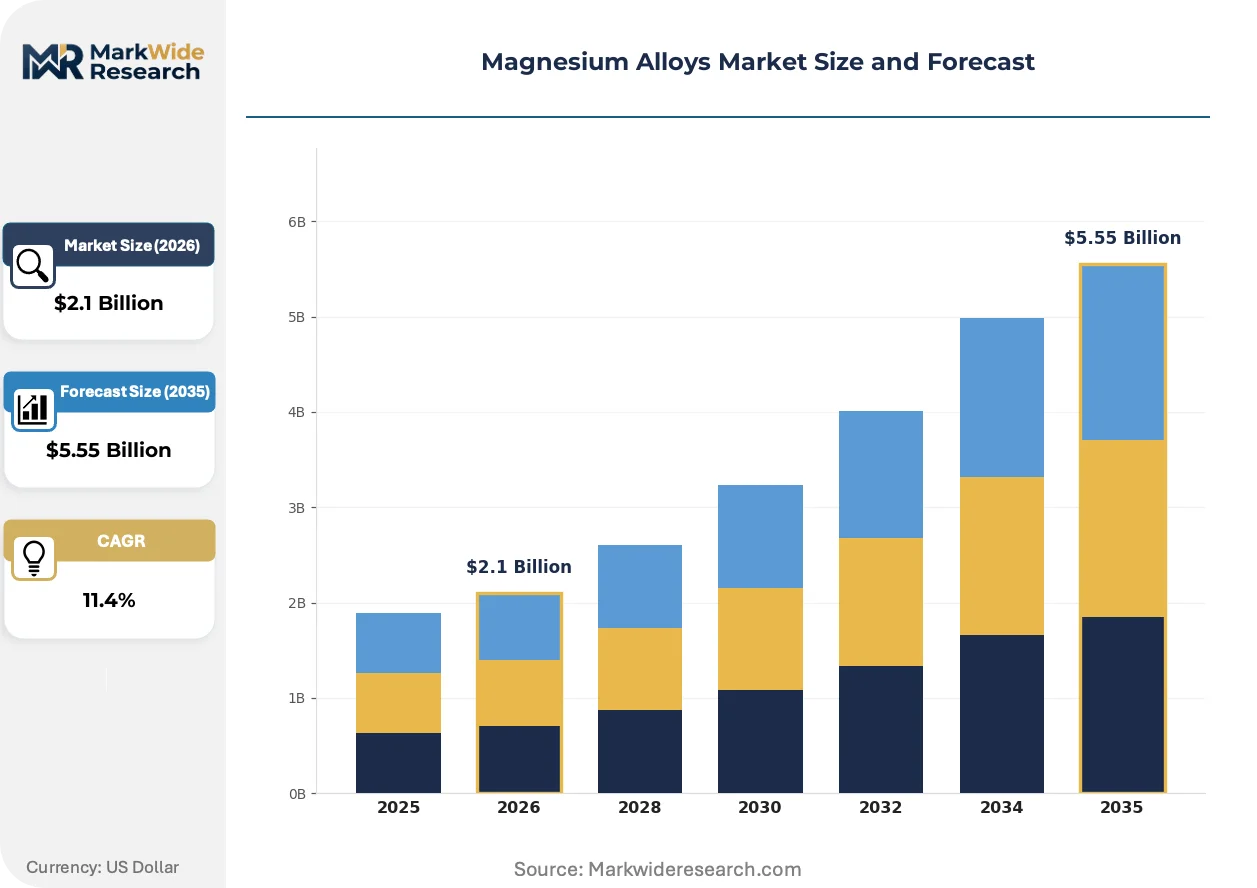
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Alloys, Wrought Alloys, Extruded Alloys, Rolled Alloys End User: Aerospace, Automotive, Electronics, Medical Devices Application: Structural Components, Powertrain, Interior Parts, Heat Exchangers Delivery Mode: Direct Sales, Distributors, Online Retailers, Third-Party Vendors |
| Companies Covered | US Magnesium LLC, Luxfer MEL Technologies, Meridian Lightweight Technologies, Dead Sea Magnesium Ltd., Nanjing Yunhai Special Metals Co., Ltd., Norsk Hydro ASA, Magontec Ltd., Dynacast, Magnesium Elektron Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Alloys Market Strategic Shifts & Innovations
The market's evolution is defined by the industrialization of manufacturing processes to meet automotive scale and the development of specialized alloys for electrification. This transition prioritizes process efficiency and material performance over traditional aerospace specifications.
Digital twin technology for high-pressure die-casting (HPDC) simulates the entire casting process, from mold filling to solidification. Automotive OEMs and Tier 1 suppliers are adopting this to reduce physical prototyping for complex parts like shock towers. This simulation-driven approach is automating process parameter optimization, ensuring higher yields and consistent microstructures in large-scale production.
Legislation like the European Union's Critical Raw Materials Act (CRMA) classifies magnesium as strategic, setting targets for domestic sourcing and recycling. This policy incentivizes investment in new EU production and recycling facilities to reduce import dependency. Alloy producers and automakers in Europe are now building more resilient, regionalized supply chains.
A shift from component purchasing to system-level design partnerships is altering how automakers source lightweight solutions. Automakers engage specialists earlier for entire sub-assemblies, like a front-end module, instead of sourcing individual parts. This model is most visible in North American and European EV sectors where rapid development is critical.
Magnesium Alloys Market Segmentation
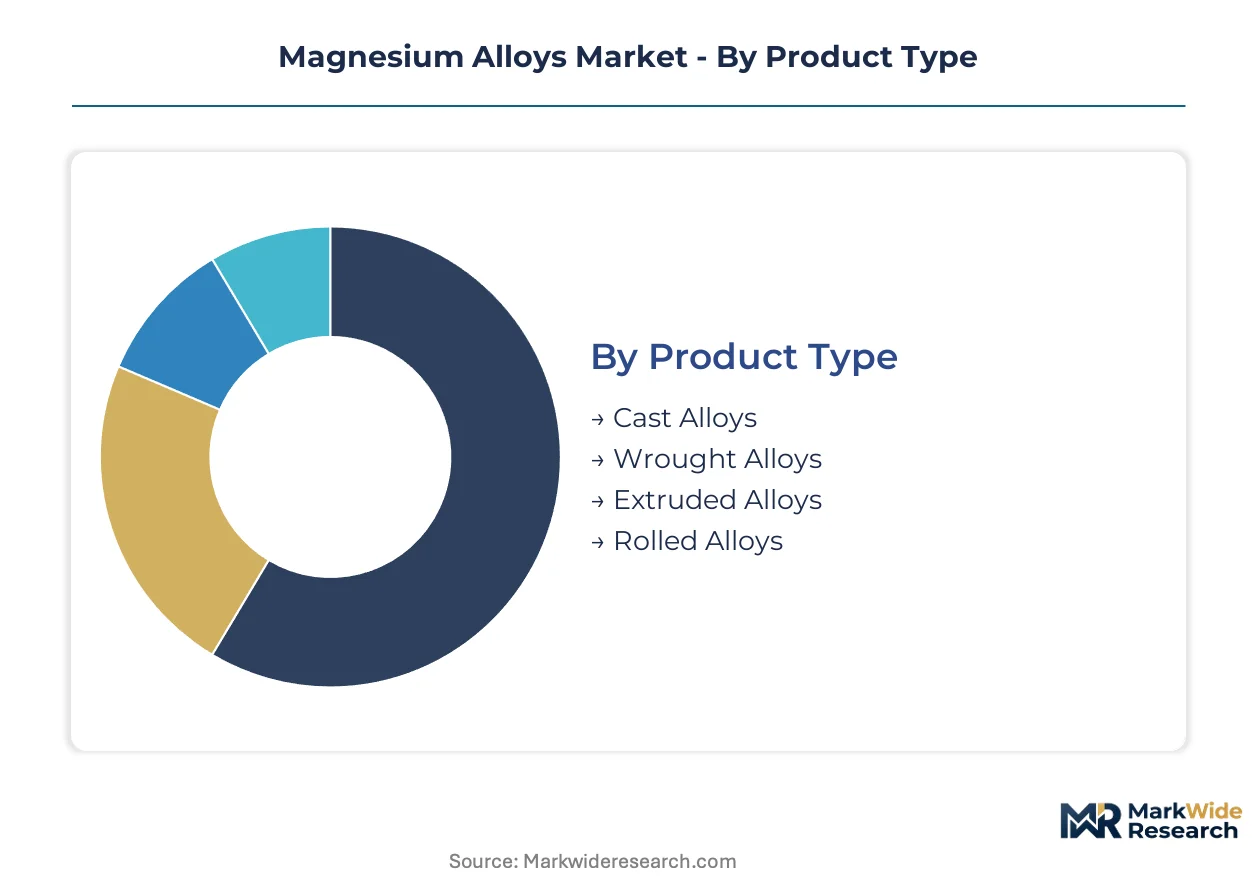
The Magnesium Alloys Market is segmented to provide a granular understanding of how different product forms, end-user industries, application areas, and delivery mechanisms influence market dynamics. This detailed breakdown highlights specific growth pockets and technological requirements across the value chain.
Product Type:
Selecting the appropriate magnesium alloy product type depends on balancing mechanical properties, manufacturing process compatibility, and final part performance requirements.
- Cast Alloys:These alloys are formed by pouring molten magnesium into molds, enabling complex shapes and high production volumes. Demand concentrates in the automotive sector for lightweight structural components like battery housings, driven by electric vehicle range mandates in Germany and China.
- Wrought Alloys:Wrought alloys are mechanically worked, such as forged or rolled, to enhance strength and ductility, often used for specialized components. Demand focuses on niche aerospace applications in the United States and high-performance consumer electronics, where superior mechanical properties justify higher costs.
- Extruded Alloys:These alloys are forced through a die to create uniform cross-sections, finding use in profiles and bars for industrial and automotive frames.
- Rolled Alloys:Rolled magnesium alloys produce sheets and plates, favored for thin-walled components and specialized aerospace panels due to their surface finish and formability.
Cast Alloys leads on scale; Wrought Alloys leads on momentum.
End User:
Different end-user industries drive magnesium alloy innovation by demanding specific performance characteristics and production volumes.
- Automotive:This sector leverages magnesium alloys for vehicle lightweighting to improve fuel efficiency and electric vehicle range. Demand is concentrating in China and Germany for large structural castings, driven by stringent CO2 emission standards.
- Medical Devices:Biodegradable magnesium alloys are gaining traction for temporary implants, offering bioresorbable solutions that eliminate the need for secondary surgeries. Demand is emerging in Europe and the United States for orthopedic screws and stents, supported by material innovation.
- Aerospace:Aerospace applications utilize magnesium alloys for their strength-to-weight ratio in non-critical structural parts and interiors, where weight reduction is paramount.
- Electronics:The electronics industry employs magnesium alloys for lightweight housings and casings in laptops and mobile devices, enhancing portability and heat dissipation.
The automotive segment exhibits the steepest expansion trajectory, while medical devices show significant emerging potential.
Application:
The volume and complexity of magnesium alloy parts vary significantly across different application areas within key industries.
- Structural Components:These applications include large castings for automotive body frames, subframes, and battery enclosures, where mass reduction directly impacts vehicle performance. Demand is strongest in the electric vehicle market, particularly for high-pressure die-cast parts in North America and Europe.
- Powertrain:Magnesium alloys in powertrain applications involve components like transmission housings and engine blocks, requiring excellent heat resistance and creep strength. The focus is on developing new alloy formulations that can withstand elevated operating temperatures in hybrid and internal combustion engines.
- Interior Parts:Magnesium alloys are used in vehicle interior parts such as seat frames, steering wheel cores, and dashboard supports, contributing to overall cabin lightweighting.
- Heat Exchangers:Specialized magnesium alloys are explored for heat exchanger applications due to their thermal conductivity and lightweight properties, although corrosion remains a challenge.
Structural Components command the largest market share, with Powertrain applications driving innovation in material properties.
Delivery Mode:
The preferred delivery mode for magnesium alloys often reflects the customer's purchasing volume, technical support needs, and supply chain integration requirements.
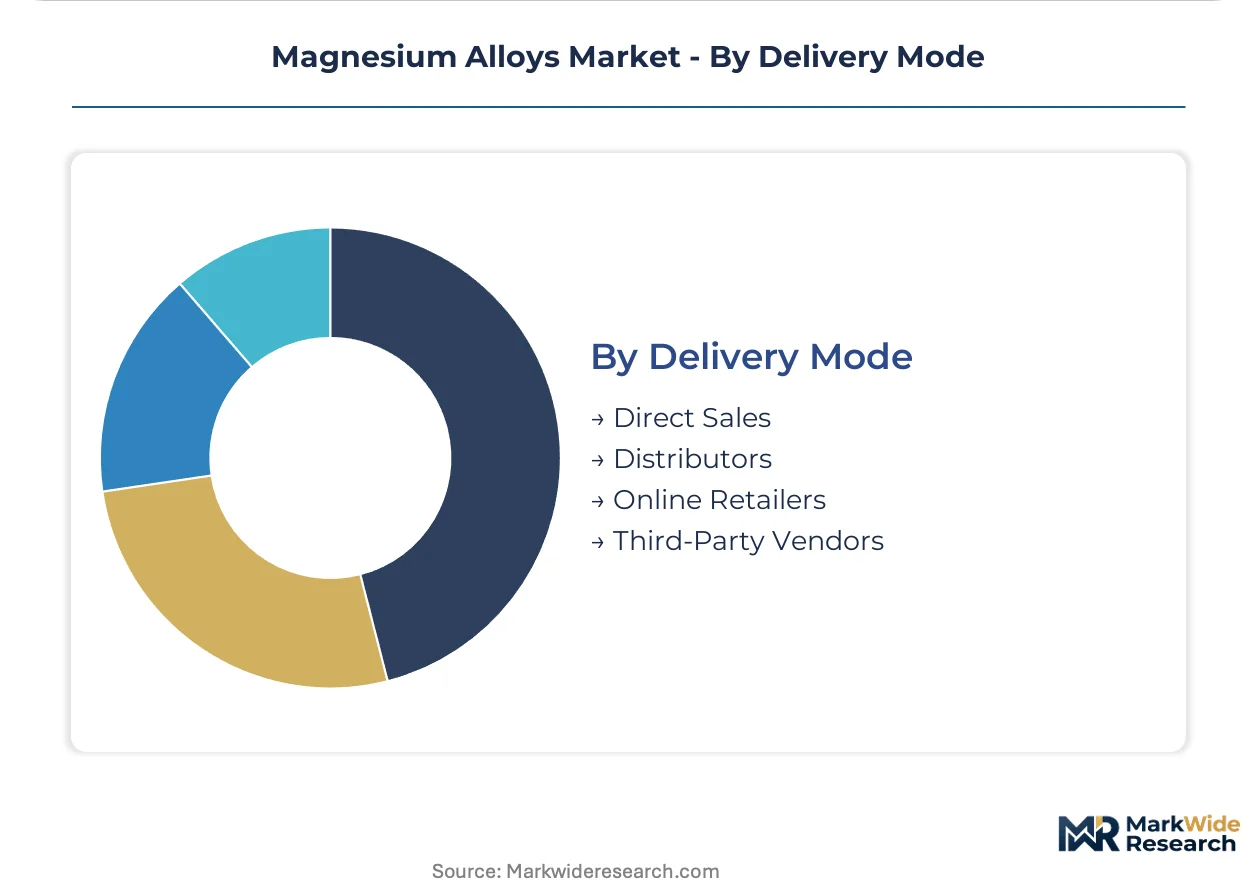
- Direct Sales:This mode involves direct engagement between alloy producers and large-volume customers, typically automotive OEMs or Tier 1 suppliers, for custom formulations and integrated supply. It offers closer technical collaboration and ensures stable, high-volume material flow for critical applications.
- Distributors:Distributors serve a broader customer base, including smaller manufacturers and specialized fabricators, by providing a range of standard alloy forms and managing inventory. This mode offers convenience and faster access to materials for diverse, lower-volume projects.
- Online Retailers:Online platforms facilitate the sale of standard magnesium alloy products, catering to research institutions, prototyping firms, and niche industrial buyers seeking quick procurement.
- Third-Party Vendors:These vendors often act as intermediaries, providing specialized services like processing, finishing, or logistics, particularly for complex supply chains or international transactions.
Direct Sales optimize supply chain efficiency for major customers, while Distributors provide essential flexibility for a wider market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's automotive manufacturing hubs drive significant demand for magnesium alloys, particularly for electric vehicle components. This global market expansion is influenced by regional policies and industrial concentrations that foster material innovation and adoption. Key countries are actively integrating lightweighting strategies into their manufacturing ecosystems.
China
China's robust electric vehicle sector creates substantial demand for magnesium alloys in battery enclosures and structural components. The Ministry of Ecology and Environment (MEE) regulations on energy-intensive smelting operations influence domestic production volumes and costs. Major EV manufacturing centers like those in the Yangtze River Delta continue to increase magnesium alloy integration for mass-produced vehicles.
Germany
Germany's premium automotive industry focuses on magnesium alloys for advanced lightweighting in luxury and electric vehicles. The EU Green Deal and stringent CO2 emission standards compel automakers to prioritize material efficiency. Manufacturing clusters in Bavaria are actively developing and integrating complex magnesium structural castings for next-generation platforms.
United States
The United States sees rising demand for magnesium alloys in electric vehicle battery housings and specialized aerospace applications. Corporate Average Fuel Economy (CAFE) standards indirectly promote lighter materials across the automotive sector. Michigan's automotive heartland is increasingly exploring magnesium solutions for vehicle body structures and interior components.
Japan
Japan's automotive and electronics industries utilize magnesium alloys for their strength-to-weight ratio in various components. The Ministry of Economy, Trade and Industry (METI) supports research into advanced material development for industrial applications. Aichi Prefecture, a major automotive manufacturing region, is a focal point for magnesium alloy application in new vehicle designs.
Magnesium Alloys Market Key Industry Players
Capacity expansion dominates the current landscape, driven by the escalating demand for lightweight materials in automotive manufacturing. The market exhibits a tiered structure, encompassing large-scale primary magnesium producers, specialized component fabricators, and advanced alloy developers focused on performance. Strategic partnerships are prevalent for technology sharing, while vertical integration into raw material supply secures critical inputs. Technology licensing also enables broader adoption of novel alloy formulations.
At the scale-driven end, Nanjing Yunhai Special Metals Co., Ltd. anchors a substantial portion of the world's primary magnesium supply, influencing global raw material pricing and availability. Meridian Lightweight Technologies exemplifies a specialized component manufacturer, focusing on complex, high-performance die-cast parts tailored for global automakers. Norsk Hydro ASA represents an advanced alloy developer, leveraging its extensive metallurgical expertise to formulate new alloys specifically for electric vehicle platforms and other high-performance applications requiring enhanced properties.
| Leading Market Players |
|---|
| US Magnesium LLC |
| Luxfer MEL Technologies |
| Meridian Lightweight Technologies |
| Dead Sea Magnesium Ltd. |
| Nanjing Yunhai Special Metals Co., Ltd. |
| Norsk Hydro ASA |
| Magontec Ltd. |
| Dynacast |
| Magnesium Elektron Ltd. |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and China's MEE regulations on energy-intensive smelting gate qualified magnesium alloy supply and influence premium-tier pricing access. These mandates compel producers to invest in decarbonization, adding cost to the manufacturing process for high-performance materials.
Pricing Analysis
Distributor margins influence pricing for smaller-volume buyers, while direct-to-OEM contracts often feature long-term, volume-based agreements. Pricing stratifies across premium, standard, and economy tiers based on alloy composition, certification level, and customization requirements. Downward pricing pressure stems from automotive OEMs seeking cost efficiencies in high-volume applications. Conversely, input cost volatility for primary magnesium creates upward pressure on overall alloy prices. Automotive customers exhibit high price sensitivity, whereas aerospace and medical device manufacturers prioritize performance over cost.
Supply Chain Analysis
Direct sales channels handle large-volume customer demand, particularly for automotive OEMs and Tier 1 suppliers. Primary magnesium supply concentrates heavily in China, creating a significant geopolitical supply risk for downstream users in Europe and North America. The supply chain relies on energy-intensive processes, linking magnesium prices to volatile coal and electricity costs. Key raw material dependencies include primary magnesium and alloying elements like aluminum and rare earths. Distribution to smaller fabricators and specialized manufacturers often runs through regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Magnesium Alloys Market is a stable compounder, driven by persistent automotive lightweighting mandates across global vehicle platforms.
For Market Incumbents: Anticipate continued demand for high-performance, cost-effective alloys by investing in advanced die-casting technologies. Secure long-term raw material contracts to mitigate input cost volatility, a persistent threat to margin stability. Expand capacity in Europe and North America to diversify supply and meet regional content requirements. Prioritize R&D into corrosion-resistant and creep-resistant alloys for next-generation EV powertrain components.
For New Entrants and Emerging Players: Specialized fabricators can target underpenetrated niche segments like biodegradable medical implants, offering high-margin opportunities. Focus on developing regional recycling infrastructure in Europe and North America to create a stable, low-carbon material source. A viable go-to-market angle involves technology licensing for novel alloy formulations that address specific performance gaps in electrification applications. Penetrate the market by partnering with Tier 2 automotive suppliers for specialized component fabrication.
For Investors and Strategic Acquirers: Roll-up economics work for specialized component fabricators because structural demand for lightweighting creates consistent order books. Long-term viability in this market rests on the sustained global push for vehicle electrification and fuel efficiency. Target acquisition profiles include advanced alloy developers with patented formulations or specialized die-casting firms with established OEM relationships. The signal to watch is successful commercialization of magnesium alloys for high-temperature powertrain or structural battery enclosure applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production scale to meet escalating demand from the global automotive sector. |
| Green Manufacturing Transition | Reduces environmental footprint and aligns with stringent regulations like China's MEE standards. |
| Long-term Supply Agreement | Secures stable raw material inputs, mitigating geopolitical and commodity price risks for producers. |
| Strategic Partnership | Facilitates technology sharing and market access for specialized alloy developers and component fabricators. |
| New Alloy Development | Addresses performance gaps, enabling magnesium use in high-temperature powertrain and structural EV applications. |
Research Approach
Direct dialogue with automotive OEMs, Tier 1 suppliers, alloy producers, and material scientists provided crucial primary insights. This qualitative grounding was validated by extensive secondary research, encompassing industry association reports, corporate financial filings, and government publications from the MEE, METI, and EU Green Deal. The approach combined bottom-up market sizing with top-down validation to ensure data accuracy.
A bottom-up analysis aggregated data from various segmentation dimensions, including product type, end-user industry, application, delivery mode, and regional production clusters. CAGRs were derived by assessing historical trends and projecting demand drivers, such as electric vehicle production forecasts and automotive lightweighting targets, across the analysis window. This framework integrated market volume and value forecasts.
Revisions become necessary when significant geopolitical shifts impacting raw material supply or rapid technological advancements in competing materials materialize. Forecasts reflect assumptions regarding regulatory stability and market adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Forgings Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Tungsten Titanium Carbide Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Quenched and Tempered Steel Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Global Metal Foams Market