
 Low Temperature Sealing Glass Composite Powder Market | 2026-2036
Low Temperature Sealing Glass Composite Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Low Temperature Sealing Glass Composite Powder Market Insights
Asset-light leasing models for specialty glass processing equipment is tilting competitive dynamics toward mid-tier entrants who previously faced capital barriers. SCHOTT AG leverages captive melt-tower capacity across Central European sites to sustain cost discipline in thermal conductive grades. Ferro Corporation anchors North American supply through vertically integrated frit production. Nippon Electric Glass Co., Ltd. dominates Asia-Pacific demand with dedicated low-temperature sealant lines for display manufacturers.
Low temperature sealing glass composite powder denotes engineered glass-ceramic formulations that sinter below 450°C, typically incorporating lead-free bismuth-zinc-borate or vanadate systems to bond dissimilar substrates without thermal damage. These materials seal organic light-emitting diode displays, solid-state batteries, and hermetic MEMS packages where conventional borosilicate glasses would degrade adjacent polymers. Thermal conductive formulations command premium positioning due to their role in dissipating heat from power-dense electronics modules, while flexible variants represent the fastest-growing category as foldable display architectures proliferate. Insulating grades retain stable margin pools in aerospace and defense applications where dielectric reliability overrides cost sensitivity.
EPA toxics release thresholds and REACH substance restrictions are jointly phasing out residual lead content, forcing reformulation investments across the supplier base. RoHS compliance documentation now functions as a de facto market access gate for electronics supply chains. ISO 9001 and IATF 16949 certifications are becoming baseline requirements for automotive sealing contracts. Stakeholders must track regulatory harmonization between Asian export standards and European chemical safety frameworks to anticipate qualification timelines for next-generation composite chemistries.
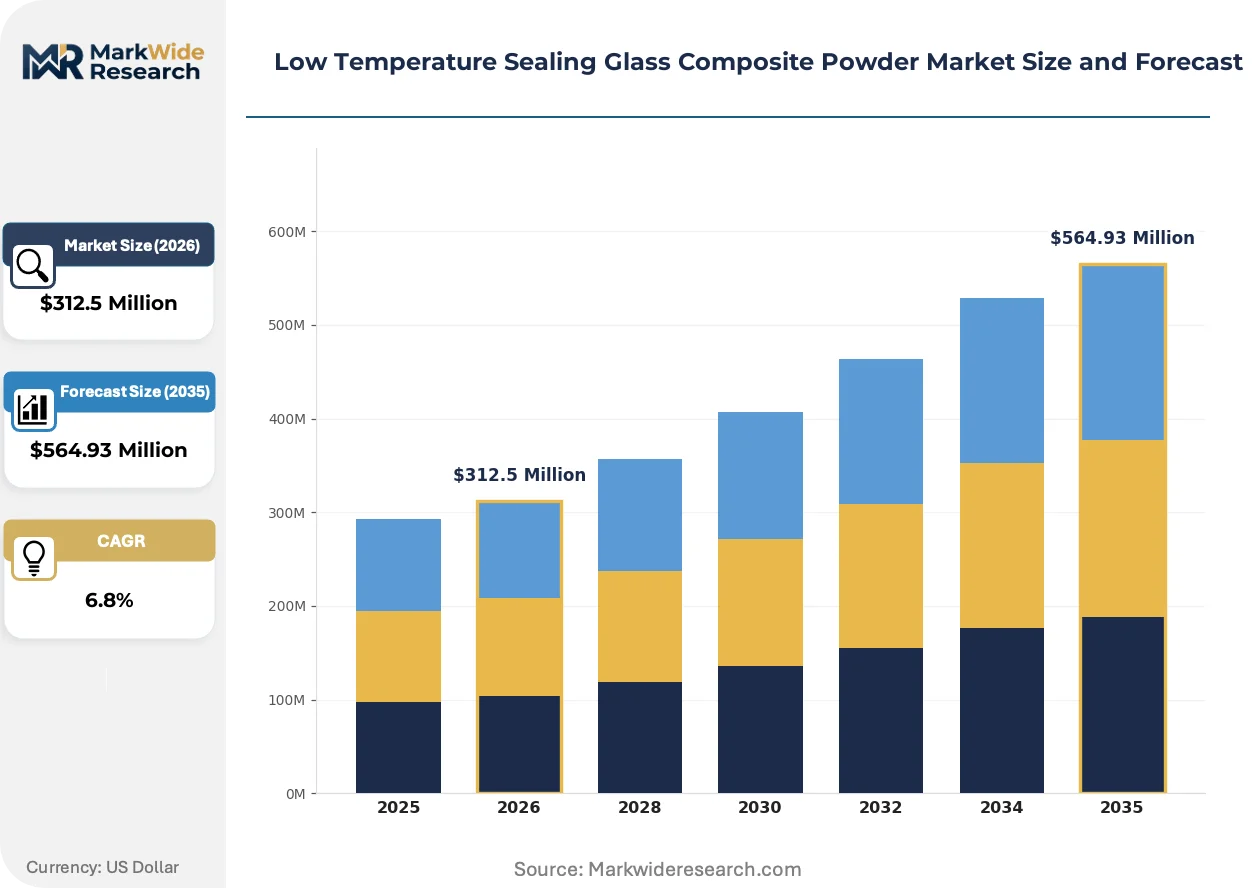
Market Dynamics
Lead-free reformulation mandates are compressing legacy supplier margins while opening entry points for bismuth-zinc-borate specialists with pre-qualified RoHS documentation. The transition from lead-bearing vanadate systems to compliant alternatives is redistributing technical advantage across the supply base.
Growth Catalysts
- Solid-state battery commercialization:Hermetic sealing requirements for sulfide electrolyte cells are pulling low-temperature formulations into gigafactory qualification pipelines. Thermal budgets below 400°C prevent electrolyte degradation during module assembly.
- REACH Article 67 restrictions:European substance thresholds are accelerating substitution away from residual lead traces in automotive sensor packages. Compliance documentation now gates supply contracts with German tier-1 automotive suppliers.
- Foldable display architectures:Korean and Chinese panel manufacturers are specifying flexible sealing grades for hinge-zone protection in rollable OLED devices. Dynamic bending cycles demand glass-ceramic composites with sub-200°C processing windows.
Market Restraints
- Bismuth oxide price volatility:Concentrated mining output from Peruvian and Chinese sources creates input cost instability for borate-formulation producers. Smelter capacity constraints transmit directly to frit pricing.
- Melt-tower asset concentration:Captive glass melting infrastructure clusters in Central Europe and East Asia, limiting regional supply responsiveness. New entrants face 24-36 month lead times for qualified furnace commissioning.
- Thermal conductivity ceiling:Lead-free alternatives top out at 3.5 W/m·K versus 6+ W/m·K for legacy vanadate-lead compositions. Power-dense RF modules in aerospace applications retain restricted material exemptions.
Strategic Opportunities
- Indian electronics manufacturing corridors:PLI scheme incentives for semiconductor packaging are creating first-mover advantage for sealant suppliers establishing local blending operations. Tamil Nadu and Gujarat fab clusters lack qualified regional glass-ceramic sources.
- Copper-to-glass direct bonding:Emerging sintering protocols enable hermetic seals without intermediate metallization layers. Process step elimination targets cost reduction in MEMS microphone packages.
- Automotive lidar hermeticity standards:ISO 20653 ingress protection mandates for autonomous sensor modules are specifying vacuum-tight glass-ceramic feedthroughs. Qualification timelines favor suppliers with IATF 16949 certification.
Industry Challenges
- Glass-ceramic process engineering talent:Nucleation kinetics expertise for controlled crystallization resides with a narrow cohort of specialists approaching retirement. University programs in inorganic materials synthesis are producing insufficient replacement pipeline.
- Multi-regulatory qualification parallelism:Simultaneous EPA, REACH, and China GB standard compliance requires divergent testing protocols. Documentation burden extends product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Temperature Sealing Glass Composite Powder Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Conductive, UV Resistant, Insulating, Flexible Application: Aerospace, Electronics, Automotive, Ceramics End User: Manufacturers, Research Institutions, Contractors, Laboratories Form: Powder, Paste, Granule, Coating |
| Companies Covered | Ferro Corporation, SCHOTT AG, Corning Incorporated, Nippon Electric Glass Co., Ltd., Shin-Etsu Chemical Co., Ltd., Henkel AG & Co. KGaA, 3M Company, AGC Corporation, NAMICS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Temperature Sealing Glass Composite Powder Market Trends and Innovations
Formulation chemistry is pivoting toward binary and ternary oxide systems that sacrifice thermal performance for regulatory compliance. Process integration demands are compressing sintering windows and driving co-development partnerships between powder suppliers and equipment manufacturers.
Laser-assisted sintering is collapsing the thermal budget for hermetic sealing from hours to seconds. Display manufacturers in South Korea are piloting selective heating systems that localize energy input to seal zones while preserving polymer substrates. This process compression is eliminating batch furnace bottlenecks and enabling inline manufacturing configurations for flexible panel production.
REACH authorization procedures are forcing inventory segregation between lead-containing legacy stocks and reformulated alternatives. European compounders are maintaining dual formulation streams during customer transition periods, inflating working capital requirements. Automotive electronics suppliers are responding by consolidating purchase orders with pre-qualified RoHS-compliant sources to simplify audit trails.
Specification-driven procurement is displacing spot-market purchasing for thermal conductive grades. Japanese automotive electronics buyers are locking 36-month supply agreements with technical acceptance criteria rather than commodity pricing. This contract structure shift is most visible in hybrid vehicle power module applications where dielectric reliability failures carry warranty exposure.
Low Temperature Sealing Glass Composite Powder Market Segmentation
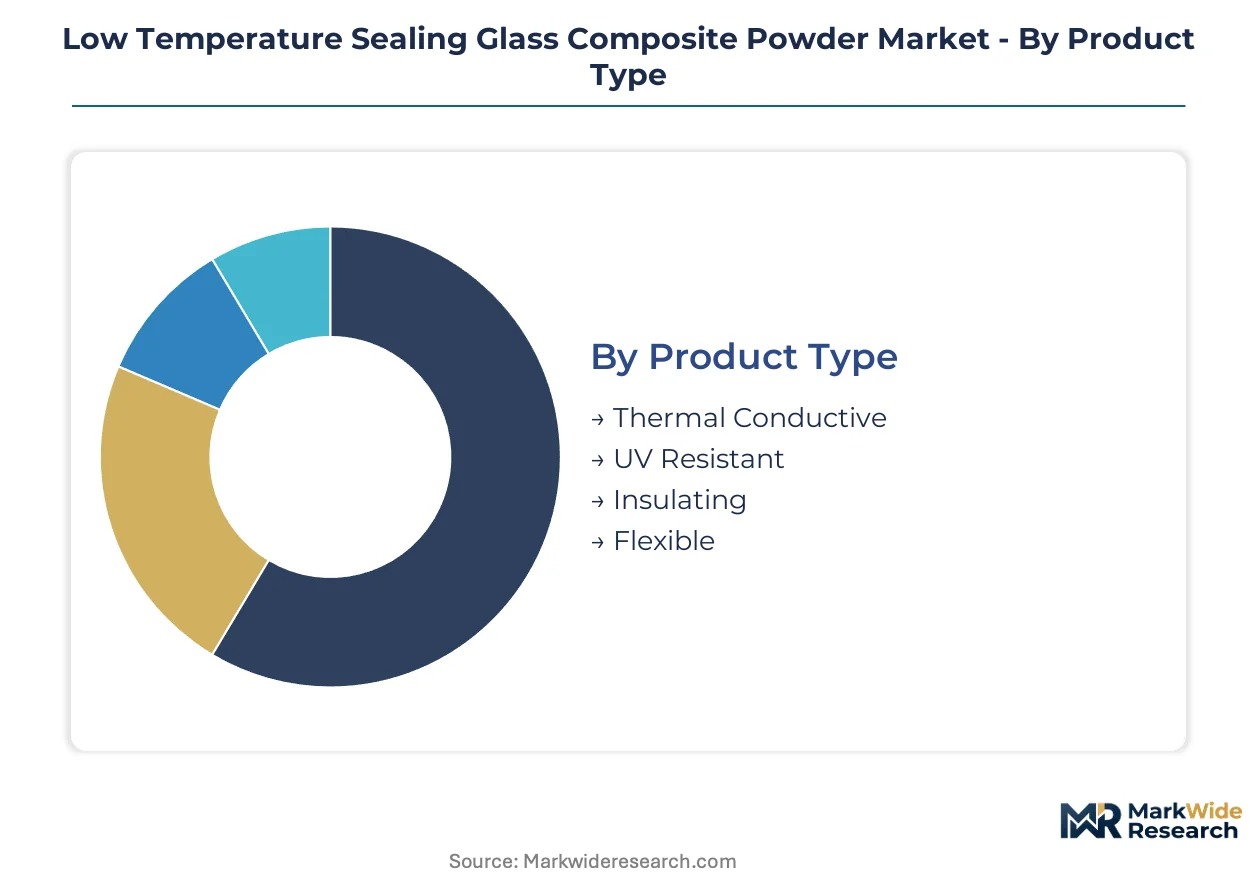
Segmentation in low-temperature sealing glass composite powders reveals distinct technical requirements across product architectures. Cycle times vary dramatically: display sealing formulations refresh quarterly with panel generation changes, while aerospace qualifications extend across decade-long certification windows. Understanding these velocity differentials guides inventory positioning and R&D resource allocation.
Product Type:
Thermal conductive grades turn inventory fastest due to power module procurement cycles, while flexible variants face extended qualification timelines for foldable display integration. UV resistant formulations occupy intermediate velocity tiers tied to outdoor electronics replacement schedules.
- Thermal Conductive:Bismuth-zinc-borate matrices loaded with alumina or boron nitride fillers achieve 2.5-3.5 W/m·K thermal conductivity. Korean semiconductor packaging corridors in Pyeongtaek and Yongin are concentrating procurement for power-dense RF modules, though lead-free alternatives remain capped below legacy vanadate-lead performance thresholds.
- Flexible:Ultra-low modulus glass-ceramic composites with sub-200°C processing windows accommodate dynamic bending in rollable OLED architectures. Chinese and Korean panel manufacturers are driving specification evolution for hinge-zone protection, creating qualification bottlenecks as nucleation kinetics expertise concentrates with retiring specialists.
- UV Resistant:Cerium-doped formulations block degradation in outdoor display and solar concentrator applications.
- Insulating:High dielectric reliability grades serve aerospace and defense hermeticity requirements where cost sensitivity yields to performance assurance.
Thermal conductive dominates installed base. Flexible is where expansion concentrates.
Application:
Cost tier stratification separates commodity electronics sealing from premium aerospace qualification pathways. Electronics applications optimize for throughput and reformulation agility, while aerospace and automotive segments absorb extended testing burdens for traceability compliance.
- Electronics:Display packaging and MEMS hermeticity drive volume demand with compressed sintering windows. South Korean OLED fabs and Chinese semiconductor packaging zones specify low-temperature sealants to protect adjacent polymers, with laser-assisted sintering collapsing thermal budgets from hours to seconds.
- Aerospace:RF module and sensor feedthrough applications retain restricted material exemptions for lead-bearing vanadate systems where thermal conductivity ceilings matter. German and French aerospace suppliers maintain decade-long qualification archives under EASA traceability mandates.
- Automotive:Lidar hermeticity standards under ISO 20653 are specifying vacuum-tight glass-ceramic feedthroughs for autonomous sensor modules.
- Ceramics:Technical ceramic-to-metal sealing applications in industrial equipment represent stable replacement demand.
Electronics commands volume leadership. Automotive lidar applications are climbing the fastest as ISO 20653 compliance deadlines approach.
End User:
Customer type determines contract structure and technical engagement depth. Manufacturers drive specification standardization, while research institutions and laboratories generate reformulation pull-through for next-generation chemistries.
- Manufacturers:Display, semiconductor, and automotive electronics producers lock multi-year supply agreements with technical acceptance criteria rather than commodity pricing. Japanese automotive electronics buyers are consolidating purchase orders with pre-qualified RoHS-compliant sources to simplify audit trails under REACH Article 67.
- Research Institutions:Solid-state battery developers and advanced packaging consortia pilot novel bismuth-zinc-borate formulations for sulfide electrolyte cell sealing. Gigafactory qualification pipelines in Germany and the United States are pulling low-temperature formulations below 400°C thermal budgets.
- Contractors:Specialty electronics assemblers and aerospace subsystem integrators procure to customer-mandated specifications.
- Laboratories:Materials characterization and failure analysis facilities maintain small-lot inventories for comparative testing.
Manufacturers anchor revenue concentration. Research institutions are where technology transition accelerates.
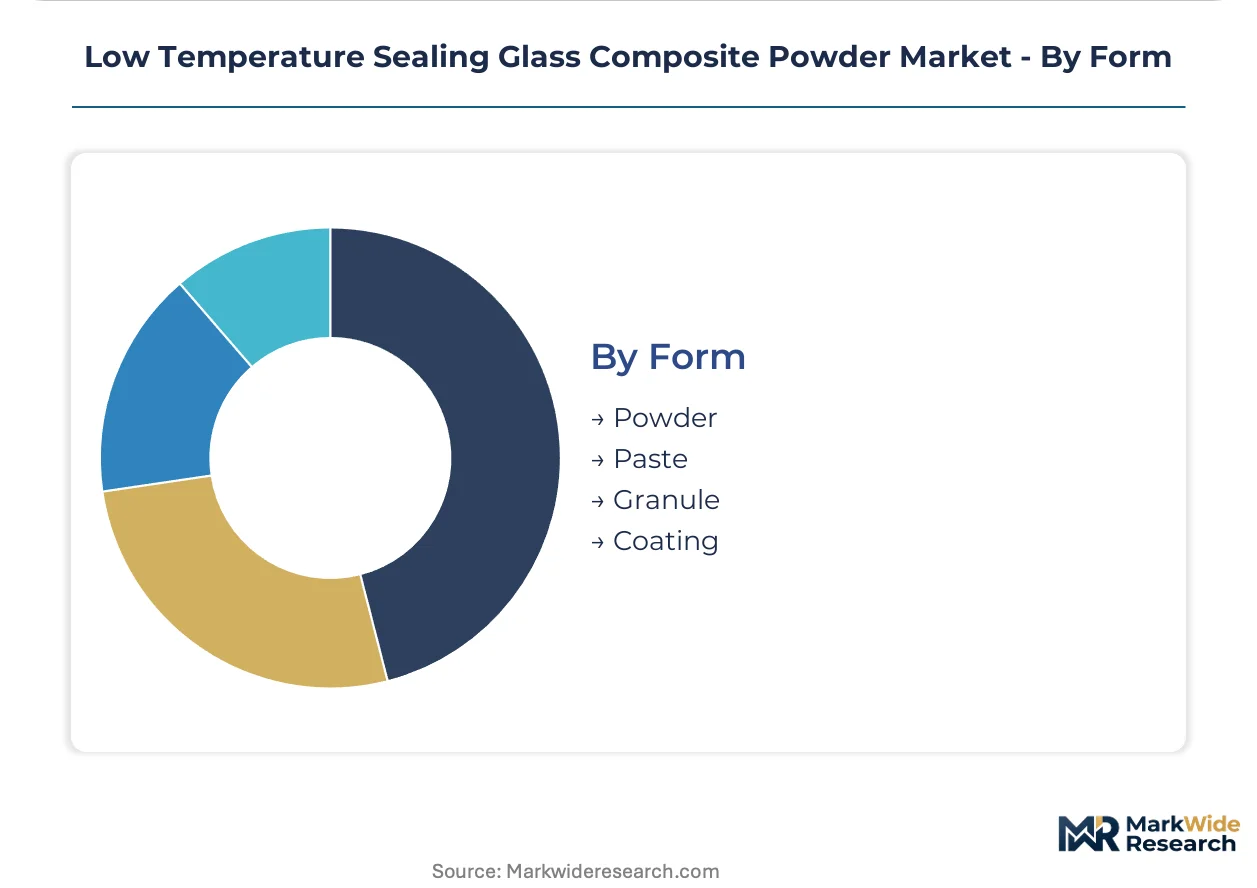
Form:
Supply concentration in melt-tower infrastructure shapes regional availability patterns for powder and granule forms, while paste and coating derivatives concentrate blending operations near end-use clusters.
- Powder:Spray-dried frit with controlled particle size distribution serves high-volume electronics packaging. Central European captive melt capacity at SCHOTT AG sites and East Asian furnace clusters limit regional supply responsiveness for qualified material.
- Paste:Pre-mixed formulations with organic vehicles enable precision dispensing in MEMS microphone and display edge sealing. Korean and Chinese panel manufacturers are driving inline manufacturing configurations that favor paste rheology optimization.
- Granule:Agglomerated forms for bulk melting and remelt applications in specialty glass fabrication.
- Coating:Suspension-based systems for selective area deposition in complex substrate geometries.
Powder commands installed base scale. Paste is where process integration investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances concentrate supply leverage in melt-tower corridors across Central Europe and East Asia. Import-dependent electronics packaging hubs face qualification bottlenecks as regional furnace capacity constraints extend lead times for qualified material.
United States
Automotive lidar hermeticity standards under ISO 20653 are pulling vacuum-tight glass-ceramic feedthroughs into autonomous sensor supply chains. EPA toxics release thresholds are phasing residual lead content from legacy vanadate formulations. Michigan and Ohio automotive electronics corridors are consolidating purchase orders with pre-qualified RoHS-compliant sources to simplify audit documentation.
Germany
Solid-state battery gigafactory pipelines in Saxony and Baden-Württemberg require sub-400°C thermal budgets for sulfide electrolyte cell sealing. ECHA REACH Article 67 restrictions are accelerating substitution away from lead traces in automotive sensor packages. Bavarian aerospace suppliers maintain decade-long qualification archives under EASA traceability mandates for RF module applications.
South Korea
Foldable OLED panel manufacturers in Pyeongtaek and Yongin are specifying flexible sealing grades with sub-200°C processing windows for hinge-zone protection. MFDS chemical safety frameworks are harmonizing with European export standards for display material qualification. Seoul Capital Area semiconductor packaging zones are piloting laser-assisted sintering systems that collapse thermal budgets from hours to seconds.
China
GB standards compliance and dual carbon goals are tightening compositional thresholds for lead-free bismuth-zinc-borate formulations. Yangtze River Delta display fabs and Pearl River Delta semiconductor packaging clusters are driving inline manufacturing configurations. Zhejiang and Jiangsu province glass-ceramic compounders face inventory segregation requirements between legacy lead-containing stocks and reformulated alternatives.
Japan
Hybrid vehicle power module applications are locking 36-month supply agreements with technical acceptance criteria rather than commodity pricing. METI industrial standards are converging with RoHS documentation requirements for automotive electronics exports. Kansai region automotive electronics buyers are consolidating procurement with pre-qualified sources to manage REACH compliance audit trails.
Low Temperature Sealing Glass Composite Powder Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in frit production and formulation chemistry. Captive melt-tower infrastructure clusters in Central Europe and East Asia, creating tiered supply responsiveness. Three archetypes dominate: vertically integrated glass manufacturers with captive furnace capacity, specialty chemical compounders with nucleation kinetics expertise, and materials distributors with regional blending operations. Capacity expansion and strategic partnerships represent the dominant competitive vectors as qualification timelines extend.
Among German fabricators, SCHOTT AG occupies a position within the captive melt-tower tier, exemplifying cost discipline through centralized European furnace networks. Ferro Corporation represents the North American vertically integrated archetype, anchoring regional frit production capacity. Nippon Electric Glass Co., Ltd. sits within the Asia-Pacific specialist tier, reflecting dedicated production lines for display manufacturer specifications.
| Leading Market Players |
|---|
| Ferro Corporation |
| SCHOTT AG |
| Corning Incorporated |
| Nippon Electric Glass Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Henkel AG & Co. KGaA |
| 3M Company |
| AGC Corporation |
| NAMICS Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive melt-tower undercapacity in Central Europe and East Asia is compressing supplier pricing power while extending lead times for qualified thermal conductive grades. Furnace utilization above 85 percent at SCHOTT AG sites and Korean glass-ceramic clusters enables selective order acceptance and premium positioning for RoHS-compliant formulations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with technical acceptance criteria rather than commodity spot pricing. Price differentiation rests on IATF 16949 certification tier and volume scale commitments from automotive electronics suppliers. Cost compression in flexible display grades is intensifying because bismuth oxide smelter constraints transmit directly to frit input costs. MEMS packaging contractors exhibit highest price sensitivity due to thin margins in microphone module assembly, while aerospace RF module buyers absorb premiums for dielectric reliability assurance.
Supply Chain Analysis
Export-control restrictions on advanced glass-melting furnace technology limit capacity expansion outside established corridors in Germany, South Korea, and Japan. Raw material dependencies center on Peruvian and Chinese bismuth oxide concentrates, boron carbide from Turkey, and high-purity zinc from Australian smelters. Single-source vulnerability concentrates in nucleation kinetics expertise as retiring specialists constrain qualified technical talent pipelines. Distribution runs through regional compounders with local blending operations serving display manufacturer clusters in the Yangtze River Delta and Seoul Capital Area.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through solid-state battery commercialization as gigafactory qualification pipelines pull low-temperature sealants into volume procurement cycles.
For Market Incumbents: Entrench backward integration into captive bismuth-zinc-borate frit production to defend margin pools against emerging compounders with pre-qualified RoHS documentation. Add qualified furnace capacity in Tamil Nadu or Gujarat to preempt Indian PLI scheme demand before regional blending operations achieve technical parity. Certification investment in IATF 16949 and ISO 20653 testing archives creates switching costs for automotive lidar feedthrough contracts. For New Entrants and Emerging Players: Establish a beachhead in flexible sealing grades for foldable OLED hinge-zone applications where nucleation kinetics expertise scarcity extends qualification timelines and protects early movers. Target paste form factors for Korean and Chinese panel manufacturers piloting laser-assisted sintering inline configurations. A co-development partnership with display equipment OEMs on rheology optimization offers faster technical validation than direct powder supply qualification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermal conductive grades as alumina and boron nitride filler loading requirements expand materials working capital needs. Five-to-ten year viability favors acquiring specialty chemical compounders with existing nucleation kinetics specialists and qualified customer archives rather than greenfield furnace investments. The signal to watch is bismuth oxide price volatility frequency as a proxy for input cost instability and margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Frit Production | Captive bismuth-zinc-borate melting secures cost discipline against smelter price volatility. |
| Laser-Assisted Sintering Partnership | Co-development with Korean equipment OEMs collapses thermal budgets for flexible display sealing. |
| IATF 16949 Certification Investment | Automotive lidar hermeticity contracts under ISO 20653 require qualified quality system gates. |
| Indian Regional Blending Expansion | Tamil Nadu fab clusters lack qualified local glass-ceramic sources under PLI incentives. |
| Dual Formulation Inventory Segregation | REACH Article 67 compliance forces parallel legacy and lead-free stock maintenance in Europe. |
Research Methodology
Initial hypotheses were tested against primary input from glass-ceramic R&D directors, automotive electronics procurement leads, display panel process engineers, and specialty chemical distribution channel partners and refined through secondary validation. Trade data from Korean and Chinese customs authorities, ECHA REACH registration databases, SEC filings from vertically integrated glass manufacturers, and semiconductor packaging equipment capex disclosures provided demand-side triangulation. Bottom-up volume estimates from application-level consumption models were reconciled with top-down value projections across the analysis window.
Demand-supply balance dynamics anchored the analytical framework across product type, application, end user, and form factor segmentation dimensions. CAGRs were derived from fitted growth curves calibrated to qualification timeline data and regulatory phase-out schedules. Industry-specific forecast inputs included solid-state battery gigafactory commissioning announcements and foldable OLED panel generation roadmaps from Korean and Chinese manufacturers.
Sensitivities concentrate around bismuth oxide concentrate supply disruptions, REACH authorization timeline accelerations, and laser-assisted sintering adoption rates in display manufacturing. Forecasts reflect documented assumptions on furnace capacity expansion schedules and regulatory harmonization progress between Asian export standards and European chemical safety frameworks. Material shifts in EPA toxics release thresholds or MFDS chemical safety convergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Composite Metal Finishing Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Pcb Laminate Materials Market
Composite Materials
Laminar Composites Market
Composite Materials
Transportation Composites Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Global Composite Resin Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
FRP Grating Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Europe Composite Process Material Kits Market