
 Chromium Carbide Market | 2026-2036
Chromium Carbide Market Size, Share, and Industry Trends Forecast 2026-2036
Chromium Carbide Market Analysis
Aerospace and oil and gas end-use demand is rebalancing as energy infrastructure investment outpaces commercial aviation recovery in several producing basins. H.C. Starck leverages its tungsten and carbide heritage to sustain premium powder supply contracts across European thermal spray shops. Kennametal anchors North American hardfacing demand through captive production of engineered carbide inserts for directional drilling. Oerlikon Metco competes on plasma spray system integration, bundying equipment with proprietary chromium carbide feedstock to lock in recurring powder sales.
Chromium carbide is a ceramic-metal compound, typically Cr₃C₂, produced by carburization of chromium oxide or direct synthesis from elemental powders at temperatures exceeding 1500°C, valued for extreme hardness and oxidation resistance up to 900°C in corrosive wear environments. Chromium carbide coating dominates value capture in the product type structure because thermal spray deposition commands higher service pricing than raw powder trading. Mining application growth is accelerating fastest among verticals as autonomous haul truck fleets multiply the severity of abrasive ground engagement on undercarriage and bucket components.
EPA NESHAP standards for hazardous air pollutants from metal finishing operations constrain permissible hexavalent chromium exposure in U.S. coating facilities, pushing demand toward closed-loop thermal spray booths and certified low-leachability formulations. REACH registration requirements under ECHA govern chromium compound import volumes into European Union member states, creating compliance cost barriers for uncertified Asian suppliers. Stakeholders must monitor how China's GB standards for occupational dust exposure and the dual carbon policy reshape domestic production economics versus import reliance for high-purity carbide feedstock.
Market Dynamics
State-backed infrastructure procurement in China and tightening hexavalent chromium exposure limits in Western coating facilities are compressing supply chains toward certified low-leachability formulations and captive thermal spray integration.
Growth Catalysts
- EPA NESHAP enforcement:U.S. metal finishing facilities face mandatory hexavalent chromium exposure reductions, accelerating investment in closed-loop thermal spray booths and certified chromium carbide feedstock formulations.
- Autonomous mining fleets:Self-driving haul trucks multiply abrasive ground engagement severity on undercarriage and bucket components, expanding procurement of chromium carbide hardfacing for wear-critical ground-engaging tools.
- REACH registration concentration:ECHA compliance requirements for chromium compound imports into EU member states favor established European powder suppliers with full substance dossiers.
Market Restraints
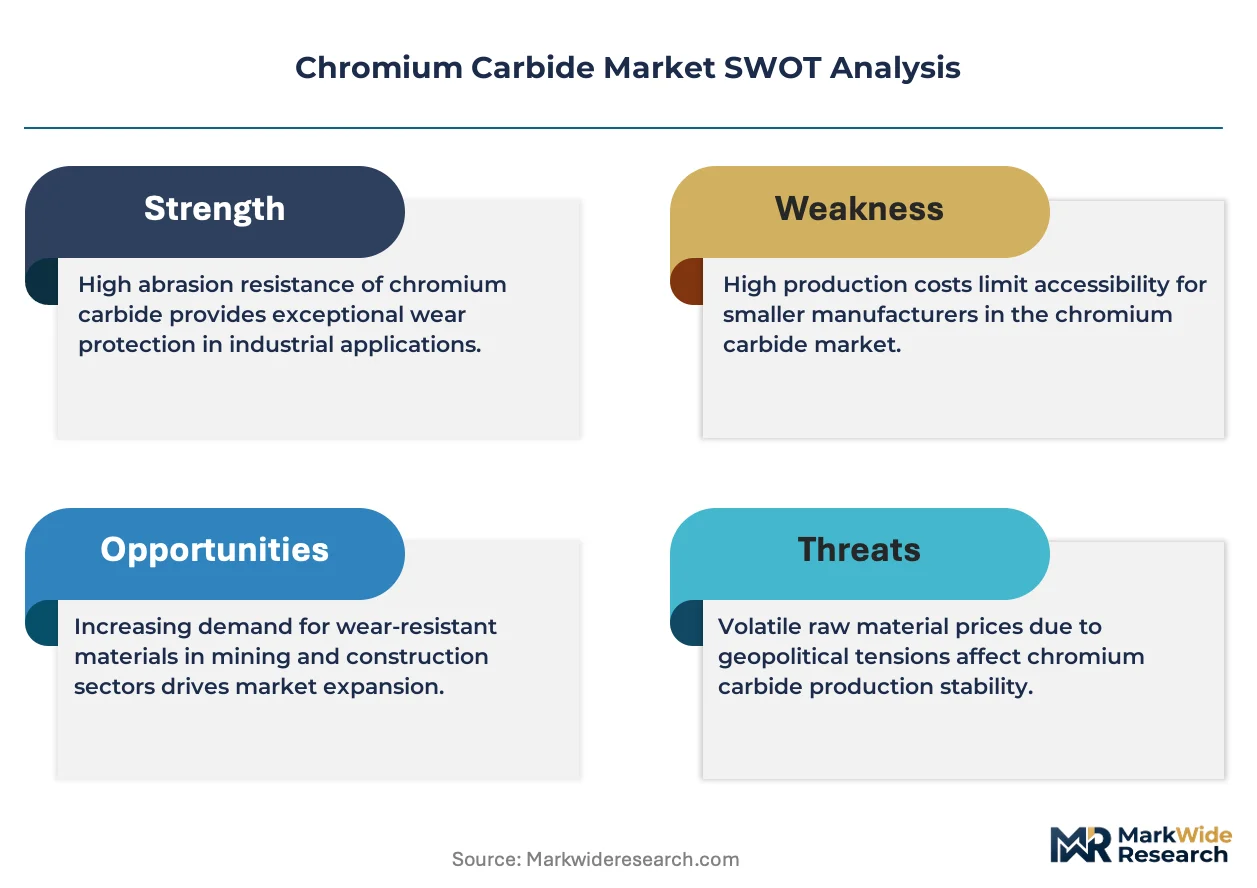
- Tungsten price volatility:Chromium carbide competes with tungsten carbide in overlapping wear applications; tungsten ore supply disruptions from Central African concentrate sources transmit cost instability through substitute material pricing.
- High-purity feedstock concentration:Production of thermal-spray-grade Cr₃C₂ powder concentrates among metallurgical-grade chromium producers with carburization furnace infrastructure, limiting second-tier supplier entry.
- Substitution by boride ceramics:Chromium boride and titanium diboride coatings gain traction in ultra-high-temperature oxidation environments above 900°C, capping chromium carbide's addressable thermal envelope.
Strategic Opportunities
- India's PLI-linked petrochemical buildout:Production-linked incentive schemes for specialty chemicals and refinery expansion create first-mover positioning for hardfacing contractors supplying severe-service valve manufacturers.
- HVOF-to-cold spray convergence:Emerging cold spray deposition technology enables chromium carbide application onto temperature-sensitive substrates previously excluded from thermal spray coverage, opening aerospace MRO opportunities.
- China's dual carbon policy:Domestic emissions intensity mandates for ferrochrome smelters accelerate consolidation toward integrated carbide producers with captive renewable power, reshaping import-export dynamics for high-purity feedstock.
Industry Challenges
- Certification timeline compression:REACH registration dossiers for new chromium carbide feedstock grades require 18-24 month ECHA review cycles, delaying market entry for reformulated low-leachability powders.
- Thermal spray technician scarcity:Qualified HVOF and plasma spray operators with chromium carbide process certification command wage premiums exceeding 40% above general welding trades, constraining coating shop capacity expansion.
- Legacy ERP integration friction:Hardfacing job shops migrating to automated powder feeding and closed-loop environmental monitoring face data architecture incompatibilities with decades-old production scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromium Carbide Market |
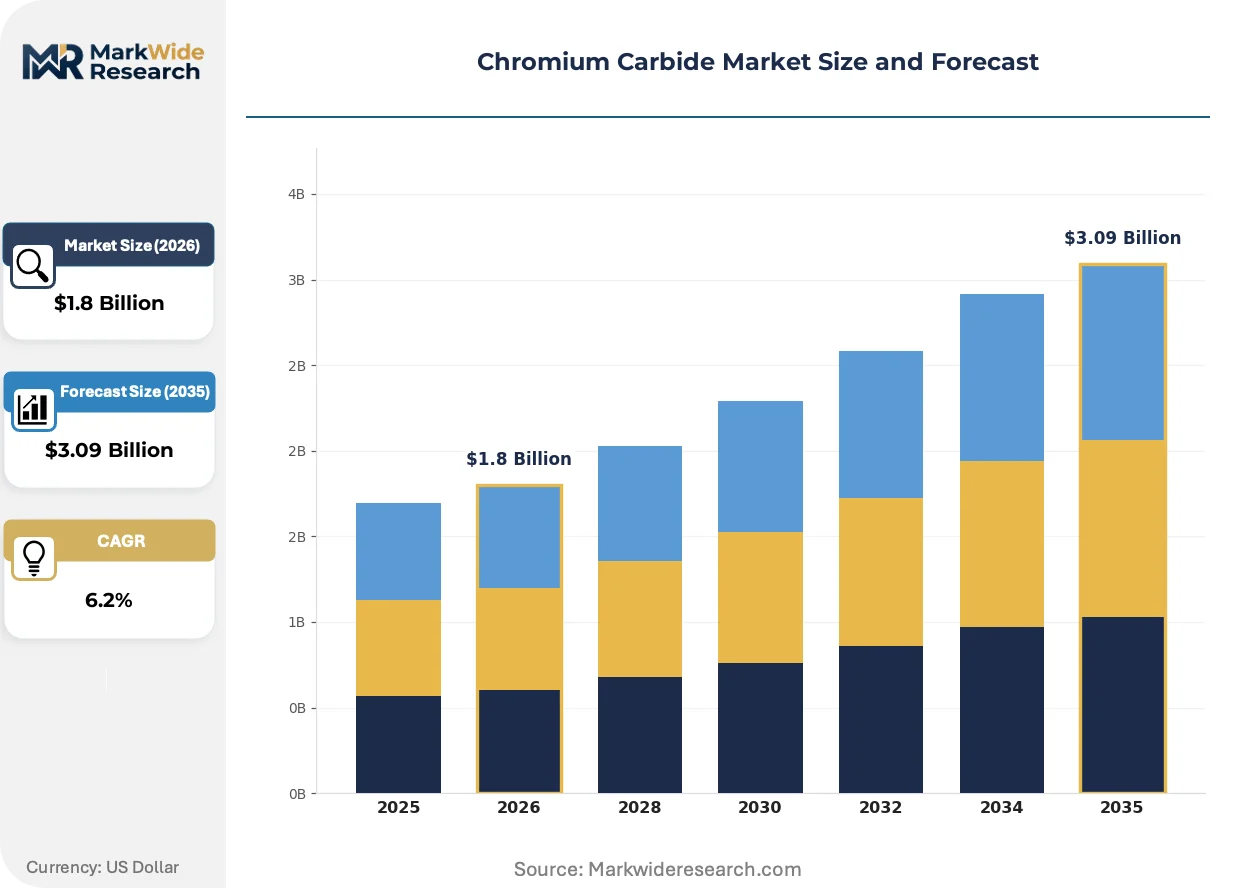
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromium Carbide Powder, Chromium Carbide Coating, Chromium Carbide Composite, Chromium Carbide Hardfacing Application: Aerospace, Automotive, Oil & Gas, Mining End User: Manufacturers, Construction, Aerospace Engineers, Energy Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | H.C. Starck, Oerlikon Metco, Kennametal, Saint-Gobain, Praxair Surface Tech, Sandvik, Bodycote, Fiven, Materion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromium Carbide Market Emerging Trajectories
Plasma spray system architecture, regulatory emissions monitoring, and procurement contracting models are undergoing simultaneous restructuring as coating shops absorb environmental compliance costs and end-users consolidate supplier bases.
Closed-loop thermal spray booth design is modularizing around integrated powder recovery, filtration, and emissions monitoring subsystems. North American hardfacing contractors facing EPA NESHAP inspections are adopting these pre-engineered environmental modules to compress permitting timelines and reduce capital deployment risk. The technology is modularizing what were previously custom-built coating facilities into repeatable, financeable asset configurations.
REACH authorization requirements under ECHA are tightening chromium compound supply chains across EU member states. Downstream coating facilities now demand full substance dossier documentation from feedstock suppliers, shifting procurement preference toward vertically integrated European metallurgical producers. Thermal spray shops in Germany and France are most affected, responding by consolidating supplier panels and demanding multi-year powder supply contracts with embedded compliance certification.
Performance-based coating service contracts are displacing traditional per-kilogram powder pricing in oil and gas valve hardfacing. Operators in the Permian Basin and North Sea now specify minimum service life guarantees for chromium carbide overlays, transferring wear risk from end-user maintenance budgets to applicator balance sheets. This shift is most visible among directional drilling tool contractors, where downhole failure penalties now exceed raw material costs by factors of ten.
Chromium Carbide Market Segmentation
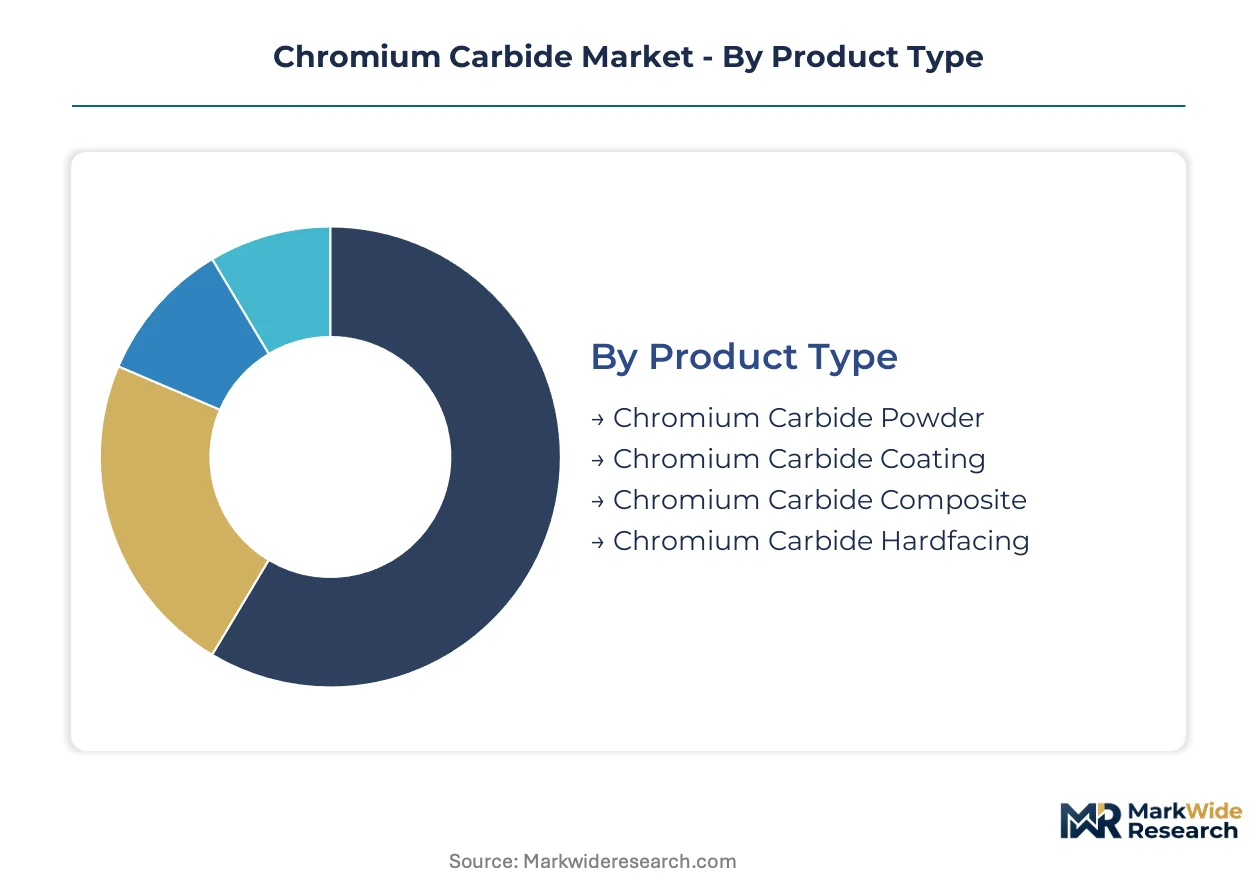
Chromium carbide procurement patterns diverge sharply between commodity powder trading and engineered coating services, with capital requirements and regulatory exposure determining supplier economics across each segment. Understanding how product specifications, application severity, and channel structures intersect reveals where margin pools concentrate and where new entrants face barriers.
Product Type:
Capital intensity peaks with in-house thermal spray integration, while powder trading requires minimal fixed asset deployment but sacrifices pricing power to metallurgical-grade producers.
- Chromium Carbide Coating:Thermal spray deposition of Cr₃C₂-NiCr formulations onto valve seats, pump impellers, and drill collars commands premium service pricing through applicator certification requirements. Demand concentrates in Permian Basin directional drilling contractors facing downhole failure penalties that dwarf raw material costs.
- Chromium Carbide Powder:Spray-dried agglomerates and sintered spherical feedstocks for HVOF and plasma spray systems constitute the foundational input, with thermal-spray-grade specifications requiring carburization furnace infrastructure exceeding 1500°C. Chinese state-backed petrochemical buildouts absorb rising import volumes of high-purity Cr₃C₂.
- Chromium Carbide Composite:Cermet blends with nickel-chromium matrices balance hardness with toughness for severe-service applications.
- Chromium Carbide Hardfacing:Welding wire and rod products for manual and automated overlay deposition on ground-engaging tools.
Chromium carbide coating absorbs the bulk of installed capacity; chromium carbide powder is expanding most quickly as captive supply chains integrate backward.
Application:
Operating environment severity determines specification grade, with downhole pressure and abrasive ore contact driving the tightest certification requirements.
- Oil & Gas:Severe-service valves, downhole drilling tools, and pipeline components require HVOF-applied Cr₃C₂-NiCr overlays resistant to corrosive wear and high-pressure erosion. North Sea and Permian Basin operators now specify minimum service life guarantees, transferring wear risk to applicator balance sheets.
- Mining:Autonomous haul truck fleets multiply abrasive ground engagement severity on undercarriage and bucket components, accelerating procurement of hardfaced ground-engaging tools. Australian iron ore and Chilean copper operations lead fleet automation adoption.
- Aerospace:Turbine blade erosion shields and landing gear components utilize plasma-sprayed chromium carbide for oxidation resistance to 900°C.
- Automotive:Piston ring coatings and valve train components employ thinner chromium carbide layers for friction reduction.
Oil and gas commands the dominant share of specification-grade procurement; mining is climbing the fastest as autonomous fleet deployment accelerates wear part replacement cycles.
End User:
Technical specification authority varies sharply between engineering-driven procurement and maintenance-driven spot purchasing.
- Energy Companies:Integrated oil majors and national oil companies wield dominant specification authority for severe-service valve hardfacing, embedding multi-year coating service contracts with embedded compliance certification. Saudi Aramco and Petrobras anchor long-term procurement frameworks.
- Aerospace Engineers:OEM airframers and tier-one suppliers dictate thermal spray process parameters through proprietary material specifications, limiting applicator qualification to pre-approved coating shops.
- Manufacturers:Industrial pump and valve producers source chromium carbide overlays through subcontractor networks.
- Construction:Civil infrastructure contractors represent fragmented, price-sensitive demand for wear plate and hardfacing rod.
Energy companies concentrate the highest-value procurement; aerospace engineers maintain the most restrictive qualification barriers.
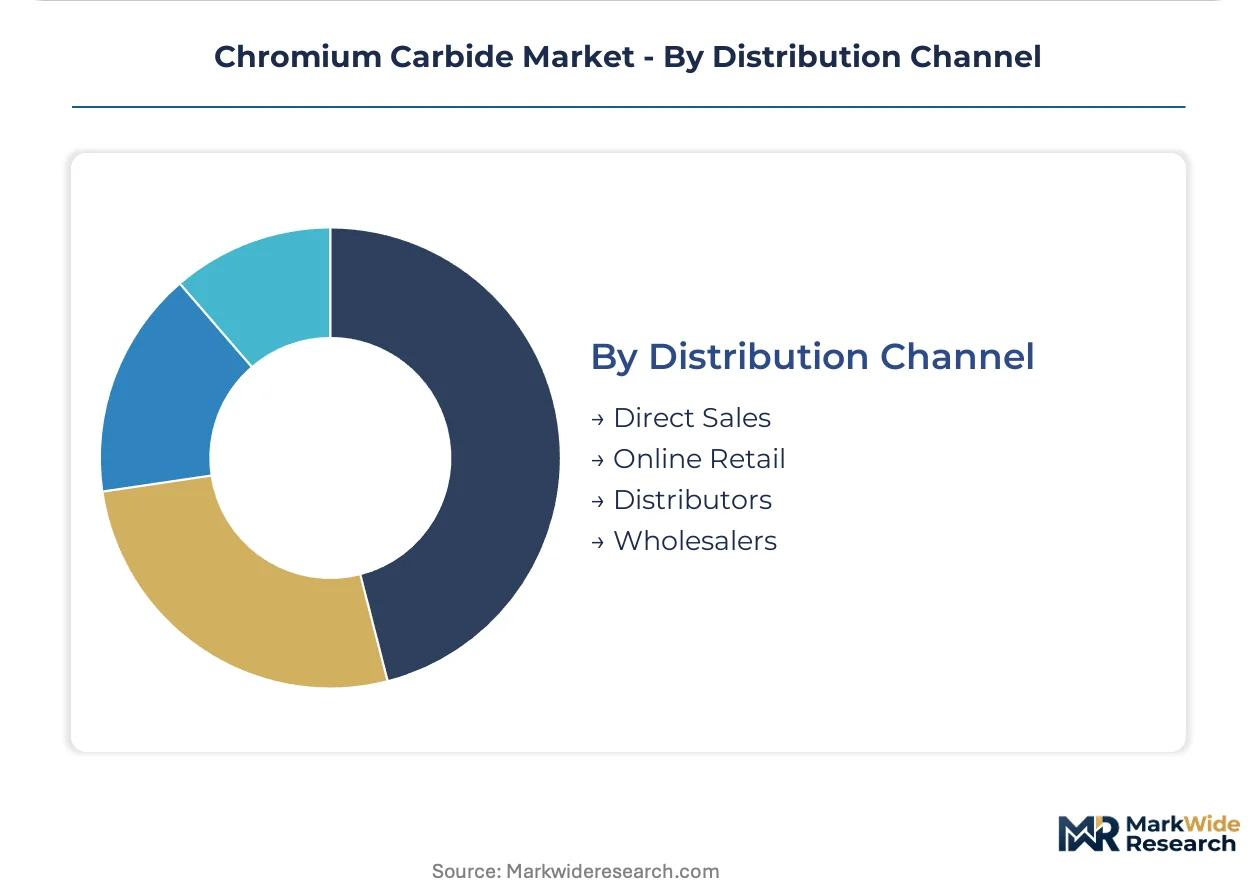
Distribution Channel:
Channel selection reflects order size, technical support requirements, and regulatory documentation burdens.
- Direct Sales:Thermal spray feedstock producers sell directly to qualified coating shops and OEM captive facilities, bundling powder supply with process parameter support and REACH dossier documentation. H.C. Starck and Oerlikon Metco anchor European direct sales networks.
- Distributors:Regional industrial supply houses stock standard-grade chromium carbide powder and welding consumables for job shop spot purchasing.
- Online Retail:Small-laboratory and R&D quantities trade through specialized chemical supply platforms.
- Wholesalers:Bulk powder aggregators serve secondary markets with limited specification requirements.
Direct sales capture the majority of specification-grade volume; distributors are gaining share fastest in mid-tier hardfacing consumables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate carbide production infrastructure, drawing state-backed petrochemical investment and captive thermal spray integration. Tax incentives for high-purity metallurgical processing anchor supply chain gravity in Jiangsu and Zhejiang provinces.
United States
Permian Basin directional drilling contractors specify chromium carbide hardfacing for downhole tools under severe-service procurement frameworks. EPA NESHAP enforcement mandates hexavalent chromium exposure reductions in Texas and Oklahoma coating facilities. Houston anchors North American thermal spray capacity, with closed-loop booth investments accelerating ahead of regulatory inspection cycles.
China
State-backed infrastructure buildouts in petrochemical and pipeline sectors absorb rising volumes of wear-resistant carbide systems. GB standards for occupational dust exposure and the dual carbon policy reshape domestic production economics for ferrochrome smelters. The Yangtze River Delta concentrates integrated carbide producers with captive renewable power capacity.
Germany
REACH registration requirements under ECHA govern chromium compound import volumes, creating compliance cost barriers for uncertified Asian suppliers. German thermal spray shops consolidate supplier panels and demand multi-year powder supply contracts with embedded compliance certification. The Ruhr industrial cluster maintains heritage metallurgical infrastructure for carburization furnace operations.
India
PLI-linked petrochemical buildout creates first-mover positioning for hardfacing contractors supplying severe-service valve manufacturers. The country's national environmental regulator tightens emissions monitoring for metal finishing operations in Gujarat and Maharashtra industrial zones. The Mumbai-Pune corridor attracts coating service investments targeting refinery expansion projects.
Saudi Arabia
Integrated oil majors embed multi-year coating service contracts with compliance certification for severe-service valve hardfacing. The national oil company anchors long-term procurement frameworks specifying minimum service life guarantees. The Eastern Province concentrates downstream petrochemical infrastructure driving specification-grade chromium carbide demand.
Chromium Carbide Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with powder trading favoring metallurgical heritage players and coating services rewarding applicator certification depth. The vendor base organizes around three tiers: integrated metallurgical producers with carburization furnace infrastructure, thermal spray system bundlers locking in recurring feedstock sales, and regional hardfacing contractors competing on turnaround speed. Dominant competitive moves include backward integration into captive powder production and geographic expansion through qualified coating shop acquisitions.
Among European-heritage metallurgical specialists, H.C. Starck and Oerlikon Metco occupy positions anchoring premium powder supply networks across thermal spray shops. Kennametal represents the North American integrated model, combining engineered carbide production with directional drilling tool hardfacing services. These three exemplify how heritage metallurgical capability and applicator certification depth determine competitive positioning in specification-grade procurement channels.
| Leading Market Players |
|---|
| H.C. Starck |
| Oerlikon Metco |
| Kennametal |
| Saint-Gobain |
| Praxair Surface Tech |
| Sandvik |
| Bodycote |
| Fiven |
| Materion |
| Others |
Supply Flow & Price Mechanics
Permian Basin directional drilling contractors anchor specification-grade procurement, locking in multi-year coating service contracts that transfer wear risk from end-user maintenance budgets to applicator balance sheets. This concentration of technical buyers around performance-guaranteed procurement compresses pricing power toward certified low-leachability formulations and captive thermal spray integration.
Pricing Analysis
Short lead-time premiums of thermal-spray-grade Cr₃C₂ powder concentrate pricing power with metallurgical-grade producers maintaining carburization furnace infrastructure above 1500°C. Three-tier pricing structure across REACH-certified premium, standard thermal-spray-grade, and economy welding consumable tiers separates specification-grade applicators from spot-purchasing job shops. Cost compression in mid-tier powder trading intensifies as Chinese state-backed petrochemical buildouts absorb rising import volumes. Construction contractors represent the most price-sensitive segment, while energy companies accept premium pricing for embedded compliance certification and minimum service life guarantees.
Supply Chain Analysis
High-purity chromium feedstock rests on metallurgical-grade producers in China, Germany, and South Africa with integrated carburization furnace operations. Production draws from ferrochrome smelters, chromium oxide carburization, and spray-dried agglomerate processing as critical inputs. Single-source vulnerability concentrates in thermal-spray-grade spherical powder supply, where ECHA REACH registration requirements create compliance barriers for uncertified Asian suppliers. Distribution runs through direct sales networks bundling powder supply with process parameter support, with regional distributors serving spot-purchasing hardfacing job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over high-purity feedstock and captive thermal spray capacity determines margin capture. Players are pursuing upstream consolidation into carburization furnace infrastructure as the dominant lever.
For Market Incumbents: Extend certification depth by embedding REACH dossier documentation into multi-year powder supply contracts demanded by German and French thermal spray shops. Add captive renewable power capacity at Yangtze River Delta production facilities to align with China's dual carbon policy consolidation pressures. Titanium diboride substitution above 900°C and cold spray technology convergence threaten chromium carbide's thermal envelope. For New Entrants and Emerging Players: Hardfacing contractors in India's Mumbai-Pune corridor offer the most penetrable entry point, with PLI-linked petrochemical buildout creating first-mover positioning for severe-service valve manufacturers. Target autonomous mining fleet maintenance networks in Australian iron ore and Chilean copper operations where abrasive ground engagement accelerates wear part replacement cycles. Partner with emerging cold spray equipment providers to access temperature-sensitive aerospace MRO applications previously excluded from thermal spray coverage. For Investors and Strategic Acquirers: The window for entry favors vertically integrated European metallurgical specialists with full ECHA substance dossiers and established direct sales networks. Long-term viability hinges on consolidation toward integrated producers with captive renewable power and closed-loop environmental module deployment. Watch EPA NESHAP enforcement cycles and ECHA authorization timeline compression as inflection indicators for regulatory-driven supplier panel consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive carburization furnace infrastructure locks in thermal-spray-grade powder margins against spot market volatility. |
| Closed-Loop Thermal Spray Booth Deployment | Pre-engineered environmental modules compress EPA NESHAP permitting timelines for North American hardfacing contractors. |
| REACH Certification Investment | Full substance dossier documentation opens EU procurement channels closed to uncertified Asian suppliers. |
| Cold Spray Technology Partnership | Aerospace MRO access expands addressable substrate coverage beyond traditional thermal spray temperature limits. |
| Renewable Power Integration | Dual carbon policy alignment secures operating licenses for Yangtze River Delta ferrochrome smelters. |
Methodological Framework
Multi-period observation of thermal spray equipment deployment, REACH registration concentration, and autonomous mining fleet adoption anchored the trend analysis, supplemented by interviews with thermal spray shop operators, hardfacing contractors, petrochemical procurement leads, and metallurgical plant managers. Secondary validation drew from ECHA substance dossier databases, EPA NESHAP enforcement records, SEC filings of integrated carbide producers, and Chinese customs trade data for high-purity Cr₃C₂ imports. Bottom-up powder volume estimates triangulated against top-down coating service revenue aggregation.
Input-output matrices modeled chromium carbide demand across product type, application severity, and end-user specification authority dimensions throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by pricing tier concentration. Industry-specific forecast inputs included directional drilling activity in Permian Basin and North Sea producing basins, plus autonomous haul truck fleet deployment rates in Australian iron ore and Chilean copper operations.
Caveats apply where tungsten price volatility, ECHA authorization timeline compression, or China's dual carbon policy enforcement intensity could materially shift the outlook. Forecasts reflect assumptions around regulatory inspection cycle timing and state-backed infrastructure procurement continuity. A small set of triggers—EPA NESHAP penalty escalation, REACH substance restriction expansion, and cold spray technology cost reduction—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Tungsten Titanium Carbide Market
Advanced Alloys
Forgings Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
North America Green Steel Market