
 Global Ferroalloys Market | 2026-2036
Global Ferroalloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ferroalloys Market Foresight
Automotive component producers are bifurcating from traditional construction buyers as the dominant growth archetype for specialty ferroalloy grades. Glencore leverages its integrated chromite-to-ferrochrome chain to secure long-dated automotive contracts. Ferroglobe sustains R&D intensity in silicon-based alloys for electric vehicle motor laminations. Tata Steel anchors Indian demand through captive ferromanganese operations at its Jamshedpur complex.
Ferroalloys denote iron-based alloys containing one or more alloying elements such as chromium, manganese, silicon, or vanadium, typically produced via submerged arc furnace smelting at temperatures exceeding 1,600°C to achieve carbothermic reduction of oxide ores. These alloys serve primarily as deoxidizers and alloying agents in steelmaking, conferring corrosion resistance, tensile strength, and heat tolerance to finished metal products. Ferrochrome commands the largest value pool among product types due to stainless steel's irreplaceable chromium requirements, while ferrosilicon experiences accelerated demand from foundries serving renewable energy casting applications. Electric arc furnace technology dominates operational installations, though oxygen converter routes gain traction where steelmakers seek lower carbon intensity per ton of alloy addition.
EPA emissions standards in the United States, REACH chemical registration in Europe, and China's MEE air quality enforcement collectively tighten permissible particulate and heavy metal discharge from ferroalloy smelters. These frameworks elevate capital requirements for environmental compliance equipment and favor producers with pre-installed baghouse filtration and gas recovery systems. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where alloy premiums for certified low-carbon production will emerge first.
Market Dynamics
China's dual carbon goals and stricter MEE emissions enforcement are forcing furnace technology upgrades across Shanxi and Inner Mongolia, compressing operating margins for producers lacking pre-installed baghouse filtration while rewarding integrated operators with captive chromite access.
Growth Catalysts
- Automotive Motor Laminations:Electric vehicle manufacturers are expanding orders for silicon-based alloys with specific magnetic properties, pulling ferrosilicon demand away from traditional construction applications.
- MEE Air Quality Enforcement:China's tightened particulate discharge limits are accelerating furnace replacement cycles, creating equipment upgrade demand for environmental compliance systems.
- Stainless Steel Capacity Expansion:Indian alloy steel producers are commissioning new submerged arc furnace installations at Odisha and Jharkhand complexes, anchoring regional ferrochrome consumption.
Market Restraints
- Chromite Supply Concentration:South African and Kazakh ore deposits dominate global feedstock availability, exposing ferrochrome producers to concentrated geopolitical and logistics risk.
- Energy Cost Volatility:Submerged arc furnace operations consume 3,500-4,500 kWh per ton of alloy, making electricity tariffs the dominant variable cost input for smelters.
- REACH Chemical Registration:European alloy importers face extended compliance timelines and testing costs for heavy metal content documentation under ECHA requirements.
Strategic Opportunities
- Renewable Energy Castings:Wind turbine gearbox and nacelle manufacturers are specifying high-purity ferrosilicon for ductile iron components, opening foundry demand outside traditional steelmaking.
- Odisha-Jharkhand Corridor:Indian domestic alloy production capacity remains underdeveloped relative to projected stainless steel output, creating import substitution potential for integrated producers.
- Baghouse Filtration Retrofits:MEE-mandated emissions upgrades in China are generating aftermarket service contracts for gas recovery and particulate capture system providers.
Industry Challenges
- Refractory Engineering Talent:Submerged arc furnace design and lining maintenance require specialized metallurgical expertise that is aging out of the workforce across major producing regions.
- Legacy EAF Integration:Steelmakers operating oxygen converter routes face technical complexity when blending refined ferroalloy grades with traditional charge materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ferroalloys Market |
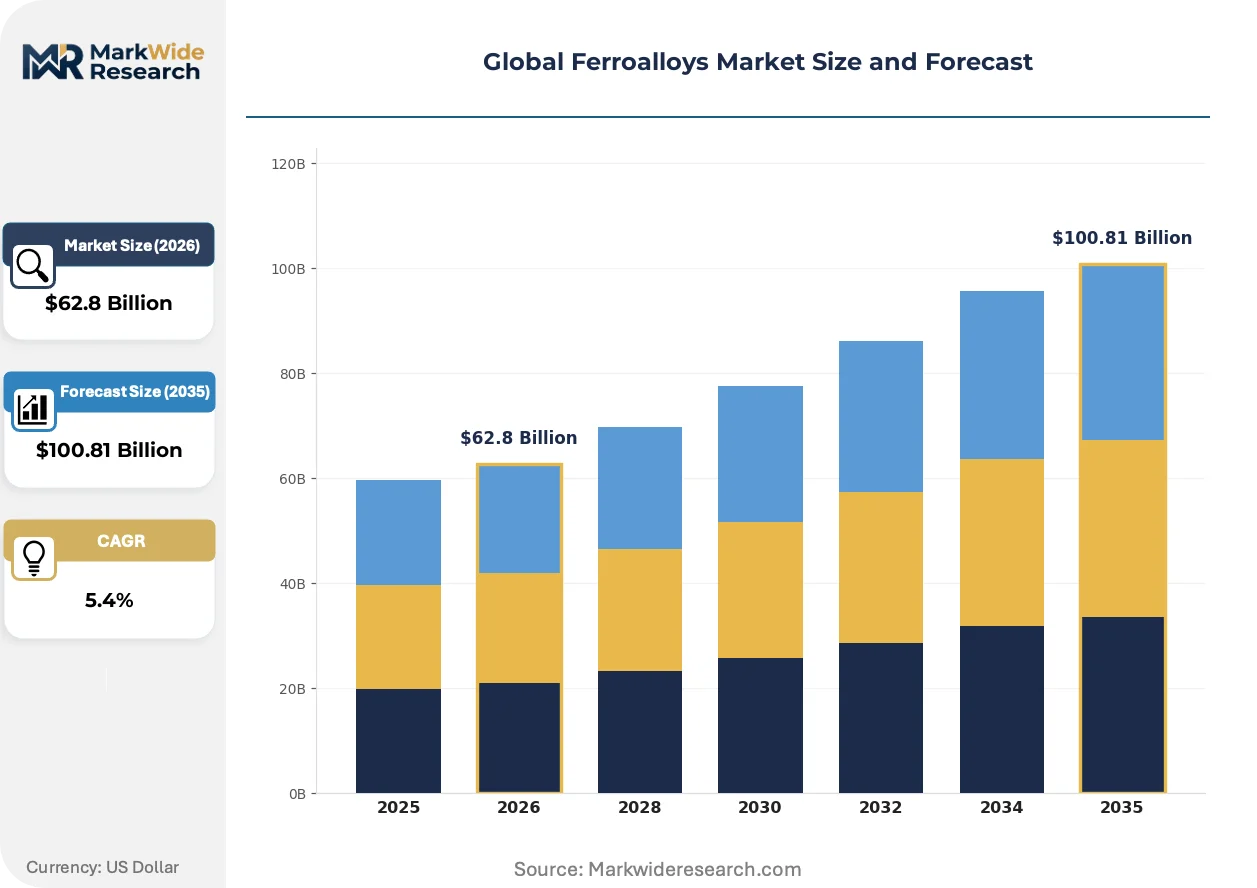
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $100.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferrosilicon, Ferromanganese, Ferrochrome, Ferrotitanium, Ferrovanadium, Ferromolybdenum Technology: Electric Arc Furnace, Blast Furnace Process, Submerged Arc Furnace, Induction Furnace, Oxygen Converter Application: Stainless Steel, Carbon Steel, Alloy Steel, Cast Iron, Tool Steel, Special Steel End User Industry: Steel Manufacturing Units, Foundries, Forging Plants, Construction, Automotive Component Producers, Heavy Machinery Fabricators |
| Companies Covered | Eurasian Resources Group, OM Holdings Ltd., Glencore, Samancor Chrome, Tata Steel, Ferroglobe, Assmang Proprietary Limited, Jindal Steel & Power, China Minmetals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ferroalloys Market Shifts & Advancements
Smelting technology is bifurcating between legacy submerged arc furnace optimization and experimental plasma-based reduction methods, with regulatory carbon accounting becoming the decisive selection criterion for new capacity investments.
Pre-reduced chromite pellet technology is decomposing the traditional ferrochrome value chain by enabling electric arc furnace operators to bypass dedicated smelter intermediaries entirely. Stainless steel producers in Finland and Sweden are trialing direct pellet charging at industrial scale. This compression of the supply tier is threatening merchant ferrochrome operators lacking backward ore integration.
REACH chemical registration requirements under ECHA are extending compliance documentation timelines for ferroalloy importers into the European Union. Heavy metal content testing and supply chain traceability obligations are elevating administrative costs for non-integrated traders. Alloy producers with pre-certified low-carbon production protocols are capturing premium positioning in German and French automotive supply contracts.
Automotive procurement departments are consolidating ferroalloy supplier panels from twelve-to-fifteen vendors down to three-to-four strategic partners with captive chromite or manganese ore access. Long-dated contracts with fixed-volume, indexed-price structures are displacing spot market purchases for specialty grades. This concentration is most visible in German and Japanese motor lamination supply chains, where Tesla and Toyota procurement teams are enforcing single-source accountability requirements.
Global Ferroalloys Market Segmentation
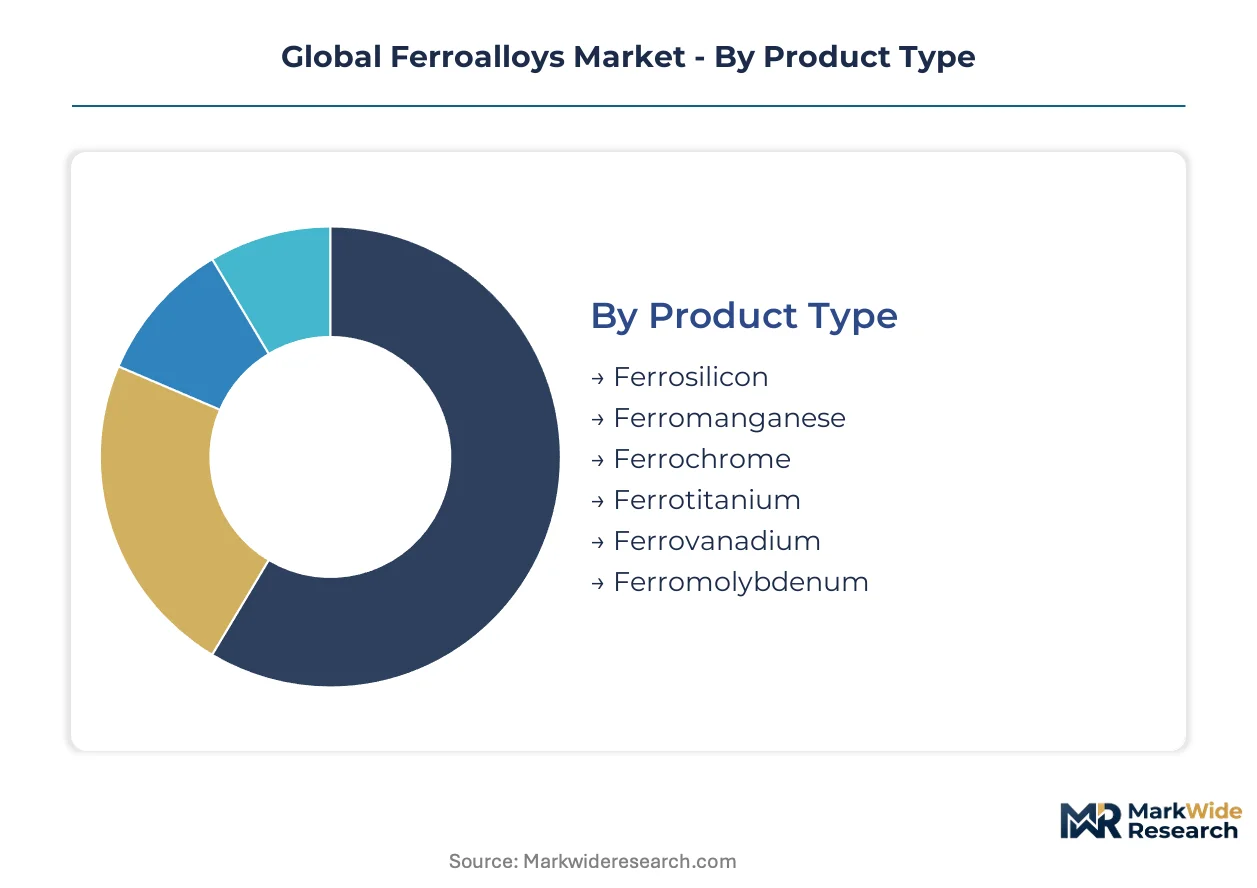
Ferroalloy producers navigate distinct demand profiles across product grades and metallurgical specifications. Channel selection varies sharply between bulk commodity sales to integrated steelmakers and precision-grade contracts serving automotive laminations and specialty foundries.
Product Type:
Merchant distributors dominate ferrosilicon and standard ferromanganese flows, while ferrochrome and specialty grades route through direct mill contracts with indexed pricing.
- Ferrochrome:Comprising iron-chromium alloys with 50-70% chromium content, this grade commands the largest value pool due to stainless steel's irreplaceable chromium requirements. Indian stainless steel expansion at Odisha and Jharkhand complexes anchors regional consumption, though South African and Kazakh ore concentration exposes supply chains to logistics risk.
- Ferrosilicon:Silicon-iron alloys containing 15-90% silicon serve dual roles as deoxidizers and inoculants. Electric vehicle motor lamination manufacturers are pulling demand toward high-purity grades with specific magnetic properties, displacing traditional construction applications.
- Ferromanganese:Manganese-rich alloys function primarily as deoxidizers and sulfur scavengers in carbon steel production. Tata Steel's captive operations at Jamshedpur exemplify backward-integrated supply security.
- Ferrotitanium:Titanium-bearing alloys provide grain refinement and nitrogen fixation in stainless and high-strength low-alloy steels. Aerospace and chemical processing equipment specifications drive premium pricing.
- Ferrovanadium:Vanadium additions enhance tensile strength and wear resistance in tool steels and high-strength structural grades. Oil and gas pipeline specifications sustain niche demand.
- Ferromolybdenum:Molybdenum alloys improve creep resistance and corrosion performance in power generation and chemical processing equipment. Spot market liquidity remains thin relative to other grades.
By volume, ferrochrome leads. By growth pace, ferrosilicon for electric vehicle applications is climbing the fastest.
Technology:
Capital intensity and energy consumption stratify technology selection, with environmental compliance costs now outweighing pure metallurgical efficiency in investment decisions.
- Submerged Arc Furnace:The dominant installed base operates at 1,600-2,000°C via carbothermic reduction, consuming 3,500-4,500 kWh per ton of alloy. China's MEE-mandated emissions upgrades are forcing replacement cycles across Shanxi and Inner Mongolia.
- Electric Arc Furnace:Pre-reduced chromite pellet charging enables stainless steel producers to bypass dedicated smelter intermediaries entirely. Finnish and Swedish trials threaten merchant ferrochrome operators lacking ore integration.
- Blast Furnace Process:Legacy installations persist where coke availability and existing infrastructure amortize conversion costs. Environmental discharge permitting constrains new capacity.
- Induction Furnace:Lower capital requirements suit small-batch specialty alloy production. Refractory maintenance costs and scale limitations restrict adoption to niche grades.
- Oxygen Converter:Gaining traction where steelmakers seek lower carbon intensity per ton of alloy addition, though technical complexity in blending refined grades constrains deployment.
Submerged arc furnaces retain volume leadership. Oxygen converter routes show steepest adoption trajectory among new investments.
Application:
Application-driven demand splits between corrosion-resistant specifications requiring precise chromium dosing and mechanical property grades where manganese and silicon dominate alloying decisions.
- Stainless Steel:Austenitic and ferritic grades consume 70-75% of global ferrochrome output. Automotive exhaust systems and architectural cladding sustain baseline demand.
- Carbon Steel:Deoxidation and sulfur control drive ferromanganese and ferrosilicon consumption. Construction and infrastructure specifications standardize around commodity grades.
- Alloy Steel:Engineering steels for automotive drivetrain and powertrain components require precise vanadium, molybdenum, and nickel microalloying.
- Cast Iron:Foundry inoculation with ferrosilicon controls graphite morphology. Wind turbine gearbox and nacelle manufacturers are specifying high-purity grades for ductile iron components.
- Tool Steel:Cutting and forming applications demand tungsten, molybdenum, and vanadium additions for hardness retention at elevated temperatures.
- Special Steel:Electrical steels for transformer laminations and nuclear pressure vessel grades require ultra-low residual element controls.
Stainless steel anchors volume. Cast iron for renewable energy equipment is expanding most quickly.
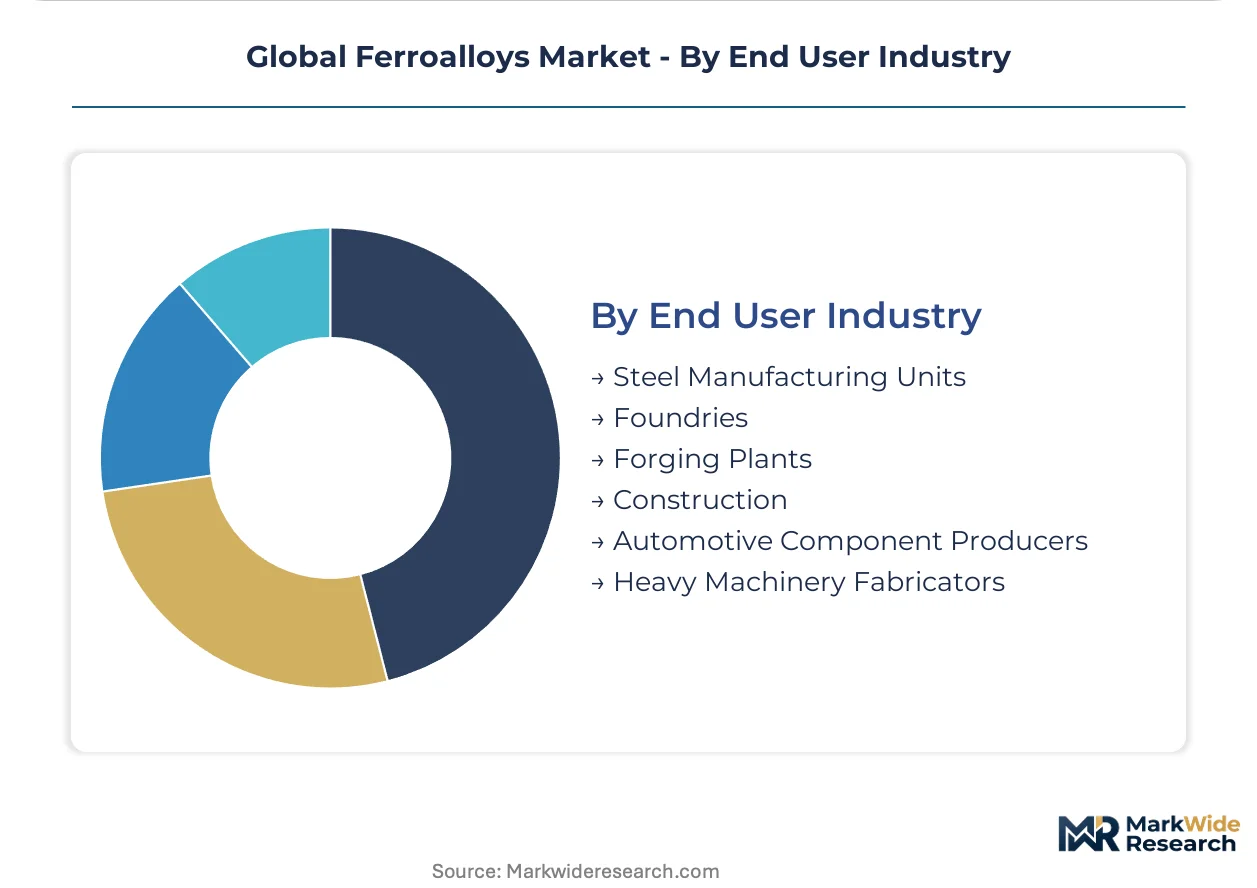
End User Industry:
Procurement consolidation is bifurcating the customer base between consolidated automotive panels demanding single-source accountability and fragmented construction buyers purchasing through distributors.
- Steel Manufacturing Units:Integrated mills with captive ferroalloy operations secure supply continuity. Merchant purchases concentrate among mini-mill operators lacking backward integration.
- Foundries:Ductile iron and steel casting operations specify inoculant and nodularizer grades. Renewable energy casting demand is opening foundry applications outside traditional steelmaking channels.
- Forging Plants:Open-die and closed-die forging operations consume alloy steel billets with precise microalloying for aerospace and power generation applications.
- Construction:Rebar and structural steel specifications standardize around commodity ferromanganese and ferrosilicon grades. Price sensitivity favors spot market purchasing.
- Automotive Component Producers:Motor lamination and drivetrain specifications are consolidating supplier panels from twelve-to-fifteen vendors down to three-to-four strategic partners with captive ore access.
- Heavy Machinery Fabricators:Mining equipment and construction machinery demand high-strength wear-resistant grades with manganese and boron alloying.
Steel manufacturing units dominate volume. Automotive component producers are gaining share fastest through electrification-driven silicon alloy demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African chromite shipments feed Chinese smelters in Shanxi and Inner Mongolia, while Kazakh ore moves westward toward European stainless steel mills. Trade corridors reflect concentrated ore geology against dispersed steel demand.
China
Shanxi and Inner Mongolia house the dominant submerged arc furnace base for ferrochrome and ferrosilicon production. MEE air quality enforcement is accelerating furnace replacement cycles and baghouse filtration retrofits. Baotou and Taiyuan industrial clusters are absorbing environmental compliance costs that compress margins for non-integrated operators.
India
Odisha and Jharkhand stainless steel expansions by Jindal Steel & Power and Tata Steel are anchoring ferrochrome consumption growth. BIS quality standards and PLI scheme incentives for specialty steel are reshaping procurement toward domestic alloy sourcing. Raipur and Jamshedpur smelter complexes are capturing import substitution momentum.
South Africa
Bushveld Complex chromite deposits supply 40% of global ferrochrome feedstock, concentrating geopolitical and logistics risk in a single geology. Department of Mineral Resources and Energy licensing frameworks govern mine-to-smelter integration. Rustenburg and Lydenburg processing hubs are defending market position through captive ore access.
United States
EPA emissions standards under the Clean Air Act constrain particulate discharge from remaining domestic ferroalloy smelters. Electric arc furnace steelmaking in the Great Lakes region sustains merchant ferrosilicon and ferromanganese demand. Ohio Valley and Southeast industrial corridors are absorbing specialty alloy imports for automotive laminations.
Finland
Outokumpu-led trials of pre-reduced chromite pellet charging threaten traditional ferrochrome smelter intermediaries. REACH chemical registration under ECHA elevates documentation costs for heavy metal content traceability. Tornio stainless steel complex is validating direct pellet charging at industrial scale.
Global Ferroalloys Market Competitive Landscape
Listed leaders compete with private specialists across chromite-to-alloy integration depth, creating a tiered structure where ore access determines margin sustainability. The vendor base stratifies between fully integrated miners, merchant smelters, and captive steel mill operations. Three archetypes dominate: chromite-integrated majors, silicon-focused specialists, and steelmaker-captive producers. Capacity expansion and backward integration into ore assets represent the dominant competitive moves.
Within the chromite-integrated tier, Glencore and Samancor Chrome exemplify ore-to-alloy control that secures long-dated automotive contracts. Among silicon-based specialists, Ferroglobe occupies a position representing R&D intensity for electric vehicle motor laminations. Tata Steel and Jindal Steel & Power sit within the steelmaker-captive archetype, anchoring Indian demand through in-house ferroalloy production.
| Leading Market Players |
|---|
| Eurasian Resources Group |
| OM Holdings Ltd. |
| Glencore |
| Samancor Chrome |
| Tata Steel |
| Ferroglobe |
| Assmang Proprietary Limited |
| Jindal Steel & Power |
| China Minmetals Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with fixed-volume, indexed-price structures lock in chromite feedstock access while capping price volatility for integrated ferrochrome producers serving automotive laminations. Glencore and Samancor Chrome leverage these arrangements to secure multi-year supply commitments from German and Japanese motor manufacturers, insulating margins against South African logistics disruptions.
Pricing Analysis
Submerged arc furnace technology commands premium pricing over legacy blast furnace output due to stricter MEE emissions compliance in Shanxi and Inner Mongolia. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified low-carbon grades from commodity ferrochrome, with certification tier and volume scale as primary differentiation drivers. Cost compression in standard-grade ferrosilicon is intensifying because Chinese smelters absorb baghouse retrofit expenses. Construction buyers exhibit highest price sensitivity, while automotive procurement panels prioritize supply security over unit economics.
Supply Chain Analysis
Strategic chromite stockpiling dominates over just-in-time preferences as South African and Kazakh ore concentration exposes ferrochrome producers to concentrated geopolitical risk. The supply chain draws from Bushveld Complex deposits, Indian Odisha-Jharkhand corridor expansions, and Finnish pre-reduced pellet trials. Chromite ore, metallurgical coke, and electricity tariffs constitute critical input dependencies. Single-source vulnerability concentrates in ore logistics routes through Richards Bay and Aqtau ports. Distribution runs through direct mill contracts for ferrochrome and merchant distributors for standard ferrosilicon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-reduced chromite pellet technology threatens traditional smelter intermediaries with supply chain compression, forcing incumbent ferrochrome operators to defend integration depth or face margin erosion from stainless steel producers bypassing dedicated alloy suppliers.
For Market Incumbents: Consolidate chromite-to-alloy integration through captive mine acquisitions or long-dated offtake agreements with South African and Kazakh ore suppliers. Deepen R&D investment in silicon-based magnetic alloys for electric vehicle motor laminations to offset displacement risk from pellet-based direct charging. MEE emissions compliance costs favor producers with pre-installed baghouse filtration. For New Entrants and Emerging Players: Differentiate on low-carbon certification protocols to capture premium positioning in German and French automotive supply chains. Target Odisha-Jharkhand corridor import substitution as Jindal Steel & Power and Tata Steel expand stainless steel capacity without matching domestic alloy production. Pursue foundry-grade ferrosilicon for wind turbine castings as a channel outside consolidated steelmaker procurement. For Investors and Strategic Acquirers: Ore-integrated mid-tier producers with captive Bushveld Complex access represent the most defensible acquisition archetype as merchant smelters face pellet-based disintermediation. Long-term viability hinges on carbon intensity per ton of alloy addition across the analysis window. Watch for MEE-mandated furnace replacement cycles in Shanxi and Inner Mongolia as inflection indicators for equipment upgrade demand and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromite Assets | Captive ore access insulates Glencore and Samancor from South African logistics volatility. |
| Baghouse Filtration Retrofit Programs | MEE compliance mandates in Shanxi generate aftermarket service contracts for gas recovery providers. |
| Low-Carbon Certification Investment | REACH-compliant producers capture premium positioning in German automotive laminations supply. |
| Pre-Reduced Pellet Technology Trials | Outokumpu's Tornio complex validates direct charging that threatens merchant ferrochrome operators. |
| Foundry Channel Expansion | Wind turbine gearbox manufacturers specify high-purity ferrosilicon outside steelmaker procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with submerged arc furnace plant managers, automotive procurement leads at German and Japanese OEMs, chromite mine operations directors, and foundry technical directors. Secondary validation drew from SEC filings of listed alloy producers, Chinese MEE emissions disclosure databases, Indian BIS quality standard notifications, and European ECHA REACH registration records. Bottom-up capacity assessments and top-down steel production forecasts were triangulated to anchor volume projections.
Across the analysis window, the forecasting framework models ferroalloy demand through product grade, metallurgical specification, end-use application, and regional production hub segmentation. CAGRs were derived from alloy intensity per ton of finished steel by application category, overlaying stainless steel capacity expansion timelines and electric vehicle motor lamination penetration curves. Energy cost trajectories and ore logistics risk premiums inform margin projections.
Material uncertainties — chromite supply disruptions, MEE enforcement intensity variations, and pellet technology adoption rates — sit outside the modeled envelope. Forecasts reflect assumptions around furnace replacement cycles and automotive procurement consolidation trajectories. Revision becomes warranted when pre-reduced pellet charging crosses industrial-scale deployment thresholds or when South African logistics chokepoints trigger sustained ore price spikes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Tantalum Carbide Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
US Green Steel Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Cermet Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Asia-Pacific Metal Casting Market