
 Titanium Aluminide Market | 2026-2036
Titanium Aluminide Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Aluminide Market Outlook
Aerospace OEMs is collapsing the historical reliance on aftermarket providers for titanium aluminide turbine blade replacements. ATI leverages captive melt capacity and vacuum arc remelting infrastructure to supply forged billet directly to engine programs. VSMPO-AVISMA dominates titanium sponge feedstock supply through its Verkhnyaya Salda complex, anchoring raw material security for Western superalloy producers. Precision Castparts Corp competes via investment casting scale at its Portland and Worcester facilities, sustaining position in low-pressure turbine blade shipments.
Titanium aluminide denotes an ordered intermetallic alloy of titanium and aluminum, typically TiAl with 46-50 atomic percent aluminum, exhibiting density below half that of nickel superalloys while retaining creep resistance above 750°C; manufacturers produce it via vacuum induction melting followed by hot isostatic pressing to eliminate casting porosity for rotating engine components. The alloy segment leads in revenue contribution due to established gamma-TiAl qualification across GE Aviation and Pratt & Whitney engine platforms, while the powder segment grows fastest as additive manufacturing qualification progresses for complex vane geometries. Aerospace applications command the dominant share of offtake, though automotive turbocharger turbine wheels represent an emerging volume outlet as diesel engine thermal efficiency targets intensify.
FAA airworthiness standards and EASA Part 21 certification requirements govern material qualification timelines for flight-critical titanium aluminide castings, extending development cycles but creating regulatory moats for qualified suppliers. REACH chemical registration in Europe and EPA hazardous air pollutant standards in the United States constrain machining and grinding operations, elevating environmental compliance costs for precision finishers. Stakeholders must monitor additive manufacturing qualification pathways and powder metallurgy cost curves to anticipate whether near-net-shape processes will displace conventional investment casting in next-generation engine architectures.
Market Dynamics
Aerospace OEM procurement strategies are collapsing the traditional aftermarket repair ecosystem for turbine components, forcing material suppliers to restructure around direct engine program partnerships rather than distributed MRO networks.
Growth Catalysts
- FAA Airworthiness Directives:Tightening traceability mandates for high-temperature engine components are locking qualified suppliers into long-term qualification pipelines with GE Aviation and Pratt & Whitney.
- Gamma-TiAl Alloy Adoption:Turbine blade manufacturers are accelerating volume orders as original equipment manufacturers shift capital toward new-engine development programs over legacy platform maintenance.
- German Precision Casting Clusters:Concentrated supplier networks serving Rolls-Royce and MTU Aero Engines are creating localized economies of scale in vacuum investment casting capacity.
Market Restraints
- Titanium Sponge Supply Concentration:VSMPO-AVISMA's Verkhnyaya Salda complex controls critical feedstock flows, exposing Western superalloy producers to single-source geopolitical risk.
- REACH Chemical Registration:European machining and grinding operations face elevated environmental compliance costs under ECHA substance authorization requirements for hazardous air pollutants.
- Nickel Superalloy Substitution Resistance:Established creep resistance benchmarks above 750°C in conventional turbine materials slow qualification timelines for intermetallic alternatives.
Strategic Opportunities
- Automotive Turbocharger Expansion:Diesel engine thermal efficiency mandates are opening volume outlets for titanium aluminide turbine wheels in European passenger vehicle platforms.
- Additive Manufacturing Qualification:Powder metallurgy pathways for complex vane geometries offer near-net-shape production economics displacing conventional investment casting.
- EASA Part 21 Certification Moats:Extended material qualification timelines create defensive barriers for first-mover suppliers with established flight-critical casting approvals.
Industry Challenges
- Vacuum Arc Remelting Talent Scarcity:Specialized metallurgical expertise for eliminating casting porosity in rotating engine components remains concentrated among legacy aerospace suppliers.
- Hot Isostatic Pressing Capacity Bottlenecks:Capital-intensive HIP infrastructure requirements constrain batch throughput for aerospace-grade billet production.
- Cross-Platform Certification Fragmentation:Divergent OEM-specific qualification standards prevent material suppliers from achieving economies of scope across engine architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Aluminide Market |
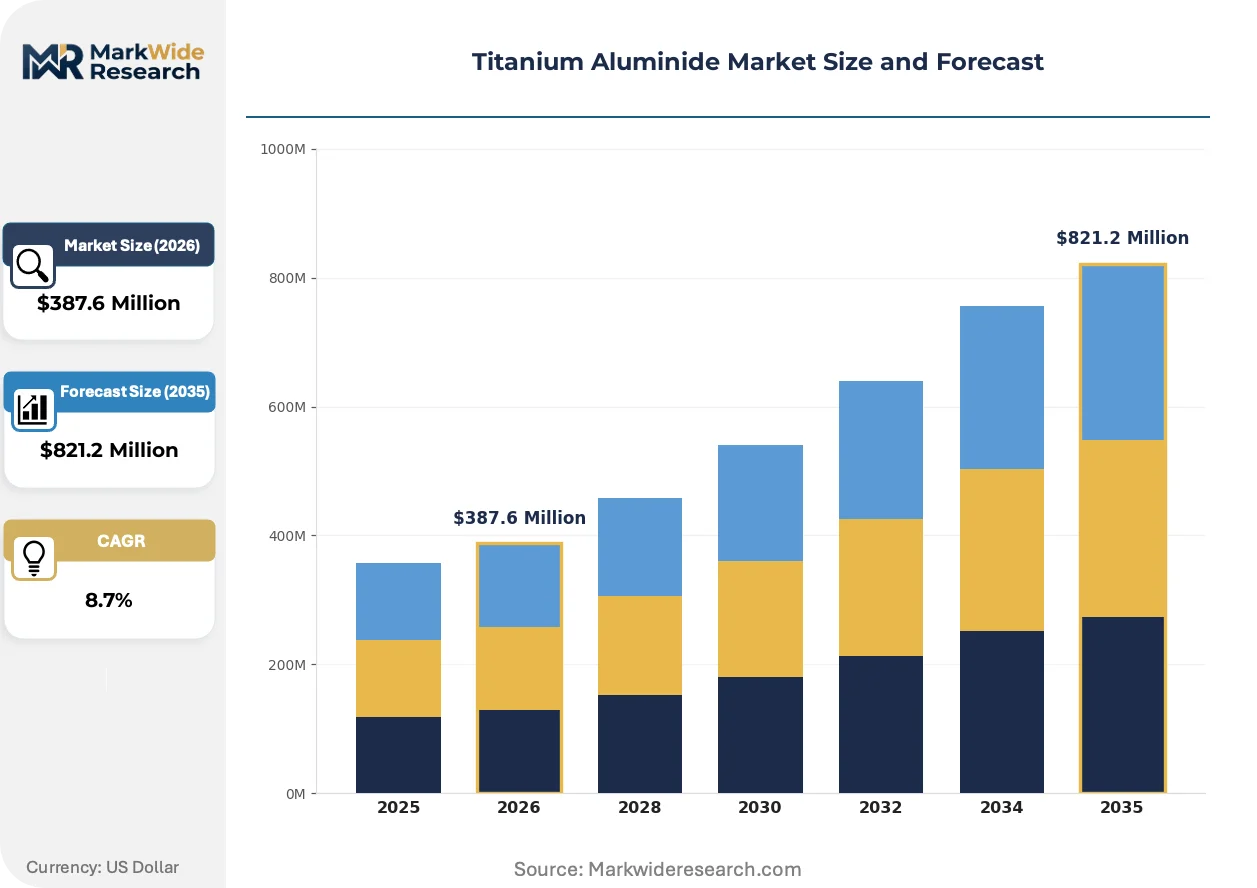
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy, Intermetallic Compound, Composite, Powder Application: Aerospace, Automotive, Industrial, Military Form: Sheet, Bar, Plate, Billet End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Manufacturers |
| Companies Covered | GfE Metalle und Materialien, ATI, VSMPO-AVISMA Corporation, Carpenter Technology Corporation, Precision Castparts Corp, Western Superconducting Technologies, Toho Titanium, Daido Steel, Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Aluminide Market Strategic Shifts
Process technology diversification is fragmenting the historically concentrated investment casting value chain, with powder metallurgy and additive routes challenging incumbent production economics.
Additive manufacturing qualification for titanium aluminide is fragmenting traditional supply relationships. GE Aviation and Pratt & Whitney are advancing selective laser melting protocols for complex low-pressure turbine vane geometries. Near-net-shape production is compressing lead times and material waste ratios compared to subtractive machining from forged billet.
EPA hazardous air pollutant standards are tightening emissions controls for precision grinding operations. Machining facilities serving aerospace casting houses face capital upgrades for particulate capture systems. Western European finishers are relocating rough machining to jurisdictions with less stringent MEE enforcement.
Direct engine program contracting is displacing aftermarket procurement channels. OEM material buyers are consolidating supplier panels and mandating captive melt capacity investments. German turbine blade casters report compressed switching cycles as Rolls-Royce and MTU Aero Engines renegotiate long-term offtake agreements.
Titanium Aluminide Market Segmentation
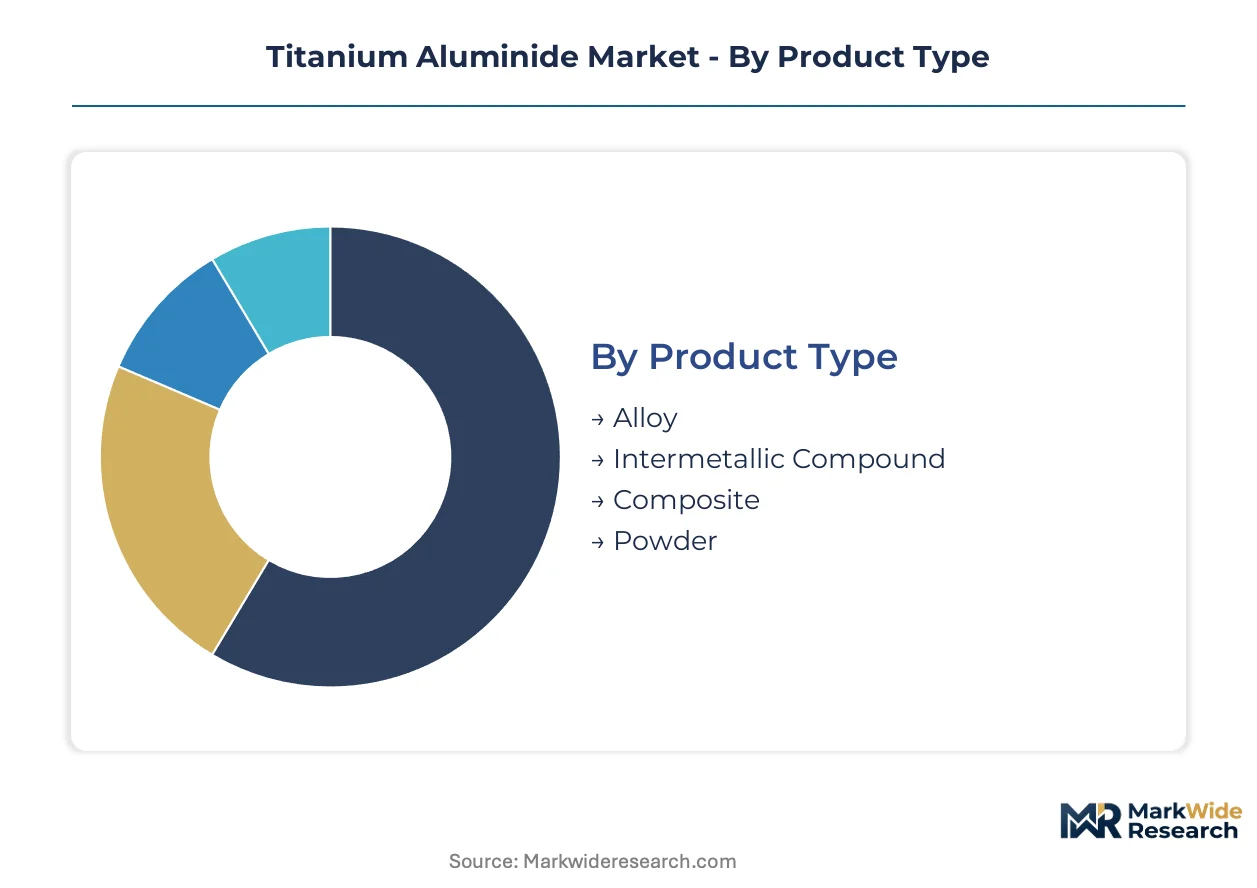
Titanium aluminide procurement patterns diverge sharply across material forms and end-use specifications, with aerospace qualification requirements creating rigid segment boundaries that resist cross-application substitution. Manufacturers must align production assets against distinct certification timelines and metallurgical tolerances rather than treating the material as a commoditized input.
Product Type:
Substitution pressure from nickel superalloys and ceramic matrix composites varies dramatically by product category, with established alloys defending aerospace positions while emerging formats face steeper qualification barriers.
- Alloy:Gamma-TiAl formulations with 46-50 atomic percent aluminum dominate rotating engine component supply chains through established vacuum induction melting protocols. GE Aviation and Pratt & Whitney procurement contracts concentrate demand in this segment for low-pressure turbine blade applications where density advantages below half that of nickel superalloys justify extended qualification investments.
- Powder:Additive manufacturing feedstock for selective laser melting of complex vane geometries is climbing the fastest as near-net-shape production economics challenge conventional investment casting waste ratios. Powder metallurgy pathways compress lead times for prototype-to-production transitions in next-generation engine architectures.
- Intermetallic Compound:Ordered crystal structures beyond gamma-phase TiAl serve specialized thermal barrier applications in research-stage turbine programs.
- Composite:Reinforced titanium aluminide matrices address extreme creep resistance requirements in experimental propulsion systems.
Alloy retains volume leadership; powder holds the steepest expansion curve.
Application:
Cost tier stratification separates flight-critical aerospace procurement from price-sensitive industrial offtake, with automotive emerging as a mid-tier volume bridge.
- Aerospace:FAA airworthiness directives and EASA Part 21 certification requirements govern material qualification timelines for turbine blade and vane castings in commercial engine platforms. OEM direct contracting is displacing aftermarket procurement channels, forcing suppliers to restructure around long-term engine program partnerships rather than distributed MRO networks.
- Automotive:Diesel engine thermal efficiency mandates in European passenger vehicle platforms are opening volume outlets for titanium aluminide turbocharger turbine wheels. Precision casting houses in Germany report accelerating inquiries from Tier-1 suppliers serving BMW and Volkswagen powertrain divisions.
- Industrial:Heat exchanger and furnace component applications face intense substitution pressure from lower-cost stainless steel and nickel alloy alternatives.
- Military:Defense propulsion programs maintain classified qualification pathways with specialized metallurgical tolerances for combat aircraft engines.
Aerospace commands procurement priority; automotive delivers the most rapid demand scaling.
Form:
Supply concentration in vacuum arc remelting and hot isostatic pressing infrastructure favors billet and bar formats over thin-gauge sheet production.
- Billet:Forged billet supply anchors the value chain through ATI's captive melt capacity and vacuum arc remelting infrastructure, with direct shipment to engine program forges eliminating intermediate processing steps. Hot isostatic pressing eliminates casting porosity for rotating components subject to centrifugal loading.
- Bar:Precision-machined bar stock serves fastener and structural bracket applications in airframe assemblies where weight reduction justifies premium material costs over titanium alloys.
- Sheet:Thin-gauge rolled product faces limited qualified demand due to brittleness challenges in forming operations.
- Plate:Intermediate thickness plate serves static structural applications in exhaust nozzles and thermal shields.
Billet maintains supply dominance; bar formats are expanding most quickly into adjacent airframe applications.
End User:
Customer type determines contracting structure, with OEM captive requirements forcing upstream integration decisions on material suppliers.
- OEMs:GE Aviation and Pratt & Whitney material buyers consolidate supplier panels and mandate captive melt capacity investments, collapsing traditional aftermarket procurement channels. Direct engine program contracting locks qualified suppliers into decade-long offtake agreements with stringent traceability mandates.
- Tier-1 Suppliers:Precision Castparts Corp and German casting clusters serving Rolls-Royce and MTU Aero Engines sustain position through investment casting scale at Portland, Worcester, and regional German facilities.
- Aftermarket Providers:Legacy MRO networks face compressed blade replacement volumes as OEMs shift capital toward new-engine development over legacy platform maintenance.
- Manufacturers:Automotive turbocharger producers and industrial equipment fabricators represent emerging demand with less stringent qualification requirements.
OEMs control procurement design authority; Tier-1 suppliers capture the most significant volume intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russian titanium sponge shipments from VSMPO-AVISMA's Verkhnyaya Salda complex feed Western European and North American superalloy producers, creating a geopolitically sensitive trade corridor that shapes regional supply security calculations.
Germany
Precision casting clusters in North Rhine-Westphalia and Baden-Württemberg serve Rolls-Royce and MTU Aero Engines with vacuum investment casting capacity for gamma-TiAl turbine blades. REACH chemical registration under ECHA mandates stringent hazardous substance tracking for machining operations. The Aachen-Dortmund industrial corridor concentrates vacuum arc remelting infrastructure for aerospace-grade billet production.
United States
GE Aviation and Pratt & Whitney procurement contracts drive gamma-TiAl demand for low-pressure turbine applications in next-generation commercial engines. FAA airworthiness directives enforce material traceability standards that extend supplier qualification timelines. Pittsburgh and Worcester casting facilities anchor domestic investment casting capacity for rotating engine components.
Japan
Toho Titanium and Daido Steel maintain integrated sponge-to-alloy production chains serving domestic aerospace and automotive turbocharger manufacturers. METI industrial policy supports advanced materials R&D through targeted funding programs. The Chubu region around Nagoya hosts precision casting clusters supplying Toyota and Honda powertrain divisions.
China
Western Superconducting Technologies and state-owned titanium producers expand domestic gamma-TiAl capacity for indigenous commercial engine programs under MIIT technology roadmaps. GB standards govern materials qualification for aviation applications. The Shaanxi and Sichuan industrial bases concentrate vacuum melting infrastructure for military and civil aerospace programs.
United Kingdom
Rolls-Royce Derby engineering centers specify titanium aluminide for UltraFan engine architectures, driving procurement from German casting networks. EASA Part 21 certification requirements align with UK CAA post-Brexit regulatory frameworks. The Midlands aerospace cluster maintains specialized hot isostatic pressing capacity for porosity elimination in rotating components.
Titanium Aluminide Market Competitive Environment
Player mix skews toward integrated titanium producers with captive melt capacity and specialized aerospace casters with established OEM qualifications. The competitive structure concentrates around three strategic archetypes: upstream sponge-to-billet integrators controlling feedstock security, precision investment casters with flight-critical approvals, and emerging powder metallurgy specialists pursuing additive manufacturing pathways. Capacity expansion and strategic partnerships dominate competitive moves as OEMs mandate direct program relationships over traditional aftermarket channels.
Among German-based material suppliers, GfE Metalle und Materialien exemplifies the integrated specialty metals archetype with positions across titanium intermetallics and superalloy feedstocks. ATI represents North American vertical integration from sponge through vacuum arc remelted billet, occupying a position as a direct engine program supplier to GE Aviation and Pratt & Whitney. Precision Castparts Corp anchors the investment casting tier with scale positions in low-pressure turbine blade shipments, while VSMPO-AVISMA sits within the critical feedstock security layer as the dominant titanium sponge source for Western superalloy producers. Japanese specialists Toho Titanium and Daido Steel occupy positions in the integrated Asia-Pacific supply base, with Western Superconducting Technologies representing Chinese state-backed capacity expansion in advanced titanium materials.
| Leading Market Players |
|---|
| GfE Metalle und Materialien |
| ATI |
| VSMPO-AVISMA Corporation |
| Carpenter Technology Corporation |
| Precision Castparts Corp |
| Western Superconducting Technologies |
| Toho Titanium |
| Daido Steel |
| Alcoa Corporation |
| Others |
Value Chain & Pricing Dynamics
Vacuum arc remelting capacity utilization at German and US facilities shapes both supply concentration and price floors for aerospace-grade billet. Hot isostatic pressing bottlenecks constrain batch throughput, forcing OEMs to accept long-term offtake premiums that lock in qualified suppliers.
Pricing Analysis
Gamma-TiAl alloy pricing for current-generation low-pressure turbine blades commands substantial premiums over prior-generation nickel superalloy benchmarks, while next-generation powder metallurgy formats face steeper qualification cost absorption. Contract-based long-term offtake dominates, with price differentiation driven by EASA Part 21 certification tier and captive melt capacity ownership. Cost compression in standard-grade billet intensifies as Russian sponge feedstock flows face tariff exposure. Tier-1 precision casters exhibit lowest price sensitivity; automotive turbocharger entrants show highest.
Supply Chain Analysis
Russia, Japan, and China anchor titanium sponge production, with VSMPO-AVISMA's Verkhnyaya Salda complex and Toho Titanium's integrated chains feeding Western superalloy producers. The supply chain draws from titanium sponge, vacuum induction melting infrastructure, and hot isostatic pressing capacity as critical inputs. Single-source vulnerability concentrates in Russian feedstock flows subject to trade restriction. Distribution runs through direct engine program contracting rather than aftermarket MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Titanium aluminide sits at an inflection where additive manufacturing qualification and FAA traceability mandates are compressing incumbent advantage windows. The report frames strategic positioning around feedstock security, certification moats, and process technology diversification.
For Market Incumbents: Fortify captive melt capacity positions through vacuum arc remelting infrastructure additions in Germany and the United States. Deepen EASA Part 21 certification portfolios to defend against powder metallurgy entrants. Secure long-term titanium sponge supply agreements that bypass Russian concentration risk. Channel control through direct OEM contracting remains the priority lever against aftermarket erosion. For New Entrants and Emerging Players: Differentiate on additive manufacturing qualification pathways for complex vane geometries where near-net-shape economics challenge investment casting incumbents. Target automotive turbocharger turbine wheels as the most penetrable volume segment with less stringent aerospace certification barriers. Pursue joint development agreements with European Tier-1 suppliers serving BMW and Volkswagen powertrain divisions as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision casters with decade-long OEM offtake agreements and flight-critical casting approvals. Long-term viability centers on suppliers with backward integration into sponge or forward integration into HIP finishing. Monitor additive manufacturing qualification timelines at GE Aviation and Pratt & Whitney as the signal for process substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Melt Capacity Expansion | ATI and German casters secure direct GE Aviation and Rolls-Royce program supply without intermediate processors. |
| Additive Manufacturing Qualification | Selective laser melting protocols at Pratt & Whitney compress lead times for complex low-pressure turbine vane geometries. |
| Long-term Sponge Supply Agreement | Toho Titanium and Japanese producers anchor feedstock security for Western superalloy makers facing Russian supply risk. |
| EASA Part 21 Certification Investment | Extended qualification timelines create defensive moats for first-mover German casting clusters serving MTU Aero Engines. |
| Automotive Turbocharger Partnership | Precision casters in North Rhine-Westphalia capture volume outlets from BMW and Volkswagen thermal efficiency mandates. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with vacuum arc remelting plant managers, aerospace procurement leads at GE Aviation and Pratt & Whitney, precision casting technical directors, and EASA certification specialists; and secondary validation against FAA airworthiness directive filings, EASA Part 21 approval databases, customs trade data for titanium sponge flows, and SEC filings from listed titanium producers. Bottom-up segment sizing triangulated against top-down aerospace engine production forecasts.
Across the analysis window, the forecasting framework modeled titanium aluminide demand by product type, application, form, and end-user category, with regional production cluster as an additional aerospace-specific dimension. CAGRs derived from engine program ramp schedules and qualification timeline assumptions. Key inputs included OEM new-engine development capital allocation shifts and automotive diesel efficiency regulatory trajectories.
Material uncertainties — geopolitical disruption to Russian sponge flows, additive manufacturing qualification acceleration, REACH chemical registration cost escalation — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification timeline stability and OEM procurement consolidation continuity. Recalibration cycles align with material shifts in FAA airworthiness directive scope or powder metallurgy process adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
North America Green Steel Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Tantalum Carbide Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Global Quartz Countertops Market