
 Quenched and Tempered Steel Market | 2026-2036
Quenched and Tempered Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Quenched and Tempered Steel Market Intelligence
The capability to produce high-specification alloy steels versus commodity-grade carbon steel is bifurcating the competitive landscape. SSAB AB specializes in high-strength steels for demanding applications, commanding premium pricing. Nucor Corporation leverages its large-scale, efficient production of carbon and alloy steels to serve a broad industrial base. ArcelorMittal competes across both specialized and commodity segments through its extensive global manufacturing footprint and diverse product portfolio.
Quenched and tempered steel is a category of high-strength steel subjected to a specific heat treatment process. This involves rapid cooling (quenching) to form a hard martensitic structure, followed by heating (tempering) to increase toughness and reduce brittleness. Alloy steel and high strength low alloy (HSLA) products command higher margins than standard carbon steel. The construction equipment and mining machinery applications drive the largest volume for these materials, requiring exceptional wear resistance.
The EU Green Deal and China's dual carbon goals are pushing for lower-emission steelmaking processes, impacting technology choices. In the United States, EPA regulations on industrial emissions and OSHA standards for worker safety also shape plant operations. Conformance to ISO 9001 quality management standards is a prerequisite for supplying to critical sectors like power generation. Decisions on capital investment in greener production technologies will define long-term market leadership.
Market Dynamics
The imperative to decarbonize steel production, driven by regulations like the EU Green Deal and China's dual carbon goals, is the central force shaping the quenched and tempered steel market, compelling investment in lower-emission manufacturing technologies.
Growth Catalysts
- Sustainable Infrastructure Mandates:The EU Green Deal and similar global initiatives prioritize materials with high durability and a lower lifecycle carbon footprint, favoring high-strength steels in construction and energy projects.
- Heavy Machinery Advancement:Demand from the construction and mining sectors for equipment with greater load capacity and superior wear resistance requires advanced quenched and tempered steels for components like excavator buckets and dump truck beds.
- Asia-Pacific Urbanization:Large-scale infrastructure development, particularly in China and India, continues to drive significant volume demand for high-strength steels in bridges, high-rise buildings, and transportation networks.
Market Restraints
- Alloying Element Volatility:The price and supply of critical alloying elements such as molybdenum, chromium, and nickel are subject to geopolitical factors and market speculation, creating cost instability for high-specification steel grades.
- Threat of Material Substitution:In certain weight-sensitive applications, particularly in the automotive and aerospace sectors, advanced aluminum alloys and carbon fiber composites present a substitution risk for specialized steel products.
- Energy-Intensive Production:The quenching and tempering process is inherently energy-intensive, exposing producers to volatile electricity prices and increasing compliance costs associated with carbon pricing mechanisms.
Strategic Opportunities
- Offshore Renewable Energy:The expansion of offshore wind farms creates an opportunity for high-strength, corrosion-resistant quenched and tempered steel plates for use in turbine foundations, towers, and monopiles exposed to harsh marine environments.
- Low-Carbon Steel Incentives:The US Inflation Reduction Act (IRA) offers tax credits and incentives for using domestically produced, low-carbon materials in green energy projects, creating a market pull for steel made with cleaner technologies.
- Digital Twin Integration:Implementing digital twin technology in heat treatment facilities allows for real-time process simulation and optimization, improving energy efficiency, ensuring consistent quality, and reducing defects for high-value products.
Industry Challenges
- Green Technology Capital Costs:Transitioning from traditional blast furnaces to lower-emission technologies like electric arc furnaces or hydrogen-based direct reduced iron requires massive capital investment, posing a significant financial challenge.
- Specialized Talent Scarcity:A shortage of metallurgists and process engineers with expertise in advanced heat treatment, alloy design, and digital process control hinders innovation and operational excellence for high-end steel grades.
- Multi-Standard Compliance Burden:Producers must navigate a complex web of certifications, including ISO 9001 for quality management and specific end-use standards for sectors like nuclear power or defense, which involves lengthy and costly validation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quenched and Tempered Steel Market |
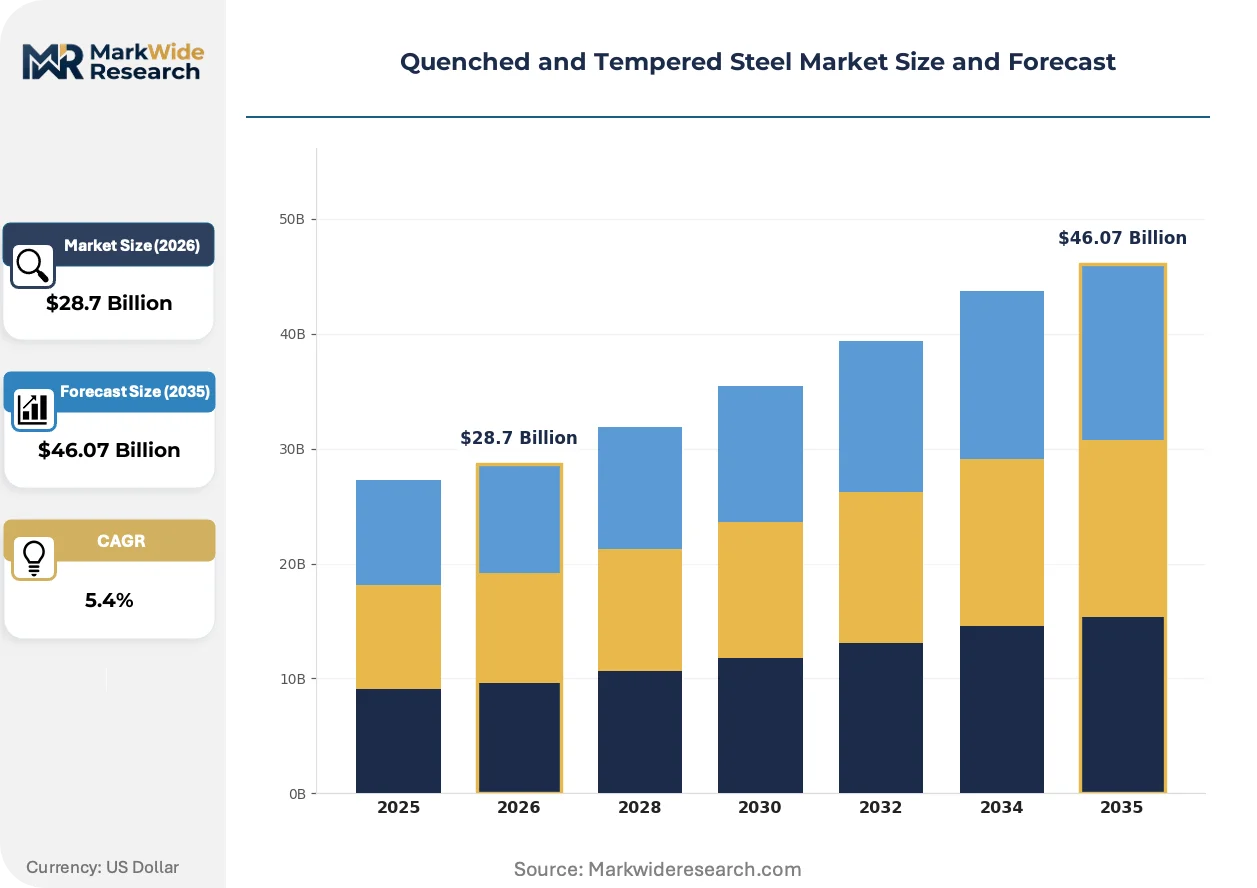
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Steel, Carbon Steel, Stainless Steel, Tool Steel, High Strength Low Alloy Heat Treatment Process: Quenching, Tempering, Normalizing, Annealing, Austempering Application: Construction Equipment, Mining Machinery, Heavy-Duty Vehicles, Pressure Vessels, Earthmoving Tools End User Industry: Oilfield Services, Shipbuilding, Military Equipment, Power Generation, Rail Manufacturing |
| Companies Covered | ThyssenKrupp AG, Nucor Corporation, ArcelorMittal, Kloeckner Metals Corporation, Gerdau S/A, Baosteel Group, SSAB AB, Leeco Steel LLC, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quenched and Tempered Steel Market Strategic Shifts & Innovations
Process innovation is focused on the dual objectives of enhancing material performance while simultaneously reducing the environmental footprint of production. This push influences everything from alloy design to heat treatment methodologies and end-use material specification.
Advanced ultra-high-strength steel (UHSS) grades, developed through precise micro-alloying and digitally controlled heat treatment, offer exceptional strength-to-weight ratios. Sectors such as automotive and defense are rapidly adopting these materials for light-weighting, fuel efficiency, and enhanced ballistic protection. This technological progress is bifurcating the competitive landscape, separating producers of high-margin specialty steels from manufacturers of standard commodity grades.
Environmental regulations, particularly the European Union's Carbon Border Adjustment Mechanism (CBAM), are altering trade dynamics. This policy imposes a tariff on carbon-intensive imports, directly impacting steel produced via conventional blast furnace routes. Steel exporters targeting the EU market are now compelled to accelerate investments in green steel technologies, such as electric arc furnaces, to remain competitive.
Customer evaluation criteria are evolving from an initial price-per-ton focus to a total cost of ownership model that incorporates lifecycle performance and sustainability metrics. This shift empowers engineering and sustainability teams in the purchasing process, especially for heavy equipment and infrastructure projects. The trend is most pronounced in North America and Europe, where regulations and corporate ESG goals drive demand for durable, lower-carbon materials.
Quenched and Tempered Steel Market Segmentation
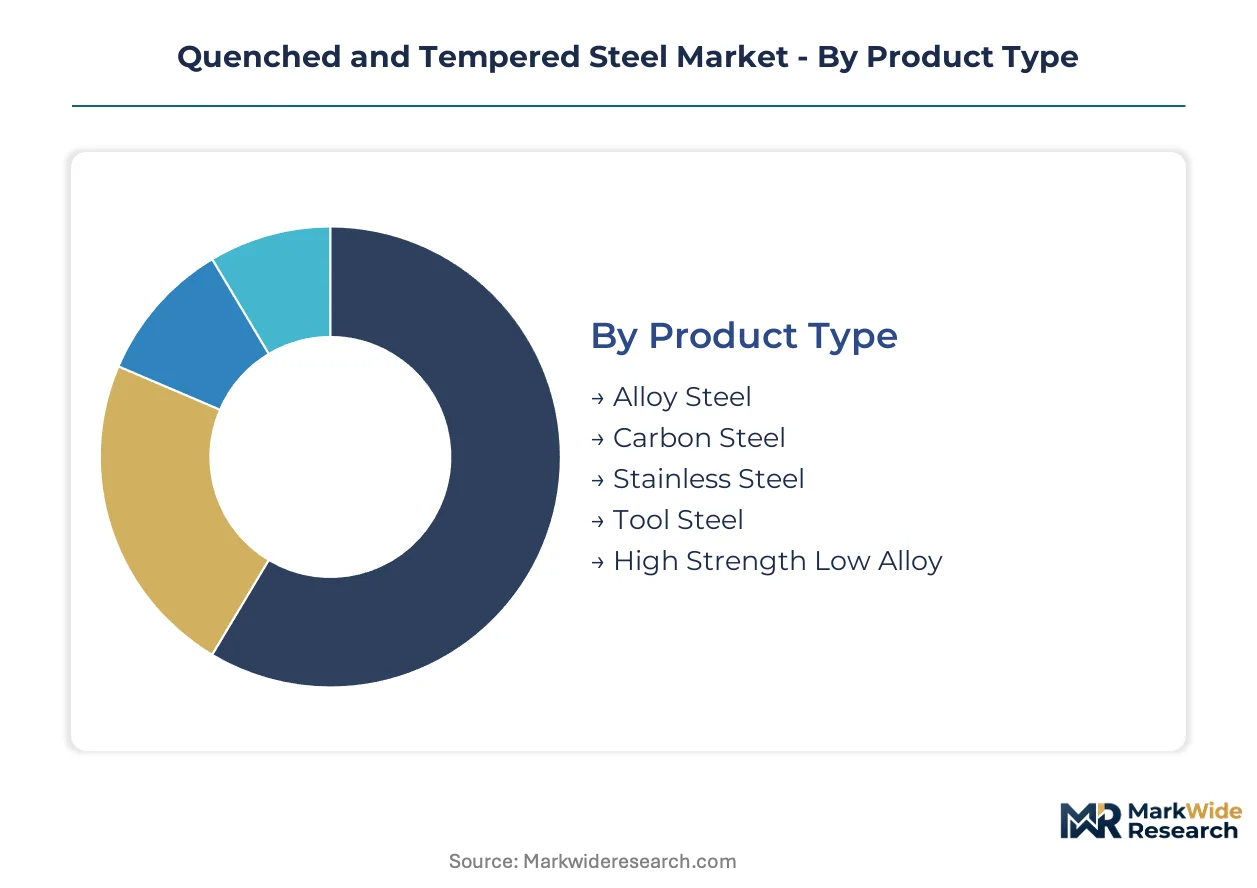
Understanding the segmentation of the quenched and tempered steel market reveals where specific material properties create distinct value propositions. Each segment addresses unique performance requirements, influencing production technologies, supply chain dynamics, and competitive strategies among steel manufacturers.
Product Type:
Substitution pressure from alternative materials challenges specific product types within the quenched and tempered steel market, particularly for weight-sensitive applications.
- Alloy Steel:These steels incorporate elements like manganese, silicon, nickel, and chromium to enhance strength, toughness, and wear resistance beyond standard carbon steel. Demand concentrates in heavy machinery and defense sectors, driven by the need for superior mechanical properties in extreme conditions.
- High Strength Low Alloy:HSLA steels achieve high strength and toughness with smaller additions of alloying elements, offering a good strength-to-weight ratio and weldability. Construction and transportation infrastructure projects, particularly in China, demand these materials for bridges and large structures due to their durability and cost-effectiveness.
- Carbon Steel:This foundational steel type primarily contains carbon as the main alloying element, offering a balance of strength and ductility for general industrial applications.
- Stainless Steel:Known for corrosion resistance due to chromium content, stainless steel finds use in environments requiring hygiene or resistance to chemical degradation.
- Tool Steel:These highly alloyed steels are designed for hardness, abrasion resistance, and dimensional stability at elevated temperatures, essential for manufacturing cutting tools and dies.
Carbon Steel retains volume leadership; High Strength Low Alloy holds the steepest expansion curve.
Heat Treatment Process:
Process selection for heat treatment directly impacts the final material properties and suitability for demanding applications.
- Quenching:This rapid cooling process, typically using water, oil, or polymers, transforms steel's microstructure into martensite, significantly increasing hardness and strength. The process is fundamental for producing high-performance components in construction equipment, requiring precise control to prevent distortion.
- Tempering:Following quenching, tempering involves reheating the steel to a lower temperature, which reduces brittleness while improving toughness and ductility. Critical components in mining machinery benefit from this process, ensuring structural integrity under high impact and stress.
- Normalizing:This heat treatment refines grain structure and homogenizes composition, improving ductility and impact strength for subsequent processing or use.
- Annealing:Annealing softens steel, relieves internal stresses, and enhances machinability, often used as a preparatory step before forming or further heat treatment.
- Austempering:A specialized isothermal heat treatment producing bainitic microstructure, austempering offers excellent toughness, ductility, and fatigue resistance for specific automotive and rail components.
Quenching remains fundamental to achieving desired hardness; Austempering is gaining share fastest for specific high-performance requirements.
Application:
The volume of quenched and tempered steel consumed varies significantly across different application areas.
- Construction Equipment:This segment includes components for excavators, bulldozers, and cranes, where high-strength steels are crucial for wear plates, buckets, and structural frames. Infrastructure development projects in Asia-Pacific countries demand high volumes of these durable materials.
- Mining Machinery:Wear resistance and impact strength are paramount for mining equipment like draglines, shovels, and crushers, making quenched and tempered steels essential for their longevity. Operational efficiency and safety in large-scale mining operations depend on these robust steel components.
- Heavy-Duty Vehicles:Truck frames, chassis components, and suspension systems in commercial vehicles utilize these steels for strength and weight reduction.
- Pressure Vessels:High-strength steels are specified for pressure vessels in chemical processing and energy industries to withstand extreme pressures and temperatures safely.
- Earthmoving Tools:Blades, teeth, and cutting edges for various earthmoving operations require exceptional hardness and abrasion resistance, provided by specialized quenched and tempered grades.
Construction Equipment drives the largest material volume; Earthmoving Tools are expanding most quickly due to wear resistance needs.
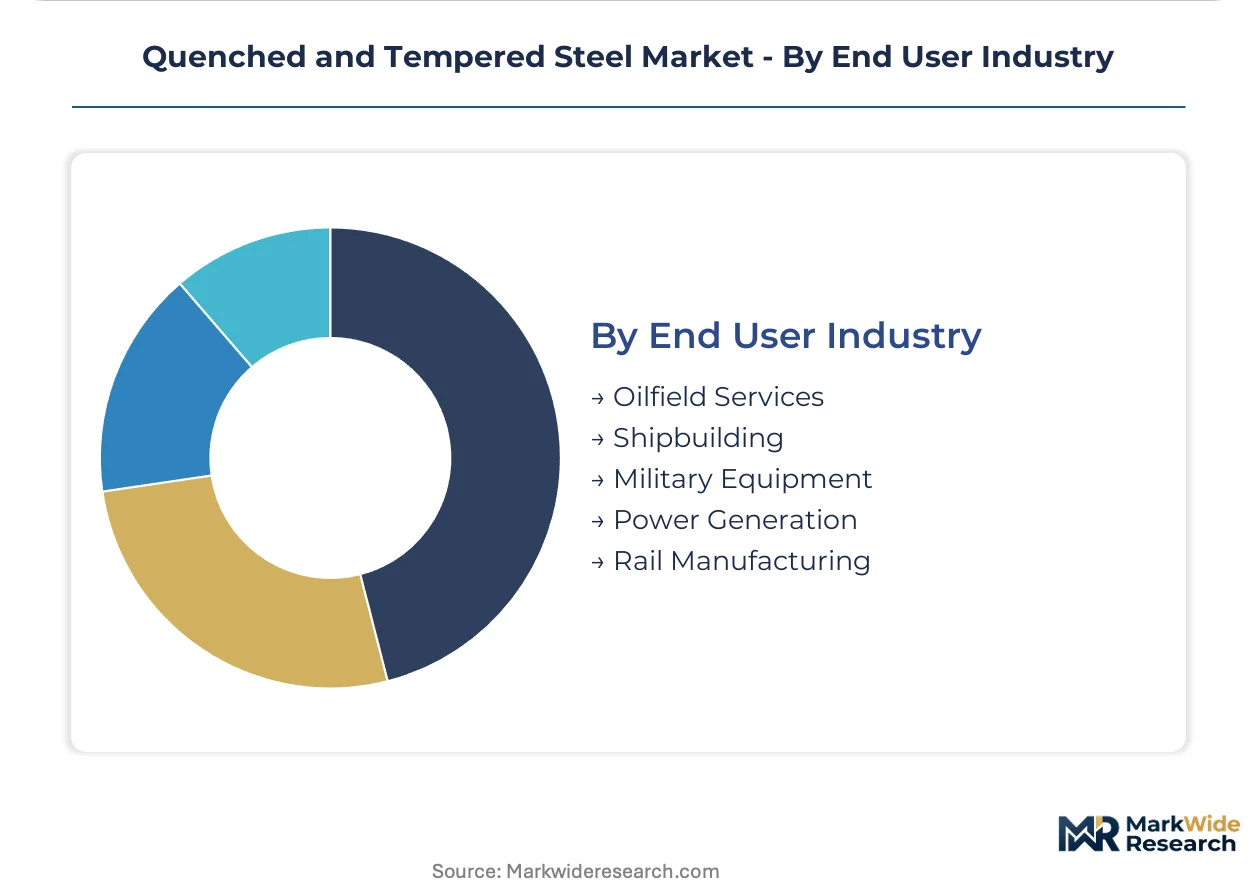
End User Industry:
Regulatory demands and performance criticality define material specifications across end-user industries.
- Power Generation:This sector requires high-strength, creep-resistant steels for turbine components, boiler parts, and structural elements in conventional and nuclear power plants. Compliance with ISO 9001 and specific national standards, such as those from the US EPA, is mandatory for suppliers.
- Military Equipment:Defense applications demand ballistic protection, high fatigue strength, and impact resistance for armored vehicles, naval vessels, and weapon systems. Strict material certifications and performance validation processes govern procurement in this highly specialized segment.
- Oilfield Services:Drilling equipment, pipelines, and offshore platforms utilize quenched and tempered steels for their resistance to corrosion and high-stress environments.
- Shipbuilding:High-strength steels reduce vessel weight while maintaining structural integrity, crucial for naval ships, cargo carriers, and offshore structures.
- Rail Manufacturing:Rolling stock components, such as axles and wheels, along with rail tracks, require durable steels to withstand heavy loads and continuous wear.
Oilfield Services represent a consistent demand base; Power Generation applications are climbing the fastest, driven by infrastructure projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global consumption patterns for quenched and tempered steel exhibit a significant differential, with Asian nations prioritizing volume for large-scale infrastructure while developed economies increasingly focus on high-specification materials for specialized applications. This bifurcation influences regional production capacities and technological investments across continents. Regulatory frameworks also drive distinct market trajectories in different geographies.
China
Large-scale infrastructure development and a booming manufacturing sector continue to drive substantial demand for high-strength steels in China. The nation's dual carbon goals are compelling steel producers to adopt lower-emission technologies, impacting investment decisions. Industrial clusters in the Yangtze River Delta actively integrate advanced steel production with heavy machinery manufacturing.
United States
Demand for quenched and tempered steel in the United States is strong from construction equipment and heavy-duty vehicles, requiring durable and high-performance materials. The US Inflation Reduction Act (IRA) provides incentives for domestically produced, low-carbon materials, fostering cleaner steelmaking processes. Steel mills in the Midwest, particularly around the Great Lakes region, are investing in electric arc furnace technology.
Germany
Germany's advanced manufacturing sector, especially in automotive and industrial machinery, requires high-specification quenched and tempered steels for critical components. The EU Green Deal mandates stringent emission reductions, pushing German steelmakers towards sustainable production methods. The Ruhr Valley remains a significant hub for steel production, focusing on process innovation and quality standards.
India
Rapid urbanization and ambitious infrastructure projects, including new roads and bridges, significantly boost the volume demand for high-strength low alloy steels in India. Government initiatives supporting domestic manufacturing, such as the PLI scheme for specialty steel, encourage local production and technological upgrades. Major steel production centers like Jamshedpur and Bhilai are expanding capacities to meet national requirements.
Japan
Japan's mature industrial base demands high-quality, specialized quenched and tempered steels for advanced machinery, shipbuilding, and precision engineering. Strict JIS standards ensure material performance and reliability across critical applications. Steel manufacturers in regions like Hiroshima and Kitakyushu are leaders in developing advanced ultra-high-strength steel grades.
Quenched and Tempered Steel Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a distinct competitive hierarchy within the quenched and tempered steel market. This tiered structure reflects varying capabilities in producing high-specification alloy steels versus commodity-grade carbon steel. Companies primarily engage in strategic partnerships to enhance technological capabilities and invest in greener production technologies to meet evolving regulatory demands.
On the premium-tier vector, SSAB AB exemplifies specialized high-strength steel production for demanding applications, commanding premium pricing. Nucor Corporation, a significant North American player, leverages its large-scale, efficient production of carbon and alloy steels to serve a broad industrial base. ArcelorMittal, with its extensive global manufacturing footprint, occupies a position across both specialized and commodity segments through its diverse product portfolio.
| Leading Market Players |
|---|
| ThyssenKrupp AG |
| Nucor Corporation |
| ArcelorMittal |
| Kloeckner Metals Corporation |
| Gerdau S/A |
| Baosteel Group |
| SSAB AB |
| Leeco Steel LLC |
| Nippon Steel Corporation |
| Others |
Cost & Logistics Intelligence
Advanced aluminum alloys replacing steel in weight-sensitive automotive applications simultaneously reshapes supply geography and pricing economics for high-strength steel producers. This dynamic necessitates strategic adjustments across the value chain, focusing on performance differentiation and cost management.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for high-specification quenched and tempered steels, particularly for major infrastructure projects and industrial OEMs. Price differentiation stems from material quality grades, specific certifications like ISO 9001 for power generation, and customization of alloy composition. Pricing pressure stems from the volatile costs of critical alloying elements and the significant capital investment required for greener production technologies. Buyers in military equipment and power generation exhibit lower price sensitivity due to stringent performance and safety requirements, while general construction equipment manufacturers are more price-sensitive.
Supply Chain Analysis
Port congestion in key Asian trade lanes impacts the inbound logistics costs for raw materials like iron ore and alloying elements, influencing global steel production. Geographic supply concentration for high-strength steel centers in China for volume and Germany for specialized grades. The market draws from critical alloying elements such as molybdenum and nickel, creating a structural risk due to geopolitical factors and market speculation. Distribution of quenched and tempered steel runs primarily through direct sales to large industrial OEMs and project-based supply for infrastructure developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The increasing buyer focus on sustainability metrics and lifecycle performance, driven by regulations like the EU Green Deal, is shifting power dynamics among purchasers of quenched and tempered steel.
For Market Incumbents:Shield core market share by accelerating investments in lower-emission steelmaking technologies, such as electric arc furnaces, to comply with evolving regulations like the EU CBAM. Diversify the sourcing of critical alloying elements to mitigate price volatility and supply chain disruptions. Develop advanced ultra-high-strength steel grades through R&D to counter material substitution threats from aluminum composites in weight-sensitive applications.
For New Entrants and Emerging Players:Anchor in niche, high-performance segments like offshore renewable energy, where demand for corrosion-resistant, high-strength steels is expanding rapidly. Target geographies offering incentives for green materials, such as the US Inflation Reduction Act, to establish a competitive foothold. A go-to-market strategy focused on digitally optimized production processes ensures consistent quality and energy efficiency for specialized, high-value products.
For Investors and Strategic Acquirers:The EU Green Deal reshapes the acquisition landscape, favoring companies with proven sustainability credentials and advanced material science capabilities. Focus on long-term viability by targeting specialists in high-strength, low-carbon steel production or those possessing proprietary heat treatment technologies. Increased M&A activity among traditional steelmakers acquiring green tech startups or advanced material science firms is the signal to watch over the next decade.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Accelerates compliance with carbon reduction mandates like the EU Green Deal. |
| Advanced Alloy R&D | Develops superior strength-to-weight ratio steels for demanding applications. |
| Digital Twin Integration | Optimizes heat treatment processes, reducing energy consumption and defects. |
| Long-term Offtake Agreements | Secures demand for high-specification steels in critical infrastructure projects. |
| Capacity Expansion (EAF) | Increases production of lower-carbon steel to capitalize on IRA incentives. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings of this study. This involved extensive discussions with metallurgists, process engineers, procurement managers in construction and mining, and sustainability officers. Secondary data sources included government environmental agency reports, corporate sustainability disclosures, and academic research on advanced materials, triangulating insights through both bottom-up and top-down approaches.
Sensitivity analysis forms the foundation of the quantitative modeling framework, projecting market dynamics across the analysis window. The study modeled segmentation dimensions including product type, heat treatment process, application, end-user industry, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends, projected demand drivers, and anticipated technological adoption rates, incorporating industry-specific inputs like infrastructure spending forecasts and alloying element price indices.
Decision-makers should treat outputs as directional under base assumptions of geopolitical stability for raw material supply and consistent regulatory enforcement of carbon reduction goals; material deviation would warrant model refresh. Unforeseen shifts in material science, rapid acceleration of substitution materials, or severe economic downturns represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Green Steel Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Cobalt Alloy Powder Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Nitinol Market
Advanced Alloys
Titanium Aluminide Market