
 Nickel Alloy Market | 2026-2036
Nickel Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel Alloy Market Analysis
Aftermarket service revenue for legacy turbine component refurbishment is narrowing as OEMs push captive repair networks. VDM Metals Group leverages its German melting capacity to dominate specialty nickel scrap recycling. Precision Castparts Corp anchors North American aerospace casting demand through vertical control over vacuum induction melting. Haynes International differentiates via cobalt-nickel formulations for ultra-high-temperature corrosion environments.
Nickel alloys are iron-nickel or nickel-chromium based metallic materials engineered to retain mechanical strength above 600°C, typically produced through vacuum arc remelting or electroslag remelting to achieve oxygen levels below 50 ppm for critical rotating components. Wrought alloys command the largest volume pool due to established forging infrastructure serving jet engine disc applications, while cast alloys capture premium margins in single-crystal turbine blade production where directional solidification yields grain structures aligned parallel to centrifugal stress vectors. Composite alloys represent the fastest-growing product category as additive manufacturing enables functionally graded nickel-titanium structures for heat exchanger headers.
REACH registration requirements in Europe mandate full substance dossiers for nickel alloy powders used in additive manufacturing, raising compliance costs for non-European exporters. The FAA and EASA airworthiness directives on engine disk life limits directly govern replacement demand cycles for nickel superalloy components. China's SAMR enforces GB/T standards for pressure vessel nickel alloys in hydrogen service, creating certification barriers for uncertified foreign mills. Stakeholders must monitor divergence between EU F-Gas Regulation phase-down schedules and US EPA hydrofluorocarbon restrictions, as mismatched timelines could strand nickel alloy heat exchanger inventories in transatlantic chemical processing projects.
Market Dynamics
Heat-resistant superalloy demand from aerospace engine manufacturers is concentrating procurement power among vertically integrated OEMs, while China's GB standards and dual carbon goals force smelter consolidation that tightens primary nickel feedstock availability for specialty alloy producers.
Growth Catalysts
- Pressure vessel certification:China's SAMR enforces GB/T standards for hydrogen service applications, creating mandatory replacement cycles for uncertified foreign mill inventories in energy infrastructure projects.
- Directional solidification:Single-crystal turbine blade production captures premium margins through grain structures aligned parallel to centrifugal stress vectors in jet engine hot sections.
- India's chemical corridor:Demand concentrates in Gujarat's processing cluster around Dahej and Mundra, where nickel alloy heat exchanger replacement cycles accelerate under corrosive process conditions.
Market Restraints
- Scrap supply concentration:German melting capacity dominates specialty nickel scrap recycling, creating geographic chokepoints for secondary feedstock access.
- REACH compliance friction:Full substance dossier requirements for nickel alloy powders used in additive manufacturing raise entry costs for non-European exporters.
- Ceramic matrix substitution:Silicon carbide fiber-reinforced composites displace nickel superalloys in static hot-section components above 1100°C operational thresholds.
Strategic Opportunities
- Additive manufacturing convergence:Functionally graded nickel-titanium structures for heat exchanger headers emerge as laser powder bed fusion enables topology-optimized geometries impossible through forging.
- EU F-Gas phase-down:Mismatched timelines with US EPA hydrofluorocarbon restrictions strand nickel alloy heat exchanger inventories, creating arbitrage opportunities for certified transatlantic suppliers.
- Legacy turbine refurbishment:Captive repair networks narrow aftermarket service revenue, opening white space for independent component restoration specialists with FAA/EASA DER approvals.
Industry Challenges
- Vacuum metallurgy skill scarcity:Operators capable of maintaining oxygen levels below 50 ppm in vacuum arc remelting operations remain concentrated among retiring workforce cohorts.
- Dual certification timelines:Simultaneous FAA and EASA airworthiness directive compliance for engine disk life limits extends qualification periods for new alloy formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel Alloy Market |
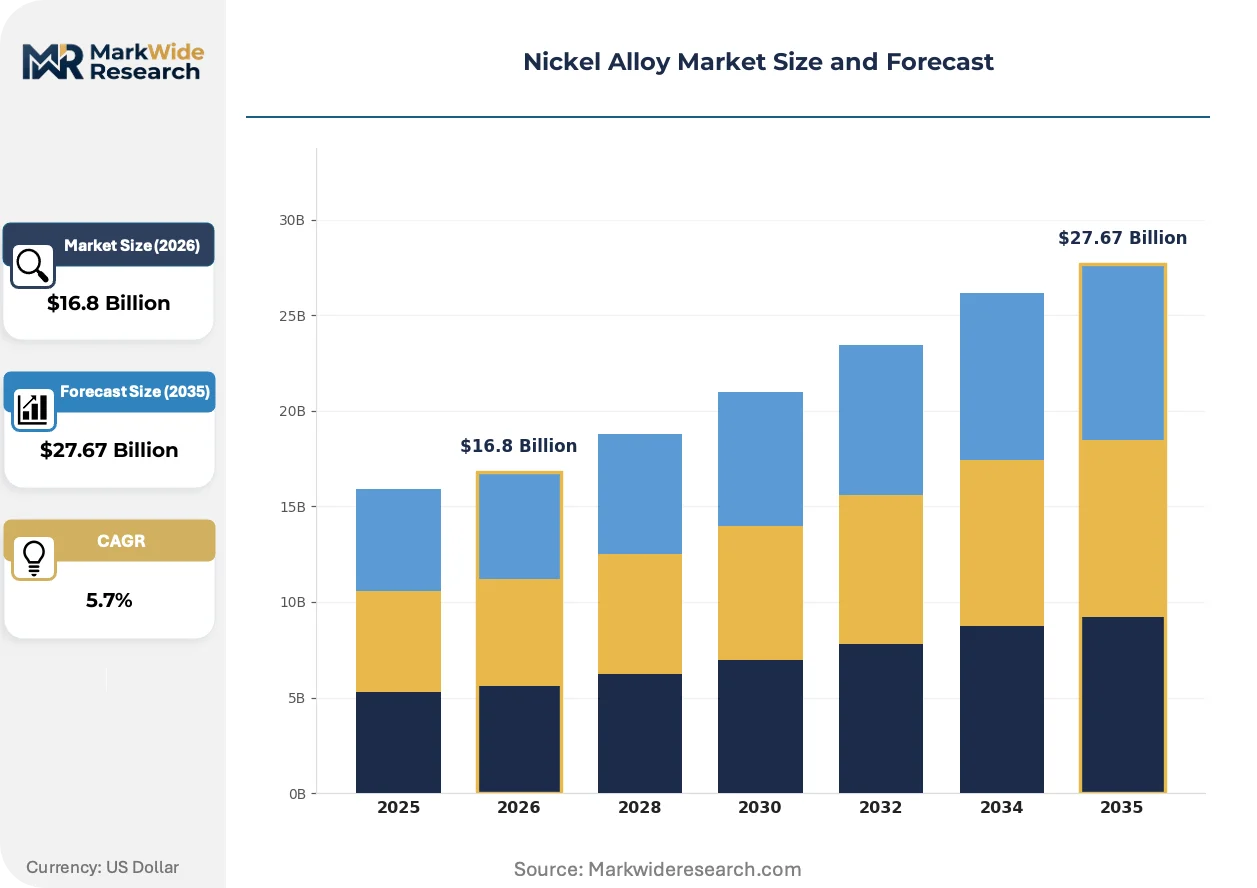
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrought Alloys, Cast Alloys, Composite Alloys, Hybrid Alloys End User: Aerospace, Chemical Processing, Oil & Gas, Marine Form: Sheets, Bars, Tubes, Plates Application: Heat Exchangers, Pressure Vessels, Turbine Components, Fasteners |
| Companies Covered | VDM Metals Group, Precision Castparts Corp, Allegheny Technologies Incorporated, Rolled Alloys, Thyssenkrupp AG, Haynes International, Aperam, Carpenter Technology Corporation, Sandvik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel Alloy Market Emerging Trajectories
Process metallurgy and regulatory compliance are converging to reshape how nickel alloys move from melt to finished component, with oxygen control, substance registration, and procurement centralization defining competitive differentiation.
Electroslag remelting is hybridizing with plasma arc cold hearth techniques to produce ingots with superior cleanliness for rotating aerospace components. Tier-one engine manufacturers specify these hybrid-processed alloys for critical disc applications. The technology is compressing acceptable inclusion size thresholds while extending lead times for qualified suppliers.
Europe's REACH registration requirements now mandate full substance dossiers for nickel alloy powders, forcing non-European exporters to establish EU-based only representatives or forfeit additive manufacturing feedstock markets. Industrial consequence includes documentation costs that favor incumbent powder producers with existing registration portfolios. Asian exporters are responding by acquiring European toll processing partnerships to maintain market access.
Aftermarket service unbundling is accelerating as OEMs push captive repair networks for legacy turbine components, displacing independent refurbishment specialists from high-margin hot-section work. Independent shops are consolidating DER approvals and specialized welding capabilities to defend position in niche blade and vane restoration. This shift concentrates most visibly in North American MRO corridors serving aging CFM56 and V2500 fleets.
Nickel Alloy Market Segmentation
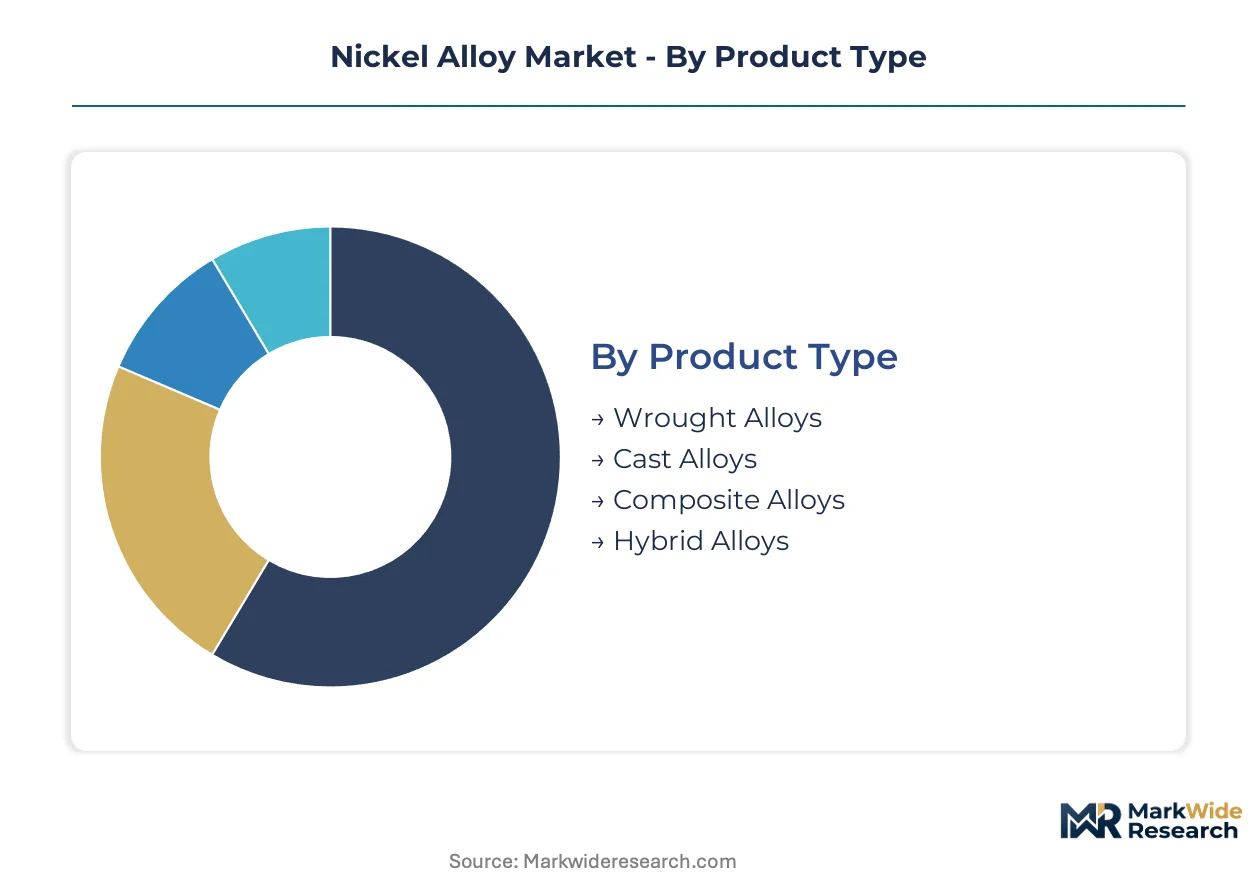
Segmentation in nickel alloys tracks how metallurgical form, thermal performance requirements, and fabrication constraints split demand across radically different value chains. Aerospace procurement specifications diverge sharply from chemical plant maintenance schedules, creating distinct competitive arenas with incompatible qualification protocols.
Product Type:
Cost tier differentiation separates commodity-volume segments from precision-metallurgy premiums, with oxygen content and grain structure defining price stratification.
- Wrought Alloys:Iron-nickel or nickel-chromium formulations produced through vacuum arc remelting achieve oxygen levels below 50 ppm for rotating disc applications. Demand concentrates in jet engine forging supply chains serving OEM disc manufacturers, where established infrastructure locks in volume dominance despite longer lead times.
- Cast Alloys:Directional solidification yields single-crystal grain structures aligned parallel to centrifugal stress vectors in turbine blade production. Premium margins attach to hot-section components where grain boundary elimination extends creep resistance, with procurement power concentrating among vertically integrated engine manufacturers.
- Composite Alloys:Functionally graded nickel-titanium structures enabled by additive manufacturing for heat exchanger headers.
- Hybrid Alloys:Electroslag remelting hybridized with plasma arc cold hearth techniques for superior ingot cleanliness.
Wrought alloys command the established base. The steepest expansion runs through composite alloys.
End User:
Application-specific certification requirements create divergent procurement patterns across industries with incompatible safety margins.
- Aerospace:FAA and EASA airworthiness directives on engine disk life limits govern replacement demand cycles for superalloy components. Heat-resistant formulations concentrate procurement among OEMs expanding orders for single-crystal turbine blades, with captive repair networks narrowing aftermarket access.
- Chemical Processing:Corrosive process conditions accelerate heat exchanger replacement cycles in India's Gujarat corridor around Dahej and Mundra. Nickel-chromium-molybdenum specifications dominate where sulfuric acid exposure exceeds 200°C operational thresholds.
- Oil & Gas:Hydrogen service pressure vessel requirements under China's GB/T standards drive certified mill procurement.
- Marine:Seawater corrosion resistance specifications for propulsion shafting and desalination plant tubing.
Chemical processing anchors volume demand. Aerospace captures margin concentration.
Form:
Processing topology determines downstream fabrication economics and scrap recovery rates.
- Sheets:Cold-rolled precision gauges for heat exchanger plate stacks and chemical reactor cladding, with thickness tolerances dictating welding protocol selection.
- Bars:Round and hexagonal stock for fastener head forging and valve stem machining, commanding premium surface finish specifications.
- Tubes:Seamless extrusions for high-pressure hydrogen service and offshore riser applications.
- Plates:Heavy-gauge hot-rolled product for pressure vessel shell construction and structural supports.
Sheets generate the broadest application footprint. Bars extract the highest per-kilogram value.
Application:
Functional performance requirements stratify demand by thermal cycling intensity and pressure containment duty.
- Heat Exchangers:Plate-and-frame and shell-and-tube configurations in chemical processing and power generation. EU F-Gas Regulation phase-down schedules mismatched with US EPA hydrofluorocarbon restrictions create inventory arbitrage opportunities for certified transatlantic suppliers.
- Pressure Vessels:China's SAMR enforces GB/T standards for hydrogen service applications, creating mandatory replacement cycles for uncertified foreign mill inventories in energy infrastructure projects.
- Turbine Components:Rotating discs and static vanes in aerospace and industrial gas turbines.
- Fasteners:High-temperature bolting for exhaust manifolds and reactor closures.
Pressure vessels concentrate regulatory-driven replacement. Heat exchangers present the most complex supply chain arbitrage dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's chemical processing corridor exhibit acute price sensitivity on standard-grade heat exchanger sheet, while aerospace OEMs in Germany and the United States accept substantial premiums for vacuum-remelted superalloys with sub-50 ppm oxygen certification.
United States
FAA airworthiness directives on engine disk life limits drive replacement demand cycles for nickel superalloy components. The EPA maintains hydrofluorocarbon restrictions that diverge from EU F-Gas Regulation timelines. Precision Castparts Corp anchors aerospace casting demand through captive vacuum induction melting capacity in the Pacific Northwest.
Germany
VDM Metals Group leverages domestic melting capacity to dominate specialty nickel scrap recycling for aerospace and chemical processing feedstock. REACH registration requirements mandate full substance dossiers for nickel alloy powders used in additive manufacturing. The Ruhr industrial cluster concentrates vacuum metallurgy expertise for rotating component applications.
China
GB/T standards for pressure vessel nickel alloys in hydrogen service create mandatory replacement cycles for uncertified foreign mill inventories. SAMR enforcement tightens emissions benchmarks for smelters under dual carbon goals. The Yangtze River Delta hosts expanding aerospace engine manufacturing orders for heat-resistant superalloys.
India
Corrosive process conditions accelerate heat exchanger replacement cycles in Gujarat's chemical processing corridor around Dahej and Mundra. BIS certification requirements pressure domestic fabricators to source certified mill product. The Dahej industrial zone concentrates demand for nickel-chromium-molybdenum alloys in sulfuric acid service above 200°C.
Japan
METI industrial policy supports domestic superalloy capacity for aerospace and power generation turbine applications. JIS standards govern nickel alloy specifications for nuclear pressure vessel and fastener applications. The Chubu region around Nagoya maintains precision forging infrastructure for jet engine disc supply chains.
Nickel Alloy Market Vendor Landscape
Integrated primary producers and specialized secondary refiners split the market between captive supply security and scrap-fed flexibility. The vendor base concentrates around vacuum metallurgy capabilities with oxygen control below 50 ppm, creating qualification barriers for new entrants. Two strategic archetypes dominate: German-based scrap recyclers with closed-loop melting networks, and North American aerospace casters with backward integration into vacuum induction melting. Competitive moves center on DER approval accumulation for aftermarket turbine refurbishment and toll processing partnerships to bypass REACH registration barriers for Asian exporters.
Within the integrated primary producer tier, Precision Castparts Corp and Carpenter Technology Corporation exemplify North American aerospace casting dominance through captive vacuum metallurgy capacity. VDM Metals Group anchors the European scrap recycling archetype with German melting infrastructure. Haynes International occupies a position among cobalt-nickel formulation specialists serving ultra-high-temperature corrosion environments. These three represent the strategic poles around which competitive positioning organizes: captive aerospace supply security, secondary feedstock circularity, and high-performance alloy differentiation.
| Leading Market Players |
|---|
| VDM Metals Group |
| Precision Castparts Corp |
| Allegheny Technologies Incorporated |
| Rolled Alloys |
| Thyssenkrupp AG |
| Haynes International |
| Aperam |
| Carpenter Technology Corporation |
| Sandvik |
| Others |
Supply Flow & Price Mechanics
Ruhr industrial cluster vacuum metallurgy capacity shapes downstream pricing power for aerospace-grade nickel alloys, with German melting infrastructure commanding premium spreads over Asian spot markets for oxygen-controlled remelted product. China's Yangtze River Delta smelter consolidation under dual carbon goals tightens primary nickel feedstock availability, forcing specialty alloy producers to absorb higher input costs or pass through to chemical processing buyers in India's Gujarat corridor.
Pricing Analysis
Aftermarket turbine component refurbishment contracts anchor lifetime value capture for incumbent suppliers, with OEM captive repair networks extracting service premiums through DER-approved restoration workflows. Pricing stratifies across vacuum-remelted superalloy certification tiers, with sub-50 ppm oxygen specifications commanding substantial markups over standard-grade chemical processing sheet. Cost compression in standard-grade heat exchanger material intensifies as Indian fabricators consolidate procurement volumes around Dahej and Mundra clusters. Aerospace OEMs in Germany and the United States exhibit minimal price sensitivity for qualified rotating disc alloys, while chemical plant maintenance buyers in India negotiate aggressively on replacement cycle economics.
Supply Chain Analysis
Primary nickel feedstock draws from Indonesian laterite operations, Russian Norilsk sulfide output, and Philippine intermediate ore shipments, with German and Chinese smelters dominating intermediate nickel product conversion. Vacuum arc remelting electrodes, electroslag remelting fluxes, and specialty scrap nickel streams constitute critical input dependencies for qualified alloy production. Single-source vulnerability concentrates in German specialty scrap recycling capacity controlled by VDM Metals Group melting networks. Distribution runs through mill-direct contracts for aerospace OEMs and distributor-stocked inventory for chemical processing maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among vertically integrated aerospace engine OEMs expanding captive repair networks, fragmenting independent aftermarket service revenue pools and forcing supplier consolidation around certification moats.
For Market Incumbents: Build regulatory certification moats by accumulating simultaneous FAA and EASA DER approvals for engine disk life limit compliance, compressing qualification timelines for new alloy formulations. Add vacuum induction melting capacity in the Pacific Northwest to anchor North American aerospace casting demand against Precision Castparts Corp's backward integration. Ceramic matrix composite substitution in static hot-section components above 1100°C threatens nickel superalloy volume; respond with cobalt-nickel formulation R&D for ultra-high-temperature corrosion environments where composites fail. For New Entrants and Emerging Players: Independent component restoration specialists with FAA/EASA DER approvals represent the most penetrable entry point as OEM captive repair networks displace incumbents from high-margin hot-section work. India's Gujarat chemical processing corridor around Dahej and Mundra offers white-space demand for nickel-chromium-molybdenum alloy heat exchanger replacement cycles under corrosive sulfuric acid conditions above 200°C. Pursue toll processing partnerships with European powder producers to bypass REACH registration barriers for additive manufacturing feedstock markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors German-based scrap recyclers with closed-loop melting networks and Asian toll processing partnerships, as circular feedstock access becomes a strategic differentiator under tightening primary nickel availability. Long-term viability over a 5-10 year window rests on vacuum metallurgy skill retention as retiring workforce cohorts concentrate operational expertise. Acquisition target archetypes include independent DER-approved refurbishment shops and European toll processors serving REACH compliance needs. Watch divergence between EU F-Gas Regulation phase-down schedules and US EPA hydrofluorocarbon restrictions as inventory arbitrage inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Induction Melting | Captive metallurgy capacity locks in aerospace OEM qualification timelines against German scrap-fed competitors. |
| DER Approval Accumulation for Aftermarket Refurbishment | FAA and EASA certifications defend position as OEM captive networks narrow independent service access. |
| European Toll Processing Partnership | REACH compliance via EU-based only representatives preserves Asian exporter access to additive manufacturing powder markets. |
| Cobalt-Nickel Formulation R&D Investment | Ultra-high-temperature corrosion resistance extends addressable market beyond ceramic matrix composite displacement thresholds. |
| Scrap Recycling Network Expansion | Secondary feedstock circularity hedges primary nickel price volatility under Chinese smelter consolidation. |
Methodological Framework
Operator-level perspectives from vacuum metallurgy plant managers, aerospace OEM procurement directors, chemical processing maintenance engineers, and specialty alloy distribution channel partners anchored the qualitative base. Primary interview insights combined with customs and trade data, SEC 10-K filings from publicly traded alloy producers, GB/T and SAMR regulatory documentation, and REACH registration databases for secondary validation. Bottom-up alloy shipment volume estimates triangulated against top-down end-use industry consumption models across wrought, cast, composite, and hybrid product categories.
Scenario-bracketing around Chinese dual carbon policy enforcement intensity, ceramic matrix composite substitution pace, and REACH registration cost pass-through informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include product metallurgical form, thermal performance grade tier, end-use industry application, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year volume estimates, with aerospace engine order backlogs and hydrogen infrastructure project pipelines serving as industry-specific forecast inputs.
Practitioners should monitor SAMR enforcement actions on GB/T pressure vessel certification, FAA/EASA airworthiness directive revision schedules, and Indonesian nickel export policy shifts for early signals warranting forecast revision. Cross-checking against IEA hydrogen infrastructure deployment benchmarks and aerospace OEM disclosed order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Aramid Prepreg Market