
 Lithium Nitride Market | 2026-2036
Lithium Nitride Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Nitride Market Insights
Aftermarket battery recycling revenue is rewriting margin capture across the lithium nitride value chain. Albemarle Corporation leverages its Chilean brine dominance to secure upstream lithium feedstock for nitride precursors. Ganfeng Lithium anchors Chinese vertical integration from spodumene conversion through high-purity nitride output. Tianqi Lithium competes via Australian hard-rock offtake agreements that sustain its chemical processing scale.
Lithium nitride (Li3N) is an ionic compound synthesized through direct reaction of metallic lithium with nitrogen gas at elevated temperatures, typically exhibiting a reddish-brown crystalline structure with a melting point near 813°C; it serves primarily as a solid-state electrolyte precursor and hydrogen storage medium in advanced energy systems. High-purity lithium nitride dominates current revenue pools due to stringent battery-grade specifications, while lithium nitride powder occupies the fastest-expanding form category as dry electrode coating techniques gain traction. The catalysts application segment sustains stable offtake from ammonia synthesis research, though battery components now attract the majority of new capital allocation.
FDA oversight of medical device batteries, EPA hazardous material handling rules for reactive lithium compounds, and China's GB standards for battery material purity collectively elevate compliance costs while filtering subscale producers from qualified supplier lists. The EU Battery Regulation's carbon footprint disclosure requirements are forcing importers to document upstream nitride processing emissions. Stakeholders must monitor which purity certifications Korean battery makers adopt as gating criteria for their solid-state supply chains.
Market Dynamics
Solid-state battery chemistry is forcing lithium nitride producers to recalibrate purity specifications and thermal processing protocols. South Korean cathode manufacturers now gate supplier qualification on sub-ppm contamination thresholds that exceed legacy industrial-grade standards.
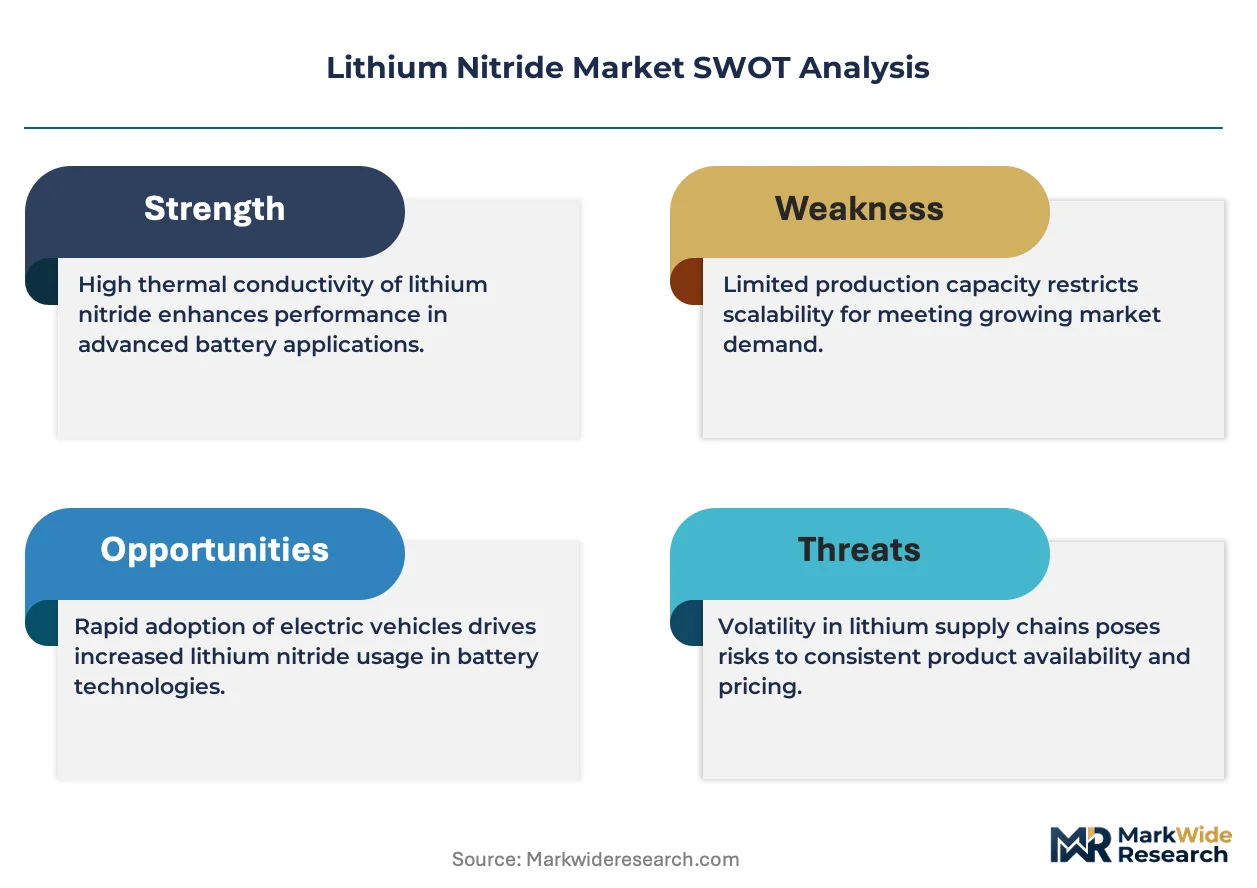
Growth Catalysts
- NMPA battery material standards:China's purity mandates for solid-state electrolyte precursors are filtering qualified suppliers and concentrating offtake among certified producers.
- Hydrogen storage R&D:Ammonia synthesis catalyst research programs in German and Japanese laboratories are sustaining baseline demand for high-surface-area lithium nitride powders.
- Dry electrode coating:Battery manufacturers are adopting solvent-free electrode production techniques that favor powdered nitride precursors over slurry-based alternatives.
Market Restraints
- Metallic lithium price volatility:Feedstock cost swings tied to South American brine and Australian spodumene contract negotiations compress nitride processor margins unpredictably.
- East Asian supply concentration:Over 70 percent of high-purity lithium nitride output originates from manufacturing clusters within 200 kilometers of Seoul and Shanghai, creating single-point vulnerability.
- Moisture sensitivity:Pyrophoric reactivity requiring argon-atmosphere handling throughout synthesis and packaging elevates capital intensity above conventional lithium salt production.
Strategic Opportunities
- EU Battery Regulation carbon accounting:Importers documenting upstream nitride processing emissions gain preferential access to European OEM qualification lists.
- India PLI scheme:Domestic cell manufacturing incentives are attracting nitride precursor investments to Gujarat and Tamil Nadu industrial corridors.
- Sulfide-nitride hybrid electrolytes:Converging solid-state architectures combining Li3N with argyrodite sulfides are opening formulation partnerships between Korean battery makers and specialty chemical suppliers.
Industry Challenges
- Battery-grade certification timelines:Korean cathode producers require 18-24 month qualification cycles for new nitride suppliers, freezing out mid-scale entrants.
- Argon recovery infrastructure:Inert atmosphere synthesis demands closed-loop gas recycling systems that strain capex budgets at sub-500-ton annual scales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Nitride Market |
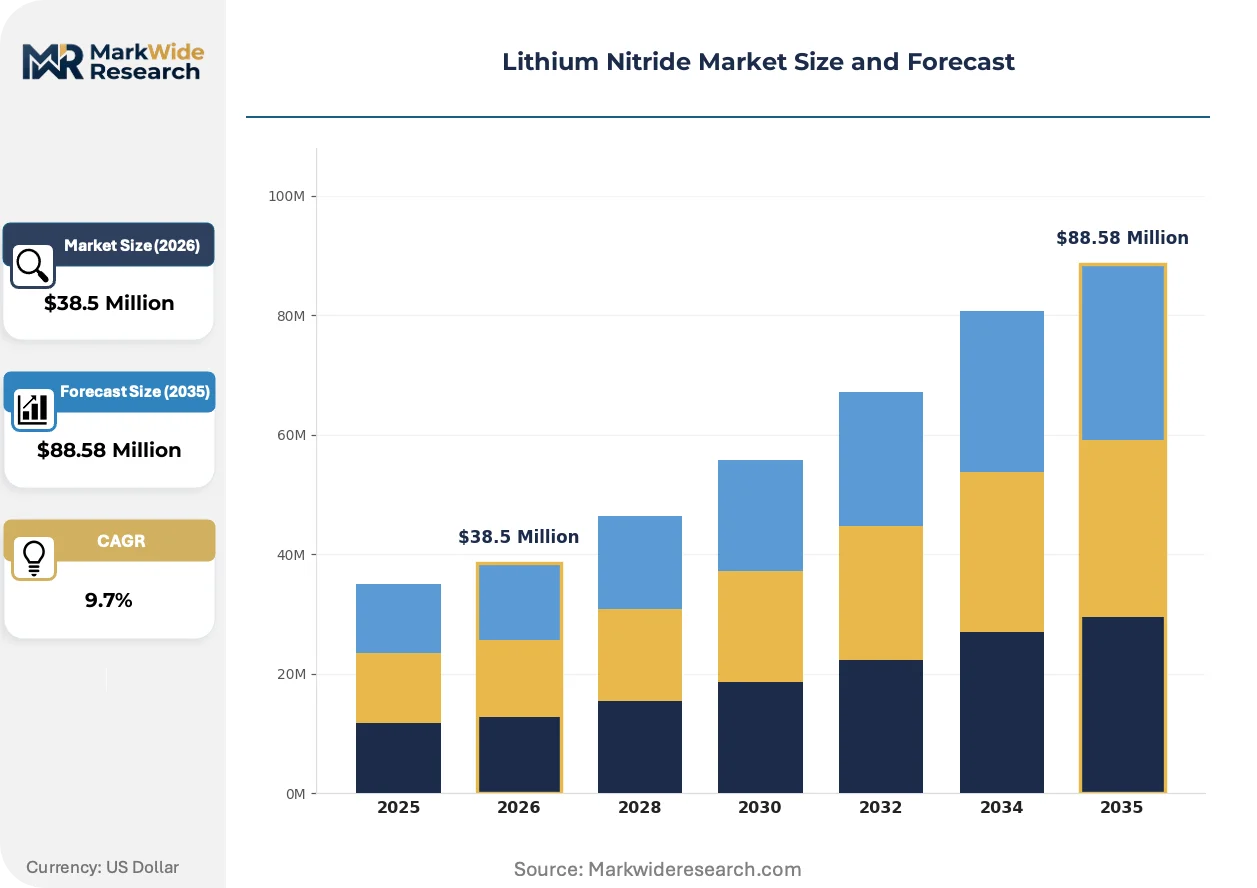
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $88.58 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity Lithium Nitride, Low-Purity Lithium Nitride, Lithium Nitride Powder, Lithium Nitride Granules End Use Industry: Aerospace, Electronics, Automotive, Energy Storage Application: Battery Components, Catalysts, Fuel Cells, Thermal Conductors Form: Powder, Solid, Liquid, Suspension |
| Companies Covered | Albemarle Corporation, Livent Corporation, Ganfeng Lithium, SQM, Tianqi Lithium, BASF, Wuhan Easpring Material Technology, Zhejiang Headway Lithium Battery Technology, Chengxin Lithium Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Nitride Market Trends and Innovations
Synthesis and application technologies for lithium nitride are diverging along purity-grade lines, with battery-grade specifications hardening while industrial catalyst applications stagnate. Process innovation now centers on contamination control rather than yield optimization.
Hybrid solid-state electrolyte formulations are hybridizing lithium nitride with sulfide and halide chemistries to balance ionic conductivity against moisture stability. Samsung SDI and SK On are piloting these architectures in 2025-2026 vehicle platform validations. This convergence is compressing the addressable market for single-chemistry nitride suppliers while rewarding multi-material formulation capabilities.
REACH substance registration requirements for lithium compounds are forcing European importers to document full supply chain toxicity profiles and safe-use guidance. The regulation is elevating compliance costs for traders while pushing battery makers toward vertically integrated nitride sourcing. German automotive OEMs are responding by auditing Chilean and Australian upstream lithium operations for REACH-aligned substance data.
Long-term offtake contracting is displacing spot market purchasing among Korean cathode producers seeking supply security for solid-state pilot lines. Direct procurement relationships with nitride synthesizers are replacing multi-tier distributor networks. This pattern is most visible in Gwangju and Ochang industrial complexes, where POSCO Chemical and EcoPro BM have established preferred supplier frameworks bypassing traditional chemical traders.
Lithium Nitride Market Segmentation
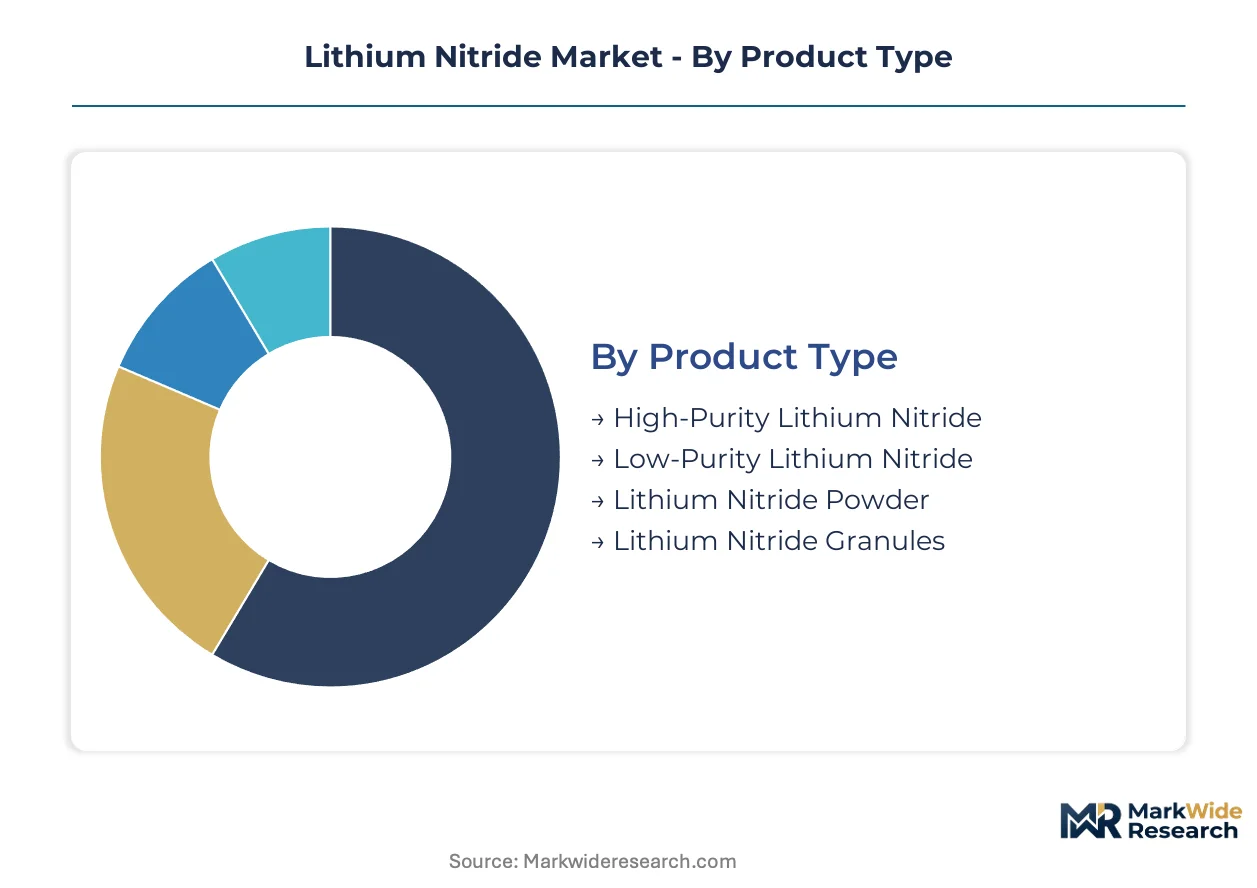
Segmentation in lithium nitride markets tracks how purity grades, physical forms, and application specifications diverge across procurement cycles. Battery-grade material commands extended qualification timelines while industrial catalyst grades turn inventory faster.
Product Type:
Cycle times vary dramatically by purity tier—high-purity material locks capital for 18-24 months during Korean cathode qualification, while low-purity industrial grades rotate inventory quarterly.
- High-Purity Lithium Nitride:Synthesized through controlled atmosphere reaction of metallic lithium with nitrogen gas, achieving sub-ppm contamination thresholds required for solid-state electrolyte precursors. Demand concentrates in South Korean cathode manufacturing zones around Gwangju and Ochang, gated by Samsung SDI and SK On supplier certification protocols that exceed legacy industrial specifications.
- Lithium Nitride Powder:Fine particulate form produced via ball milling or spray pyrolysis with controlled particle size distribution for dry electrode coating compatibility. Adoption is climbing fastest among battery manufacturers adopting solvent-free production techniques at facilities in China's Jiangsu province and South Korea's Incheon cluster.
- Low-Purity Lithium Nitride:Industrial-grade material with relaxed contamination specifications serves ammonia synthesis catalyst research programs in German and Japanese laboratories.
- Lithium Nitride Granules:Pelletized form optimized for thermal conductivity applications and hydrogen storage vessel packing.
High-purity lithium nitride dominates installed base. Lithium nitride powder is where expansion concentrates.
End Use Industry:
Cost tier separation splits procurement—automotive and energy storage buyers absorb premium pricing for certified material while aerospace and electronics segments optimize for specification compliance at lower purity grades.
- Energy Storage:Solid-state battery development programs drive specification tightening for electrolyte precursors, with South Korean cell manufacturers establishing dedicated nitride qualification teams. This segment absorbs the majority of new capital allocation as dry electrode coating techniques gain manufacturing scale.
- Automotive:OEM solid-state pilot lines require documented carbon footprint data under EU Battery Regulation compliance frameworks, favoring suppliers with vertically integrated upstream lithium sourcing from Chilean brine or Australian spodumene operations.
- Electronics:Thermal management applications in high-performance computing hardware utilize lithium nitride's thermal conductivity properties.
- Aerospace:Hydrogen storage research programs sustain baseline offtake for lightweight metal hydride systems.
Energy storage commands premium pricing tiers. Automotive procurement is climbing the fastest.
Application:
Volume concentration separates commodity catalyst demand from specialized battery component supply chains requiring dedicated synthesis infrastructure.
- Battery Components:Solid-state electrolyte precursors and electrode coating materials require argon-atmosphere handling throughout production, packaging, and transport. Korean cathode producers POSCO Chemical and EcoPro BM have established preferred supplier frameworks that bypass traditional chemical distributors.
- Catalysts:Ammonia synthesis research programs at German and Japanese laboratories sustain stable demand for high-surface-area lithium nitride powders with less stringent purity requirements than battery grades.
- Fuel Cells:Hydrogen storage medium applications in portable power systems utilize lithium nitride's reversible hydrogen absorption properties.
- Thermal Conductors:Heat spreader applications in electronics packaging exploit the material's thermal conductivity.
Battery components dominate installed base. Fuel cell applications are gaining share fastest.
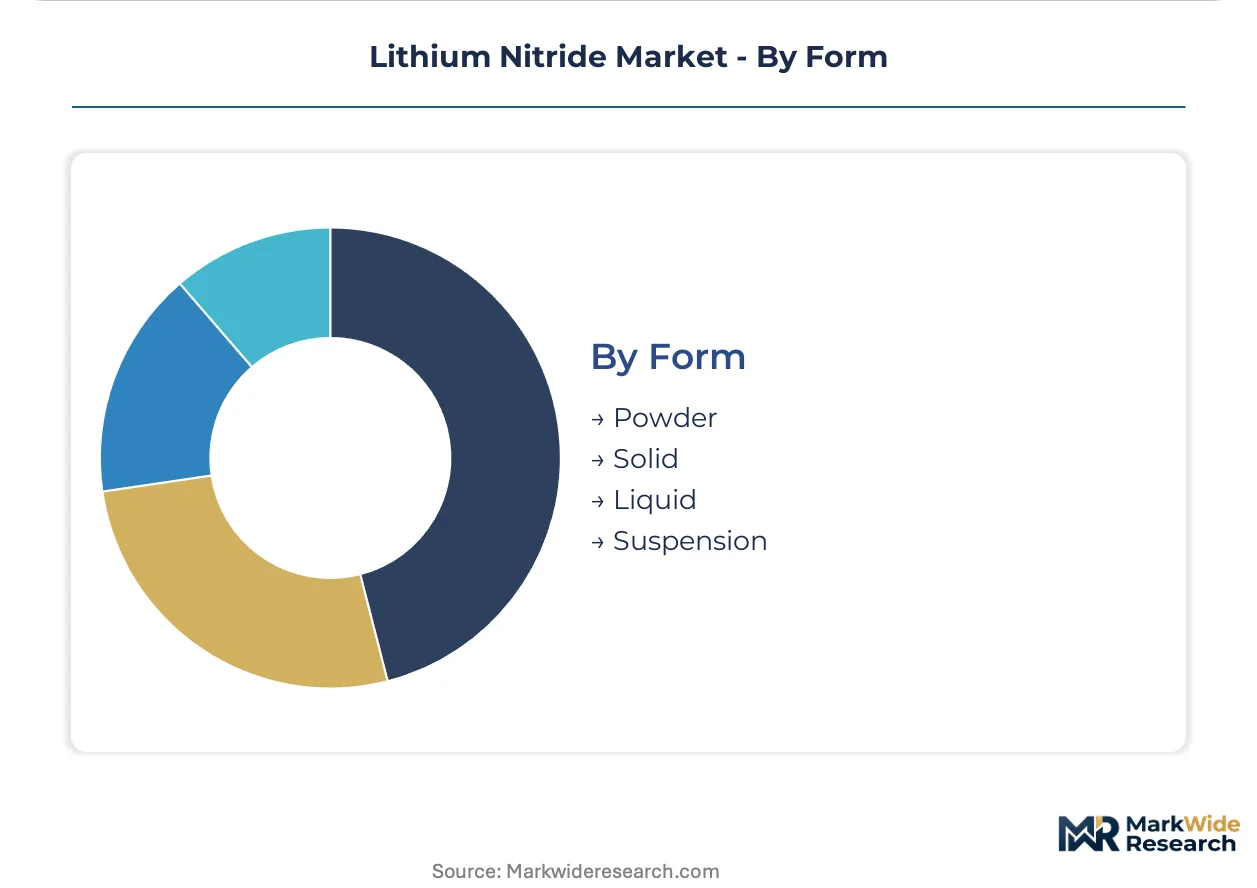
Form:
Supply concentration clusters around powder and solid forms, with liquid and suspension variants serving niche research applications with limited commercial scale.
- Powder:Dominant commercial form produced through controlled atmosphere milling and classification, optimized for dry electrode coating and catalyst applications. Manufacturing concentrates in East Asian clusters within 200 kilometers of Seoul and Shanghai where argon recovery infrastructure achieves economic scale.
- Solid:Bulk crystalline form used in thermal management and hydrogen storage vessel fabrication, requiring specialized machining under inert atmosphere conditions.
- Liquid:Dispersed suspensions for specialized coating applications in laboratory research settings.
- Suspension:Colloidal preparations for wet chemical processing in catalyst precursor synthesis.
Powder form dominates installed base. Solid form is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and China absorb premium pricing for battery-grade certification, while European automotive OEMs negotiate hardest on carbon-accounting documentation costs. Price elasticity flattens in research laboratory segments where purity specifications drive procurement regardless of cost. Regional regulatory divergence is fragmenting supplier qualification protocols.
China
NMPA battery material standards filter qualified suppliers through GB purity mandates for solid-state electrolyte precursors. The MIIT dual carbon goals pressure Jiangsu province manufacturers to document nitride processing emissions. Manufacturing concentrates in Yangtze River Delta clusters where argon recovery infrastructure achieves economic scale at sub-500-ton annual thresholds.
South Korea
Samsung SDI and SK On solid-state pilot lines require 18-24 month supplier qualification cycles that freeze out mid-scale entrants. MFDS oversight of medical device batteries extends to precursor material traceability requirements. Gwangju and Ochang industrial complexes host preferred supplier frameworks that bypass traditional chemical distributors for direct nitride procurement.
Germany
ECHA REACH substance registration forces importers to document full lithium compound supply chain toxicity profiles. The EU Battery Regulation carbon footprint disclosure requirements favor suppliers with vertically integrated upstream lithium sourcing. German automotive OEMs audit Chilean and Australian upstream operations for REACH-aligned substance data.
United States
EPA hazardous material handling rules for reactive lithium compounds elevate compliance costs while filtering subscale producers from qualified supplier lists. FDA oversight of medical device batteries extends to solid-state electrolyte precursor documentation. Domestic cell manufacturing investments cluster around Pacific Northwest and Southwest industrial corridors seeking proximity to lithium refining infrastructure.
India
The PLI scheme for domestic cell manufacturing attracts nitride precursor investments to Gujarat and Tamil Nadu industrial corridors. CEA grid-scale energy storage mandates create pull-through demand for solid-state battery development programs. Procurement patterns favor suppliers demonstrating backward integration into spodumene conversion capabilities.
Lithium Nitride Market Competitive Landscape
Integrated lithium majors and specialty chemical synthesizers split the market along feedstock control lines. The structure concentrates around five to seven qualified producers capable of battery-grade certification. Three archetypes dominate: brine-to-nitride integrators controlling Chilean and Australian upstream assets; spodumene converters with captive chemical processing scale; and regional specialists serving industrial catalyst grades outside battery supply chains. Competitive moves center on capacity expansion in East Asian manufacturing clusters and strategic partnerships for hybrid sulfide-nitride electrolyte formulations.
Among integrated lithium majors, Albemarle Corporation anchors the brine-to-nitride archetype through Chilean upstream dominance. Ganfeng Lithium exemplifies Chinese vertical integration from spodumene conversion through high-purity output. Tianqi Lithium occupies a position sustained by Australian hard-rock offtake agreements. These three represent the tier capable of meeting Korean cathode producer qualification timelines.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Livent Corporation |
| Ganfeng Lithium |
| SQM |
| Tianqi Lithium |
| BASF |
| Wuhan Easpring Material Technology |
| Zhejiang Headway Lithium Battery Technology |
| Chengxin Lithium Group |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in South Korean argon recovery infrastructure drives supplier consolidation and elevates pricing power for qualified nitride synthesizers serving Samsung SDI and SK On qualification protocols. Battery-grade certification timelines stretching 18-24 months lock buyers into long-term offtake contracts that insulate producers from spot market volatility.
Pricing Analysis
Aftermarket recycling revenue from spent solid-state batteries drives lifetime value capture across the lithium nitride value chain. Contract-based long-term offtake dominates procurement, with price differentiation anchored in certification grade and argon-atmosphere handling capabilities. Cost compression in industrial catalyst grades intensifies as research laboratory budgets face pressure from redirected energy storage R&D funding. Korean cathode manufacturers exhibit lowest price sensitivity due to supply security imperatives, while ammonia synthesis research programs in Germany and Japan optimize for specification compliance at lower purity tiers.
Supply Chain Analysis
Tariff exposure between China and South Korea dominates supply chain risk planning for nitride precursor flows into Gwangju and Ochang industrial complexes. Manufacturing concentrates in China, South Korea, and Australia, with raw material dependencies on Chilean brine, Australian spodumene, and industrial nitrogen gas feedstocks. Single-source vulnerability in East Asian argon recovery infrastructure threatens production continuity for sub-500-ton annual scales. Distribution runs through direct procurement frameworks that bypass traditional chemical distributors, with POSCO Chemical and EcoPro BM establishing preferred supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat sustained by regulatory entrenchment—battery-grade certification protocols create switching costs that freeze out mid-scale entrants and protect incumbent positioning.
For Market Incumbents: Insulate qualification status by expanding argon recovery capacity in Yangtze River Delta clusters to capture economies of scale below 500-ton thresholds. Deepen backward integration into Australian spodumene offtake agreements to secure feedstock cost predictability against South American brine contract volatility. Korean cathode producer consolidation threatens distributor margins; direct procurement frameworks now bypass traditional chemical traders entirely.
For New Entrants and Emerging Players: Industrial catalyst grades for ammonia synthesis research in German and Japanese laboratories represent the most penetrable entry point outside battery supply chain certification barriers. India's PLI scheme for Gujarat and Tamil Nadu cell manufacturing corridors offers second-mover positioning before Korean-style qualification protocols harden. A go-to-market angle emphasizing REACH-aligned substance documentation gains traction with German automotive OEMs auditing upstream lithium operations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among brine-to-nitride integrators controlling Chilean upstream assets through captive chemical processing scale. Long-term viability over the next decade rests on multi-material formulation capabilities for hybrid sulfide-nitride electrolytes. The signal to monitor is Korean battery maker adoption of carbon footprint disclosure requirements as gating criteria for solid-state supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Argon Recovery Capacity Expansion | Closed-loop gas recycling systems achieve economic scale in Yangtze River Delta manufacturing clusters. |
| Backward Integration into Spodumene | Australian hard-rock offtake agreements reduce feedstock cost exposure to South American brine volatility. |
| Hybrid Electrolyte Formulation Partnership | Sulfide-nitride convergence opens collaboration channels between Korean cell makers and specialty chemical suppliers. |
| REACH-Aligned Substance Documentation | Full supply chain toxicity profiles satisfy ECHA registration requirements for European automotive OEM access. |
| Direct Procurement Framework Establishment | Preferred supplier relationships with POSCO Chemical and EcoPro BM bypass traditional chemical distributor networks. |
Research Methodology
Operator-level perspectives from nitride synthesis plant managers, Korean cathode producer procurement leads, argon recovery infrastructure engineers, and solid-state battery R&D directors anchored the qualitative base. Primary interviews combined with secondary validation drawn from NMPA battery material filings, MIIT dual carbon goal disclosures, EU Battery Regulation carbon accounting documentation, and Korean customs trade data. Bottom-up capacity assessments and top-down demand modeling from energy storage deployment projections provided triangulation discipline.
Scenario-bracketing around solid-state battery commercialization timelines and hydrogen storage R&D funding trajectories bounded the analytical framework across the analysis window. Segmentation dimensions modeled include purity grade tier, physical form specification, end-use industry application, and regional manufacturing hub concentration. CAGRs derived from weighted average of bottom-up capacity expansion schedules and top-down cathode producer procurement forecasts. Industry-specific inputs incorporated Korean supplier qualification cycle durations and argon-atmosphere handling capital intensity curves.
Practitioners should monitor Korean battery maker purity certification adoptions and EU Battery Regulation carbon footprint enforcement intensity for early signals of forecast revision. Forecasts reflect assumptions regarding solid-state electrolyte precursor demand trajectories and East Asian manufacturing cluster concentration stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Chromium Carbide Overlay Plate Market
Advanced Alloys
Green Steel Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Global Corrosion Resistant Alloys Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
India Aluminum Extrusion Market