
 United States Material Testing Market | 2026-2036
United States Material Testing Market Size, Share, and Industry Trends Forecast 2026-2036
United States Material Testing Market Intelligence
The Buy American Act and domestic content mandates for federally funded infrastructure is rebalancing procurement patterns toward domestically manufactured testing equipment. Instron leverages its Massachusetts manufacturing base to sustain government contract eligibility. MTS Systems anchors its position through Minnesota-based production of servo-hydraulic test systems. ZwickRoell competes via its Pennsylvania facility serving Penn State's materials research complex.
Material testing encompasses mechanical, thermal, electrical, and chemical evaluation of substances to determine properties including tensile strength, hardness, fatigue life, and thermal conductivity for quality verification and design validation. Tensile testers dominate capital expenditure in automotive and aerospace certification labs where ASTM E8 compliance is mandatory. Hardness testers serve mature demand in Midwest manufacturing quality rooms. Thermal testing equipment captures premium margins from electronics reliability programs in Silicon Valley and Research Triangle Park.
FAA airworthiness standards, ASTM International protocols, and OSHA workplace safety regulations collectively dictate equipment calibration frequencies, operator certification requirements, and acceptable test methodologies across US facilities. The Department of Transportation's infrastructure spending guidelines incorporate material verification clauses that expand testing service contracts. Stakeholders must monitor NIST's evolving reference standards for advanced composites and additive manufacturing to anticipate equipment upgrade cycles.
Market Dynamics
FAA airworthiness directives on additive manufacturing certifications are compressing equipment replacement cycles across aerospace testing labs. Domestic content mandates under the Buy American Act are rebalancing procurement toward US-manufactured systems.
Growth Catalysts
- Infrastructure Investment and Jobs Act:Department of Transportation material verification clauses expand third-party testing service contracts for bridge and highway projects.
- Composite airframe adoption:Boeing and Gulfstream are expanding non-destructive testing protocols for carbon fiber reinforced polymer structures.
- Silicon Valley electronics reliability programs:Semiconductor manufacturers are driving thermal testing equipment demand for chip packaging validation.
Market Restraints
- Calibration-grade sensor supply:German and Japanese load cell manufacturers control critical strain gauge supply, creating input cost volatility.
- ASTM E8 compliance complexity:Mandatory protocol adherence extends equipment qualification timelines for tensile testing systems.
- Used equipment arbitrage:Refurbished Instron and MTS units from automotive plant closures substitute for new capital purchases.
Strategic Opportunities
- Texas energy infrastructure hubs:Permian Basin pipeline projects lack sufficient materials testing capacity for weld qualification services.
- Digital twin convergence:Physical testing data feeds into simulation software, creating integrated validation workflows for aerospace OEMs.
- NIST advanced composites initiative:Federal reference standard development creates upgrade pull for labs seeking accreditation.
Industry Challenges
- ASNT NDT Level III certification scarcity:Ultrasonic and radiographic testing specialists command premium wages, constraining service expansion.
- Legacy servo-hydraulic integration:1990s-era MTS test frames require costly controller retrofits to interface with modern data acquisition systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Material Testing Market |
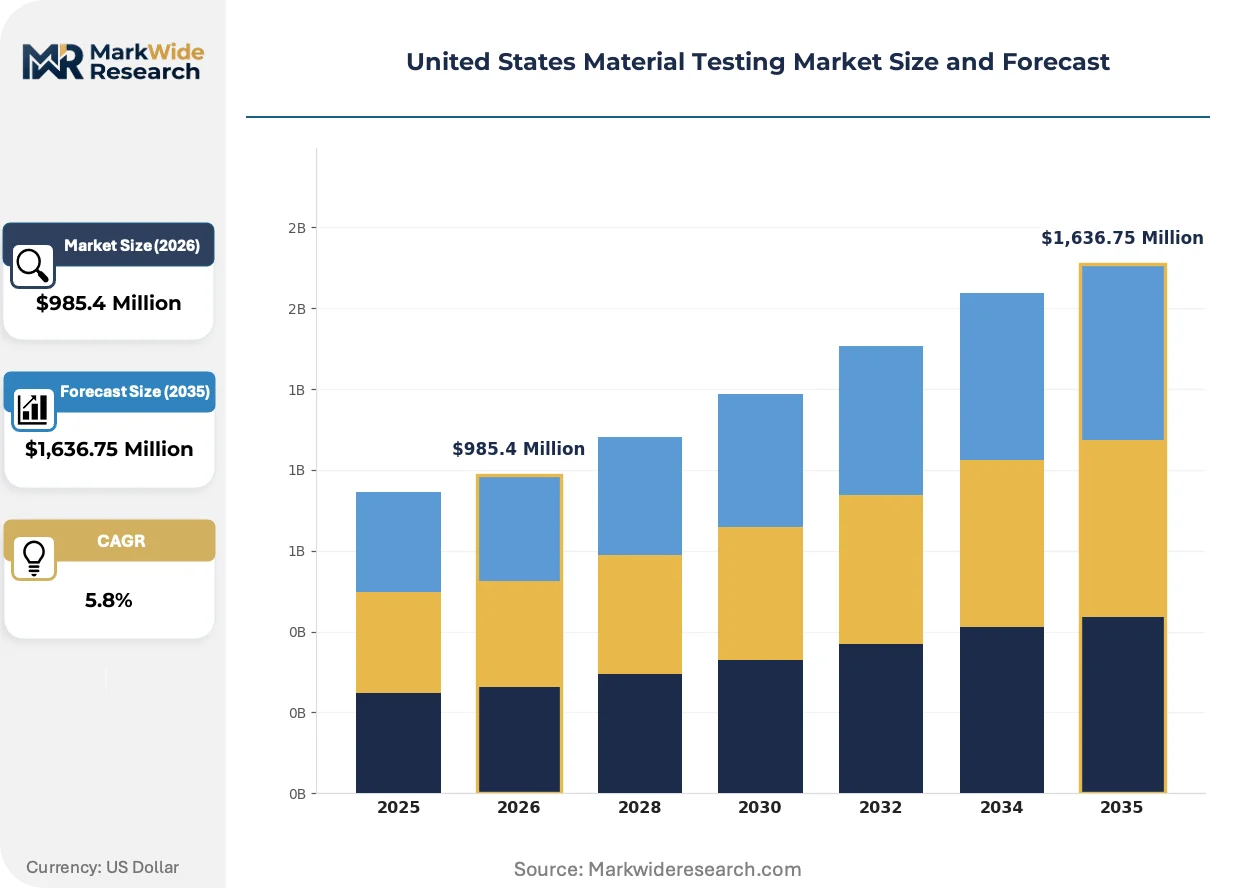
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,636.75 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tensile Testers, Hardness Testers, Fatigue Testers, Compression Testers End User: Aerospace, Construction, Automotive, Electronics Technology: Mechanical Testing, Thermal Testing, Electrical Testing, Chemical Testing Application: Quality Assurance, Research & Development, Compliance Testing, Process Control |
| Companies Covered | Illinois Tool Works Inc., Instron, Tinius Olsen, Ametek, MTS Systems, ZwickRoell, Shimadzu Corporation, Mitutoyo Corporation, Element Materials Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Material Testing Market Strategic Shifts & Innovations
Digitalization of test workflows and convergence of physical-metrology with simulation software are restructuring how validation data is generated and consumed across US manufacturing.
Automated robotic testing cells are expanding into high-throughput automotive materials qualification. Tier-1 suppliers adopt these systems to compress alloy screening cycles from weeks to days. The technology is expanding into fatigue testing programs where repetitive specimen loading previously required operator attendance.
OSHA workplace safety regulations now mandate real-time force monitoring on universal testing machines with personnel access. Equipment retrofit orders surged following 2023 enforcement memoranda. California and Washington state OSHA plans are extending requirements to smaller fabrication shops.
Testing service contracts now unbundle equipment ownership from data delivery. Automotive OEMs lease validation capacity from regional labs rather than maintaining captive facilities. This pattern concentrates most visibly in Michigan's automotive supplier corridor and South Carolina's BMW supplier park.
United States Material Testing Market Segmentation
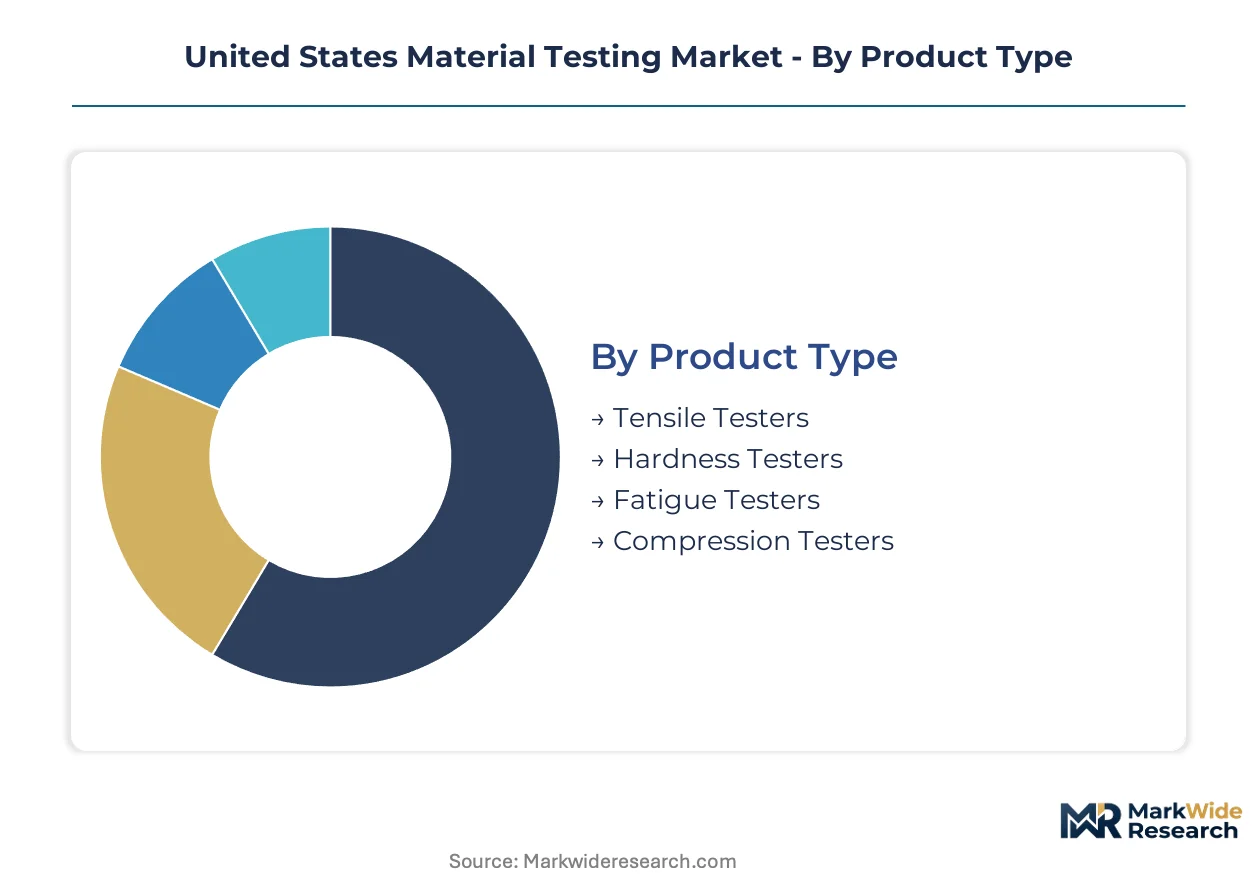
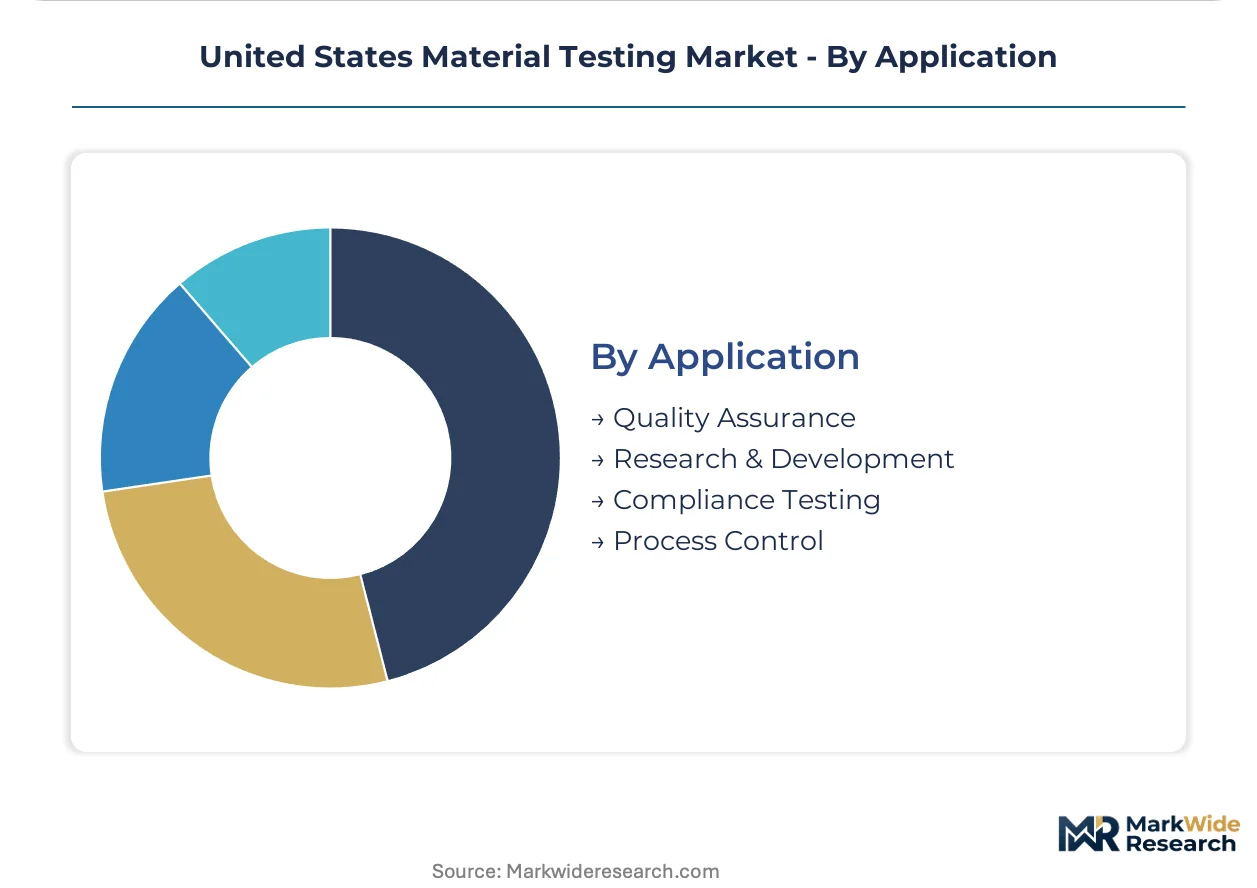
Segmentation reveals how procurement concentrates around regulatory compliance requirements and capital intensity thresholds. Equipment specifications diver sharply between high-volume automotive qualification labs and low-volume aerospace certification facilities.
Product Type:
Supply concentration in servo-hydraulic actuators and precision load cells concentrates manufacturing among three domestic production centers.
- Tensile Testers:Universal testing machines apply controlled tension to characterize yield strength, ultimate tensile strength, and elongation per ASTM E8 protocols. Demand clusters in Michigan automotive supplier labs and California aerospace certification facilities where FAA airworthiness directives mandate specimen-level validation. Equipment refresh cycles compress as additive manufacturing certifications expand.
- Fatigue Testers:Cyclic loading systems evaluate material endurance limits under repeated stress amplitudes. Boeing and Gulfstream programs in Washington state and Georgia drive servo-hydraulic system demand for composite airframe validation. NDT integration requirements extend specification complexity.
- Hardness Testers:Indentation-based systems serve mature quality room demand across Midwest manufacturing.
- Compression Testers:Axial loading equipment validates structural member performance for construction and energy infrastructure applications.
Today's leader: Tensile Testers. Tomorrow's challenger: Fatigue Testers.
End User:
Customer capital deployment patterns separate captive facility ownership from outsourced testing service contracts.
- Aerospace:OEMs and Tier-1 suppliers operate dedicated materials qualification labs for airframe and engine component certification. FAA airworthiness directives on additive manufacturing compress equipment replacement timelines. Washington state, California, and Georgia host the densest facility concentrations.
- Automotive:OEMs shift from captive labs to leased validation capacity in Michigan and South Carolina supplier corridors. Alloy screening throughput demands accelerate robotic testing cell adoption.
- Construction:Bridge and highway projects under Department of Transportation funding expand third-party weld qualification demand.
- Electronics:Semiconductor packaging reliability programs in Silicon Valley and Research Triangle Park drive thermal testing equipment procurement.
Capital intensity peaks in Aerospace. Volume scaling accelerates fastest in Automotive.
Technology:
Margin structures diverge between commoditized mechanical systems and premium thermal-electrical platforms serving electronics reliability.
- Mechanical Testing:Tensile, compression, and fatigue systems constitute the equipment revenue base. Domestic manufacturing concentration in Massachusetts and Minnesota supports Buy American Act compliance for federal infrastructure contracts.
- Thermal Testing:Thermal conductivity and expansion measurement systems capture premium pricing from semiconductor packaging validation programs. California and North Carolina electronics clusters concentrate demand.
- Electrical Testing:Dielectric and resistivity characterization serves wire and cable qualification.
- Chemical Testing:Spectroscopic and chromatographic methods support materials composition verification.
Mechanical Testing anchors current revenue. Thermal Testing climbs the fastest on electronics reliability investment.
Application:
Service contract unbundling separates equipment ownership from data delivery, restructuring procurement economics.
- Quality Assurance:In-process and incoming inspection protocols dominate equipment utilization hours. Midwest manufacturing quality rooms and Texas energy fabrication shops sustain baseline demand for hardness and tensile verification.
- Research & Development:Alloy screening and composite formulation studies require flexible testing protocols. Automotive Tier-1 suppliers deploy robotic cells to compress evaluation cycles from weeks to days.
- Compliance Testing:Regulatory-mandated verification for FAA, DOT, and OSHA adherence expands third-party service contracts.
- Process Control:Real-time production monitoring integrates testing data into manufacturing execution systems.
Quality Assurance commands current volume. Research & Development offers the steepest expansion trajectory on digital twin convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Material testing infrastructure in the United States traces its modern lineage to postwar aerospace expansion in California and defense manufacturing concentration across the Midwest. Federal laboratory networks established during the Cold War era seeded commercial testing capacity that now serves diversified industrial demand. State-level procurement preferences and sector-specific regulatory clusters continue to reshape geographic deployment patterns.
California
Silicon Valley semiconductor packaging programs and Los Angeles aerospace corridors drive thermal and mechanical testing equipment demand. Cal/OSHA workplace safety enforcement extends real-time force monitoring mandates to smaller fabrication shops. San Diego's defense contractor cluster sustains non-destructive testing service contracts for naval aviation programs.
Texas
Permian Basin pipeline construction and Gulf Coast petrochemical expansion create weld qualification capacity shortages. Department of Transportation infrastructure spending guidelines incorporate material verification clauses for bridge projects across the state. Houston's energy fabrication hub concentrates third-party testing service demand for pressure vessel certification.
Michigan
Automotive OEM alloy screening programs and Tier-1 supplier quality rooms sustain tensile and hardness tester utilization. OSHA enforcement memoranda on universal testing machine safety drive retrofit orders across manufacturing facilities. Detroit's automotive supplier corridor leads adoption of robotic testing cells for high-throughput materials qualification.
Washington
Boeing composite airframe programs and FAA additive manufacturing certification requirements compress equipment replacement cycles. Washington State Department of Labor and Industries extends safety inspection protocols to testing laboratory operations. Everett and Renton manufacturing clusters anchor dedicated materials qualification facilities for commercial aviation programs.
Pennsylvania
Penn State's materials research complex and Pittsburgh's advanced manufacturing institutes drive R&D-focused testing equipment procurement. Buy American Act compliance requirements favor domestically manufactured systems for federally funded research contracts. Philadelphia's medical device cluster generates specialized mechanical testing demand for implantable component validation.
United States Material Testing Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a bifurcated market structure. Equipment manufacturers with captive manufacturing assets in Massachusetts, Minnesota, and Pennsylvania leverage domestic content mandates for federal contract eligibility. Testing service providers operate asset-light networks that unbundle equipment ownership from data delivery. Three strategic archetypes dominate: integrated equipment-service hybrids, pure-play equipment manufacturers, and independent testing laboratories. Competitive moves concentrate on geographic expansion into Texas energy corridors and portfolio diversification toward thermal-electrical testing platforms.
Among domestically anchored equipment producers, Instron, MTS Systems, and ZwickRoell exemplify the integrated manufacturing archetype. Instron's Massachusetts production base secures government contract eligibility under Buy American Act provisions. MTS Systems anchors its position through Minnesota-based servo-hydraulic system manufacturing. ZwickRoell occupies a position within the Pennsylvania industrial corridor, proximate to Penn State's materials research infrastructure. These manufacturers represent the capital-intensive tier where domestic production assets confer regulatory compliance advantages.
| Leading Market Players |
|---|
| Illinois Tool Works Inc. |
| Instron |
| Tinius Olsen |
| Ametek |
| MTS Systems |
| ZwickRoell |
| Shimadzu Corporation |
| Mitutoyo Corporation |
| Element Materials Technology |
| Others |
Cost & Logistics Intelligence
Captive manufacturing of servo-hydraulic actuators and precision load cells in Massachusetts, Minnesota, and Pennsylvania anchors domestic equipment producers' pricing power against import competition. This geographic concentration of production assets enables Buy American Act compliance premiums while insulating margin structures from currency volatility affecting German and Japanese sensor suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aerospace systems from general industrial units and refurbished equipment. Premium tiers capture certification-grade margins through NIST-traceable calibration and ASNT-compliant operator training bundles. Cost compression in the economy tier intensifies because automotive plant closure liquidations flood secondary markets with 1990s-era MTS and Instron frames. Tier-1 automotive suppliers exhibit highest price sensitivity, deferring capital purchases through leased validation capacity arrangements.
Supply Chain Analysis
Freight cost differentials between domestic actuator assembly and offshore strain gauge sourcing shape procurement economics for US equipment builders. Critical load cell components draw from Germany and Japan, creating single-source vulnerability for calibration-grade sensors. Supply chain risk centers on tariff exposure affecting precision electronics imports from East Asian manufacturing clusters. Distribution runs through direct OEM sales for large aerospace accounts and regional distributor networks serving Midwest manufacturing quality rooms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States material testing market functions as a regulatory compounder where FAA additive manufacturing certification mandates perpetually refresh equipment replacement demand. Infrastructure Investment and Jobs Act material verification clauses extend this dynamic into construction and energy infrastructure applications.
For Market Incumbents: Deepen backward integration into precision sensor manufacturing to reduce dependency on German and Japanese load cell suppliers. Expand NIST-accredited calibration service footprints in Texas energy corridors before weld qualification capacity shortages attract specialist entrants. Robotic testing cell capabilities represent the critical defensive lever against automated alloy screening demands from automotive Tier-1 suppliers. For New Entrants and Emerging Players: Digital service platforms offering unbundled data delivery from equipment ownership provide entry routes into Michigan and South Carolina automotive supplier corridors. Target third-party compliance testing contracts for Department of Transportation-funded bridge projects where incumbent equipment manufacturers lack service infrastructure. Thermal testing equipment for semiconductor packaging validation in Silicon Valley presents the most penetrable premium segment. For Investors and Strategic Acquirers: Roll-up economics work for independent testing laboratories because service contract unbundling concentrates procurement decisions on data quality rather than equipment brand loyalty. The five-to-ten year viability window favors asset-light regional labs with established DOT and FAA accreditation over capital-intensive equipment manufacturing. Watch NIST reference standard releases for advanced composites as the inflection signal triggering accreditation-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load Cell Manufacturing | Reduces tariff exposure and secures calibration-grade sensor supply for FAA-certified systems. |
| Robotic Testing Cell Deployment | Compresses automotive alloy screening cycles from weeks to days for Tier-1 supplier contracts. |
| NIST Accreditation Investment | Positions labs for federal infrastructure contract eligibility under Buy American Act provisions. |
| Texas Energy Corridor Expansion | Captures Permian Basin pipeline weld qualification demand before capacity shortages peak. |
| Digital Twin Platform Integration | Feeds physical testing data into aerospace OEM simulation workflows for recurring validation revenue. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from equipment manufacturing executives, testing laboratory operations directors, FAA certification engineers, automotive Tier-1 supplier quality managers, and NIST calibration specialists. Secondary validation drew from FAA airworthiness directive filings, ASTM International protocol updates, Department of Transportation infrastructure spending disclosures, and OSHA enforcement memoranda. Bottom-up equipment shipment data triangulated against top-down federal contract award values.
Historical reference periods spanning pre-pandemic baseline through post-regulatory-shift recovery anchored the forecast window. The analytical framework modeled segmentation across product type, end-user industry, technology platform, and application purpose. CAGRs derived from equipment replacement cycle compression rates and federal spending authorization trajectories. Forecast inputs incorporated FAA additive manufacturing certification timelines and NIST advanced composites reference standard development schedules.
The model assumes a particular technology adoption path; alternative pathways for digital twin convergence would alter the outlook if aerospace OEMs accelerate simulation-first validation workflows. Forecasts reflect assumptions about regulatory enforcement consistency and federal infrastructure appropriation continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Global Chromatography Instrumentation Market
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Environmental Testing Equipment Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Brittleness Tester Market
Testing Equipment
Global Online Coal Ash Analyzers Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Electrical Testing Equipment Market
Testing Equipment
Global Lab Supplies Market