
 Battery Alloys Market | 2026-2036
Battery Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Alloys Market Outlook
Utility-scale energy storage procurement is collapsing as the dominant buyer archetype, while electric vehicle OEM direct contracting is gaining share. Umicore anchors European cathode precursor capacity through integrated refining in Belgium and Poland. Sumitomo Metal Mining Co., Ltd. dominates nickel sulfate supply to Japanese battery makers through captive Indonesian laterite processing. Glencore International AG controls cobalt feedstock flows from the DRC into Asian alloy smelters.
Battery alloys are engineered metallic compositions—typically nickel-cobalt-manganese, lithium-aluminum, or lead-calcium systems—produced via vacuum induction melting or hydrometallurgical precipitation to achieve precise electrochemical stability and corrosion resistance for electrode substrates and current collectors. Lithium alloys lead in value contribution due to cathode active material demand, while aluminum alloys grow fastest in cell housing and busbar applications as manufacturers pursue pack-level weight reduction. Cast alloys occupy the mature volume position in lead-acid grids, whereas powder metallurgy captures margin in solid-state battery prototype programs.
The EU Battery Regulation and REACH framework enforce recycled-content thresholds and restricted substance declarations, compelling alloy processors to certify circular feedstock chains. China's MIIT publishes GB standards for battery material purity that determine import eligibility for foreign alloy suppliers. Japan's METI subsidizes domestic precursor production to reduce cobalt supply exposure. Stakeholders must monitor how carbon border adjustments and critical mineral security designations reshape alloy procurement geography before committing to long-term offtake structures.
Market Dynamics
Cathode precursor manufacturers face acute feedstock pressure as Chinese processors absorb Indonesian nickel matte capacity and EU recycled-content mandates force alloy suppliers to requalify supply chains.
Growth Catalysts
- EU Battery Regulation recycled-content thresholds:The framework mandates minimum recycled cobalt, lithium, and nickel in new batteries, compelling alloy processors to build circular feedstock infrastructure and secure long-term scrap offtake agreements.
- Cell energy density targets:Electric vehicle OEMs are tightening specifications for nickel-cobalt-manganese cathode materials, pulling high-purity alloy demand toward advanced precursor chemistries with elevated nickel ratios.
- Jiangsu-Zhejiang port clustering:Cathode precursor plants concentrate near Ningbo and Shanghai port infrastructure, creating dense supplier ecosystems that reduce logistics costs and accelerate sample-to-production timelines.
Market Restraints
- Cobalt feedstock concentration:Glencore International AG controls substantial Democratic Republic of Congo cobalt flows, creating single-source vulnerability for Asian alloy smelters dependent on hydroxide intermediates.
- Laterite processing cost inflation:High-pressure acid leach facilities in Indonesia face escalating sulfur and energy input costs, compressing margins for nickel sulfate destined for battery alloys.
- REACH substance restrictions:ECHA authorization requirements for certain nickel compounds add compliance friction to European alloy imports, lengthening qualification cycles for non-EU suppliers.
Strategic Opportunities
- Solid-state battery prototype programs:Powder metallurgy techniques for lithium-metal anodes and sulfide electrolyte interfaces represent uncontracted demand from automotive cell development labs.
- US Inflation Reduction Act critical mineral credits:The IRA's domestic content bonuses create pull-through for North American-sourced nickel and cobalt feedstock into alloy production.
- Pack-level weight reduction:Aluminum alloy cell housings and busbars are capturing share from steel in premium electric vehicle platforms, opening margin pools outside cathode active materials.
Industry Challenges
- Hydrometallurgical precipitation expertise:The shift from pyrometallurgical to hydrometallurgical nickel-cobalt recovery requires process engineers with rare earth and battery metals specialization, tightening talent pools.
- Dual carbon compliance documentation:China's MIIT GB standards and EU Battery Regulation carbon footprint declarations impose parallel certification burdens, forcing alloy suppliers to maintain incompatible traceability systems.
- Legacy lead-acid grid alloy displacement:Cast lead-calcium-tin alloy producers face stranded asset risk as lithium-ion chemistry erodes starter battery demand, complicating capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Alloys Market |
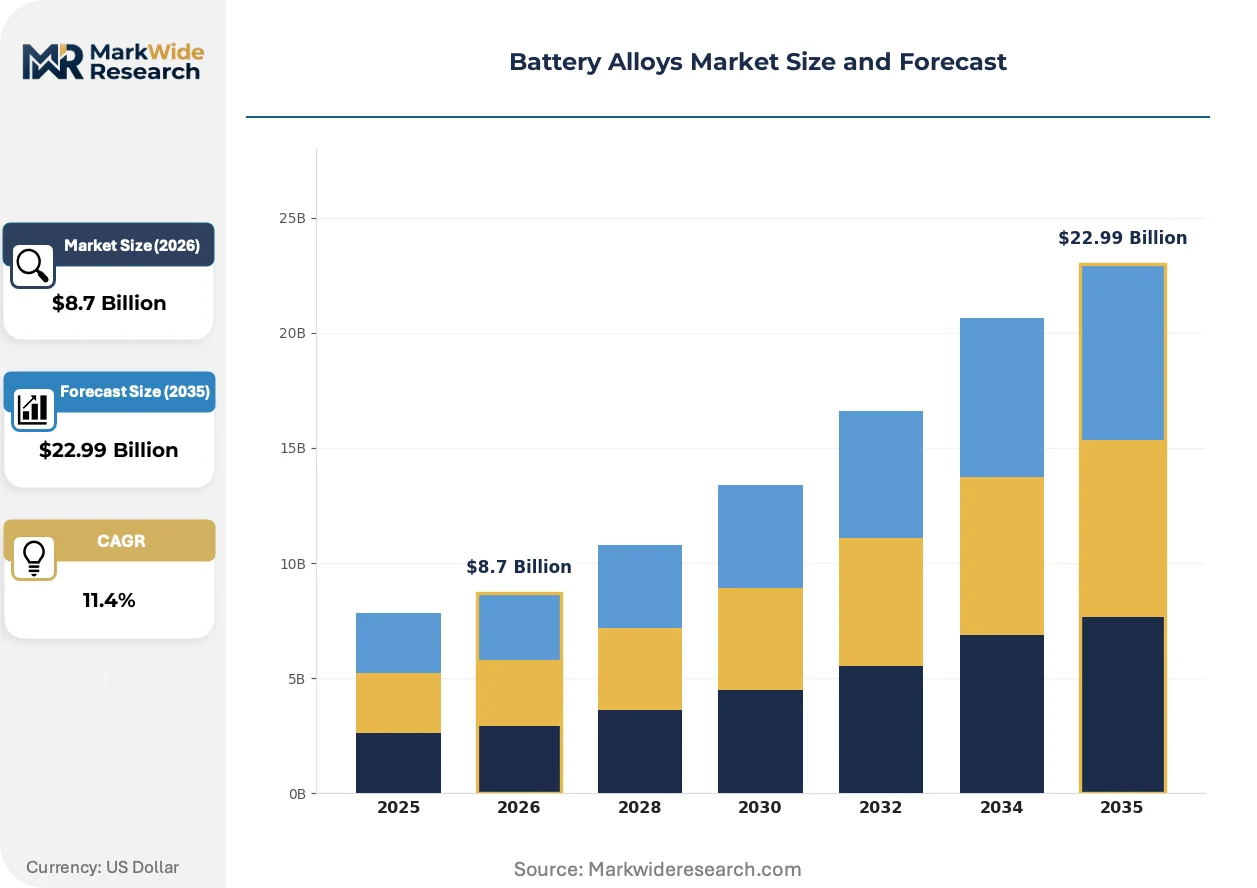
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Alloy Type: Lithium Alloys, Lead Alloys, Aluminum Alloys, Cadmium Alloys Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Industrial Batteries End User: Automotive, Electronics Manufacturers, Renewable Energy Providers, Aerospace Production Method: Cast Alloys, Wrought Alloys, Powder Metallurgy, Additive Manufacturing |
| Companies Covered | Panasonic Corporation, BASF SE, Umicore, Johnson Matthey plc, Sumitomo Metal Mining Co., Ltd., JFE Steel Corporation, Glencore International AG, Freeport-McMoRan Inc., American Battery Materials Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Alloys Market Strategic Shifts
Alloy processing technology and procurement structures are restructuring around solid-state development timelines, regulatory carbon accounting, and direct OEM contracting models that bypass traditional distributor channels.
High-nickel NMC cathode compositions are supplanting lower-nickel alternatives as the dominant precursor specification. Cell manufacturers targeting 300 Wh/kg pack densities are specifying 90% nickel content in cathode active materials, compressing demand for manganese-rich and cobalt-heavy legacy formulations. This chemistry pivot is concentrating alloy procurement among suppliers with Indonesian laterite and African cobalt hydroxide integration.
REACH substance authorization and the EU Battery Regulation's carbon footprint methodology are tightening disclosure requirements for alloy importers. The ECHA restriction process for nickel compounds and the EU's mandatory recycled-content declarations are forcing processors to document smelter emissions and scrap provenance. Asian suppliers without EU refining presence face exclusion from premium automotive supply chains.
Direct long-term offtake contracting between cathode plants and alloy smelters is eroding spot market and distributor intermediation. Procurement teams at precursor manufacturers are negotiating five-year supply agreements with fixed volume floors and price collars, displacing quarterly tender processes. This pattern is most visible in Chinese Jiangsu province, where CATL and BYD suppliers have locked Indonesian nickel sulfate capacity through 2028.
Battery Alloys Market Segmentation
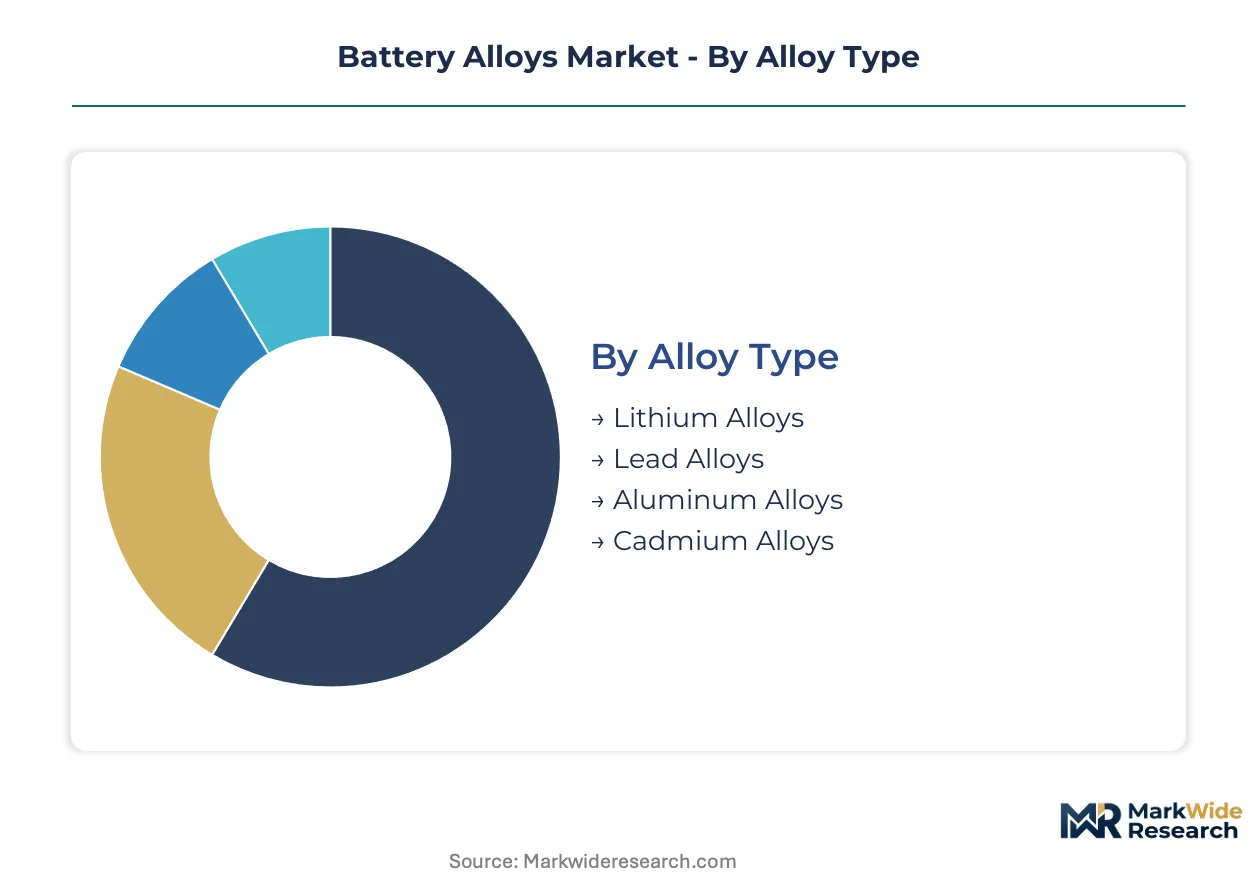
Segmentation in battery alloys reveals how chemistry selection, manufacturing process, and end-use specifications create divergent margin structures. Procurement teams route high-purity cathode materials through distinct qualification pathways than commodity lead-acid grids.
Alloy Type:
Domestic demand in China and Japan concentrates on lithium and aluminum systems for EV cathodes, while lead alloys retain regional captive consumption in Southeast Asian starter battery plants. Export-led segments serve European energy storage and North American aerospace qualification programs.
- Lithium Alloys:Lithium-aluminum and lithium-metal compositions serve solid-state and conventional cathode active materials. Demand clusters in Jiangsu province cathode precursor facilities supplying CATL and BYD, pulled by 300 Wh/kg cell energy density targets.
- Lead Alloys:Lead-calcium-tin formulations dominate conventional SLI battery grids. Mature demand concentrates in Indonesian and Vietnamese assembly plants serving replacement battery markets, facing displacement risk as lithium-ion penetrates micro-hybrid architectures.
- Aluminum Alloys:Cell housings and busbar applications.
- Cadmium Alloys:Nickel-cadmium aviation and industrial backup systems.
Lithium alloys command the established base. The steepest expansion runs through aluminum alloys.
Application:
Volume concentration tilts toward electric vehicle platforms, where annual cathode precursor offtake dwarfs stationary storage procurement. Cost tier separation emerges between premium automotive qualification and price-sensitive grid-scale storage tenders.
- Electric Vehicles:High-nickel NMC cathodes and lithium-metal anode prototypes. OEM direct contracting in China and South Korea absorbs Indonesian nickel sulfate and DRC cobalt hydroxide through qualified precursor supply chains.
- Energy Storage Systems:Lithium iron phosphate and sodium-ion alternatives for grid-scale installations. Utility procurement teams prioritize cost per kWh over energy density, sourcing aluminum busbar and lower-nickel cathode formulations.
- Consumer Electronics:Cobalt-rich LCO cathodes for portable power.
- Industrial Batteries:Nickel-cadmium and lead-acid systems for backup power.
Electric vehicles anchor procurement volumes. Energy storage systems are climbing the fastest as IRA domestic content credits reshape North American project finance.
End User:
Automotive OEMs enforce the most stringent qualification protocols, requiring 18-24 month sample-to-production timelines. Electronics manufacturers and renewable developers operate on compressed procurement cycles with lighter traceability burdens.
- Automotive:Cell manufacturers and tier-one cathode plants. European OEMs mandate EU Battery Regulation carbon footprint declarations and recycled-content thresholds, excluding Asian suppliers without continental refining presence.
- Electronics Manufacturers:Smartphone and laptop battery pack assemblers. Procurement concentrates in South Korea and Japan, where METI subsidies for domestic precursor production reduce cobalt supply exposure.
- Renewable Energy Providers:Utility and independent power developers.
- Aerospace:Satellite and aviation battery systems with extreme reliability specifications.
Automotive commands the established base. The steepest expansion runs through renewable energy providers.
Production Method:
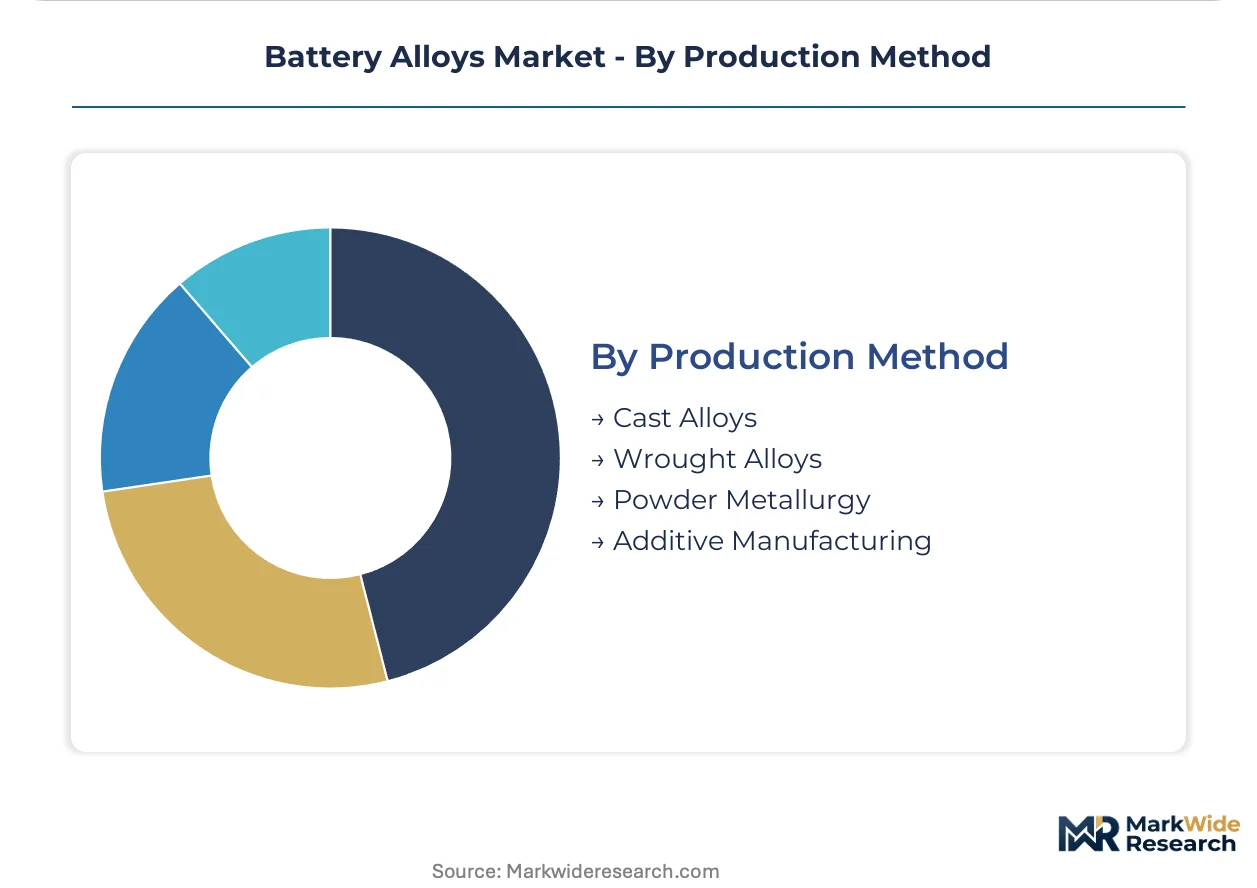
Maturity gradients separate century-old casting techniques from powder metallurgy processes still in prototype qualification. Supply concentration varies: cast alloys source from distributed secondary lead smelters, while powder metallurgy requires specialized atomization and sintering equipment.
- Cast Alloys:Conventional gravity and pressure casting for lead-acid grids. Mature capacity in China, India, and Mexico serves replacement battery demand with thin margins and minimal R&D intensity.
- Powder Metallurgy:Gas atomization and mechanical alloying for lithium-metal anodes and sulfide electrolyte interfaces. Solid-state battery development labs in Japan, Germany, and the United States represent uncontracted demand with premium pricing potential.
- Wrought Alloys:Rolled and extruded aluminum for cell housings.
- Additive Manufacturing:Laser powder bed fusion for complex current collector geometries.
Cast alloys command the established base. The steepest expansion runs through powder metallurgy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle OEM direct contracting concentrates procurement power among cathode precursor manufacturers in East Asia, while European alloy processors reconfigure supply chains to satisfy recycled-content mandates.
China
Jiangsu and Zhejiang provinces host dense clusters of cathode precursor plants near Ningbo and Shanghai port infrastructure. MIIT GB standards enforce battery material purity thresholds that determine import eligibility for foreign alloy suppliers. CATL and BYD suppliers have locked Indonesian nickel sulfate capacity through 2028 via direct long-term offtake agreements.
Japan
Domestic battery makers drive nickel sulfate demand through qualified supply chains anchored by Sumitomo Metal Mining Co., Ltd. METI subsidizes precursor production to reduce cobalt supply exposure from Democratic Republic of Congo sources. Solid-state battery development labs in Kansai and Chubu regions represent uncontracted demand for powder metallurgy lithium-metal anodes.
Belgium
Umicore anchors European cathode precursor capacity through integrated refining operations serving automotive OEMs. EU Battery Regulation recycled-content thresholds and ECHA REACH substance restrictions compel alloy processors to certify circular feedstock chains. The Antwerp-Liege industrial corridor concentrates hydrometallurgical precipitation capacity for high-purity nickel-cobalt recovery.
United States
IRA critical mineral credits create pull-through for North American-sourced nickel and cobalt feedstock into alloy production. FERC grid interconnection rules indirectly shape utility-scale energy storage procurement patterns affecting aluminum busbar demand. Michigan and Ohio automotive manufacturing clusters are qualifying domestic precursor suppliers for EV platform contracts.
Indonesia
Laterite nickel processing facilities supply matte and sulfate intermediates to Chinese and Japanese alloy smelters. High-pressure acid leach operations face escalating sulfur and energy input costs compressing margins for battery-grade nickel output. Morowali and Weda Bay industrial parks concentrate HPAL capacity with captive port infrastructure.
Battery Alloys Market Competitive Environment
Player mix skews toward diversified mining conglomerates with captive feedstock positions and specialized cathode material processors with OEM qualification relationships. Tier separation emerges between integrated refiners controlling Indonesian laterite flows and European processors building circular scrap infrastructure. Two dominant competitive moves define positioning: backward integration into African cobalt hydroxide and Indonesian nickel matte sources, and strategic partnerships with automotive cell manufacturers to secure volume commitments ahead of capacity expansion cycles.
Among diversified mining conglomerates, Glencore International AG and Freeport-McMoRan Inc. exemplify the feedstock-control archetype through positions in African cobalt and Indonesian nickel resources. BASF SE represents the chemical-processor vector with European refining presence qualifying for EU Battery Regulation compliance. Panasonic Corporation anchors the electronics-integrated tier, leveraging cathode material relationships built through consumer battery supply chains.
| Leading Market Players |
|---|
| Panasonic Corporation |
| BASF SE |
| Umicore |
| Johnson Matthey plc |
| Sumitomo Metal Mining Co., Ltd. |
| JFE Steel Corporation |
| Glencore International AG |
| Freeport-McMoRan Inc. |
| American Battery Materials Corporation |
| Others |
Value Chain & Pricing Dynamics
High-nickel cathode chemistry substitution for cobalt-heavy legacy formulations simultaneously concentrates supply geography in Indonesian laterite processing corridors and compresses pricing power among alloy processors lacking captive nickel matte positions. This input shift forces buyers to absorb HPAL cost volatility while rewarding smelters with integrated Indonesian operations.
Pricing Analysis
Long-term offtake contracts with London Metal Exchange indexation dominate cathode precursor procurement. Price differentiation hinges on battery-grade purity certification under China's MIIT GB standards and volume scale commitments from Jiangsu province cathode plants. Cost compression in nickel sulfate runs through escalating sulfur and energy inputs at Indonesian HPAL facilities. Grid-scale energy storage developers exhibit highest price sensitivity, while automotive OEMs prioritize qualification security over unit economics.
Supply Chain Analysis
Indonesia and the Democratic Republic of Congo anchor raw material supply for battery alloy production. Nickel laterite and cobalt hydroxide feedstock draws from Morowali industrial park capacity and Glencore-controlled African flows. Single-source vulnerability concentrates in DRC cobalt hydroxide intermediates. Distribution runs through direct long-term contracting between cathode precursor manufacturers and qualified smelters, displacing spot market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The battery alloys market functions as a defensive-moat industry where regulatory entrenchment—specifically EU Battery Regulation recycled-content mandates and carbon footprint declarations—creates switching costs that lock automotive OEMs into qualified supplier relationships.
For Market Incumbents: Consolidate captive feedstock positions through backward integration into Indonesian laterite processing and African cobalt hydroxide sourcing. Expand hydrometallurgical precipitation capacity in Belgium and Poland to preserve EU automotive qualification access against Asian competitors lacking continental refining presence. Prioritize talent acquisition in rare earth and battery metals process engineering to address tightening expertise pools. For New Entrants and Emerging Players: Lead with solid-state battery prototype programs targeting uncontracted demand from Japanese and German automotive cell development labs. Penetrate aluminum alloy cell housing and busbar applications where pack-level weight reduction priorities create margin pools outside established cathode active material competition. Establish qualification relationships with North American EV platform engineers leveraging IRA domestic content credits. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European alloy processors building circular scrap infrastructure to satisfy EU Battery Regulation thresholds. Five-to-ten year viability favors targets with Indonesian nickel integration and qualified precursor relationships with CATL or BYD supply chains. Monitor carbon border adjustment mechanism implementation as inflection indicator for Asian supplier exclusion risk from premium automotive segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indonesian Laterite | Captive nickel matte supply secures margin protection against HPAL cost inflation at Morowali facilities. |
| Circular Scrap Infrastructure Buildout | EU Battery Regulation recycled-content mandates require certified feedstock chains for automotive qualification. |
| Solid-State Battery Powder Metallurgy Investment | Gas atomization capacity addresses uncontracted demand from Toyota and QuantumScape development programs. |
| North American Precursor Qualification | IRA critical mineral credits create pull-through for domestic nickel and cobalt feedstock into alloy production. |
| Dual Carbon Compliance Documentation Systems | Parallel MIIT GB standards and EU Battery Regulation traceability requirements determine import eligibility. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from diversified mining conglomerates, and EU regulatory submissions. Primary interviews encompassed cathode precursor procurement managers at Chinese and South Korean cell manufacturers, hydrometallurgical process engineers at Indonesian HPAL facilities, and regulatory affairs leads at European alloy processors. Bottom-up demand modeling triangulated against top-down supply capacity assessments across Indonesian laterite corridors and African cobalt hydroxide flows.
Segmentation dimensions modeled span alloy type, application, end user, and production method across the analysis window. The analytical framework incorporated cathode chemistry evolution toward high-nickel NMC compositions, pack-level weight reduction specifications, and utility-scale energy storage procurement patterns. CAGRs derived from volume-weighted trajectory analysis of precursor plant capacity announcements and OEM platform electrification roadmaps.
Forecasts assume regulatory continuity in EU Battery Regulation implementation and China's MIIT GB standard enforcement; material policy shifts in carbon border adjustments or critical mineral security designations would require re-modeling. Recalibration cycles align with material shifts in solid-state battery commercialization timelines and Indonesian HPAL cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Asia-Pacific Metal Casting Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Prepreg Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Nitinol Market