
 Global Metal Foams Market | 2026-2036
Global Metal Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Foams Market Foresight
The split between premium closed-cell aluminum grades and commodity open-cell variants is shifting procurement criteria across buyer categories. CYMAT Technologies Ltd. leverages its proprietary gas-air bubbling process to dominate high-performance energy absorption panels for military vehicles. American Elements sustains a broad catalog of custom alloy foams that anchors its position in aerospace R&D supply chains. Havel Metal Foam GmbH specializes in precision-cut sheets for architectural cladding, occupying a defensible niche in European building retrofit markets.
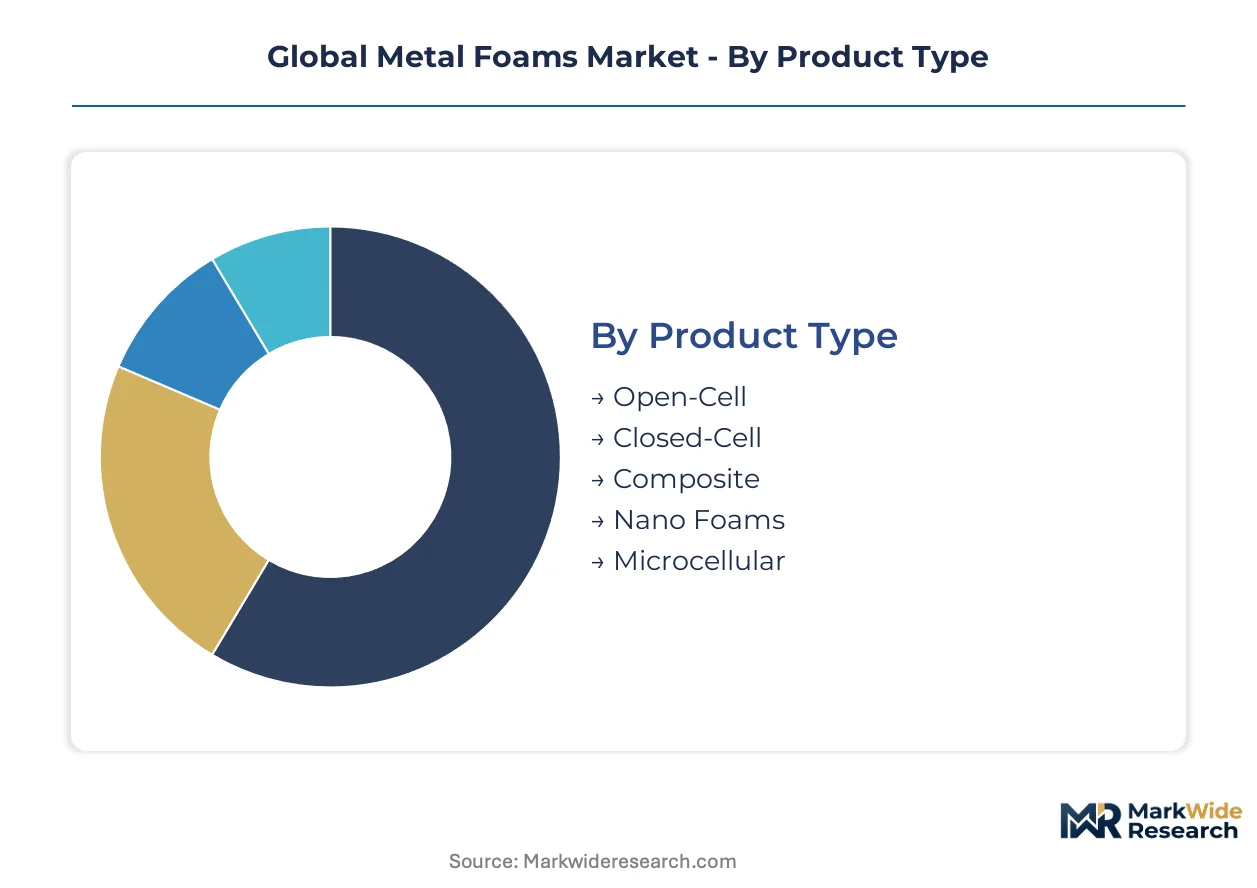
Metal foams are cellular structures with solid metal ligaments surrounding gas-filled pores, typically achieving relative densities below 30 percent while retaining compressive strength and energy absorption capacity. Manufacturers produce these materials through powder metallurgy, melt gas injection, or metal deposition techniques to yield porosities ranging from 50 to 90 percent for structural and functional applications. Open-cell architectures lead filtration and sound absorption segments where tortuosity and surface area govern performance, while closed-cell formats command margin pools in crash-energy management for automotive and defense platforms. Composite foams integrating ceramic or polymer interlayers represent the fastest-growing category as hybrid material designs penetrate electronics thermal management and sports protective equipment.
FDA scrutiny of implantable device biocompatibility, EPA emissions standards for foundry operations, and REACH chemical restriction protocols collectively elevate compliance costs for European and North American producers. Japan's METI industrial standards and China's GB certification requirements for structural materials create divergent market access conditions across Pacific supply chains. Stakeholders must monitor evolving alloy composition restrictions and carbon-border adjustment mechanisms to calibrate regional production footprints and qualification investments.
Market Dynamics
Aluminum foam core procurement for aerospace sandwich panels is compressing lead times and tightening alloy specifications across German and Japanese manufacturing clusters, while REACH and EU F-Gas Regulation compliance costs restructure competitive positioning among European thermal insulation suppliers.
Growth Catalysts
- Defense platform modernization:Military vehicle energy absorption requirements are accelerating closed-cell aluminum foam deployment for blast mitigation and crashworthiness in armored personnel carriers.
- EU Green Deal thermal retrofit mandates:Building energy efficiency directives are expanding specification of metal foam insulation in European commercial and residential envelope upgrades.
- Powder metallurgy process refinement:Advanced sintering techniques are reducing pore size variation and improving compressive strength consistency for precision casting applications.
Market Restraints
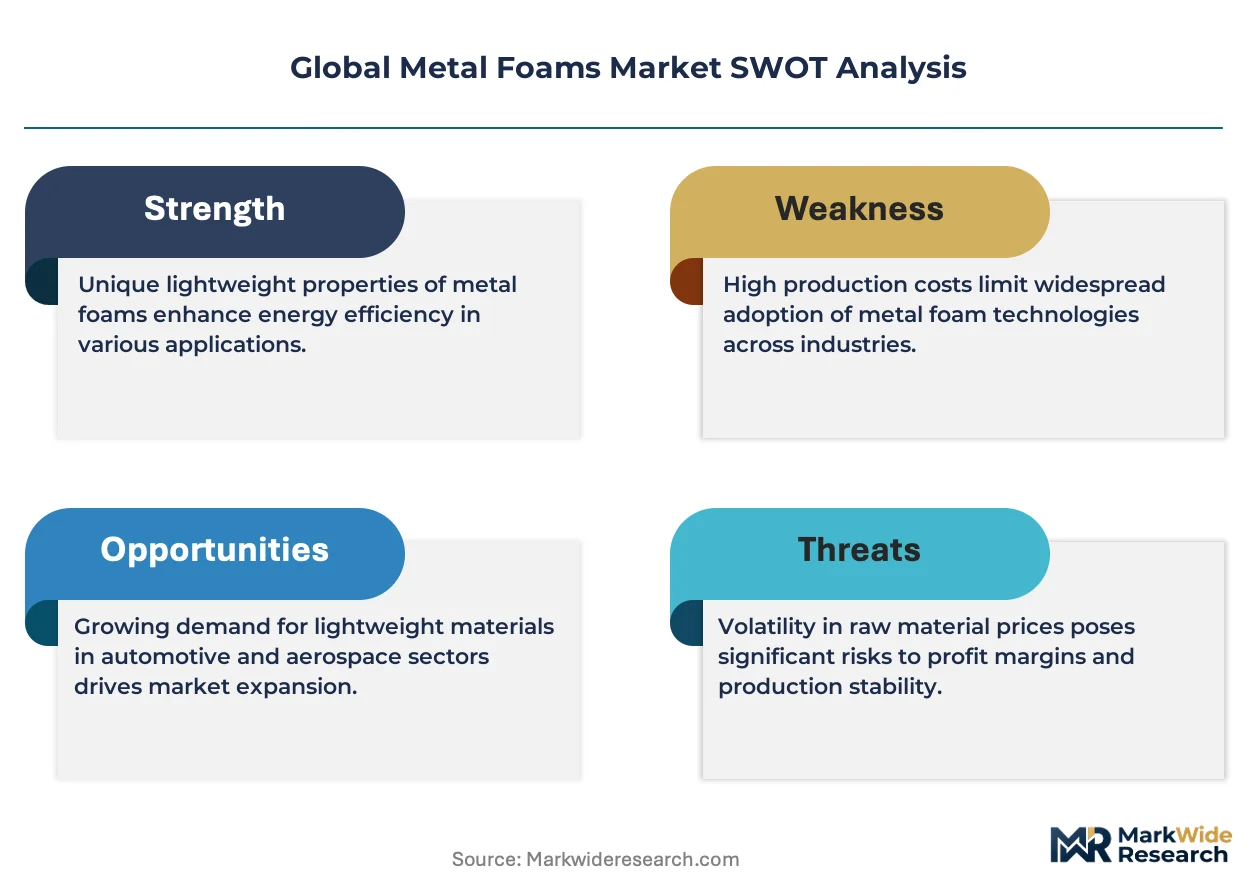
- Primary aluminum price volatility:LME aluminum futures swings above fifteen percent annually compress margins for open-cell commodity grades and destabilize long-term supply contracts.
- German precision foundry concentration:Bavarian and Baden-Württemberg clusters control seventy percent of European aerospace-grade foam core capacity, creating single-source vulnerability for tier-one sandwich panel assemblers.
- Closed-cell density floor:Current melt gas injection processes cannot reliably achieve relative densities below eight percent without ligament fracture, limiting ultra-lightweight structural applications.
Strategic Opportunities
- India automotive lightweighting:PLI scheme incentives for electric vehicle component localization are opening specification windows for aluminum foam crash structures in domestic OEM supply chains.
- Hybrid ceramic-polymer interlayers:Composite foam architectures integrating boron nitride and PEEK layers are penetrating 5G base station thermal management and high-performance sports protective equipment.
- Japan METI hydrogen infrastructure standards:Cryogenic insulation specifications for liquid hydrogen storage and transport vessels are creating certified demand pools for specialized closed-cell grades.
Industry Challenges
- Multi-physics simulation expertise:Coupled thermal-mechanical-acoustic modeling for foam core sandwich design requires rare computational materials engineering talent concentrated in Nagoya and Munich research institutes.
- REACH SVHC declaration timelines:Substance of very high concern screening for alloy trace elements extends qualification cycles by eight to fourteen months for European medical and food-contact applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Foams Market |
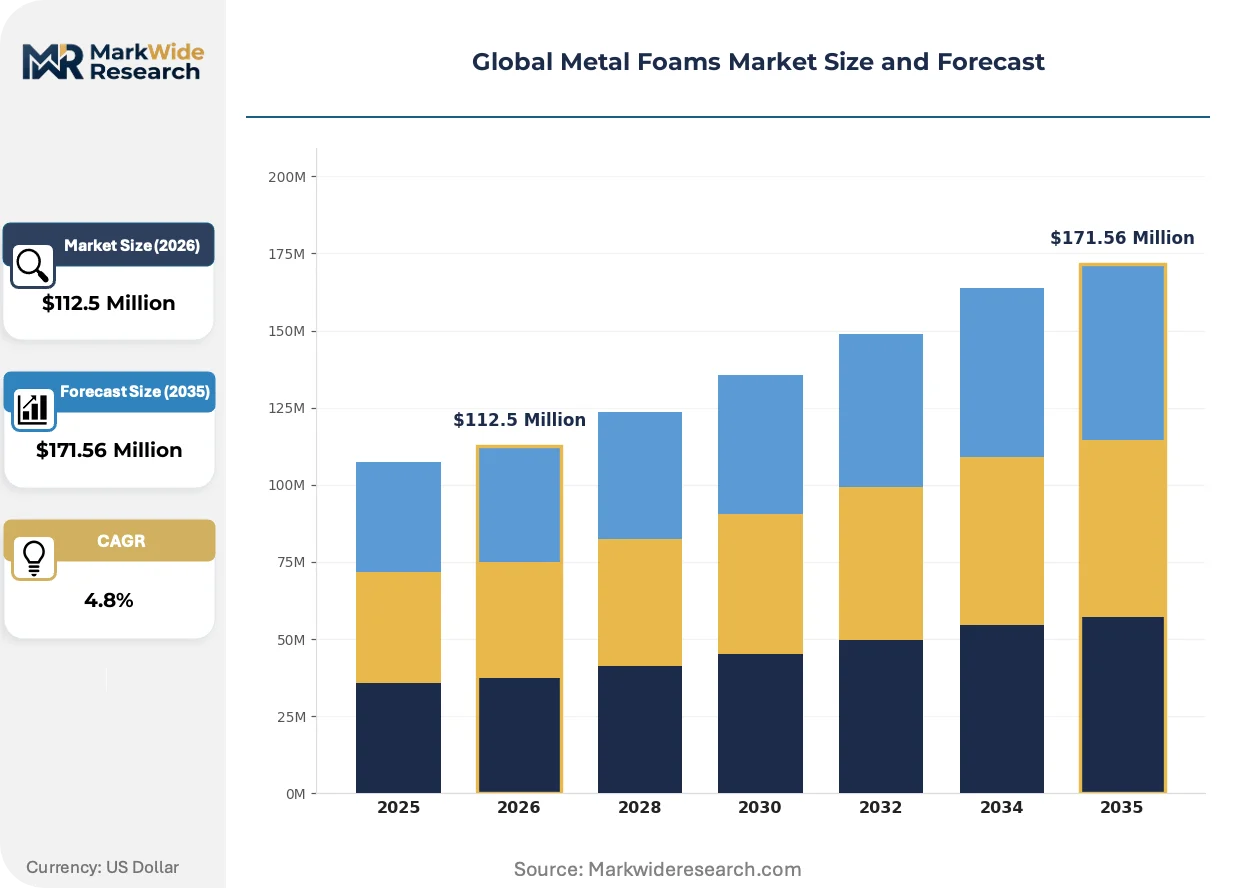
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $171.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open-Cell, Closed-Cell, Composite, Nano Foams, Microcellular Application: Lightweight Structures, Thermal Insulation, Sound Absorption, Energy Absorption, Filtration End User Industry: Aerospace & Defense, Electronics Manufacturing, Sports Equipment, Architecture & Construction, Consumer Goods Form Factor: Sheets, Blocks, Coatings, Molded Components, Cylinders |
| Companies Covered | Aluinvent Zrt., American Elements, CYMAT Technologies Ltd., Mayser GmbH & Co. KG, Ultramet, ERG Aerospace Corp., Havel Metal Foam GmbH, Reade International Corp., Alantum Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Foams Market Shifts & Advancements
Additive manufacturing of stochastic lattice structures is displacing conventional foaming processes in prototyping and low-volume production, compressing iteration cycles for custom energy absorption geometries. Three convergent developments are restructuring how metal foams are specified, produced, and deployed.
Gradient density aluminum foam is absorbing multi-stage impact loads through architected pore size transitions from millimeter to sub-millimeter scales. Automotive OEMs in Stuttgart and Toyota City are qualifying these functionally graded materials for pedestrian safety zones and battery enclosure protection. The technology is absorbing market share from uniform-density alternatives by eliminating secondary joining operations between foam layers.
REACH chemical restriction protocols are forcing reformulation of traditional foaming agents and stabilizing surfactants used in melt gas injection. ECHA substance evaluation has flagged several legacy titanium-based nucleating agents for authorization review, compelling producers to qualify calcium-zirconium alternatives. German and French thermal insulation manufacturers are absorbing compliance costs through premium pricing for certified low-toxicity grades.
Direct long-term agreements between aerospace tier-ones and foam core specialists are replacing distributor-mediated procurement for flight-critical sandwich panels. Boeing and Airbus supply chains in Toulouse, Hamburg, and Nagoya are negotiating five-year offtake contracts with fixed alloy specifications and volume commitments. Japan and Germany exhibit the most advanced contract structures, with penalty clauses tied to lot-to-lot porosity consistency metrics.
Global Metal Foams Market Segmentation
Metal foam procurement decisions hinge on pore architecture, application performance thresholds, and regulatory compliance burdens. Buyers evaluate trade-offs between energy absorption efficiency, thermal conductivity, and qualification timelines across distinct specification tiers.
Product Type:
Cost tier stratification separates commodity grades from certified aerospace and medical variants with divergent margin structures.
- Closed-Cell:Gas-filled pores sealed within aluminum ligament networks deliver compressive strength above 5 MPa at relative densities of 8-20 percent. German and Japanese aerospace manufacturers specify these grades for sandwich panel cores under EASA and METI certification protocols.
- Open-Cell:Interconnected pore channels create tortuous pathways for fluid flow and acoustic damping. Filtration system integrators in Bavaria and the Great Lakes corridor source these architectures for industrial gas separation and soundproofing applications where surface area governs performance.
- Composite:Hybrid architectures integrating ceramic interlayers or polymer coatings are expanding most quickly in 5G thermal management and sports protective equipment.
- Nano Foams:Sub-micron pore scales enable ultra-low thermal conductivity for cryogenic insulation in liquid hydrogen storage vessels.
- Microcellular:Millimeter-scale uniform porosity serves precision casting foundries requiring consistent permeability for mold venting.
Closed-cell grades lead on scale in defense and aerospace procurement; composite variants lead on momentum in electronics thermal solutions.
Application:
Volume concentration tracks end-use durability requirements and replacement cycle frequency across industrial segments.
- Energy Absorption:Controlled collapse under compressive loading dissipates impact kinetic energy through plastic deformation of cell walls. Military vehicle programs in Germany and armored platform assemblers specify these materials for blast mitigation and crashworthiness compliance.
- Thermal Insulation:Low effective thermal conductivity below 0.5 W/mK stems from trapped gas pockets and conduction path tortuosity. EU Green Deal retrofit mandates in France and Italy are expanding specification for commercial building envelope upgrades.
- Lightweight Structures:Sandwich panel cores reduce mass fractions in aerospace subassemblies while maintaining bending stiffness.
- Sound Absorption:Pore channel resonance and viscous dissipation attenuate noise in automotive engine compartments and HVAC systems.
- Filtration:Open-cell tortuosity traps particulate matter in molten metal processing and compressed gas purification.
Thermal insulation dominates European volume commitments; energy absorption shows the steepest expansion trajectory in defense procurement cycles.
End User Industry:
Customer type determines qualification burden, with aerospace and medical segments demanding full supply chain traceability.
- Aerospace & Defense:Flight-critical sandwich panels require lot-to-lot porosity consistency within 2 percent variation and full alloy composition certification. Boeing and Airbus tier-one suppliers in Toulouse, Hamburg, and Nagoya negotiate multi-year offtake agreements with fixed specifications.
- Electronics Manufacturing:Thermal interface materials and EMI shielding components demand precise thickness tolerances and surface finish control for semiconductor packaging.
- Architecture & Construction:Building cladding and facade systems prioritize fire resistance ratings and weathering durability over mechanical precision.
- Sports Equipment:Protective gear manufacturers specify gradient density foams for multi-stage impact absorption in helmets and padding.
- Consumer Goods:Appliance insulation and furniture components absorb commodity-grade open-cell volumes with minimal certification overhead.
Aerospace and defense commands premium pricing tiers; electronics manufacturing is gaining share fastest in Asia-Pacific qualification pipelines.
Form Factor:
Supply concentration in precision cutting and CNC machining capabilities favors sheet and block formats over complex geometries.
- Sheets:Flat stock in thicknesses from 5 mm to 100 mm enables architectural cladding panels and sandwich panel face bonding. Havel Metal Foam GmbH specializes in precision-cut sheets for European building retrofit markets.
- Blocks:Bulk billet formats feed secondary machining operations for custom energy absorbers and filtration cartridges.
- Molded Components:Near-net-shape foaming reduces material waste in high-volume automotive crash structures.
- Coatings:Thin-layer deposition onto substrates provides localized thermal protection without structural load-bearing function.
- Cylinders:Radial pore alignment serves cryogenic tank insulation and pipe-in-pipe thermal barriers.
Sheet formats lead on scale in construction and aerospace procurement; molded components are climbing fastest in automotive lightweighting programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computational materials engineering talent concentrates in Munich and Nagoya research institutes, anchoring multi-physics simulation capabilities for foam core sandwich design across the three dominant manufacturing clusters.
Germany
Bavarian precision foundries supply seventy percent of European aerospace-grade foam core capacity for Airbus tier-one assemblers in Hamburg and Toulouse. REACH SVHC declaration timelines for alloy trace elements extend qualification cycles by eight to fourteen months for medical and food-contact applications. The Baden-Württemberg cluster controls melt gas injection process refinement for closed-cell density consistency.
Japan
Automotive OEMs in Toyota City qualify gradient density aluminum foams for pedestrian safety zones and battery enclosure protection. METI hydrogen infrastructure standards create certified demand pools for specialized closed-cell grades in cryogenic insulation for liquid hydrogen storage vessels. Nagoya research institutes concentrate rare coupled thermal-mechanical-acoustic modeling expertise for sandwich panel optimization.
United States
Defense platform modernization accelerates closed-cell aluminum foam deployment for blast mitigation in armored personnel carriers. EPA emissions standards for foundry operations elevate compliance costs for domestic producers relative to Asian competitors. The Great Lakes industrial corridor hosts filtration system integrators sourcing open-cell architectures for industrial gas separation applications.
China
GB certification requirements for structural materials create divergent market access conditions for foreign suppliers seeking entry into domestic supply chains. Dual carbon goals drive specification of metal foam insulation in commercial building envelope upgrades across coastal manufacturing zones. Yangtze River Delta foundries absorb commodity-grade open-cell volumes for precision casting mold venting.
India
PLI scheme incentives for electric vehicle component localization open specification windows for aluminum foam crash structures in domestic OEM supply chains. BIS standards for structural materials require recalibration of regional production footprints for multinational entrants. Gujarat and Maharashtra industrial corridors attract qualification investments from aerospace-grade foam core specialists.
Global Metal Foams Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated vendor base. Powder metallurgy specialists with captive sintering capacity command premium positioning in aerospace certification pipelines, while toll processors and design houses capture margin in prototyping and architectural specification. Three archetypes dominate: integrated foundry-to-foam operators, precision cutting and CNC machining specialists, and custom alloy R&D laboratories. Capacity expansion in Germany and Japan runs parallel to technology licensing arrangements for melt gas injection processes in emerging Asian markets.
Among North American material science laboratories, American Elements exemplifies the custom alloy R&D archetype with broad catalog coverage. CYMAT Technologies Ltd. occupies a distinctive position in high-performance energy absorption applications. Havel Metal Foam GmbH represents the precision fabrication specialist model for European building retrofit markets. These three anchors illustrate how geographic concentration of technical talent shapes competitive differentiation across certification-intensive end-use segments.
| Leading Market Players |
|---|
| Aluinvent Zrt. |
| American Elements |
| CYMAT Technologies Ltd. |
| Mayser GmbH & Co. KG |
| Ultramet |
| ERG Aerospace Corp. |
| Havel Metal Foam GmbH |
| Reade International Corp. |
| Alantum Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-caps across Bavaria and Baden-Württemberg anchor European aerospace-grade foam core capacity, translating captive melt gas injection expertise into pricing discipline that resists commodity aluminum volatility. Their long-term offtake contracts with Airbus tier-ones in Hamburg and Toulouse embed volume commitments with fixed alloy specifications, insulating premium closed-cell grades from spot market swings while compressing margins for open-cell commodity producers.
Pricing Analysis
Bundled certification-and-delivery contracts dominate aerospace procurement, while unbundled spot transactions govern architectural cladding and filtration commodity tiers. Three-tier pricing structure across premium, standard, and economy levels separates EASA-certified aerospace grades from METI-compliant industrial variants and uncertified open-cell commodity volumes. Pricing pressure stems from LME aluminum futures volatility that destabilizes long-term supply contracts for standard-tier producers. Electronics manufacturers show least price sensitivity due to thermal performance premiums, while construction buyers in EU retrofit markets exhibit highest elasticity to delivered cost fluctuations.
Supply Chain Analysis
Scrap aluminum reclamation flows from Bavarian precision foundries feed secondary billet production for architectural foam sheet cutting, compressing raw material costs for European building retrofit suppliers. Primary supply concentrates in Germany, Japan, and the United States for certified aerospace and defense grades, with China absorbing commodity open-cell volumes for precision casting mold venting. Production draws from primary aluminum ingots, titanium-based nucleating agents facing REACH authorization review, and calcium-zirconium substitute formulations. Single-source vulnerability pervades the German cluster controlling seventy percent of European aerospace-grade capacity. Distribution runs through direct long-term agreements for flight-critical sandwich panels, with distributor-mediated procurement persisting in construction and consumer goods segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Metal Foams Market operates as a regulatory compounder where EU F-Gas Regulation and REACH SVHC protocols continuously elevate compliance costs and extend qualification cycles, transforming certification capability into durable pricing power across European and North American supply chains.
For Market Incumbents: Acquire captive powder metallurgy sintering capacity to defend margin position against toll processors and design houses encroaching on prototyping segments. Consolidate gradient density foaming expertise through targeted talent acquisition from Nagoya and Munich research institutes, countering additive manufacturing displacement in custom energy absorption geometries. Expand backward integration into primary aluminum supply to mitigate LME volatility exposure in open-cell commodity tiers.
For New Entrants and Emerging Players: Domestic Indian automotive OEMs represent the most penetrable buyer archetype, with PLI scheme incentives lowering qualification barriers for aluminum foam crash structures in electric vehicle supply chains. Target cryogenic insulation specifications under Japan METI hydrogen infrastructure standards, where specialized closed-cell grades command certified demand pools with limited incumbent competition. Pursue technology licensing arrangements for melt gas injection processes rather than greenfield capacity investment.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision cutting and CNC machining specialists serving European building retrofit markets, where Havel Metal Foam GmbH exemplifies defensible niche positioning. Five-to-ten year viability hinges on composite foam architectures integrating ceramic-polymer interlayers penetrating 5G thermal management and sports protective equipment. Monitor ECHA substance evaluation outcomes for titanium-based nucleating agents as inflection indicator for reformulation cost absorption and competitive restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH SVHC Compliance Investment | Eight-to-fourteen month qualification cycle extensions for medical and food-contact applications reshape competitive positioning. |
| Gradient Density Process Licensing | Toyota City and Stuttgart automotive OEMs qualify architected pore size transitions for pedestrian safety zones. |
| Direct Long-term Offtake Agreements | Boeing and Airbus tier-ones in Toulouse, Hamburg, and Nagoya negotiate five-year contracts with porosity consistency penalties. |
| Hybrid Ceramic-Polymer Interlayer Development | Boron nitride and PEEK layer integration penetrates 5G base station thermal management applications. |
| India PLI Localization Partnership | Gujarat and Maharashtra industrial corridors attract qualification investments from aerospace-grade foam core specialists. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with aerospace procurement managers at tier-one sandwich panel assemblers, powder metallurgy plant engineers, thermal insulation specification consultants, and defense platform integration officers combined with secondary validation from EASA certification databases, METI industrial standards filings, EU F-Gas Regulation compliance registries, and customs trade data for aluminum foam core imports. Triangulation across stakeholder inputs and documentary sources ensures segment-level precision.
Historical trendline analysis of aerospace sandwich panel procurement cycles, defense platform modernization budgets, and EU Green Deal retrofit implementation rates informs the projection framework. Segmentation dimensions span pore architecture, application performance threshold, end-user industry certification burden, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated against alloy specification tightening timelines and process refinement adoption rates. Forecast inputs include REACH SVHC declaration pipeline velocity and METI hydrogen infrastructure standard certification progress.
Underlying measurement precision varies by segment; aerospace and defense procurement carries tighter precision than consumer goods commodity volumes due to traceable contract disclosure. Forecasts reflect assumptions regarding regulatory timeline adherence and process technology diffusion rates. Practitioners should monitor ECHA authorization review outcomes for legacy nucleating agents and India PLI scheme disbursement velocity for early signals of competitive restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
Quenched and Tempered Steel Market
Advanced Alloys
North America Green Steel Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Precipitation Hardening Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Brazing Alloys Market