
 India Carbon Black Market | 2026-2036
India Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
India Carbon Black Market Insights
Direct supply contracts between carbon black producers and tire original equipment manufacturers are reshaping procurement patterns across India. Birla Carbon leverages its integrated manufacturing footprint to sustain long-term supply agreements with major automotive hubs. Phillips Carbon Black Limited anchors its position through dedicated port-linked facilities on the eastern coast. Epsilon Carbon Private Limited competes by specializing in high-structure grades for performance tire applications.
Carbon black consists of elemental carbon produced through the incomplete combustion or thermal decomposition of hydrocarbons, with primary particle sizes ranging from 10 to 100 nanometers and surface areas between 20 and 150 square meters per gram, functioning mainly as a reinforcing filler and pigment in rubber and polymer systems. The N330 and N550 furnace grades dominate volume flows into tire manufacturing, where structural properties determine tread wear and rolling resistance performance. Coatings and plastics applications are gaining traction as downstream formulators seek specialized conductivity and UV-protection grades.
The Bureau of Indian Standards mandates quality certification under IS 4589 for rubber-grade carbon black, while the Central Pollution Control Board enforces emission norms that constrain furnace black production economics. The Petroleum and Explosives Safety Organization regulates feedstock storage and handling protocols at manufacturing sites. Stakeholders must monitor feedstock cost volatility and evolving BIS specifications to align capacity expansion with qualified product tiers.

Market Dynamics
The Bureau of Indian Standards' tightened IS 4589 certification requirements are compressing the qualified supplier base while domestic tire capacity expansion accelerates feedstock competition across the western industrial corridor.
Growth Catalysts
- Automotive cluster expansion:Tire manufacturers in Gujarat and Maharashtra are scaling furnace black offtake as domestic vehicle production rises, creating dedicated demand anchors for regional carbon black plants.
- BIS quality mandate:The Bureau of Indian Standards' stricter IS 4589 norms for rubber-grade carbon black are filtering out substandard imports and consolidating volume toward certified domestic producers.
- Feedstock infrastructure:Port-linked carbon black facilities on India's eastern and western coasts are reducing inland logistics costs for imported petroleum feedstock.
Market Restraints
- Feedstock cost volatility:Fluctuating crude oil-derived petroleum feedstock prices compress margin predictability for furnace black producers operating on thin conversion spreads.
- Emission compliance burden:The Central Pollution Control Board's furnace black emission norms raise capital intensity for particulate capture and sulfur recovery systems.
- Import dependency for specialty grades:High-structure conductivity and UV-protection carbon blacks for coatings and plastics remain concentrated in overseas supply chains.
Strategic Opportunities
- Specialty grade localization:Underpenetrated high-structure grades for performance tire treads and industrial rubber goods offer white space for domestic technical upgrades.
- Coatings conductivity demand:Downstream formulators in automotive and electronics coatings are seeking qualified domestic sources of conductive carbon black.
- PLI scheme alignment:India's Production Linked Incentive scheme for advanced chemistry cell batteries creates adjacent demand for conductive additives in electrode formulations.
Industry Challenges
- Process engineering talent scarcity:Furnace black reactor design and feedstock optimization expertise remains concentrated among a narrow cohort of experienced technical specialists.
- Certification timeline compression:BIS IS 4589 qualification cycles for new product grades extend commercialization timelines amid tightening customer qualification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Carbon Black Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: N220, N330, N550, N660 Application: Tires, Coatings, Plastics, Inks End User: Automotive, Aerospace, Electronics, Industrial Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Himadri Specialty Chemical Ltd., Atlas Organics Private Limited, Birla Carbon, Epsilon Carbon Private Limited, Balkrishna Industries Limited, Phillips Carbon Black Limited, Continental Carbon India Private Limited, Ralson Shine Carbon Ltd., Cabot Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Carbon Black Market Trends and Innovations
Carbon black production technology and procurement architectures are undergoing parallel transformation as environmental compliance tightens and tire OEMs consolidate supplier relationships.
Plasma and gasification-based carbon black processes are collapsing the traditional furnace black capital cost structure for smaller-scale plants. Specialty chemical producers in Maharashtra are piloting these systems to serve regional tire compounders with lower minimum order quantities. The technology is collapsing the scale barrier that historically protected large integrated producers from niche competitors.
The Central Pollution Control Board's evolving emission norms for particulate matter and sulfur dioxide are forcing furnace black producers toward continuous emissions monitoring systems and tail gas treatment investments. Plants in Gujarat are retrofitting scrubber systems and thermal oxidizers to maintain operating permits. The western industrial corridor faces the steepest compliance cost escalation as regulator scrutiny intensifies near populated zones.
Tire original equipment manufacturers are consolidating carbon black procurement through direct supply contracts rather than distributor channels. Major automotive hubs in Chennai and Pune are negotiating multi-year offtake agreements with dedicated volume commitments and joint quality assurance protocols. This concentration is most visible in Maharashtra and Gujarat where tire production clusters sit adjacent to carbon black manufacturing capacity.
India Carbon Black Market Segmentation

Carbon black grades vary in particle structure and surface area, creating distinct performance profiles that align with specific rubber reinforcement and pigment requirements. Tire manufacturers in Maharashtra and Gujarat drive volume concentration across multiple segment categories, while specialty applications in electronics and coatings are opening new procurement channels.
Product Type:
Furnace black grades span a use-case spectrum from high-reinforcement tread compounds to semi-reinforcing industrial rubber goods, with structural properties determining load-bearing capacity and abrasion resistance.
- N220:Fine particle size with high surface area delivers superior abrasion resistance and tensile strength for heavy-duty truck tire treads. Demand concentrates at commercial vehicle production hubs in Tamil Nadu where radial tire specifications mandate premium reinforcement grades.
- N330:Intermediate structure balances processing ease with mechanical properties, making it the workhorse grade for passenger car tires. Gujarat-based tire OEMs anchor national offtake volumes through long-term supply contracts with dedicated carbon black plants.
- N550:Semi-reinforcing grade with lower structure serves carcass compounds and industrial rubber applications. Maharashtra industrial belt consumes significant volumes for conveyor belts and molded goods.
- N660:Large particle size with low surface area functions primarily as a filler for inner liners and non-critical rubber components. Cost-sensitive applications in general rubber goods favor this grade for volume formulations.
Established volume favors N330; emerging adoption favors N220 as radial truck tire specifications tighten.
Application:
Application segmentation tracks the migration from commodity rubber reinforcement toward conductivity and UV-protection functionalities in non-tire sectors.
- Tires:Tread, sidewall, and carcass compounds consume the majority of furnace black output, with structural grades determining rolling resistance and wear characteristics. Western industrial corridor plants in Gujarat and Maharashtra sit adjacent to tire manufacturing clusters, minimizing inbound logistics.
- Coatings:Conductive carbon black enables electrostatic discharge protection in automotive and electronics finishes. Formulators in Pune and Chennai seek qualified domestic sources to replace imported specialty grades.
- Plastics:UV stabilization and conductivity applications in polyethylene and polypropylene compounds are gaining specification traction. Masterbatch producers in Maharashtra pilot high-structure grades for photovoltaic cable sheathing.
- Inks:Pigment-grade carbon black delivers jetness and rheology control for printing applications. Packaging hub demand in Uttar Pradesh and West Bengal drives regional distributor networks.
Tire applications anchor current revenue; coatings and plastics are climbing the fastest as compounders diversify formulation portfolios.
End User:
End user segmentation reveals divergent qualification requirements, with automotive OEMs imposing the strictest certification protocols while industrial buyers prioritize cost efficiency.
- Automotive:Tire and automotive rubber component manufacturers enforce BIS IS 4589 certification and joint quality assurance protocols. Direct supply contracts dominate procurement, bypassing traditional distributor channels.
- Aerospace:Niche demand for high-purity grades in sealing systems and anti-static components. Stringent material traceability requirements favor established producers with documented batch history.
- Electronics:Conductive grades for battery electrodes and electromagnetic shielding are expanding with India's PLI scheme for advanced chemistry cells. Electrode formulators seek consistent particle dispersion properties.
- Industrial:Conveyor belts, hoses, and molded goods manufacturers represent price-sensitive volume demand. Rajasthan and Madhya Pradesh industrial corridors source through distributor networks with flexible minimum order quantities.
Automotive qualification standards dominate producer attention; electronics represents the steepest expansion trajectory as domestic battery manufacturing scales.
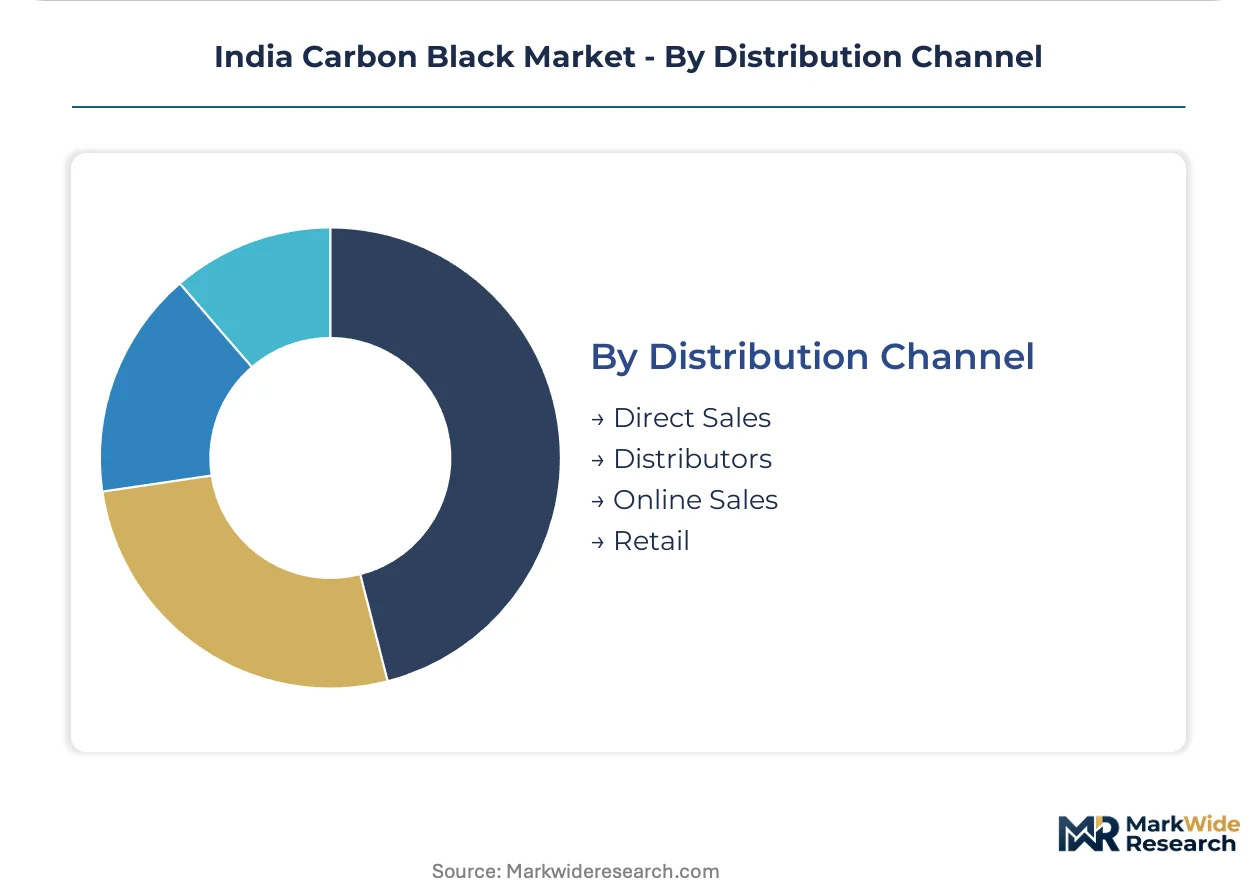
Distribution Channel:
Channel segmentation reflects the tension between consolidated direct procurement by large tire OEMs and fragmented distributor networks serving smaller compounders.
- Direct Sales:Multi-year offtake agreements with volume commitments and dedicated logistics arrangements. Major tire manufacturers in Chennai, Pune, and Ahmedabad negotiate directly with carbon black producers possessing integrated manufacturing footprints.
- Distributors:Regional stockists serve small and mid-sized rubber goods manufacturers with fragmented order patterns. Maharashtra and Gujarat host the densest distributor networks given manufacturing cluster proximity.
- Online Sales:Emerging channel for standard grades and technical documentation access. Specialty chemical platforms list carbon black alongside complementary rubber chemicals for formulation convenience.
- Retail:Minimal presence limited to small-scale repair shops and artisan rubber processors. Urban hardware markets in Delhi and Mumbai carry limited bagged inventory for immediate needs.
Direct sales capture the largest revenue share; distributor networks retain critical importance for geographic and customer segment coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust and Hazira Port complex anchor carbon black feedstock flows into India's western industrial corridor. Dedicated liquid cargo terminals handle imported petroleum feedstock for furnace black production. Rail-linked storage depots distribute finished product to tire manufacturing clusters.
Maharashtra
Pune and Mumbai host concentrated tire OEM manufacturing that drives N330 and N550 grade consumption. The Maharashtra Pollution Control Board enforces stringent particulate emission norms for furnace black plants in Thane and Raigad districts. PCMC industrial belt facilities are retrofitting continuous emissions monitoring systems to maintain operating permits amid tightening regulator scrutiny.
Gujarat
Dahej and Hazira chemical complexes sustain integrated carbon black production adjacent to petroleum refinery feedstock sources. The Gujarat Pollution Control Board mandates sulfur recovery system upgrades under revised stack emission guidelines. Mundra Port-linked facilities are expanding storage capacity to reduce inland logistics costs for coastal manufacturing plants.
Tamil Nadu
Chennai automotive hub demand concentrates on N220 high-reinforcement grades for radial truck tire specifications. The Tamil Nadu Pollution Control Board enforces Consent to Operate renewals with enhanced fugitive emission controls. Sriperumbudur-Oragadam industrial corridor plants are qualifying direct supply contracts with commercial vehicle manufacturers.
West Bengal
Haldia Port receives carbon black imports serving eastern region rubber goods manufacturers. The West Bengal Pollution Control Board monitors particulate discharge from storage and handling facilities. Durgapur-Asansol industrial belt distributors maintain regional inventory for price-sensitive conveyor belt and hose compounders.
Haryana
Manesar-Bawal automotive supplier parks generate secondary demand for carbon black in rubber components and seals. The Haryana State Pollution Control Board regulates feedstock storage tank farm emissions under Petroleum Rules compliance. IMT Manesar logistics hubs facilitate just-in-time delivery to NCR-based tire retreading operations.
India Carbon Black Market Competitive Landscape
On the supply side, the industry is consolidating around integrated producers with captive feedstock arrangements and port-linked manufacturing footprints. Three archetypes dominate: large integrated petrochemical-linked producers, mid-scale specialty grade specialists, and import-dependent trading houses serving fragmented industrial demand. Capacity expansion and direct OEM contract negotiation represent the primary competitive vectors as distributor channels lose share to dedicated supply agreements.
Among India-based integrated producers, Himadri Specialty Chemical Ltd., Birla Carbon, and Phillips Carbon Black Limited occupy positions spanning standard furnace grades through specialized reinforcement carbon blacks. These entities exemplify the scale-driven archetype through manufacturing footprints aligned with western and eastern port infrastructure. Epsilon Carbon Private Limited represents the specialty-focused tier concentrating technical grades for performance tire applications. Cabot Corporation anchors the multinational presence through technology licensing and quality certification protocols. Continental Carbon India Private Limited and Balkrishna Industries Limited sit within the diversified industrial groupings where carbon black serves captive tire manufacturing or external sales channels.
| Leading Market Players |
|---|
| Himadri Specialty Chemical Ltd. |
| Atlas Organics Private Limited |
| Birla Carbon |
| Epsilon Carbon Private Limited |
| Balkrishna Industries Limited |
| Phillips Carbon Black Limited |
| Continental Carbon India Private Limited |
| Ralson Shine Carbon Ltd. |
| Cabot Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals in Gujarat's furnace black corridor are compressing conversion margins and forcing suppliers toward volume-commitment contracts that lock in pricing floors. The Central Pollution Control Board's emission retrofit mandates are layering fixed cost burdens onto variable pricing structures, tightening the feedback loop between compliance investment and contract negotiation leverage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs carbon black procurement, with BIS IS 4589 certification tier and volume scale serving as the primary differentiation drivers. Premium grades command positioning through joint quality assurance protocols with tire OEMs, while economy tiers face price erosion from feedstock cost volatility and thin conversion spreads. Tire manufacturers in Maharashtra exhibit the highest price sensitivity due to consolidated procurement power, whereas specialty coatings formulators in Pune show tolerance for certified-grade premiums.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are emerging as competitive differentiators as working capital pressure intensifies across the value chain. Geographic supply concentration centers on India, China, and South Korea, with furnace black production drawing from imported petroleum feedstock, natural gas, and coal tar derivatives. Single-source vulnerability looms over high-structure conductivity grades for battery electrode applications. Distribution runs through direct sales channels for tire OEMs and fragmented distributor networks serving industrial rubber goods manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silica-silane coupling systems in green tire formulations represent a credible substitution threat that carbon black incumbents must neutralize through performance-grade specialization and certification depth.
For Market Incumbents: Entrench position by deepening captive feedstock arrangements at Mundra and Hazira port complexes, and accelerate BIS IS 4589 qualification for N220 high-reinforcement grades to defend against silica displacement in radial truck tire specifications. Channel control through dedicated logistics arrangements with Pune and Chennai automotive hubs reinforces contract stickiness against specialty grade imports. For New Entrants and Emerging Players: Mid-scale coatings formulators in Maharashtra and Tamil Nadu seeking conductive carbon black for automotive electrostatic discharge applications represent the most penetrable entry point. Plasma-based production systems enable lower minimum order quantities for regional compounders. A technical-service-led go-to-market approach bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across emission-compliant furnace black capacity as scrubber and thermal oxidizer investments become permit prerequisites. Target acquisition archetypes include port-linked mid-scale producers with unfunded retrofit liabilities and qualified product pipelines. The signal to watch is BIS certification timeline compression as customer qualification windows tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive petroleum feedstock supply at Dahej and Hazira complexes insulates margin from crude price volatility. |
| Emission Compliance Retrofit | Continuous emissions monitoring systems satisfy Gujarat Pollution Control Board Consent to Operate renewals. |
| Specialty Grade Localization | High-structure conductivity grades for PLI-scheme battery electrodes reduce import dependency for electrode formulators. |
| Direct Supply Agreement | Multi-year offtake contracts with Chennai and Pune tire OEMs displace distributor channel volume. |
| Port-Linked Capacity Expansion | Mundra and JNPT storage infrastructure reduces inland logistics costs for western corridor manufacturing clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to calibrate volume and pricing assumptions, including tire compound procurement managers at Gujarat and Maharashtra OEMs, carbon black plant operations directors, BIS certification specialists, and petroleum feedstock traders. Secondary validation drew from Directorate General of Commercial Intelligence and Statistics trade data, Central Pollution Control Board emission compliance filings, Bureau of Indian Standards certification registries, and Ministry of Chemicals and Fertilizers production statistics. Bottom-up capacity utilization estimates and top-down end-use consumption models were triangulated to cross-verify segment-level outputs.
Calibration against historical production and import volumes anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include furnace black grade tier, end-use application, automotive versus industrial end-user qualification requirements, and direct versus distributor channel structure. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion pipelines. Key forecast inputs encompass tire OEM production schedules and PLI scheme battery manufacturing commitments.
Practitioners should monitor feedstock cost volatility, BIS specification revisions, and emission norm enforcement intensity for early signals of forecast deviation. Macroeconomic contraction in automotive output, regulatory acceleration of silica substitution mandates, or breakthroughs in plasma-based production economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
North America Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
Europe Lime Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Methanesulfonic Acid Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market