
 Global Magnesium Market | 2026-2036
Global Magnesium Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnesium Market Outlook
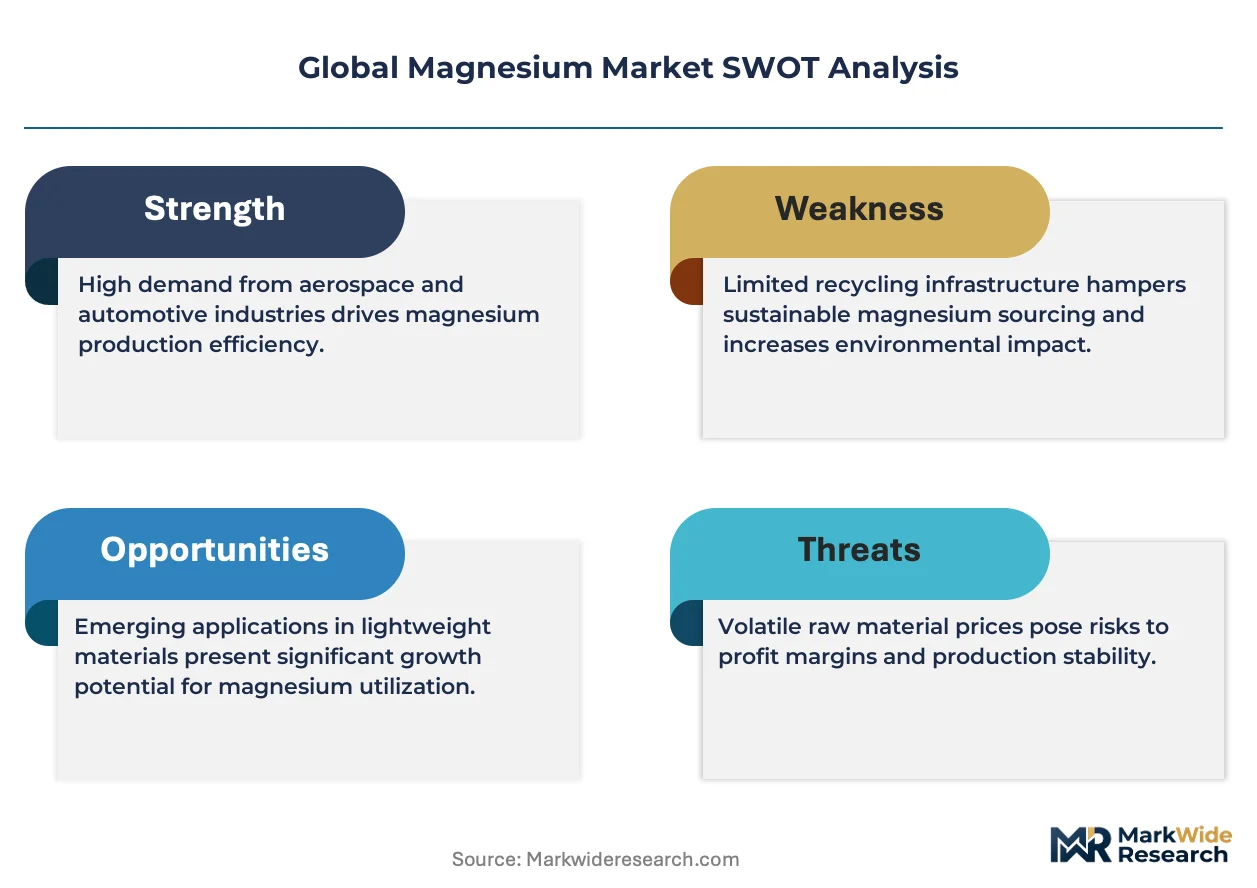
The capital-intensity divergence between electrolytic and thermal reduction players is unwinding as energy costs reshape competitive economics. US Magnesium LLC leverages captive brine resources in Utah to sustain cost-advantaged primary output. Wenxi YinGuang Magnesium Industry anchors its position through integrated dolomite mining and alloy casting in Shanxi Province. POSCO competes via specialized high-purity magnesium sheet for aerospace qualification programs.
Magnesium, the lightest structural metal at one-quarter the density of steel, serves primarily as an alloying element and reduction agent across industrial chemistry and transportation applications; commercial grades range from 99.8% pure primary ingot to AZ91D alloy with 9% aluminum and 1% zinc for die-casting. Magnesium alloys command the largest value share due to automotive and aerospace penetration, while magnesium oxide grows fastest in flame-retardant construction board formulations. Die-casting dominates volume throughput but faces margin compression from aluminum substitution in non-critical automotive brackets.
China's MEE enforces dual carbon emissions intensity targets on thermal Pidgeon-process smelters, while REACH in Europe mandates full supply-chain substance registration for magnesium alloy importers. The EU's CSRD will soon require Scope 3 emissions disclosure from automotive OEMs, directly pressuring magnesium sourcing transparency. Stakeholders must monitor energy-transition policy divergence between Chinese provincial carbon budgets and European border carbon adjustments to anticipate supply relocation.
Market Dynamics
Energy cost differentials between electrolytic and thermal reduction routes are compressing margin structures and forcing capacity relocation toward captive energy assets. Smelters with stranded renewable power or integrated fossil fuel reserves now command structural advantage over grid-dependent competitors.
Growth Catalysts
- Automotive lightweighting mandates:Germany's KBA enforces fleet CO2 reduction targets that accelerate magnesium die-casting adoption in transmission housings and seat frames. OEMs specify AZ91D and AM60 alloys for powertrain components.
- REACH substance registration:ECHA's full supply-chain disclosure requirements for magnesium alloy importers create compliance barriers that favor established European distributors with documented metallurgical certificates.
- Flame-retardant construction boards:Magnesium oxide formulations gain specification in high-rise cladding systems across Gulf Cooperation Council building codes, displacing halogenated alternatives in curtain wall assemblies.
Market Restraints
- Ferrosilicon price volatility:Thermal Pidgeon-process operators face margin erosion when Chinese ferrosilicon export tariffs spike, as Shanxi Province smelters lack backward integration into ferroalloy production.
- Aluminum substitution in non-critical brackets:Automotive Tier-1 suppliers switch to aluminum A380 alloy for cosmetic and low-load structural components, eliminating magnesium content from door handles and mirror housings.
- MEE emissions intensity enforcement:China's dual carbon targets impose hard caps on thermal reduction smelters, forcing capacity idling during provincial energy audits without compensation mechanisms.
Strategic Opportunities
- India automotive component manufacturing:PLI scheme incentives for advanced chemistry cell and electric vehicle production create localized magnesium alloy demand for battery enclosures and motor housings in Tamil Nadu and Gujarat.
- CSRD Scope 3 disclosure:EU automotive OEMs must trace magnesium sourcing emissions by 2026, creating premium pricing tiers for low-carbon primary metal with verified renewable energy inputs.
- Solid-state battery anode integration:Magnesium metal anodes interface with sulfide electrolytes in next-generation cell architectures, offering energy density advantages over graphite in prototype electric aviation powertrains.
Industry Challenges
- High-purity ingot certification timelines:Aerospace qualification programs require 18-24 month AS9100 audit cycles for magnesium sheet suppliers, locking out new entrants from Boeing and Airbus supply chains.
- Skilled pyrometallurgical workforce scarcity:Pidgeon-process furnace operation and vacuum distillation expertise concentrates among retiring technicians in Shanxi and Ningxia provinces without structured apprenticeship pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnesium Market |
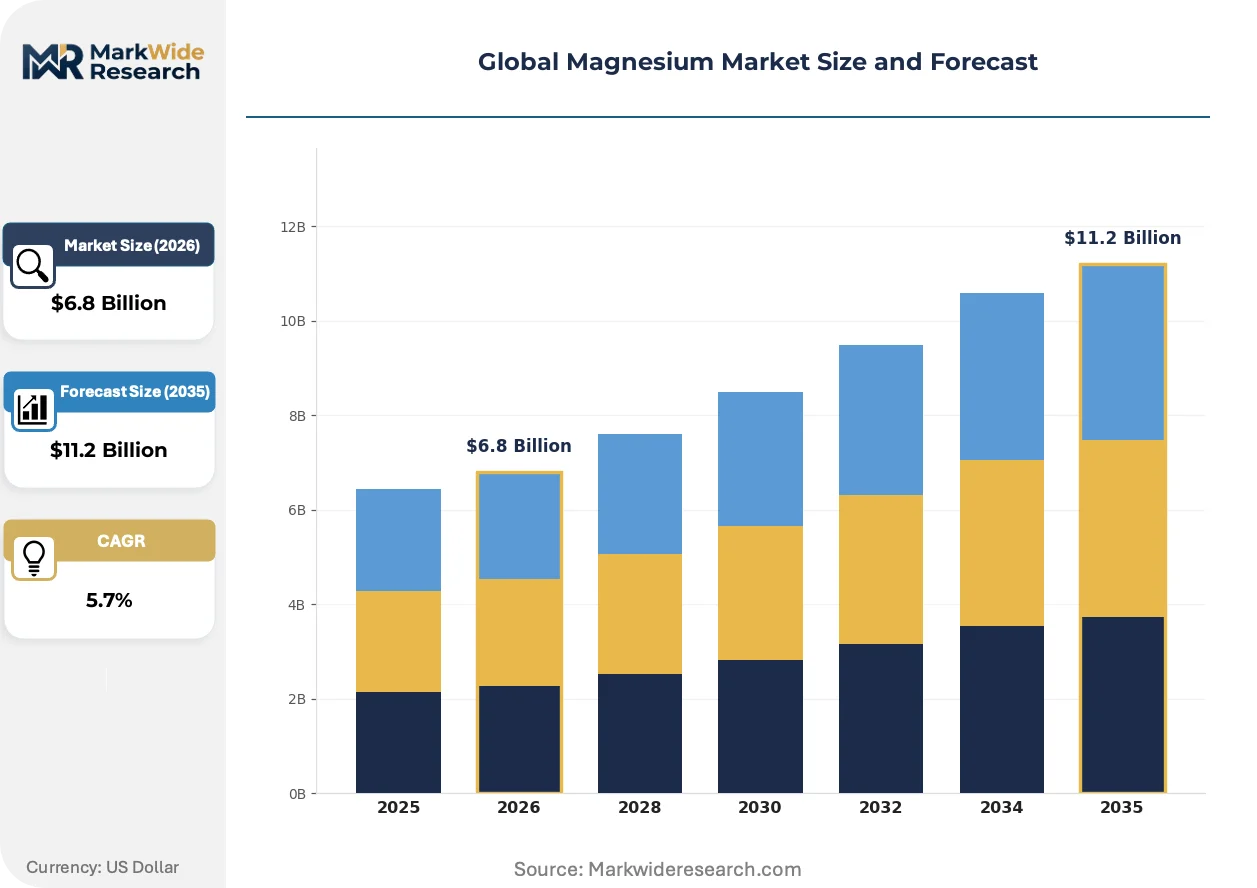
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die-Casting, Electrolytic Magnesium, Magnesium Alloys, Magnesium Oxide End Use Industry: Aerospace, Automotive, Construction, Electronics Form: Granules, Powder, Sheet, Liquid Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | US Magnesium LLC, Dead Sea Magnesium Ltd., Western Magnesium Corporation, Latrobe Magnesium, Wenxi YinGuang Magnesium Industry (Group) Co. Ltd, POSCO, Nippon Kinzoku Co. Ltd., RIMA Group, Shanxi Wenxi Yinguang Magnesium Industry Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnesium Market Strategic Shifts
Process electrification and digital metallurgical control are converging to redefine competitive economics. Smelters now instrument reduction retorts with real-time temperature and pressure telemetry to optimize yield and energy intensity.
Aluminum-free magnesium alloys are decomposing the historical AZ/AM series dominance in automotive applications. Rheinmetall and GF Casting Solutions specify MRI153A and MRI230D alloys with rare-earth additions for powertrain components operating above 150°C. These formulations eliminate high-temperature creep failure modes that limited magnesium in engine blocks, enabling structural substitution in cylinder head covers and oil pans.
The EU F-Gas Regulation phase-down of hydrofluorocarbons is tightening magnesium die-casting cell protection gas requirements. SF6 cover gas faces mandatory replacement by SO2 or NOVEC 612 blends by 2030, forcing foundries to retrofit gas recovery and abatement systems. German automotive suppliers in Baden-Württemberg pilot closed-loop SO2 recycling to maintain surface quality in high-pressure casting operations without emissions penalties.
Automotive OEMs now mandate supplier-funded inventory positioning near assembly plants, compressing traditional mill-direct procurement cycles. BMW and Mercedes-Benz require magnesium alloy distributors to hold 4-6 weeks of tailored specification stock at logistics hubs in Leipzig and Bremen. This vendor-managed inventory model transfers working capital burden upstream while insulating OEMs from Shanxi production volatility and ocean freight scheduling disruptions.
Global Magnesium Market Segmentation
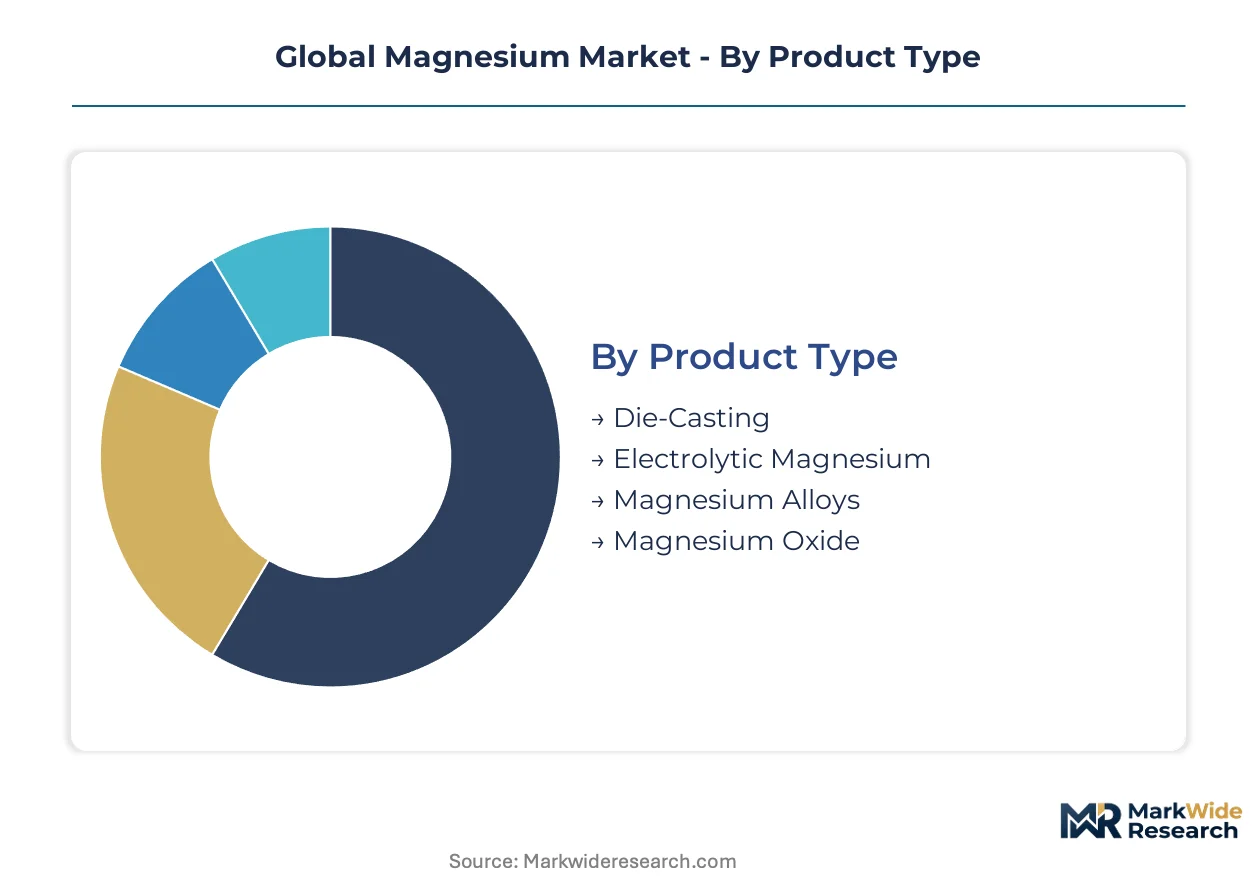
Magnesium's industrial utility spans metallurgical, chemical, and structural applications that demand divergent purity grades and physical forms. Regulatory thresholds for emissions intensity and substance registration reshape procurement patterns across each segment boundary.
Product Type:
REACH substance registration and China's MEE emissions caps create divergent compliance burdens across primary production routes versus downstream conversion products.
- Magnesium Alloys:AZ91D and AM60 formulations with aluminum and zinc additions serve die-casting specifications for powertrain housings and seat frames. Automotive OEMs in Germany source these alloys through vendor-managed inventory hubs near Leipzig and Bremen assembly plants to mitigate Shanxi supply volatility.
- Die-Casting:High-pressure injection molding of magnesium into complex geometries dominates volume throughput for transmission cases and structural brackets. The EU F-Gas Regulation mandates SF6 cover gas replacement by 2030, forcing foundries in Baden-Württemberg to retrofit closed-loop SO2 recovery systems.
- Electrolytic Magnesium:Purity grades reaching 99.8% suit reduction chemistry and specialty alloying.
- Magnesium Oxide:Refractory and flame-retardant formulations displace halogenated alternatives in Gulf Cooperation Council high-rise cladding specifications.
Die-Casting handles the majority of throughput; Magnesium Oxide is the fastest mover on share.
End Use Industry:
Customer procurement patterns cluster around emissions disclosure mandates and lightweighting engineering targets.
- Automotive:Germany's KBA fleet CO2 reduction targets accelerate magnesium substitution in transmission housings, with BMW and Mercedes-Benz specifying AZ91D for powertrain components. Tier-1 suppliers face compressed margins from aluminum A380 substitution in cosmetic brackets.
- Aerospace:AS9100 qualification cycles spanning 18-24 months lock Boeing and Airbus supply chains to incumbent high-purity sheet suppliers. POSCO competes via specialized magnesium sheet for structural applications requiring strength-to-weight ratios superior to aluminum 7075.
- Construction:Magnesium oxide boards gain specification in curtain wall assemblies under tightened fire safety codes.
- Electronics:Miniaturized housings and EMI shielding applications drive demand for thin-gauge sheet and precision die-castings.
Automotive commands the largest volume position; Construction is expanding most quickly on code-driven specification changes.
Form:
Physical state determines logistics economics and conversion yield in downstream manufacturing.
- Sheet:Rolled magnesium plate and coil serve aerospace structural panels and automotive body-in-white prototypes. Rheinmetall and GF Casting Solutions specify rare-earth modified MRI153A sheet for powertrain components operating above 150°C, eliminating historical creep failure limitations.
- Powder:Atomized and ground particulate feeds additive manufacturing and pyrotechnic applications requiring controlled burn rates.
- Granules:Desulfurization reagent for steelmaking and chemical reduction processes.
- Liquid:Molten metal delivery to integrated die-casting operations reduces remelt energy and oxidation losses.
Sheet carries premium pricing on qualification barriers; Powder is gaining share fastest on additive manufacturing adoption.
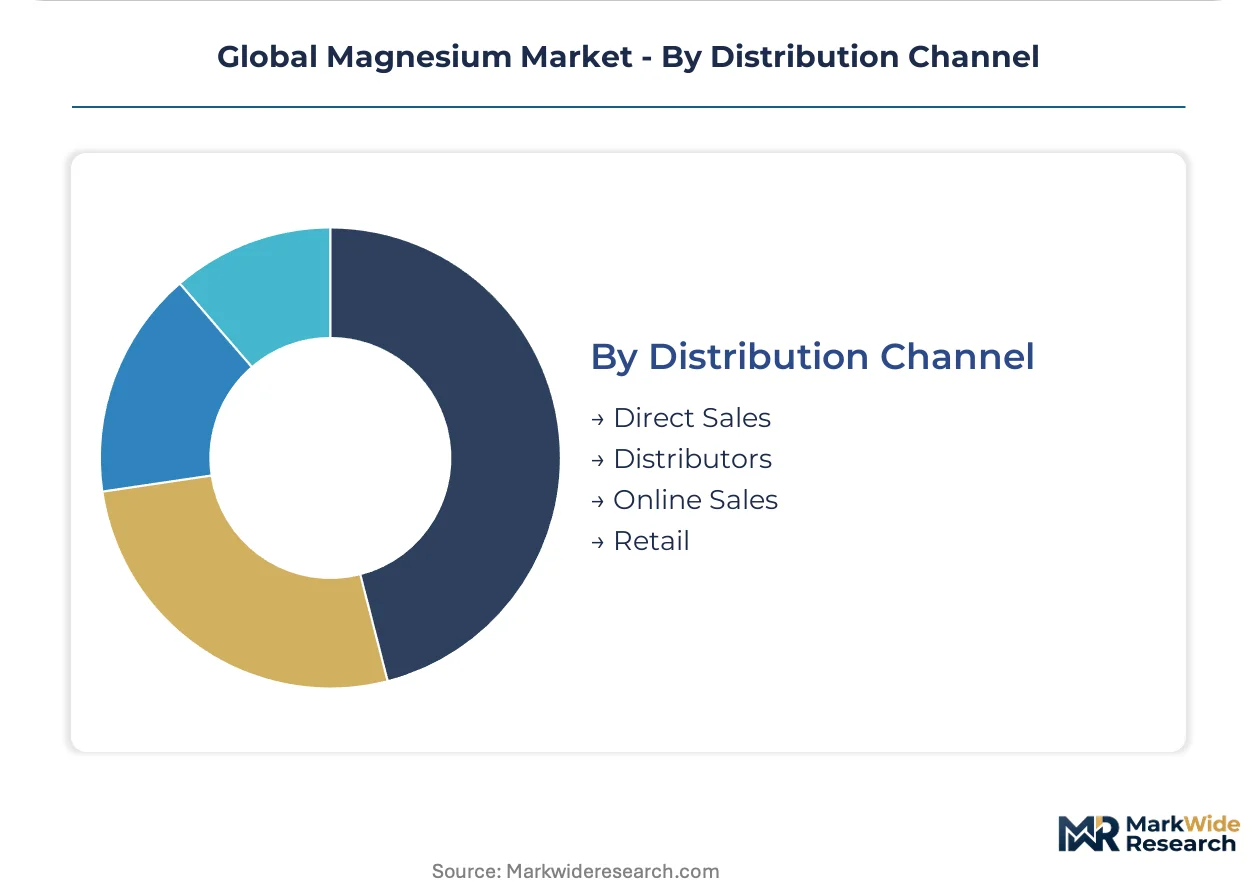
Distribution Channel:
Working capital allocation and supply assurance priorities separate procurement models across customer scale.
- Distributors:European distributors with documented REACH metallurgical certificates capture alloy procurement from automotive OEMs requiring full supply-chain substance registration. Vendor-managed inventory models transfer 4-6 weeks of specification-tailored stock burden upstream from BMW and Mercedes-Benz.
- Direct Sales:Mill-direct procurement persists for high-volume die-casters with predictable offtake and technical service requirements.
- Online Sales:Spot market access for research quantities and non-critical industrial grades.
- Retail:Limited to specialty welding and foundry supply outlets serving maintenance and repair operations.
Distributors handle the majority of alloy volume; Direct Sales maintains position in captive vertical operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price-elasticity for aerospace-grade sheet, while Chinese automotive die-casters remain highly sensitive to primary ingot fluctuations. This demand-elasticity contrast shapes regional procurement strategies and inventory positioning across the value chain.
China
Shanxi Province's captive dolomite reserves anchor thermal Pidgeon-process output for AZ91D die-casting alloys. MEE enforces dual carbon emissions intensity targets that force capacity idling during provincial energy audits. Wenxi industrial cluster concentrates primary smelting and alloy casting operations serving domestic automotive OEMs.
Germany
KBA fleet CO2 reduction targets accelerate magnesium substitution in BMW and Mercedes-Benz transmission housings. EU F-Gas Regulation mandates SF6 cover gas replacement by 2030, forcing Baden-Württemberg foundries to retrofit closed-loop SO2 recovery systems. Leipzig and Bremen logistics hubs hold 4-6 weeks of vendor-managed alloy inventory.
United States
US Magnesium LLC leverages captive brine resources in Utah for cost-advantaged electrolytic primary output. EPA emissions standards and Utah state environmental permits constrain expansion timelines. Great Salt Lake industrial corridor sustains the country's only integrated primary magnesium production.
South Korea
POSCO specializes in high-purity magnesium sheet qualification for Boeing and Airbus supply chains. MFDS and national industrial standards govern metallurgical certification for aerospace applications. Busan-Ulsan manufacturing belt hosts specialized rolling and heat-treatment facilities.
India
PLI scheme incentives for electric vehicle production create localized alloy demand for battery enclosures in Tamil Nadu and Gujarat. BIS standards and DGFT import tariffs shape procurement economics for automotive Tier-1 suppliers. Pune-Chennai industrial corridor attracts die-casting investments from multinational component manufacturers.
Global Magnesium Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with electrolytic specialists commanding purity premiums and thermal reduction operators competing on scale. The market structure tiers around three strategic groups: integrated miners with captive dolomite reserves, brine-based electrolytic producers with stranded energy assets, and specialized sheet rollers serving aerospace qualification programs. Dominant competitive moves include backward integration into ferrosilicon or dolomite mining, and geographic expansion toward automotive assembly clusters to reduce logistics costs.
Within the integrated mining tier, Wenxi YinGuang Magnesium Industry and Shanxi Wenxi Yinguang Magnesium Industry Group Co. Ltd. exemplify Chinese operators with captive upstream resources. US Magnesium LLC occupies a position among brine-based electrolytic producers with access to stranded renewable power. POSCO represents the specialized high-purity sheet segment serving aerospace qualification requirements.
| Leading Market Players |
|---|
| US Magnesium LLC |
| Dead Sea Magnesium Ltd. |
| Western Magnesium Corporation |
| Latrobe Magnesium |
| Wenxi YinGuang Magnesium Industry (Group) Co. Ltd |
| POSCO |
| Nippon Kinzoku Co. Ltd. |
| RIMA Group |
| Shanxi Wenxi Yinguang Magnesium Industry Group Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Shanxi Province smelters and German automotive OEMs lock in both supply access and price visibility for AZ91D die-casting alloys. These arrangements insulate BMW and Mercedes-Benz from spot volatility in ferrosilicon and dolomite feedstock costs while committing smelters to fixed volume floors.
Pricing Analysis
After-sales technical service contracts for magnesium alloy specification support now drive lifetime value beyond ingot sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by AS9100 aerospace certification tier and volume commitment scale. Cost compression in standard-grade automotive alloys is intensifying because aluminum A380 substitution erodes magnesium content in cosmetic brackets. Tier-1 suppliers in Germany demonstrate lowest price sensitivity for qualified aerospace sheet, while Chinese die-casters remain highly responsive to primary ingot fluctuations.
Supply Chain Analysis
Strait of Malacca transit underwrites seaborne logistics for dolomite feedstock moving from Southeast Asian quarries to Shanxi Province smelters. Supply concentrates in China, South Korea, and the United States for primary production, with downstream conversion anchored in Germany and Japan. Raw material dependencies center on ferrosilicon reductant, high-purity dolomite ore, and rare-earth alloying additions. Single-source vulnerability in Shanxi Province's thermal Pidgeon-process cluster exposes automotive supply chains to MEE emissions enforcement idling. Distribution runs through vendor-managed inventory hubs positioned near Leipzig and Bremen assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor-managed inventory and technical specification services represent a service-attach opportunity expanding faster than primary metal production. After-sales metallurgical consulting and closed-loop alloy recycling contracts now outpace ingot volume growth in margin contribution.
For Market Incumbents: Shield market position by deepening captive dolomite reserve control in Shanxi Province and accelerating AS9100 certification investment for aerospace sheet qualification. Aluminum substitution in non-critical automotive brackets threatens volume erosion in die-casting grades. Backward integration into ferrosilicon production defends margin structures against Chinese export tariff volatility. For New Entrants and Emerging Players: Closed-loop magnesium recycling and alloy re-specification services represent a service-layer gap where incumbents under-serve automotive OEMs seeking Scope 3 emissions reduction. India's PLI scheme incentives for electric vehicle production create the most penetrable geography for localized die-casting capacity. Target battery enclosure and motor housing applications with technical partnership models rather than commodity ingot competition. For Investors and Strategic Acquirers: Brine-based electrolytic producers with stranded renewable energy assets offer acquisition exposure to low-carbon primary metal premiums under EU CSRD disclosure mandates. Long-term viability hinges on energy transition policy divergence between Chinese provincial carbon budgets and European border carbon adjustments. Watch for MEE enforcement intensity in Shanxi as the inflection signal for supply relocation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrosilicon | Shanxi smelters reduce feedstock cost exposure to Chinese export tariff volatility. |
| AS9100 Aerospace Certification Investment | POSCO and specialized sheet rollers lock Boeing and Airbus supply chain positions. |
| Closed-Loop SO2 Recovery Retrofit | Baden-Württemberg foundries comply with EU F-Gas Regulation phase-down mandates. |
| Vendor-Managed Inventory Expansion | BMW and Mercedes-Benz transfer working capital burden upstream to distributors. |
| Rare-Earth Alloy Formulation Development | Rheinmetall and GF Casting Solutions enable powertrain components above 150°C. |
Study Parameters
Initial hypotheses were tested against primary input from magnesium smelter operations directors, automotive Tier-1 procurement managers, aerospace qualification engineers, and specialty alloy distributors and refined through secondary validation. Primary fieldwork drew from technical interviews across Shanxi Province industrial clusters, German automotive supply hubs, and South Korean rolling facilities. Secondary sources encompassed customs trade data for magnesium ingot and alloy movements, SEC filings from listed producers, MEE emissions disclosure records, and ECHA REACH registration databases. Bottom-up capacity and consumption estimates were triangulated against top-down industry association aggregates.
Variance decomposition across product type, end-use industry, physical form, and regional production hub shaped the analytical framework. Segmentation dimensions modeled included alloy grade tier, die-casting versus sheet conversion route, and automotive versus aerospace qualification status. CAGRs were derived from trend extrapolation of historical production and consumption patterns, adjusted for policy intervention scenarios. Forecast inputs incorporated KBA fleet CO2 target stringency, MEE dual carbon enforcement trajectories, and PLI scheme incentive uptake in India.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules and China's MEE emissions intensity caps; material policy shifts would require re-modeling of competitive economics between electrolytic and thermal reduction routes. Specific risk factors include ferrosilicon price volatility, aluminum substitution acceleration, and aerospace qualification timeline extensions. Practitioners should keep alternative scenarios live as CSRD Scope 3 disclosure implementation and solid-state battery anode commercialization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Rare Earth Elements Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Silver Mining Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Dolomite Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Diamond Market