
 Energy Efficient Powder Coatings Market | 2026-2036
Energy Efficient Powder Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Efficient Powder Coatings Market Intelligence
The accelerating transition in the automotive industry towards lightweight composites and electric vehicle components is repositioning the application landscape for these coatings. Akzo Nobel N.V. leverages its extensive R&D in low-temperature cure formulations to serve this evolving demand. Meanwhile, PPG Industries, Inc. competes on its global manufacturing scale and supply chain integration for industrial applications. The Sherwin-Williams Company specializes in architectural and consumer goods finishes, diversifying its portfolio.
Energy efficient powder coatings are solvent-free thermosetting or thermoplastic powders applied electrostatically and cured with minimal heat. These formulations are engineered to cross-link at lower temperatures, often below 150°C, to reduce energy consumption during the curing process. Within the technology segment, UV Curing represents the fastest-growing category due to its suitability for heat-sensitive materials. The automotive application segment remains the largest, but industrial applications are showing significant expansion.
Regulatory frameworks are a primary market accelerator, particularly those targeting volatile organic compounds (VOCs). The European Union's REACH regulation, the US EPA's air quality standards, and China's MEE directives on industrial emissions all incentivize the switch from liquid to powder coatings. For formulators and end-users, the critical decision path involves balancing the upfront cost of new equipment against long-term energy savings and regulatory compliance.
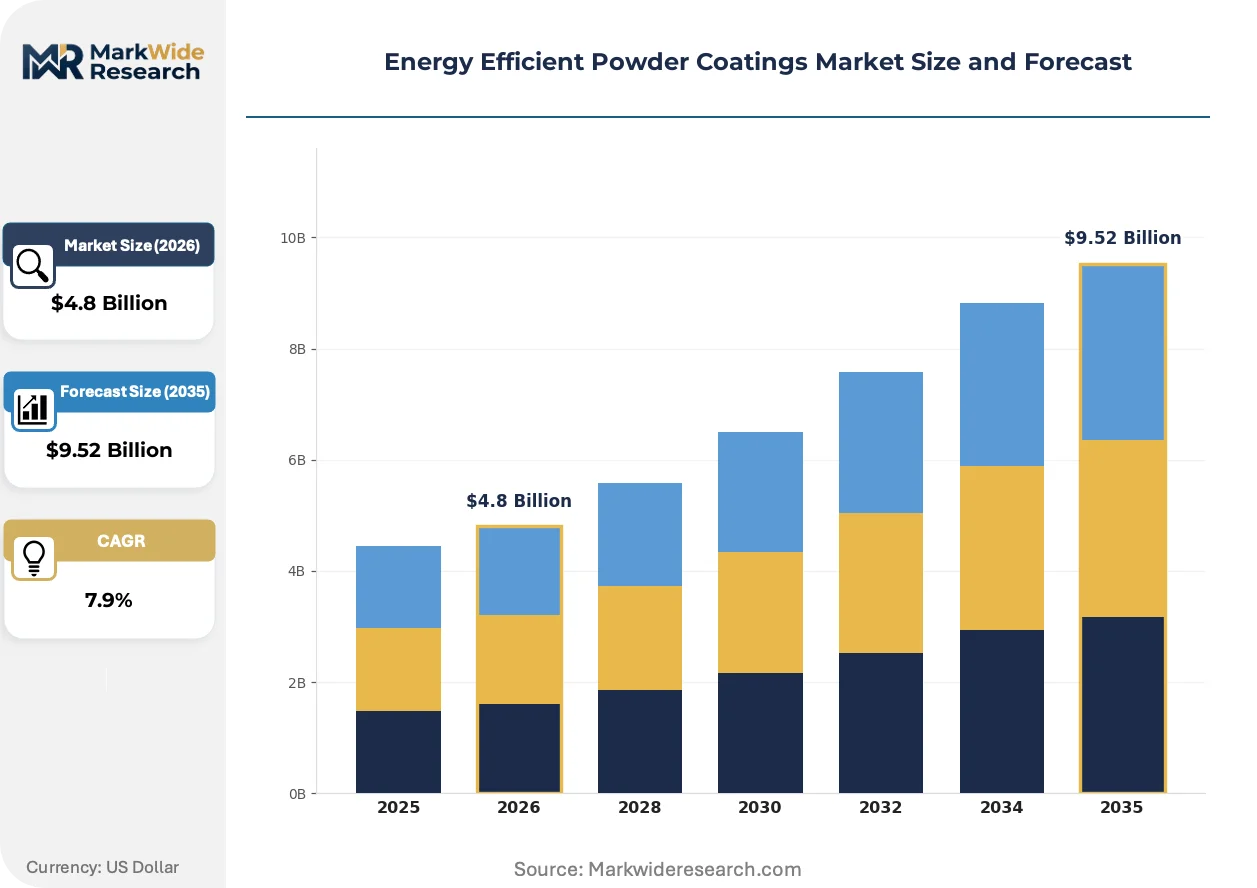
Market Dynamics
The central structural force shaping the market is the intensifying regulatory pressure on volatile organic compounds, compelling a systemic shift from liquid paints to powder-based systems across industrial manufacturing, particularly within the automotive and appliance sectors.
Growth Catalysts
- Automotive Lightweighting:The sector's transition to composite materials and aluminum alloys for electric vehicle bodies and components requires low-temperature cure coatings that do not damage the substrate, directly benefiting energy efficient formulations.
- Regulatory Mandates:Strict environmental standards, including the European Union's REACH framework and China's MEE directives, penalize high-VOC liquid coatings, creating a powerful incentive for industrial finishers to adopt compliant powder technologies.
- UV Curing Technology:Advances in UV-curable powders enable the coating of heat-sensitive materials like wood, MDF, and plastics, opening entirely new end-use markets previously inaccessible to traditional thermoset powders.
Market Restraints
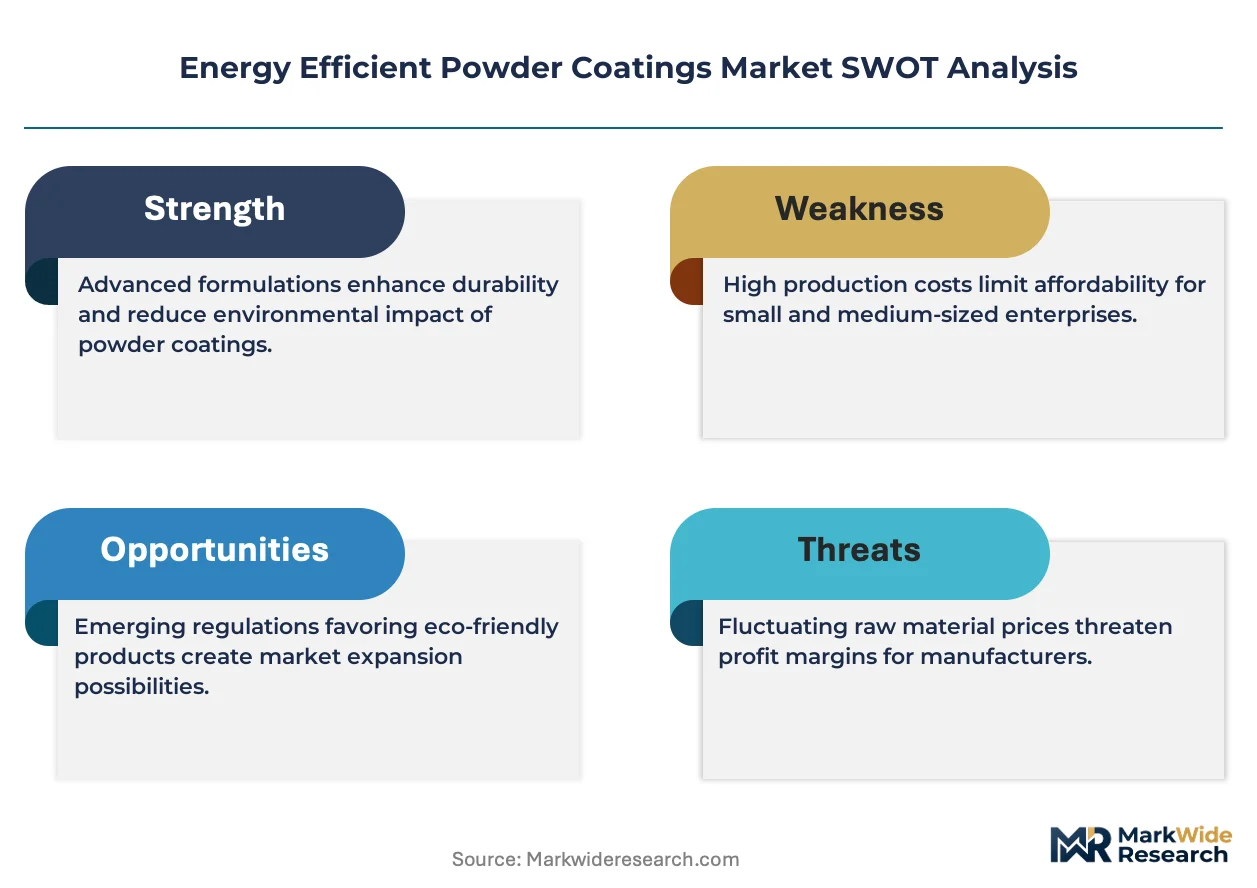
- Capital Expenditure:The high upfront investment required for electrostatic spray guns, powder booths, and specialized curing ovens presents a significant barrier to entry for small and medium-sized enterprises converting from liquid paint lines.
- Technical Limitations:Certain low-temperature cure formulations exhibit lower resistance to abrasion, chemicals, and UV degradation compared to their high-temperature counterparts, limiting their use in some demanding exterior applications.
- Raw Material Volatility:The market is dependent on key resins like polyesters and epoxies, which are subject to price fluctuations based on petrochemical feedstock costs and supply chain disruptions, impacting formulator margins.
Strategic Opportunities
- Architectural Market Penetration:There is a significant opportunity to displace liquid coatings in architectural applications, such as aluminum window frames, facade panels, and metal roofing, by promoting long-term durability and color stability.
- Bio-Based Formulations:Developing powder coatings from bio-based or recycled polyester resins offers a path to enhanced sustainability credentials, appealing to end-users with corporate ESG goals and circular economy targets.
- Emerging Economies:Rapid industrialization and tightening environmental regulations in Southeast Asian nations create new growth frontiers for powder coating manufacturers as local industries upgrade their finishing operations.
Industry Challenges
- Skilled Labor Gap:Achieving a high-quality, consistent finish with powder coatings on complex geometries requires trained operators, and a shortage of skilled technicians can lead to application defects and operational inefficiencies.
- Process Integration Complexity:Retrofitting powder coating lines into facilities designed for liquid painting involves significant operational disruption, including challenges with material handling, workflow redesign, and contamination control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Efficient Powder Coatings Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Hybrid, Acrylic Application: Automotive, Industrial, Architectural, Consumer Goods End User: Manufacturers, Retailers, Contractors, Distributors Technology: Thermal Curing, UV Curing, Electron Beam, Others |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Axalta Coating Systems, BASF SE, Jotun, Teknos Group, Nippon Paint Holdings Co., Ltd., RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Efficient Powder Coatings Market Strategic Shifts & Innovations
Material science advancements are converging with digital process control to enhance the performance and application efficiency of energy efficient powder coatings. This synthesis is creating systems that offer superior durability while meeting stringent energy and environmental targets across multiple industries.
Advanced application equipment, including sensor-integrated spray guns and zoned infrared curing ovens, provides real-time feedback on coating parameters. Automotive and appliance manufacturers are the primary adopters, seeking flawless finishes and reduced rework rates. This integration of digital sensors and automated controls is automating process validation, ensuring consistent film thickness and complete cross-linking with minimal operator intervention.
Regulatory frameworks like the US EPA's National Emission Standards for Hazardous Air Pollutants (NESHAP) continue to tighten limits on industrial solvent use. This directly pressures sectors such as metal furniture and heavy machinery manufacturing to abandon high-VOC liquid paints. Consequently, the industrial finishing segment is accelerating its transition to powder coatings to ensure compliance and avoid penalties.
Demand is shifting from a transactional product purchase to a performance-based specification model. This change disrupts traditional sales channels, favoring formulators who can provide comprehensive technical support and long-term durability warranties for finished goods. This trend is most prominent in large-scale architectural and industrial projects in Germany and Japan, where lifecycle cost and asset protection are primary procurement drivers.
Energy Efficient Powder Coatings Market Segmentation
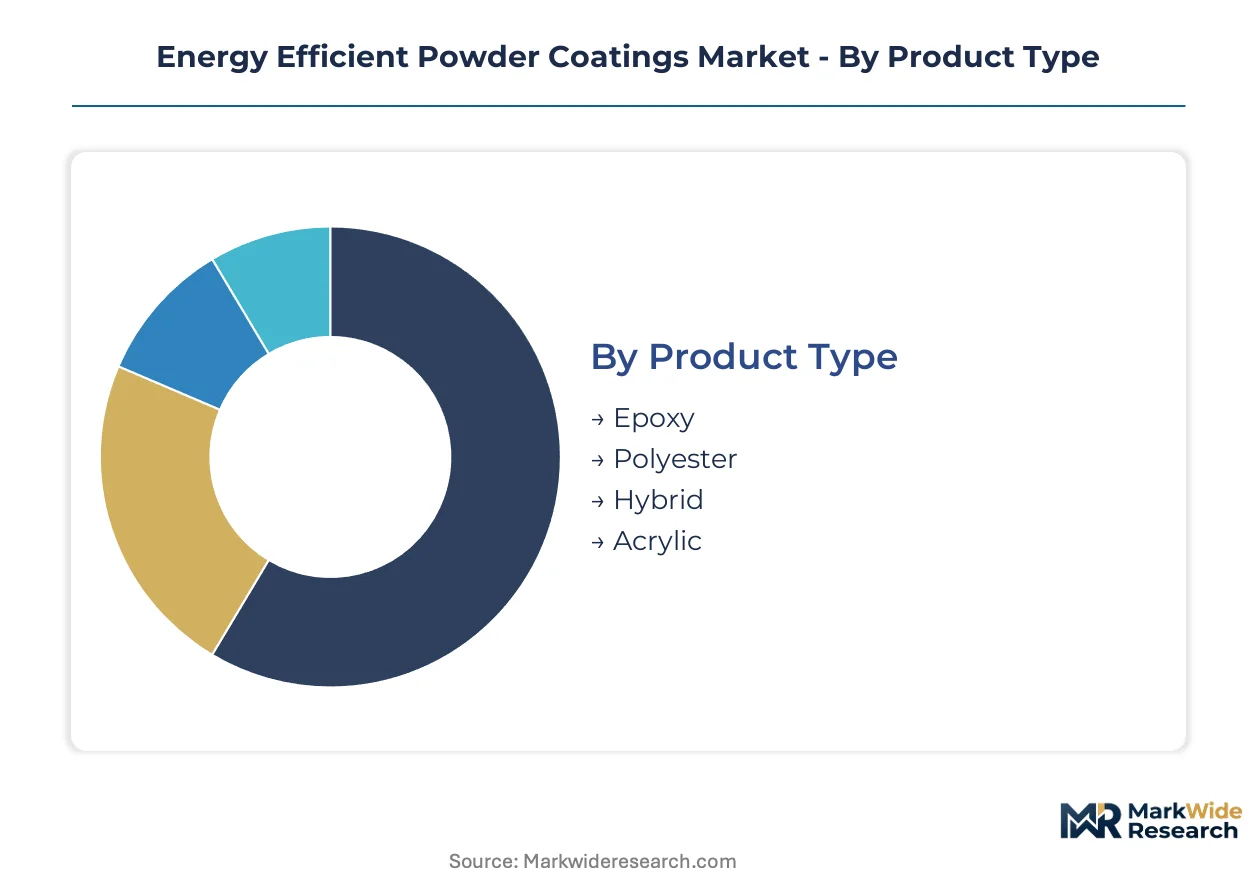
Understanding the varied characteristics and applications of energy efficient powder coatings is crucial for market participants. The segmentation highlights distinct product formulations, diverse application areas, and specific end-user requirements shaping demand. Technology advancements further differentiate market offerings and adoption patterns across industries.
Product Type:
The product type segment is heavily influenced by regulatory approvals, with specific formulations requiring stringent certifications for safety and environmental compliance.
- Polyester:These thermosetting resins offer excellent weatherability and UV resistance, making them ideal for exterior architectural applications. Demand concentrates in Germany and China due to stringent building codes and infrastructure development.
- Hybrid:Combining epoxy and polyester resins, hybrid powders provide a balance of chemical resistance and aesthetic appeal, suitable for indoor industrial machinery and appliance components. Manufacturers in the US and Japan value their versatility.
- Epoxy:These coatings provide superior corrosion protection and chemical resistance, primarily used for indoor applications like pipe coatings and automotive underbody parts.
- Acrylic:Known for their clarity and hardness, acrylic powder coatings find niche applications in automotive clear coats and certain decorative finishes.
Polyester sits at the top of the volume ranking, with Hybrid climbing the fastest.
Application:
Application segments dictate specific performance requirements, influencing coating durability, aesthetic properties, and cure profiles.
- Automotive:These coatings protect vehicle bodies and components from corrosion, abrasion, and UV degradation, crucial for electric vehicle lightweighting initiatives. Demand is high in Germany and Japan for OEM and tier-1 suppliers.
- Industrial:This segment covers a broad range of manufactured goods, including heavy machinery, agricultural equipment, and general metal finishing. Manufacturers in China prioritize robust, energy-efficient solutions for high-volume production.
- Architectural:Applied to building elements like window frames and facade panels, these coatings provide long-term weather resistance and color stability.
- Consumer Goods:This segment includes coatings for appliances, furniture, and electronics, requiring aesthetic appeal and scratch resistance.
Demand for energy efficient powder coatings in the Automotive segment drives significant innovation, while Industrial applications show robust expansion.
End User:
End-user types influence procurement patterns and technical support needs, ranging from large-scale manufacturers to specialized contractors.
- Manufacturers:Large-scale industrial producers in sectors like automotive and appliance manufacturing directly integrate powder coating lines into their production processes. They prioritize efficiency, consistency, and long-term cost savings.
- Contractors:These specialized firms apply powder coatings for various clients, often handling complex geometries or smaller batch sizes. Their expertise in application technique and equipment optimization is critical for quality finishes.
- Retailers:These entities primarily sell pre-coated consumer goods and architectural components, influencing material selection through product specifications.
- Distributors:They serve as intermediaries, supplying powder coating materials and related equipment to smaller manufacturers and application shops.
Manufacturers represent the largest direct consumers of energy efficient powder coatings, with Contractors providing specialized application services.
Technology:
Technology segments differentiate based on curing mechanisms and substrate compatibility, impacting capital expenditure and operational flexibility.
- UV Curing:This technology uses ultraviolet light to initiate cross-linking, enabling rapid curing at low temperatures suitable for heat-sensitive substrates like MDF and plastics. It gains traction in Europe and North America.
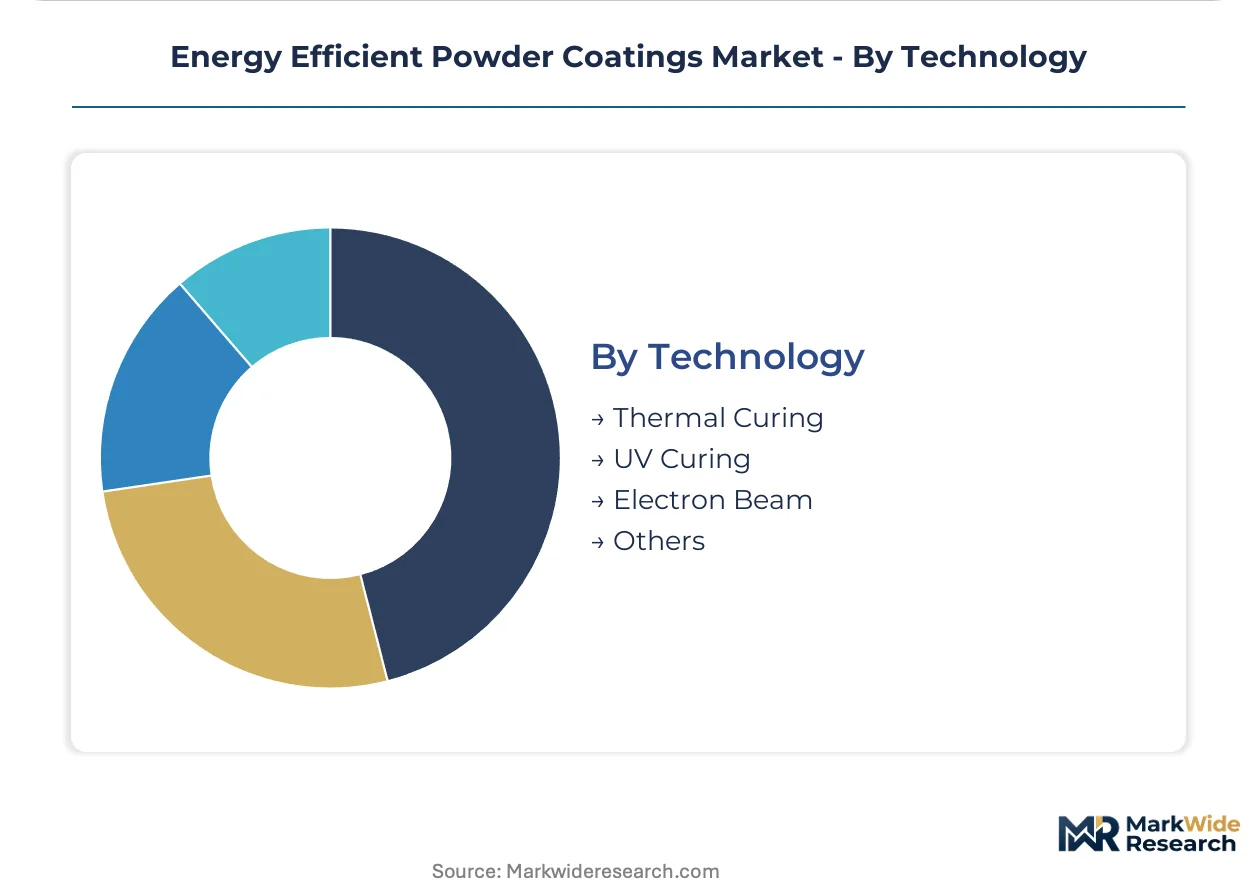
- Thermal Curing:The traditional method involves heating coated parts in an oven to achieve cross-linking, widely used for metal substrates in automotive and industrial applications. This remains the dominant technology globally.
- Electron Beam:This advanced curing method offers ultra-fast curing without heat, suitable for highly sensitive materials and specialized applications.
- Others:This category encompasses emerging or niche curing technologies, including infrared (IR) and near-infrared (NIR) systems, offering specific process advantages.
Thermal Curing remains the established technology, while UV Curing offers distinct advantages for new material applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage drives shifts in energy efficient powder coatings production, as manufacturers seek geographies with favorable environmental compliance costs. This dynamic compels a re-evaluation of supply chain locations, particularly where stringent VOC regulations meet evolving industrial demand. Production centers often relocate to optimize both operational expenses and adherence to regional standards.
China
China's accelerating industrialization and significant manufacturing output drive demand for energy efficient powder coatings. The country's MEE directives on industrial emissions strongly incentivize the adoption of low-VOC solutions. Manufacturing centers in the Yangtze River Delta region are rapidly upgrading finishing lines for appliances and general industrial goods.
Germany
Germany exhibits strong demand from its advanced automotive industry and stringent architectural building codes. The European Union's REACH regulation compels manufacturers to adopt environmentally compliant coating solutions. Production hubs in Bavaria and North Rhine-Westphalia focus on specialized, high-performance coatings for vehicles and industrial equipment.
United States
Demand in the United States stems from the automotive sector's shift to lightweight materials and robust appliance manufacturing. The US EPA's air quality standards and NESHAP drive the transition from high-VOC liquid paints. The Midwest industrial belt, including Michigan and Ohio, integrates powder coating lines for vehicle components and heavy machinery.
Japan
Japan's automotive OEMs and sophisticated consumer goods manufacturers prioritize durable, aesthetically pleasing finishes. METI's environmental guidelines and JIS standards promote the use of advanced, low-energy coating technologies. The Kanto region, particularly around Tokyo, serves as a hub for precision coating applications in electronics and automotive parts.
India
India's rapid industrialization and significant infrastructure development fuel a growing need for protective coatings. The Bureau of Indian Standards (BIS) mandates quality and environmental compliance for various industrial products. Manufacturing clusters in Maharashtra and Gujarat are expanding their adoption of energy efficient powder coatings for architectural and industrial applications.
Energy Efficient Powder Coatings Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with established players often dominating high-performance niches. The market structure exhibits a tiered consolidation, where large chemical conglomerates compete with specialized coating providers. Strategic archetypes include global diversified suppliers, regional niche players, and technology innovators focusing on specific curing methods. Dominant competitive moves involve strategic partnerships for new material development and targeted geographic expansion into emerging industrial hubs.
On the premium-tier vector, Akzo Nobel N.V., a Dutch public limited company, and PPG Industries, Inc., a US-based corporation, exemplify global reach and extensive product portfolios. These entities often anchor the market for advanced formulations and broad industrial applications. Meanwhile, The Sherwin-Williams Company, another US-based corporation, occupies a significant position within architectural and consumer goods segments, representing a strong focus on end-user specific solutions. These companies leverage their scale for supply chain integration and research and development investment.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| BASF SE |
| Jotun |
| Teknos Group |
| Nippon Paint Holdings Co., Ltd. |
| RPM International Inc. |
| Others |
Cost & Logistics Intelligence
Skilled technicians for powder coating application in advanced manufacturing regions contribute to premium pricing for specialized formulations. This labor-cost differential influences the pricing tiers across various product types and end-use applications. Supply chain integration also dictates cost structures, particularly for large-volume industrial customers.
Pricing Analysis
Direct-to-OEM discounts characterize the pricing structure for large-volume automotive and appliance manufacturers. The dominant pricing model is contract-based long-term offtake, ensuring supply stability. Price differentiation stems from quality grade, specifically abrasion and chemical resistance, and the level of regulatory certification required. Pricing pressure stems from raw material volatility, impacting formulator margins. Small and medium-sized enterprises (SMEs) exhibit the most price sensitivity due to upfront capital expenditure, while automotive OEMs prioritize performance over marginal cost savings.
Supply Chain Analysis
Stringent regulatory approvals and performance certifications gate the entry of new suppliers into the energy efficient powder coatings market. Geographic supply concentration centers in China, Germany, and the United States, reflecting major manufacturing hubs. The market draws from key raw material dependencies, including polyester and epoxy resins, which are susceptible to petrochemical feedstock costs. Commodity price volatility represents a structural supply chain risk. Distribution runs through direct sales channels to large manufacturers and specialized distributors serving smaller application shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, as demand shifts toward premium specifications driven by automotive lightweighting initiatives. Manufacturers increasingly seek long-term durability for architectural and industrial applications.
For Market Incumbents: Anticipate continued regulatory tightening by investing heavily in R&D for low-temperature cure and bio-based formulations. Strategic partnerships with advanced application equipment providers can enhance process efficiency and quality control. This approach counters the threat from emerging niche players specializing in specific curing technologies. Incumbents should also leverage certification investment to expand compatibility with new heat-sensitive materials.
For New Entrants and Emerging Players: Online technical support platforms and integrated equipment packages can provide a compelling value proposition. Target underpenetrated segments like the architectural market in emerging economies, displacing traditional liquid coatings. Focus on small and medium-sized enterprises (SMEs) in industrial applications, who seek cost-effective conversion solutions. A go-to-market angle emphasizing ease of adoption and energy savings can capture market share.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers specializing in niche applications or specific curing technologies. The market offers strong long-term viability over the next 5-10 years due to persistent regulatory tailwinds and sustainability drivers. Acquisition targets should include technology innovators in UV curing or bio-based formulations. A signal to watch is the accelerated adoption of UV curing in new end-use markets, indicating broader substrate compatibility and market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | This move leverages lower operational costs and serves a rapidly industrializing regional demand. |
| Joint Venture for Bio-Based Resins | Such collaboration accelerates sustainable formulation development, appealing to corporate ESG goals. |
| Green Manufacturing Transition | Adopting eco-friendly production processes enhances brand reputation and ensures long-term regulatory compliance. |
| Technology Licensing for UV Curing | This expands market reach for advanced curing methods, particularly for heat-sensitive substrates like MDF. |
| Distribution Channel Expansion in India | Broadening access to growing industrial and architectural sectors supports regional market penetration. |
Research Approach
Bottom-up automotive modeling reconciled against top-down resin manufacturer tracking forms the analytical core of this study. Primary interviews with R&D directors at Akzo Nobel, procurement managers at automotive OEMs, environmental compliance officers, and application specialists provided critical qualitative insights. These insights were validated against secondary sources including EU REACH documentation, US EPA air quality standards, China MEE directives, and industry association reports.
Historical trend analysis and market dynamics across the modeling period informed the forecast framework. Segmentation dimensions modeled included product type, application, technology, and geographic region. Compound annual growth rates were derived from regression analysis applied to historical data, projecting future growth. Key industry-specific forecast inputs included electric vehicle production forecasts and construction spending trends across major economies.
The model assumes a particular technology adoption path; alternative pathways for electron beam curing would alter the outlook significantly. Forecasts reflect assumptions documented through extensive primary and secondary research. A model refresh is warranted upon material change in regulatory enforcement intensity or raw material supply stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Low Temperature Powder Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
Transportation Coating Market
Coatings
Solvent Borne Coatings Market
Coatings
ASEAN Protective Coatings Market
Coatings
Self-Healing Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Polyester Coatings Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Russia Architectural Coatings Market
Coatings
Textile Coatings Market