
 Forgings Market | 2026-2036
Forgings Market Size, Share, and Industry Trends Forecast 2026-2036
Forgings Market Insights
Defense and aerospace procurement is rotating toward domestic-forging capacity across multiple geographies, displacing traditional commercial-automotive offtake as the dominant buyer archetype. Bharat Forge leverages its vertical integration into artillery barrels and aircraft structural forgings to capture this shift. Thyssenkrupp anchors European supply through specialized press-forging lines serving submarine hull sections and power-plant rotors. Alcoa Corporation dominates North American aerospace-grade aluminum forging, controlling qualification pathways that lock in multi-year OEM contracts.
Forgings are metal components shaped by compressive force under controlled temperature, typically achieving grain-flow alignment that delivers fatigue resistance superior to cast or machined equivalents; closed-die processes produce near-net shapes for crankshafts and turbine disks, while open-die work yields large custom ingots for pressure vessels and shafts. Carbon steel and stainless steel categories sustain the bulk of volume, serving mature infrastructure and oilfield replacement cycles where price competition is acute. Titanium and aluminum segments represent the fastest-growing material pools, driven by aerospace lightweighting and corrosion mandates in offshore equipment. Impression-die forging concentrates margin capture in complex-geometry aerospace and medical applications where tooling amortization barriers protect incumbent specialists.
The U.S. FAA, EASA in Europe, and India's BIS enforce divergent certification regimes for fatigue-rated forgings, fragmenting qualification costs and favoring regional champions with existing approvals. ISO and ASTM metallurgical standards further shape market access by specifying ultrasonic-inspection protocols that smaller forges struggle to implement. Stakeholders must monitor how dual-use export controls and carbon-border adjustments reshape sourcing economics for cross-border forging supply.
Market Dynamics
Aerospace OEMs are redesigning narrow-body landing gear and engine mounts around heavier forged components, forcing suppliers to recalibrate press capacities and inspection protocols simultaneously.
Growth Catalysts
- Next-generation aircraft programs:Boeing and Airbus narrow-body redesigns specify larger titanium and aluminum forgings for structural loads, pulling capacity from automotive lines.
- FAA fatigue-testing mandates:The U.S. regulator's tightened protocols for safety-critical parts are accelerating ultrasonic inspection upgrades across qualified supplier bases.
- India's heavy-machinery buildout:Domestic infrastructure and defense programs anchor demand for carbon-steel crankshafts and pressure-vessel components at Bharat Forge and Larsen and Toubro facilities.
Market Restraints
- Scrap and alloy input volatility:Nickel and titanium sponge prices swing with mining supply disruptions, compressing margin visibility on long-delivery aerospace contracts.
- Regional qualification fragmentation:Divergent FAA, EASA, and BIS certification regimes force redundant testing spend, favoring incumbents with existing multi-jurisdiction approvals.
- Additive manufacturing substitution:Powder-bed fusion for complex titanium brackets is capturing low-volume aerospace geometries previously routed to closed-die forges.
Strategic Opportunities
- Offshore wind foundation flanges:Monopile and jacket designs specify mega-forged transition pieces above 12 meters diameter, opening capacity utilization at open-die presses in South Korea and Spain.
- EU carbon-border adjustment mechanism:The phased CBAD implementation creates first-mover advantage for European forges with verified low-carbon steel sourcing and electric-arc furnace integration.
- Medical implant near-net shaping:Cobalt-chrome and titanium hip stems demand impression-die precision at ISO 13485-certified shops, commanding tooling amortization premiums above aerospace tiers.
Industry Challenges
- Ultrasonic technician scarcity:FAA and EASA Level II certification requirements outpace vocational pipeline output, extending lead times for safety-critical part qualification.
- Press reconfiguration capex:Retrofitting mechanical lines to servo-electric control for closed-die precision demands capital commitments exceeding mid-tier forge balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forgings Market |
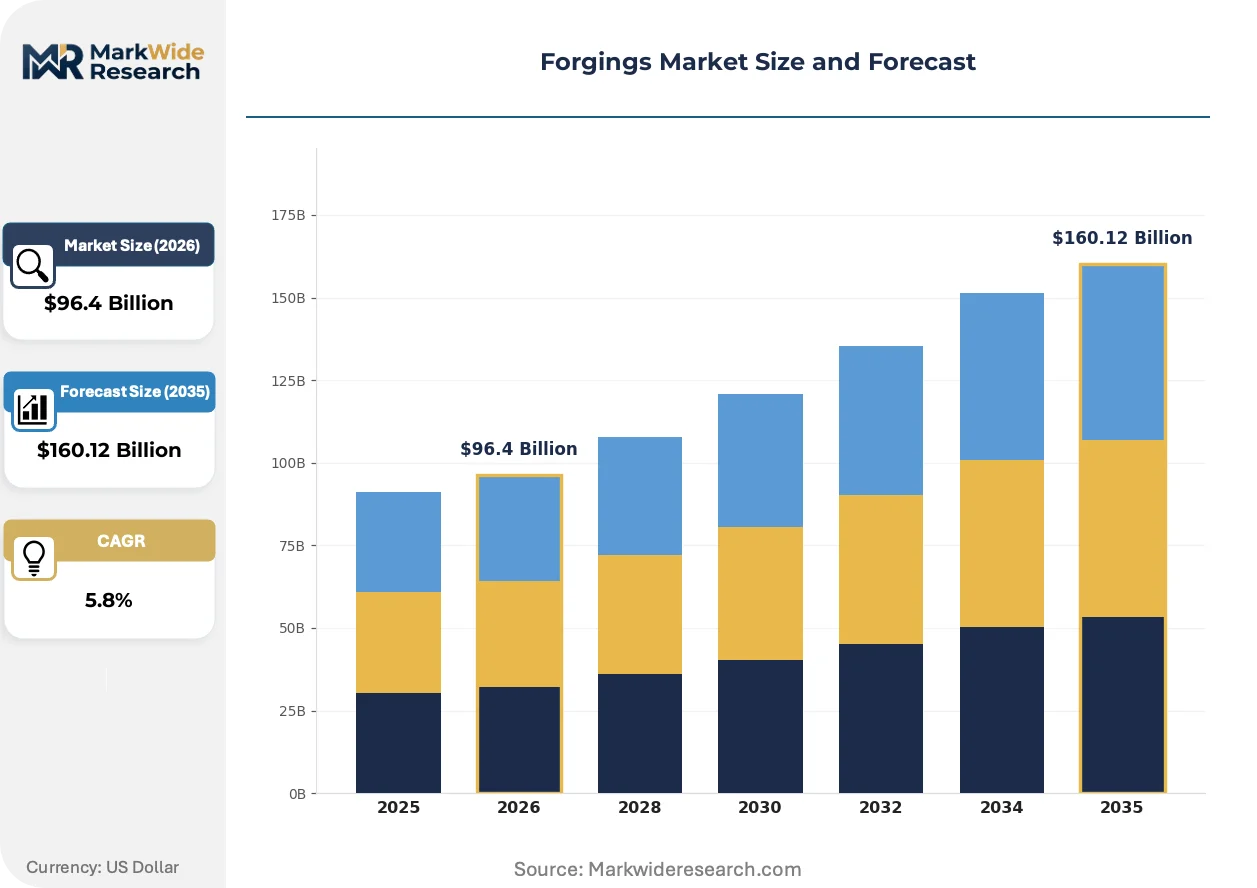
| Market Size in 2026 | $96.4 Billion |
| Market Size in 2035 | $160.12 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Die, Closed Die, Impression Die, Roll Forging, Press Forging Material: Carbon Steel, Stainless Steel, Aluminum, Titanium, Copper Alloys End Use Industry: Oilfield Services, Heavy Machinery, Aerospace, Power Generation, Shipbuilding Application: Gear Components, Valve Components, Structural Parts, Transmission Parts, Hydraulic Equipment |
| Companies Covered | Bharat Forge, Arconic, ATI, thyssenkrupp, Precision Castparts Corp, Scot Forge, Alcoa Corporation, Larsen and Toubro, China First Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forgings Market Trends and Innovations
Digital thread integration and advanced metallurgy are compressing development cycles for fatigue-rated components while regulatory divergence forces parallel qualification tracks.
Isothermal forging of gamma titanium aluminide is displacing conventional nickel superalloy turbine blades in geared turbofan engines, with Pratt and Whitney and Rolls-Royce qualifying these lighter intermetallic components for high-pressure sections. The process maintains uniform die temperature through induction heating, eliminating thermal gradients that cause residual stress in conventional hammer forging. This metallurgical shift is displacing established Inconel supply chains and requiring forge shops to install vacuum chambers and ceramic die systems.
REACH authorization requirements for nickel compounds are compelling European forges to reformulate grinding fluids and surface treatments used in stainless-steel finishing operations. The ECHA sunset date for uncontrolled hexavalent chromium exposure is accelerating plasma electrolytic oxidation and laser surface texturing as replacement technologies. Medical and aerospace segments in Germany and France face the steepest compliance cost curves, with mid-size job shops consolidating to amortize environmental capital expenditure.
Long-term throughput contracts are replacing spot purchasing for aerospace-grade aluminum and titanium forgings, with OEMs locking multi-year volumes to secure capacity after 2021-2023 supply crunches. The model transfers inventory carrying cost to forge operators while guaranteeing minimum utilization at specialized press lines. This contractual evolution is most pronounced in North American and Japanese supply chains, where Boeing, Lockheed Martin, and Mitsubishi Heavy Industries have negotiated take-or-pay structures through 2028.
Forgings Market Segmentation
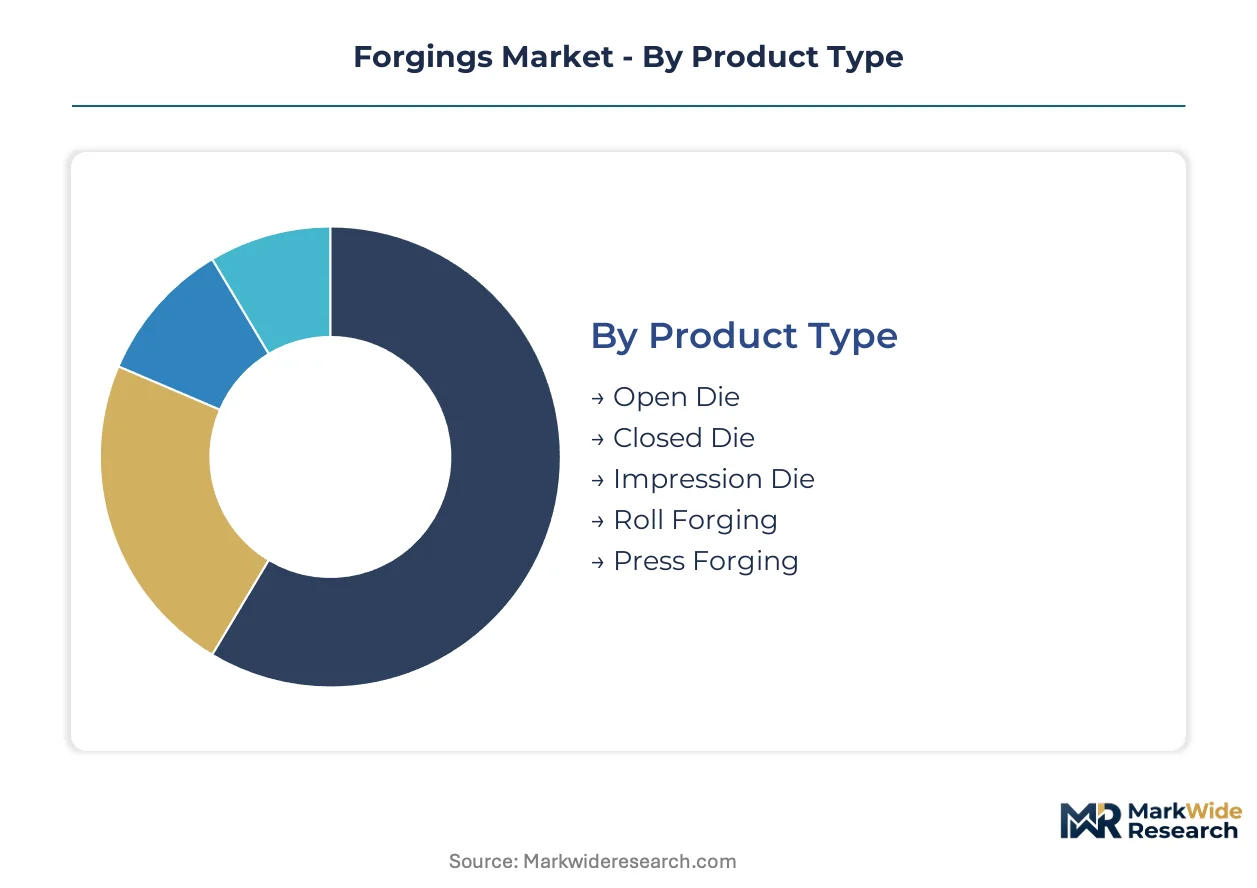
Forgings manufacturers compete across distinct technical specifications where regulatory regimes fragment qualification pathways. Each segment demands specialized press configurations, metallurgical expertise, and certification investments that lock in supplier-customer relationships.
Product Type:
FAA, EASA, and BIS fatigue-testing protocols diverge most sharply on closed-die versus open-die forgings, forcing parallel inspection infrastructure at multi-jurisdiction suppliers.
- Open Die:Large custom ingots shaped between flat dies without lateral constraint, producing shafts and pressure vessels exceeding 20 tons. Demand clusters at Larsen and Toubro facilities serving India's domestic infrastructure buildout, constrained by long lead times for ultrasonic technician certification.
- Closed Die:Precision near-net shapes formed in contoured dies with flash control, delivering crankshafts and turbine disks with aligned grain flow. Aerospace OEMs redirecting narrow-body landing gear programs toward heavier forged components are pulling capacity from automotive lines at qualified suppliers.
- Impression Die:Complex geometries with minimal machining allowance, commanding tooling amortization premiums in medical implant applications.
- Roll Forging:Continuous reduction of bar stock through shaped rolls, producing tapered shafts and axles for heavy machinery replacement cycles.
- Press Forging:Slow compressive forming under servo-electric control, enabling isothermal processing of gamma titanium aluminide for geared turbofan engines at Pratt and Whitney and Rolls-Royce.
Established volume favors Open Die; emerging adoption favors Press Forging.
Material:
Cost tiers separate commodity carbon grades from aerospace-certified alloys where long-term throughput contracts now dominate procurement.
- Carbon Steel:Ferritic and pearlitic compositions serving mature oilfield and infrastructure replacement demand. Price competition is acute at Bharat Forge and Thyssenkrupp facilities serving heavy-machinery OEMs with thin margin visibility.
- Stainless Steel:Austenitic and martensitic grades for corrosion-resistant pressure vessels and process equipment. ECHA REACH sunset dates for hexavalent chromium exposure are accelerating plasma electrolytic oxidation adoption at German and French job shops.
- Aluminum:Heat-treatable aerospace grades where Alcoa Corporation controls North American qualification pathways that lock in multi-year OEM contracts through 2028.
- Titanium:Alpha-beta and near-beta alloys for lightweight structural loads, with powder-bed fusion additive manufacturing capturing low-volume aerospace brackets previously routed to closed-die forges.
- Copper Alloys:High-conductivity forgings for electrical transmission and power-plant rotors, concentrated in European press-forging lines.
Margin stability favors Stainless Steel; steepest expansion trajectory favors Titanium.
End Use Industry:
Customer concentration shifts from automotive toward defense-aerospace procurement rotating through domestic-forging capacity across multiple geographies.
- Oilfield Services:Drill string components and wellhead forgings subject to API specification Q1 quality mandates. Replacement cycles dominate over greenfield investment, compressing pricing power at carbon-steel specialists.
- Heavy Machinery:Mining and construction equipment frames, anchors, and pivot pins. India's infrastructure programs sustain demand at domestic facilities despite input volatility in nickel and scrap pricing.
- Aerospace:Landing gear, engine mounts, and turbine disks where FAA fatigue-testing mandates are accelerating ultrasonic inspection upgrades. Boeing and Airbus narrow-body redesigns specify larger titanium and aluminum forgings.
- Power Generation:Steam and gas turbine rotors, generator shafts, and nuclear pressure vessels requiring multi-decade service life certification.
- Shipbuilding:Submarine hull sections and propulsion shafts where Thyssenkrupp anchors European supply through specialized press-forging lines.
Contract security favors Power Generation; technology premium capture favors Aerospace.
Application:
Functional performance requirements determine whether impression-die precision or open-die scale delivers optimal unit economics.
- Gear Components:Ring gears and pinion blanks requiring controlled grain flow for contact fatigue resistance. Automotive transmission demand is plateauing as electrification reduces multi-speed gearbox content.
- Valve Components:Pressure-retaining bodies and bonnets for oilfield and process industries, standardized around API 6A specifications.
- Structural Parts:Aircraft wing and fuselage fittings where Bharat Forge leverages backward integration into artillery barrels to capture defense procurement shifts.
- Transmission Parts:Synchronizer hubs and shafts facing substitution risk from powder metallurgy and machining-from-solid alternatives.
- Hydraulic Equipment:Cylinder heads and piston rods for construction and agricultural machinery, concentrated in South Korean and Spanish open-die capacity serving offshore wind foundation programs.
Qualification barriers favor Valve Components; substitution exposure weighs on Transmission Parts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian forges export titanium and aluminum structural components to Boeing and Airbus assembly lines in the United States and France, while European suppliers ship press-forged submarine hull sections to naval programs across NATO member states.
United States
Aerospace OEMs in Washington State and South Carolina pull capacity toward heavier landing gear forgings for narrow-body redesigns. The FAA mandates upgraded ultrasonic inspection protocols for fatigue-rated safety-critical parts. Alcoa Corporation anchors supply from Tennessee and Texas facilities controlling North American qualification pathways.
Germany
Thyssenkrupp operates specialized press-forging lines serving submarine hull sections and power-plant rotors for domestic and export naval programs. ECHA REACH sunset dates for hexavalent chromium exposure accelerate plasma electrolytic oxidation adoption at finishing shops. Industrial concentration clusters in North Rhine-Westphalia and Lower Saxony.
India
Bharat Forge and Larsen and Toubro anchor domestic supply for artillery barrels, aircraft structural forgings, and heavy-machinery crankshafts. India's BIS enforces divergent fatigue-testing certification regimes that fragment qualification costs for exporters. Production concentrates at Pune and Hazira facilities serving both defense procurement and infrastructure buildout.
China
China First Heavy Industries and state-owned fabricators supply carbon-steel pressure vessels and nuclear forgings for domestic energy programs. MIIT standards and GB metallurgical specifications shape market access for safety-critical components. Capacity clusters in Shenyang and Dalian serving power generation and shipbuilding demand.
South Korea
Open-die presses at Hyundai Heavy Industries and Doosan Enerbility produce mega-forged transition pieces exceeding 12 meters diameter for offshore wind foundation programs. METI-aligned quality protocols for export markets drive inspection infrastructure investment. Manufacturing concentrates in Ulsan and Changwon industrial zones.
Forgings Market Competitive Landscape
Listed leaders compete with private specialists across qualification pathways, with publicly traded aerospace-grade suppliers facing off against family-owned carbon-steel job shops. Market structure fragments along certification tiers rather than scale, creating protected niches for incumbents with existing FAA, EASA, or BIS approvals. Three archetypes dominate: vertically integrated defense-aerospace specialists, regional infrastructure-focused forges, and medical-precision impression-die shops. Competitive moves concentrate on M&A to acquire dormant qualification certificates and strategic partnerships to share ultrasonic technician training pipelines.
Within the defense-aerospace tier, Bharat Forge and thyssenkrupp exemplify vertically integrated specialists with backward control over metallurgical inputs. Alcoa Corporation occupies a position as the North American anchor for aerospace-grade aluminum qualification. These three entities represent distinct geographic anchors—Indian, German, and American—each sitting within protected regulatory moats that lock in multi-year OEM contracting structures.
| Leading Market Players |
|---|
| Bharat Forge |
| Arconic |
| ATI |
| thyssenkrupp |
| Precision Castparts Corp |
| Scot Forge |
| Alcoa Corporation |
| Larsen and Toubro |
| China First Heavy Industries |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for aerospace-grade titanium forgings concentrate pricing power at qualified suppliers with existing FAA and EASA fatigue-test certifications, while carbon-steel job shops compete on thin margins without such regulatory moats. Long-term throughput contracts now dominate procurement for safety-critical components, transferring inventory carrying costs to forge operators while locking in minimum utilization.
Pricing Analysis
Servo-electric press-forging technology commands 15-20 percent premiums over mechanical-line output due to precision tolerances required for gamma titanium aluminide turbine blades, while conventional hammer-forged carbon steel competes on commodity spot pricing. Three-tier pricing structure across premium aerospace certification, standard industrial grade, and economy infrastructure tiers reflects divergent qualification investments. Cost compression in carbon-steel categories intensifies because scrap and alloy input volatility erodes margin visibility on thin-contract heavy-machinery orders. Defense-aerospace procurement shows lowest price sensitivity due to multi-year qualification lock-ins, while oilfield replacement cycles face acute buyer pressure.
Supply Chain Analysis
Inventory buffers at Indian and German facilities have compressed to 45-60 days as OEMs shift toward just-in-time delivery under long-term offtake structures. Supply concentrates in India for carbon-steel crankshafts and artillery barrels, Germany for submarine hull press-forgings, and the United States for aerospace aluminum qualification pathways. Raw material flows draw from nickel mining disruptions, titanium sponge supply constraints, and specialized alloy formulations. Single-source vulnerability runs through qualified ultrasonic technician pools where FAA Level II certification outpaces vocational pipeline output. Distribution runs through direct OEM contracting rather than merchant spot markets for fatigue-rated safety-critical tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forgings markets operate as defensive-moat businesses where regulatory entrenchment protects incumbent returns. Multi-jurisdiction fatigue-test certifications create switching costs that lock out unqualified competitors for years.
For Market Incumbents: Secure dormant qualification certificates through targeted M&A to acquire FAA, EASA, or BIS approvals without multi-year testing cycles. Deepen backward integration into titanium sponge and nickel alloy supply to offset raw material volatility compressing margins on long-delivery aerospace contracts. Add servo-electric press capacity in South Korea or Spain to capture offshore wind foundation flange demand exceeding 12-meter diameters. For New Entrants and Emerging Players: Lead with medical implant near-net shaping where ISO 13485 certification barriers are lower than aerospace tiers and tooling amortization premiums exceed standard industrial margins. Target cobalt-chrome and titanium hip stem geometries where impression-die precision commands price premiums absent from commodity carbon-steel competition. Partner with established ultrasonic technician training pipelines to accelerate qualification timelines rather than building captive inspection capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized forge assets lacking dedicated aerospace certification focus. Five-to-ten year viability hinges on regulatory entrenchment durability rather than cyclical demand swings. Watch powder-bed fusion additive manufacturing penetration in low-volume titanium brackets as signal for closed-die forging substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Throughput Contracting | Locks multi-year aerospace volumes at Alcoa and Bharat Forge facilities through 2028. |
| Servo-electric Press Retrofit | Enables isothermal gamma titanium aluminide processing for Pratt and Whitney engine programs. |
| Ultrasonic Technician Pipeline Investment | Addresses FAA Level II scarcity extending safety-critical part qualification lead times. |
| Backward Integration into Alloy Supply | Captures margin from nickel and titanium sponge volatility affecting long-delivery contracts. |
| Medical Impression-die Certification | Opens ISO 13485-qualified capacity for cobalt-chrome hip stem premium pricing tiers. |
Research Methodology
A spread of perspectives from forge operations managers, aerospace OEM procurement directors, metallurgical testing engineers, and defense program contracting officers converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from FAA airworthiness directives, EASA certification databases, BIS metallurgical standards, and SEC filings of listed forge operators. Bottom-up capacity utilization data triangulated against top-down aerospace and defense procurement forecasts.
Segmentation dimensions modeled include product type hierarchy, material grade tiering, end-use industry concentration, and application-specific qualification pathways across the analysis window. CAGRs derived from production capacity expansion schedules, OEM narrow-body aircraft delivery programs, and infrastructure investment cycles. Industry-specific forecast inputs incorporated ultrasonic technician certification pipeline constraints and REACH authorization timelines for hexavalent chromium alternatives.
The analysis sits within stated boundaries; outcomes outside sustained defense-aerospace procurement growth or accelerated additive manufacturing substitution would require recalibration. Forecasts reflect documented assumptions regarding regulatory divergence persistence and alloy input cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Quartz Kitchen Countertops Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
High Strength Steel (HSS) Market