
 Automotive Aluminum Alloy (OE) Market | 2026-2036
Automotive Aluminum Alloy (OE) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Aluminum Alloy (OE) Market Outlook
Asset-light leasing structures for aluminum rolling mills is narrowing the field of competitors capable of serving high-volume OEM programs. Norsk Hydro ASA leverages its integrated smelter-to-sheet operations across Norwegian and German plants to sustain long-term supply agreements with premium European automakers. Constellium anchors its position through specialized aerospace-grade aluminum capabilities that transfer directly into crash-management applications for electric vehicle architectures.
Automotive aluminum alloy (OE) denotes wrought and cast aluminum grades engineered to specific yield strength, elongation, and corrosion-resistance parameters for original equipment manufacturing, typically delivered in heat-treated tempers such as T6 or T4 conditions to meet crashworthiness and weight-reduction targets. Sheet products dominate value capture in closure panels and body-in-white structures where surface quality and formability command premium positioning, while extrusions compete aggressively in battery enclosure rails and crash-absorption profiles where geometric complexity favors hollow-section capability. Die-casting technology leads volume throughput for engine blocks and structural nodes, though cold forming gains traction in chassis components where strain-hardening properties reduce downstream heat-treatment costs.
The EU Green Deal and REACH framework shape material selection through embodied carbon disclosure requirements, while EPA fuel-economy standards in the United States and China's MIIT dual carbon goals enforce lightweighting mandates that directly expand aluminum content per vehicle. NHTSA crash-safety protocols and ECE R94 regulations further dictate alloy specifications for frontal-impact structures, creating compliance barriers for non-certified suppliers. Stakeholders must monitor evolving battery-electric platform architectures and corresponding aluminum grade qualification timelines to align capacity investments with OEM program ramps.
Market Dynamics
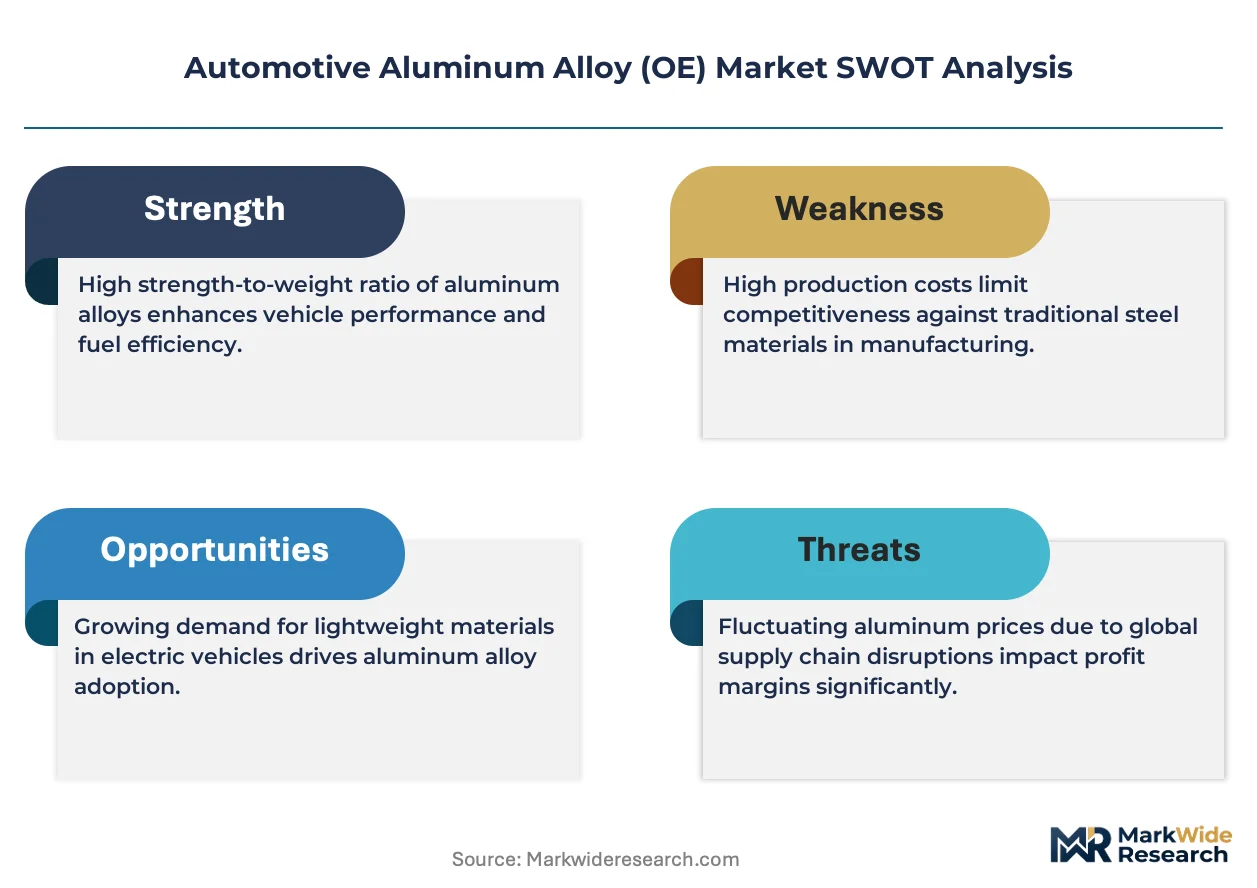
Electric vehicle platform architectures are compressing aluminum grade qualification timelines and forcing capacity investments ahead of confirmed OEM program ramps. Battery enclosure specifications now dictate alloy selection for entire vehicle programs, shifting supplier influence upstream into platform engineering decisions.
Growth Catalysts
- EU Green Deal embodied carbon mandates:REACH disclosure requirements for automotive materials are accelerating aluminum substitution for steel in closure panels across German and French OEM supply chains.
- MIIT dual carbon targets:China's fuel-economy standards enforce lightweighting mandates that expand aluminum content per vehicle in domestic electric SUV platforms.
- Die-casting technology advancement:Large structural casting cells for battery tray integration are consolidating multiple stamped steel components into single aluminum castings.
Market Restraints
- Primary aluminum smelter concentration:European rolling mills depend on Norwegian and Icelandic hydro-powered smelters, creating geographic single-point vulnerability for low-carbon billet supply.
- Scrap contamination thresholds:Post-consumer aluminum recovery streams fail to meet automotive-grade purity specifications for body-in-white applications, limiting closed-loop recycling economics.
- Magnesium price volatility:Magnesium alloying additions for automotive sheet grades expose cost structures to Chinese supply dominance and export quota fluctuations.
Strategic Opportunities
- CSRD reporting requirements:The EU Corporate Sustainability Reporting Directive creates first-mover advantage for suppliers with verified Scope 3 emissions data and product-level carbon footprints.
- Solid-state battery thermal management:Next-generation cell architectures require aluminum cooling plate designs with enhanced thermal conductivity specifications.
- Direct-to-OEM digital platforms:Alloy specification databases and real-time availability APIs are compressing distributor layers in spot purchasing for prototype builds.
Industry Challenges
- Heat-treatment technician scarcity:Specialized furnace operation and temper verification skills are aging out of the workforce faster than apprenticeship programs replace them.
- Multi-grade qualification timelines:OEM platform approvals require 18-24 month alloy validation cycles that misalign with battery-electric vehicle development sprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Aluminum Alloy (OE) Market |
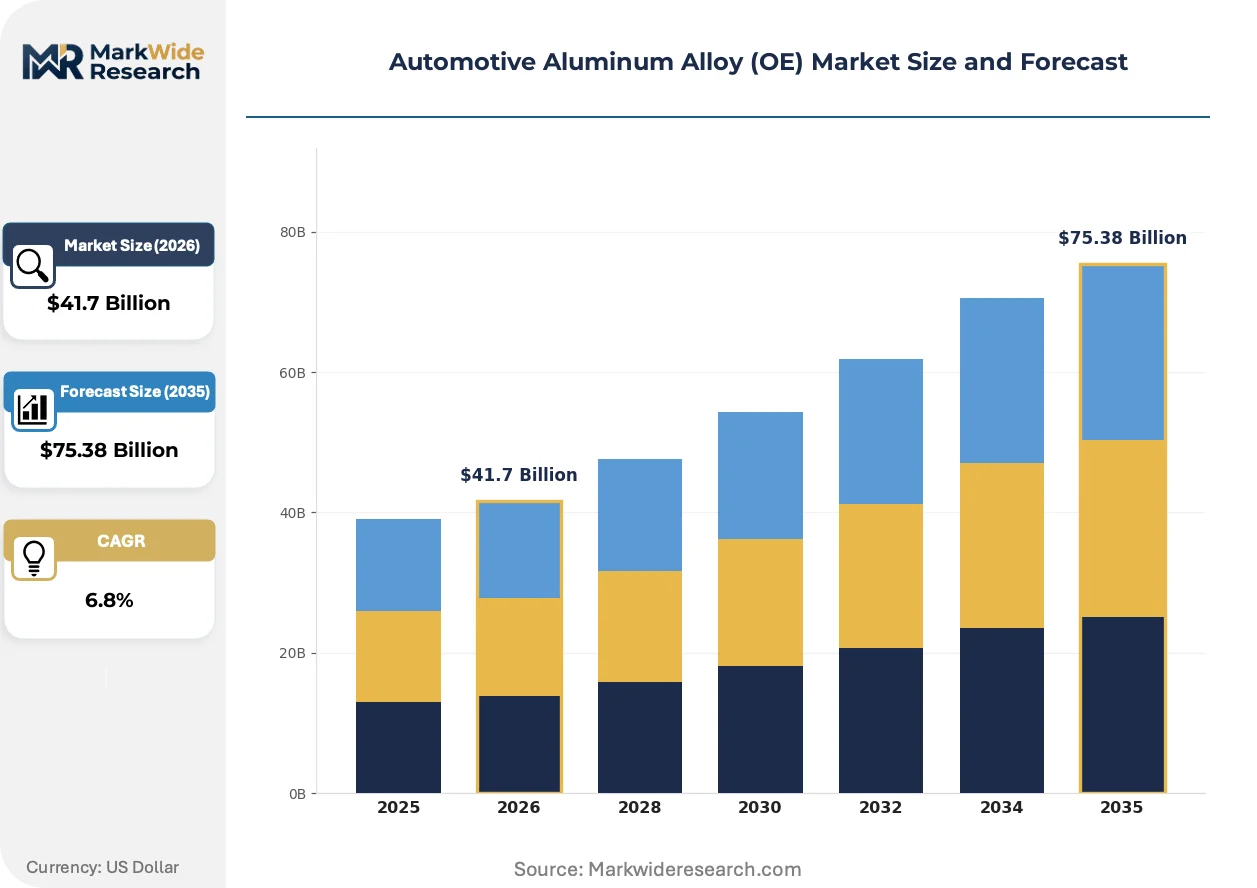
| Market Size in 2026 | $41.7 Billion |
| Market Size in 2035 | $75.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Extrusions, Castings, Foams Application: Body Structure, Engine Components, Chassis, Wheels End User: OEMs, Aftermarket Suppliers, Component Manufacturers, Assemblers Technology: Die-Casting, Cold Forming, Powder Metallurgy, Rolling |
| Companies Covered | Norsk Hydro ASA, Constellium, Novelis, Alcoa Corporation, UACJ Corporation, AMG Advanced Metallurgical Group, thyssenkrupp AG, Kobe Steel, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Aluminum Alloy (OE) Market Strategic Shifts
High-pressure die-casting scale-up and closed-loop scrap recovery systems are redefining process economics for structural aluminum components. These shifts are compressing the cost gap between aluminum and advanced high-strength steel in mass-market vehicle segments.
6XXX-series sheet alloys are migrating from traditional T4 tempers to T6 conditions for outer body panels, enabling higher yield strength in hood and door applications. European premium OEMs are qualifying these grades for Class A surface requirements. This migration from soft-temper formability to hard-temper performance is reducing springback compensation needs and enabling thinner gauge specifications.
REACH authorization procedures for chromium-based conversion coatings are tightening surface treatment specifications for corrosion-critical automotive aluminum. Suppliers are accelerating trivalent chromium and zirconium-based pretreatment qualifications to maintain European market access. Extrusion and sheet processors serving German OEMs face the most compressed compliance timelines for process chemistry transitions.
Consolidated aluminum procurement through platform-level supply agreements is displacing commodity-grade spot purchasing for battery enclosure programs. Tier-1 integrators are capturing specification authority previously held by rolling mill distributors. This concentration is most visible in Stuttgart and Wolfsburg manufacturing corridors where single-source aluminum contracts now span multiple vehicle nameplates.
Automotive Aluminum Alloy (OE) Market Segmentation
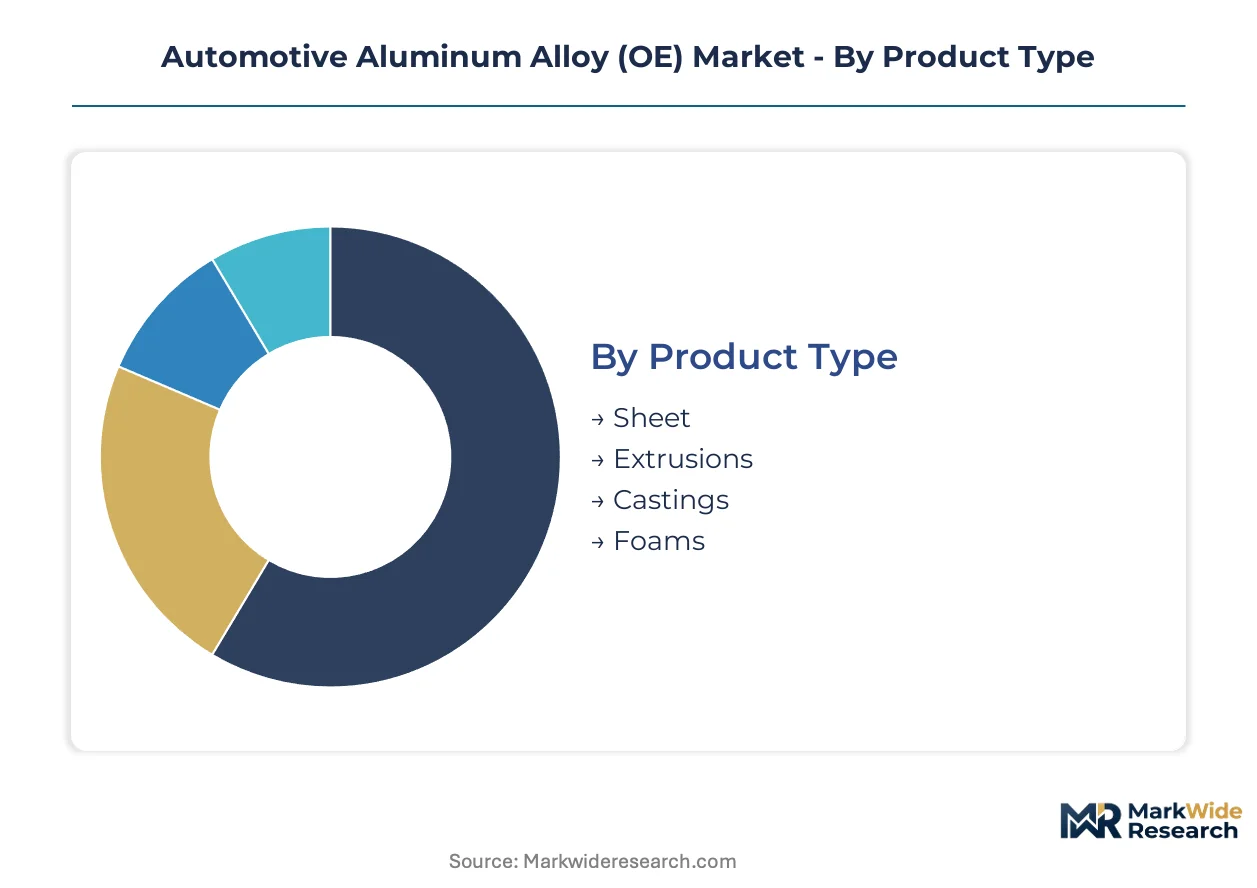
Aluminum alloy specification varies sharply across product forms and manufacturing processes, with each segment demanding distinct technical service support and qualification protocols. OEM program approvals require segment-specific metallurgical validation that shapes supplier capability investments and margin structures.
Product Type:
After-sales service intensity runs highest for sheet products requiring surface defect remediation and temper verification, while castings demand foundry-level technical support for porosity and heat-treatment troubleshooting.
- Sheet:Wrought aluminum delivered in coil or blank form for closure panels and body-in-white structures, typically in 5XXX or 6XXX series grades. Demand concentrates in German premium OEM stamping operations around Stuttgart, driven by EU Green Deal embodied carbon disclosure requirements for closure panel substitution. Surface quality specifications for Class A exterior panels command intensive technical service engagement throughout qualification.
- Extrusions:Hollow and solid profiles produced through direct or indirect extrusion of 6XXX-series billets. Battery enclosure rails and crash-absorption profiles in Wolfsburg manufacturing corridors absorb volume, with geometric complexity favoring hollow-section capability for electric vehicle architectures. Cross-section design support and die maintenance programs elevate after-sales intensity.
- Castings:Molten aluminum poured into permanent molds or die-cast into high-pressure cells for engine blocks and structural nodes.
- Foams:Cellular aluminum structures produced through gas injection or powder compacting for energy absorption applications.
By volume, Sheet leads. By growth pace, Extrusions is climbing the fastest.
Application:
Application segmentation tracks aluminum content penetration depth, with body structures commanding premium alloy grades and engine components representing mature, cost-optimized specifications.
- Body Structure:Aluminum-intensive body-in-white, closure panels, and structural reinforcements where crashworthiness and weight reduction converge. German OEMs in Baden-Württemberg dominate specification authority, with NHTSA and ECE R94 frontal-impact protocols dictating alloy selection for energy-absorption zones. Multi-material joining expertise separates qualified suppliers.
- Engine Components:Cylinder heads, blocks, pistons, and thermal management hardware in cast or wrought grades. Established supply chains around Munich and Ingolstadt maintain volume, though electrification is compressing content per vehicle in pure battery-electric platforms. Legacy internal combustion programs sustain near-term demand.
- Chassis:Control arms, subframes, and suspension links where stiffness-to-weight ratios determine specification.
- Wheels:Cast or forged aluminum rims for passenger and commercial vehicles, with cosmetic finish requirements driving grade selection.
Body Structure captures value concentration. Engine Components retains shipment scale.
End User:
End user segmentation reveals diverging procurement patterns, with OEMs consolidating platform-level supply agreements while aftermarket suppliers fragment across spot purchasing.
- OEMs:Vehicle manufacturers specifying aluminum grades at platform conception and locking in multi-year rolling mill commitments. Volkswagen Group and BMW anchor European demand through consolidated aluminum procurement spanning multiple nameplates, with single-source contracts now standard for battery enclosure programs.
- Component Manufacturers:Tier-1 and Tier-2 suppliers converting semi-finished aluminum into subassemblies for OEM delivery. Brake and suspension specialists in Germany's automotive corridor manage alloy inventory against just-in-sequence delivery requirements, with specification authority migrating upstream to platform integrators.
- Aftermarket Suppliers:Independent distributors and remanufacturers serving collision repair and performance upgrade channels.
- Assemblers:Contract manufacturers and vehicle finishers integrating aluminum components into final assembly.
OEMs dictate specification. Component Manufacturers absorb inventory risk.
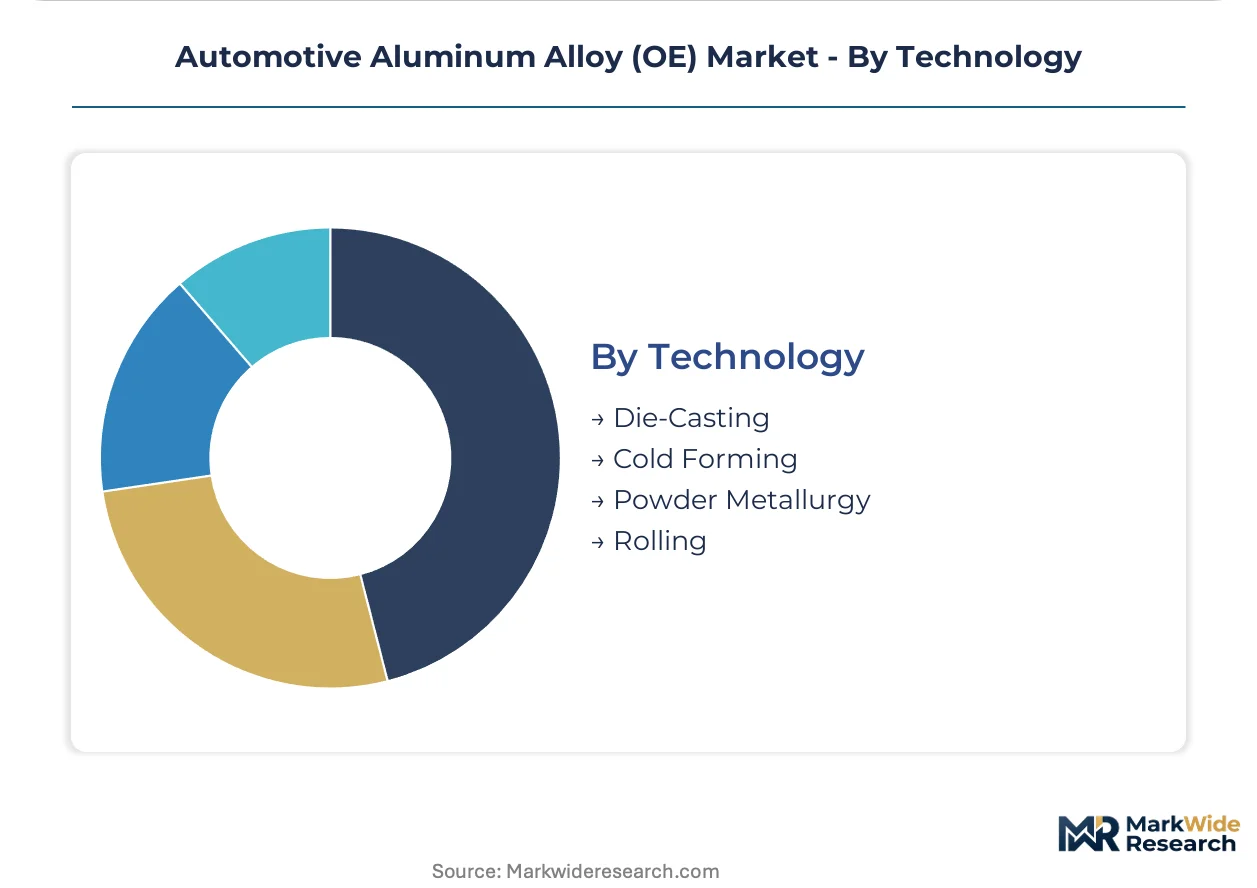
Technology:
Technology segmentation separates high-volume casting operations from precision forming methods, with process selection determining capital intensity and scrap economics.
- Die-Casting:High-pressure injection of molten aluminum into hardened steel molds for complex geometries. Large structural casting cells for battery tray integration are consolidating multiple stamped steel components near Wolfsburg and Stuttgart, with machine locking forces exceeding 4,000 tonnes enabling single-piece castings that were previously assemblies.
- Cold Forming:Room-temperature shaping of sheet or extrusion feedstock through stamping, bending, and hydroforming. Chassis component applications exploit strain-hardening properties to reduce downstream heat-treatment costs, with 5XXX-series grades preferred for their formability in suspension link production.
- Powder Metallurgy:Compaction and sintering of aluminum powders for near-net-shape components with controlled porosity.
- Rolling:Continuous or reversing mill reduction of cast ingot into sheet or plate products with controlled thickness tolerance.
Die-Casting leads on throughput. Cold Forming gains on energy efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium European OEMs extract pricing leverage from embodied carbon mandates, while Chinese battery-electric platforms compete on volume throughput. This asymmetry concentrates specification authority in Stuttgart and Wolfsburg while compressing margins in high-volume Asian supply chains.
Germany
Volkswagen Group and BMW consolidate aluminum procurement across multiple nameplates through single-source platform agreements. The EU Green Deal and REACH framework enforce embodied carbon disclosure for closure panel substitution. Baden-Württemberg's stamping corridor around Stuttgart drives 6XXX-series sheet qualification for Class A surface requirements.
China
Domestic electric SUV platforms from BYD and NIO expand aluminum content per vehicle to meet MIIT dual carbon targets. The Ministry of Industry and Information Technology tightens fuel-economy standards that mandate lightweighting. Yangtze River Delta rolling mills serve battery enclosure programs with compressed grade qualification timelines.
United States
Ford and General Motors accelerate aluminum-intensive body structure adoption for electric truck architectures. EPA fuel-economy standards and NHTSA crash-safety protocols dictate alloy specifications for frontal-impact zones. Michigan's automotive corridor anchors die-casting investments for structural battery tray integration.
Japan
Toyota and Honda qualify aluminum grades for hybrid platform continuity amid electrification transitions. METI carbon neutrality roadmaps pressure steel-aluminum substitution in closure applications. Kansai region extrusion houses specialize in hollow-section crash-absorption profiles for export programs.
South Korea
Hyundai Motor Group consolidates aluminum supply for E-GMP platform battery enclosures across Kia and Genesis nameplates. KBA-equivalent homologation requirements align with EU crash standards for export vehicles. Seoul Capital Area integrators capture specification authority previously held by rolling mill distributors.
Automotive Aluminum Alloy (OE) Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in a structure that concentrates around heat-treatment capabilities and OEM qualification depth. The field narrows to operators with captive smelter access and long-term alloy validation histories. Three archetypes dominate: integrated smelter-to-sheet producers, aerospace-grade capability transfer specialists, and high-volume rolling mill operators serving mass-market programs. Competitive moves center on capacity commitments ahead of confirmed OEM ramps and scrap-loop integration to secure low-carbon billet supply.
Among integrated Nordic producers, Norsk Hydro ASA exemplifies the smelter-to-sheet archetype through Norwegian and German plant networks. Constellium occupies a position representing aerospace-grade aluminum capability that transfers into crash-management applications. Novelis anchors the high-volume rolling tier serving closure panel specifications across multiple OEM platforms. These three companies collectively illustrate how qualification depth and carbon disclosure capabilities separate sustainable suppliers from commodity competitors.
| Leading Market Players |
|---|
| Norsk Hydro ASA |
| Constellium |
| Novelis |
| Alcoa Corporation |
| UACJ Corporation |
| AMG Advanced Metallurgical Group |
| thyssenkrupp AG |
| Kobe Steel |
| Nippon Steel Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European rolling mill capacity is driving supplier discipline and pricing leverage for qualified sheet producers serving German OEM platform agreements. This utilization tightness is compressing spot-market availability while reinforcing long-term contract premiums for battery enclosure programs.
Pricing Analysis
The customization-premium spread between configured-to-order Class A surface sheet and standard-grade extrusions is widening as OEMs consolidate platform-level procurement. Contract-based long-term offtake dominates high-volume battery enclosure supply, with price differentiation driven by certification depth and volume scale. Pricing pressure stems from Chinese rolling mill overcapacity in commodity grades, though European buyers show low price sensitivity for embodied carbon-verified supply. Aftermarket distributors absorb the highest price sensitivity due to fragmented spot purchasing.
Supply Chain Analysis
Export-control regimes on advanced rolling mill technology and smelter equipment are limiting capacity expansion in emerging supply regions. Geographic supply concentration centers on Norway, Germany, and China, with raw material dependencies spanning primary aluminum ingot, magnesium alloying additions, and specialized rolling oils. Single-source vulnerability runs through Norwegian hydro-powered smelters for low-carbon billet. Distribution runs through Tier-1 platform integrators who have displaced traditional rolling mill distributors in specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a platform-economics inflection as battery-electric vehicle architectures force interoperability standards across aluminum grade specifications and thermal management interfaces.
For Market Incumbents: Harden qualification depth by securing captive smelter access for low-carbon billet supply ahead of CSRD disclosure mandates. Invest in heat-treatment technician apprenticeship pipelines to address workforce aging. Defend against emerging Chinese rolling mill competitors by embedding technical service teams within Stuttgart and Wolfsburg OEM engineering centers.
For New Entrants and Emerging Players: Pursue solid-state battery cooling plate specifications where thermal conductivity requirements create white-space for specialized alloy development. Target aftermarket collision repair channels in North America where spot purchasing patterns favor agile distributors. Build go-to-market credibility through direct-to-OEM digital platforms with real-time availability APIs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across large structural die-casting cells as machine locking forces exceed 4,000 tonnes. Long-term viability favors operators with integrated scrap-loop economics and verified Scope 3 emissions data. Watch for consolidation signals when multi-grade qualification timelines compress below 18 months.
| Strategic Initiative | Industry Significance |
|---|---|
| Scrap-Loop Integration | Closed-loop recovery systems secure low-carbon billet supply for EU Green Deal compliance. |
| Platform-Level Supply Agreement | Single-source contracts spanning multiple nameplates capture specification authority from distributors. |
| Heat-Treatment Apprenticeship Pipeline | Specialized furnace operation skills address workforce aging faster than industry replacement rates. |
| Direct-to-OEM Digital Platform | Real-time availability APIs compress distributor layers in prototype build spot purchasing. |
| Solid-State Battery Thermal Qualification | Enhanced conductivity specifications for next-generation cell architectures create alloy development opportunity. |
Study Parameters
Desk research of customs trade data, SEC filings from listed aluminum producers, and vehicle production databases preceded structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, rolling mill operations directors, and heat-treatment technical specialists. Bottom-up volume estimates from alloy-grade consumption patterns were triangulated against top-down OEM production forecasts across the analysis window.
Assumptions held fixed include MIIT dual carbon target enforcement levels, REACH authorization timelines for chromium-based coatings, and NHTSA crash-safety protocol stability. The analytical framework modeled segmentation across propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from regression analysis of historical aluminum intensity trends against battery-electric platform penetration curves, with alloy qualification timelines and scrap recovery economics as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in primary aluminum LME pricing, magnesium export quota volatility, or European energy cost trajectories would shift the trajectory. Material shifts in battery-electric platform architecture standardization or solid-state battery commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Chromium Carbide Overlay Plate Market
Advanced Alloys
Quartz Kitchen Countertops Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Cobalt Alloy Powder Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
Titanium Alloys Market