
 Canada Bioresorbable Polymers Market | 2026-2036
Canada Bioresorbable Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Bioresorbable Polymers Market Intelligence
Quebec's polymer production base is consolidating around specialized medical-grade resin capabilities. Evonik Industries AG leverages its global biomaterials network to supply Canadian device manufacturers with precision-controlled polylactic acid grades. Corbion NV sustains fermentation-derived supply chains that anchor domestic availability of high-purity lactic acid precursors. Poly-Med Inc. specializes in custom absorbable fiber and mesh configurations for orthopedic and wound-closure applications.
Bioresorbable polymers are synthetic or naturally derived macromolecules engineered to degrade hydrolytically or enzymatically into non-toxic byproducts within controlled timeframes, typically spanning weeks to twenty-four months depending on crystallinity, molecular weight, and copolymer ratios. These materials serve primarily as temporary structural scaffolds in implantable medical devices, eliminating the need for surgical retrieval. Polylactic acid dominates current formulation volumes due to its tunable degradation profile and established processing history. Medical devices command the largest application share, while drug delivery systems represent the fastest-expanding segment as manufacturers integrate controlled-release functionality into resorbable carriers. Injection molding remains the prevailing fabrication technology, though 3D printing adoption accelerates for patient-specific scaffold geometries.
Health Canada and the Canadian Standards Association govern biocompatibility and degradation testing protocols, while ISO 10993 standards provide the foundational framework for biological risk assessment. These regulatory layers shape product development timelines, requiring extensive preclinical documentation before market authorization. Manufacturers must navigate evolving requirements for resorption-byproduct toxicology as novel copolymer compositions enter clinical pipelines. Stakeholders should monitor Health Canada's anticipated alignment with international harmonization initiatives for absorbable implant classifications.
Market Dynamics
Health Canada's evolving medical device regulations are compressing product development timelines while simultaneously validating higher-grade resorbable materials, forcing manufacturers to front-load clinical documentation before market entry.
Growth Catalysts
- Orthopedic Implant Demand:Ontario's hospital networks are expanding surgical volumes for fracture fixation and spinal fusion procedures requiring temporary structural scaffolds. Toronto's medical technology corridor concentrates procurement authority among university-affiliated research hospitals.
- ISO 10993 Harmonization:Alignment with international biocompatibility testing frameworks is reducing redundant validation cycles for Canadian manufacturers seeking export markets. Health Canada's adoption of standardized degradation protocols accelerates regulatory clearance pathways.
- Polylactic Acid Process Maturity:Injection molding infrastructure across Quebec's polymer production base enables cost-efficient fabrication of complex implant geometries with tunable resorption profiles.
Market Restraints
- Lactic Acid Feedstock Volatility:Fermentation-derived precursor costs fluctuate with agricultural commodity markets, compressing margins for domestic resin converters dependent on Corbion NV's supply chains.
- Clinical Validation Burden:Health Canada's resorption-byproduct toxicology requirements demand extensive preclinical documentation that extends development cycles by eighteen to thirty-six months for novel copolymer compositions.
- Permanent Implant Substitution:Titanium and cobalt-chrome alloys retain cost advantages for load-bearing applications where retrieval surgery remains clinically acceptable, limiting addressable market expansion.
Strategic Opportunities
- Drug Delivery Integration:Controlled-release functionality in resorbable carriers opens orthopedic and oncology applications where localized therapeutic delivery eliminates systemic dosing complications.
- Quebec Manufacturing Expansion:Specialized medical-grade resin capabilities around Montreal offer underutilized fermentation and polymerization capacity for domestic production scale-up.
- 3D Printing Adoption:Patient-specific scaffold geometries for craniomaxillofacial reconstruction are penetrating Toronto's hospital procurement networks, displacing standardized off-the-shelf implants.
Industry Challenges
- Biomaterials Talent Scarcity:Polymer chemists with dual expertise in degradation kinetics and medical device regulatory pathways command premium compensation, constraining R&D team expansion.
- Cleanroom Capex Requirements:ISO 14644 Class 7 certification for implantable device fabrication demands facility investments exceeding fifteen million dollars per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Bioresorbable Polymers Market |
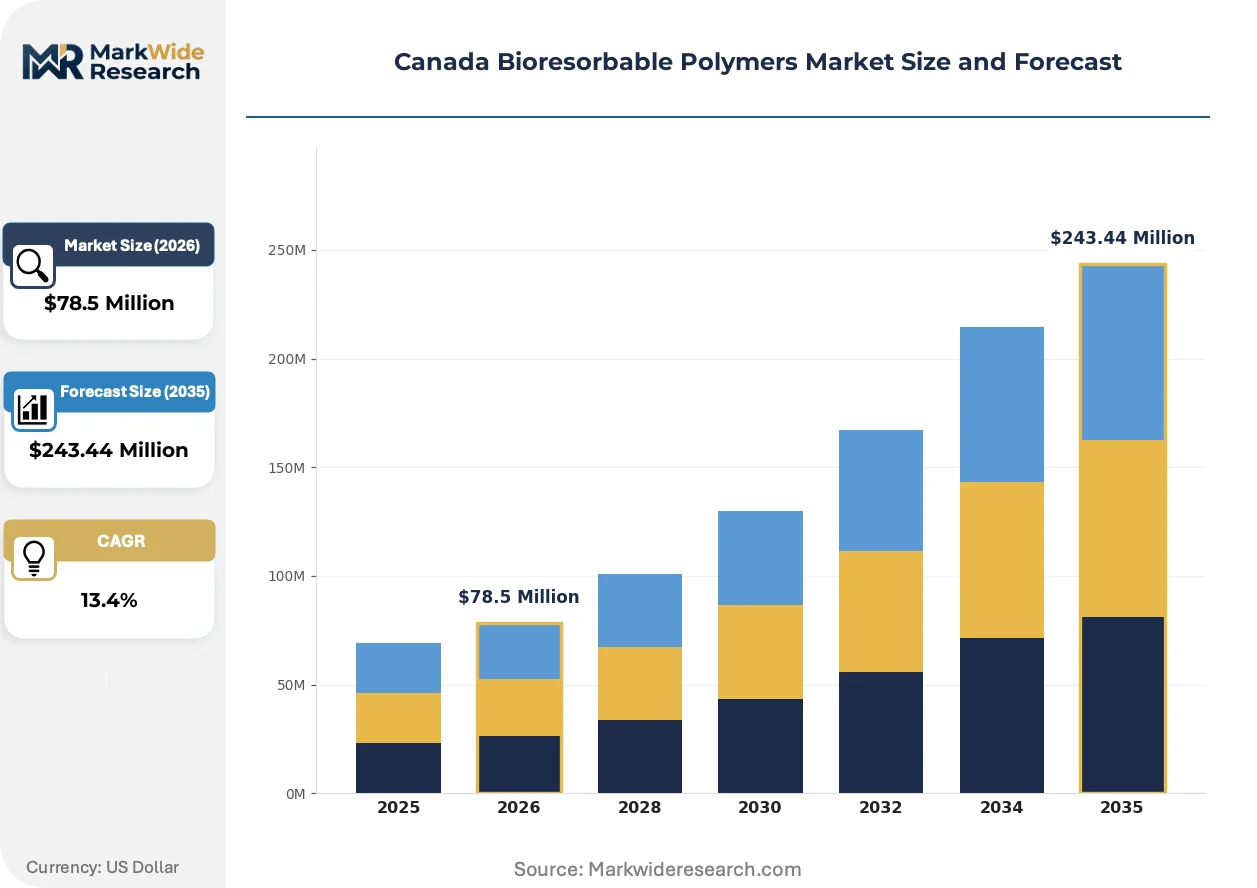
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $243.44 Million |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polylactic Acid, Polycaprolactone, Polyhydroxyalkanoates, Others Application: Medical Devices, Drug Delivery, Sutures, Tissue Engineering End User: Hospitals, Research Institutions, Clinics, Pharmaceutical Companies Technology: Injection Molding, Extrusion, 3D Printing, Electrospinning |
| Companies Covered | Evonik Industries AG, Corbion NV, Poly-Med Inc., Foster Corporation, DSM Biomedical, KLS Martin Group, Ashland Global Holdings Inc., Zeus Company LLC, Seqens Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Bioresorbable Polymers Market Strategic Shifts & Innovations
Electrospinning technology is reshaping fabrication capabilities for bioresorbable polymers, enabling sub-micron fiber architectures that accelerate tissue integration while compressing traditional mesh production timelines.
Electrospun polycaprolactone-gelatin composites are absorbing market share from conventional melt-spun fibers in wound-closure applications. Quebec-based manufacturers are retrofitting production lines to accommodate solvent-based electrospinning systems. The technology is absorbing capital allocation previously directed toward incremental injection molding capacity expansions.
Health Canada's anticipated alignment with MDR-equivalent classification rules for absorbable implants is forcing manufacturers to restructure quality management systems. Device sponsors must now submit periodic safety update reports that track degradation-byproduct accumulation in vivo. Toronto's regulatory consulting sector is expanding headcount to manage pre-submission briefing packages.
Hospital procurement committees are consolidating vendor relationships around full-service polymer suppliers offering validated sterilization and packaging capabilities. Ontario's hospital networks are displacing fragmented multi-source purchasing with single-source agreements spanning raw resin through finished device. Quebec's integrated polymer producers capture disproportionate share of these consolidated contracts.
Canada Bioresorbable Polymers Market Segmentation
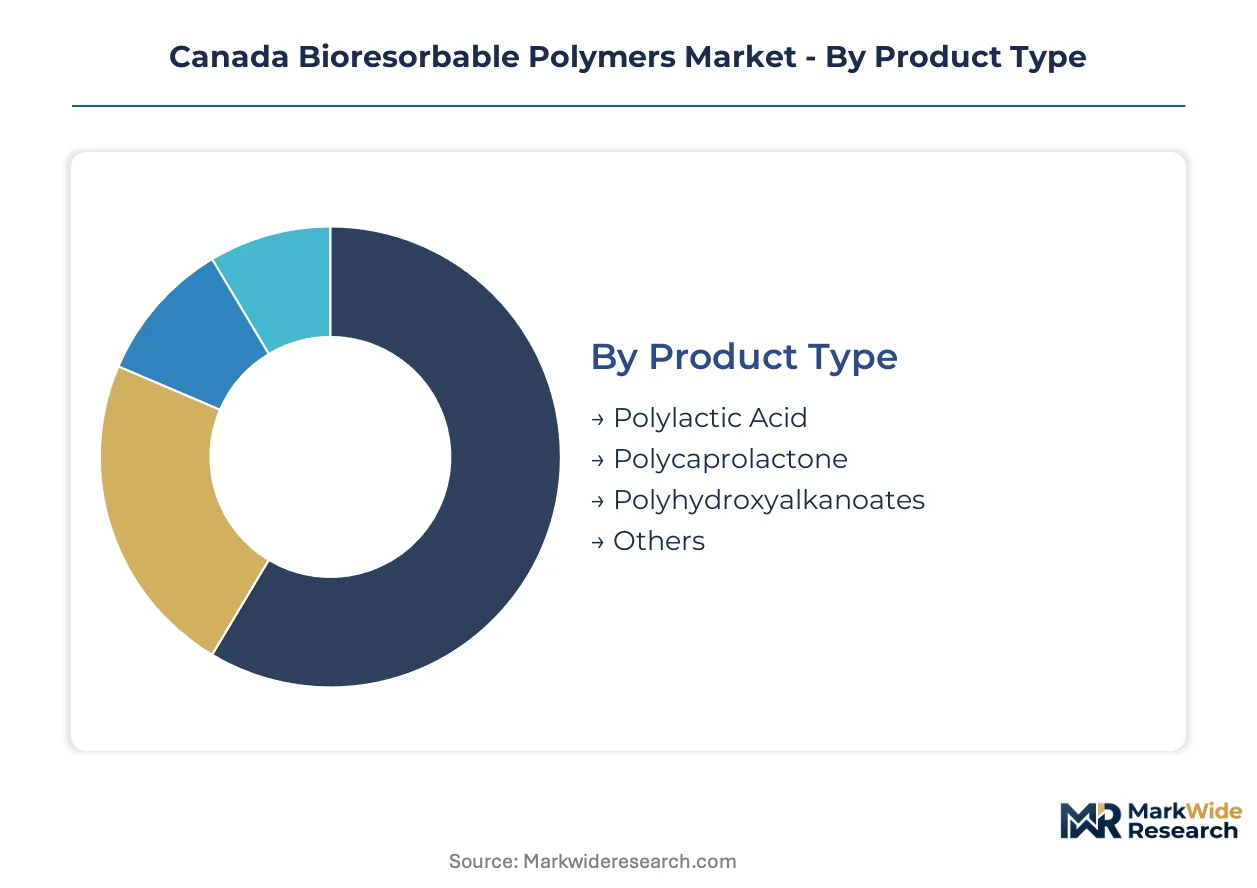
Segmentation reveals how procurement authority, fabrication constraints, and clinical validation requirements reshape competitive positioning across Canada's bioresorbable polymer value chain. Buyers in Toronto's hospital networks prioritize validated sterilization capabilities, while Quebec's resin converters compete on fermentation-derived precursor purity.
Product Type:
Cost tier differentiation separates commodity-grade resins from medical-certified formulations requiring extended degradation-byproduct toxicology documentation.
- Polylactic Acid:Semi-crystalline thermoplastic with tunable degradation windows spanning six to twenty-four months depending on molecular weight and stereochemistry. Ontario's orthopedic implant manufacturers concentrate procurement around high-purity PLLA grades for spinal fusion cages, driven by Health Canada's alignment with ISO 10993 degradation protocols.
- Polycaprolactone:Aliphatic polyester exhibiting slower hydrolytic degradation than PLA, extending structural integrity to thirty-six months in load-bearing applications. Quebec's electrospinning specialists favor PCL for sub-micron fiber mesh production targeting wound-closure contracts with Toronto's university-affiliated research hospitals.
- Polyhydroxyalkanoates:Bacterial fermentation-derived polyesters with intrinsic biocompatibility advantages for sensitive tissue contact applications.
- Others:Copolymer formulations and novel compositions including polyglycolic acid and trimethylene carbonate blends entering preclinical pipelines.
Volume sits with polylactic acid; growth tilts toward polycaprolactone.
Application:
Application selection determines regulatory pathway complexity and sterilization validation requirements.
- Medical Devices:Structural implants including fracture fixation plates, interference screws, and craniofacial reconstruction scaffolds fabricated through injection molding or 3D printing. Toronto's hospital procurement committees are consolidating vendor relationships around full-service suppliers offering validated packaging through finished device.
- Drug Delivery:Resorbable microparticles, implants, and hydrogels enabling localized therapeutic release with elimination of retrieval surgery. This segment is climbing the fastest as oncology and orthopedics manufacturers integrate controlled-release functionality to eliminate systemic dosing complications.
- Sutures:Absorbable monofilament and braided configurations for internal wound closure with programmed tensile strength retention profiles.
- Tissue Engineering:Porous scaffolds seeded with autologous cells for regenerative medicine applications in cartilage and bone reconstruction.
Medical Devices dominates current revenue; drug delivery absorbs disproportionate R&D allocation.
End User:
Customer type dictates order scale, technical support intensity, and regulatory documentation depth.
- Hospitals:Direct procurement of sterile-packaged finished devices for surgical implantation, with Toronto's university-affiliated networks exercising concentrated purchasing authority. Ontario's expanding surgical volumes for fracture fixation are strengthening demand for temporary structural scaffolds with tunable resorption profiles.
- Research Institutions:Small-batch specialty formulations for preclinical and clinical investigation, requiring extensive Certificate of Analysis documentation.
- Clinics:Outpatient surgical centers with limited inventory capacity favoring just-in-time delivery of standardized suture and mesh configurations.
- Pharmaceutical Companies:Integrated drug-device combination product developers seeking validated excipient and carrier materials with established DMF filings.
Hospitals anchor procurement volume; pharmaceutical partnerships offer highest margin expansion potential.
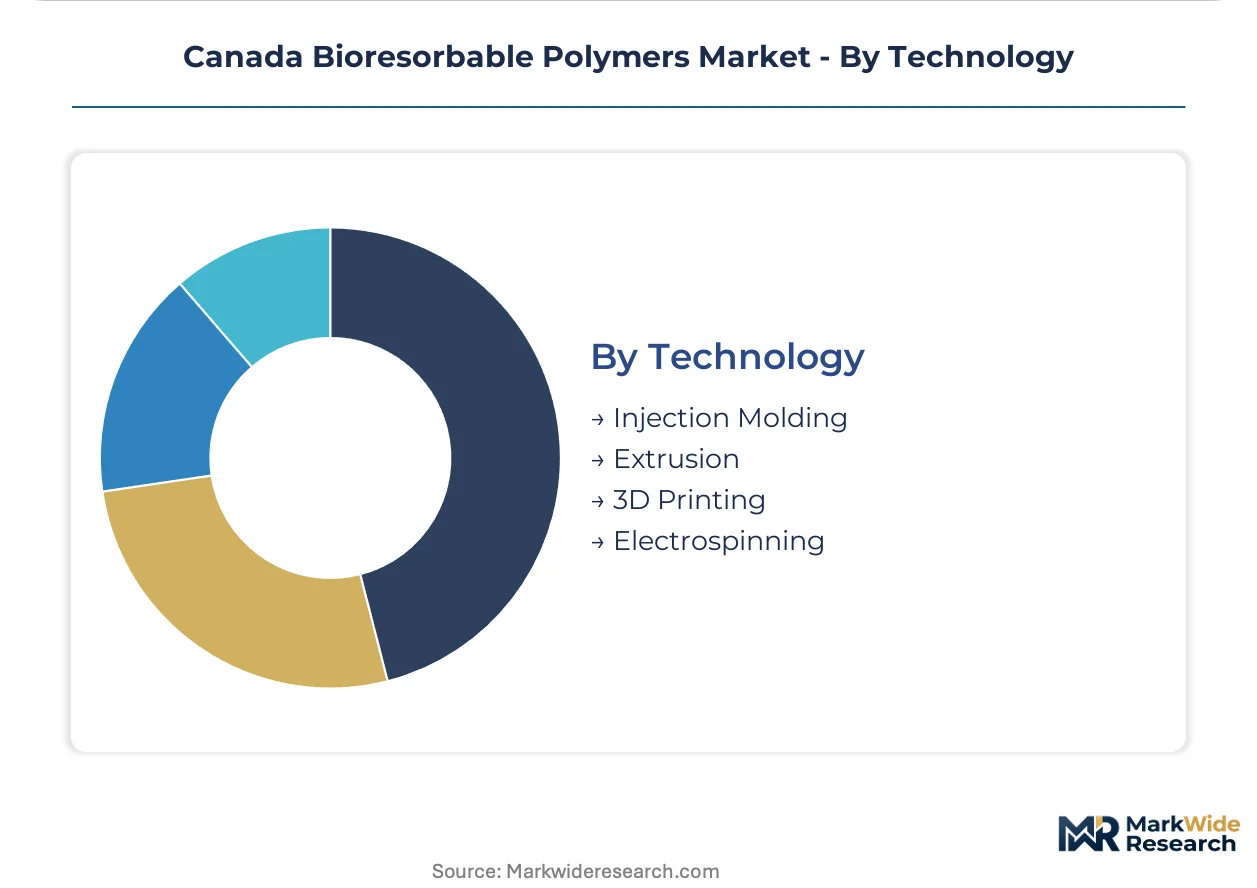
Technology:
Fabrication method selection constrains achievable geometries, surface architectures, and production economics.
- Injection Molding:High-throughput fabrication of complex implant geometries with tight dimensional tolerances and tunable crystallinity. Quebec's polymer production base leverages mature infrastructure for cost-efficient medical device component manufacturing.
- Extrusion:Continuous processing of fiber, rod, and sheet stock with controlled molecular orientation for suture and fixation pin applications.
- 3D Printing:Patient-specific scaffold fabrication enabling anatomically matched craniomaxillofacial reconstruction implants. Toronto's hospital networks are penetrating procurement channels for customized geometries displacing standardized off-the-shelf alternatives.
- Electrospinning:Solvent-based fiber formation producing sub-micron architectures that accelerate tissue integration while compressing traditional mesh production timelines.
Injection molding commands installed capacity; electrospinning captures capital allocation previously directed toward incremental expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-derived lactic acid from Quebec's agricultural processing belt anchors domestic resin production. Ontario's hospital procurement networks concentrate demand authority in Toronto's medical technology corridor. Health Canada's regulatory harmonization with ISO standards shapes cross-provincial supply chain configurations.
Ontario
University-affiliated research hospitals in Toronto drive surgical volumes for spinal fusion and fracture fixation devices. Health Canada's medical device licensing requirements compress development timelines for implant manufacturers. The Waterloo-Toronto corridor clusters polymer converters and sterilization service providers around hospital procurement committees.
Quebec
Montreal's fermentation infrastructure supplies high-purity lactic acid precursors to domestic resin manufacturers. The Canadian Standards Association governs biocompatibility testing protocols for materials produced in provincial polymerization facilities. Quebec City's electrospinning specialists retrofit production lines for sub-micron fiber mesh targeting wound-closure applications.
British Columbia
Vancouver's biomedical research institutes generate preclinical demand for specialty copolymer formulations. Health Canada's anticipated alignment with MDR-equivalent classification rules forces quality management system restructuring. The Vancouver-Seattle technology corridor facilitates cross-border collaboration on patient-specific 3D-printed scaffold development.
Alberta
Calgary's orthopedic surgery centers expand procedural volumes for sports medicine applications requiring temporary fixation devices. Health Canada's resorption-byproduct toxicology documentation requirements extend validation cycles for novel compositions. Edmonton polymer distributors serve regional device manufacturers with just-in-time resin delivery.
Canada Bioresorbable Polymers Market Key Industry Players
Global majors compete with regional champions across raw material supply and finished device fabrication. The market structure tiers between fermentation-derived precursor suppliers, specialized resin converters, and full-service device manufacturers. Three archetypes dominate: integrated polymer producers controlling upstream lactic acid supply, custom compounders serving niche orthopedic applications, and hospital-contracted sterilization-packaging integrators. Capacity expansion and strategic partnerships represent the primary competitive moves as manufacturers secure Health Canada validation certificates.
Among European-headquartered material suppliers, Evonik Industries AG and Corbion NV occupy positions anchoring global biomaterial networks to Canadian device manufacturers. Poly-Med Inc. exemplifies the North American specialist archetype, representing custom absorbable fiber and mesh configurators serving orthopedic and wound-closure segments. These three entities collectively illustrate the supply chain segmentation between precursor production, resin formulation, and application-specific fabrication that defines competitive positioning in Health Canada's regulated environment.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Corbion NV |
| Poly-Med Inc. |
| Foster Corporation |
| DSM Biomedical |
| KLS Martin Group |
| Ashland Global Holdings Inc. |
| Zeus Company LLC |
| Seqens Group |
| Others |
Cost & Logistics Intelligence
Polymer chemists with dual expertise in degradation kinetics and Health Canada regulatory pathways cluster in Toronto's medical technology corridor, commanding premium compensation that widens spreads between medical-certified formulations and commodity-grade resins. Labor-cost differentials between specialized biomaterials talent and standard manufacturing workforce directly translate into pricing-tier stratification across implantable device categories.
Pricing Analysis
After-sales service bundling separates full-service polymer suppliers offering validated sterilization and packaging from unbundled raw resin vendors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with Health Canada validation certificates commanding substantial premiums. Cost compression in standard-grade segments is intensifying because hospital procurement committees are consolidating vendor relationships around single-source agreements. Research institutions demonstrate highest price sensitivity due to small-batch specialty formulation requirements, while pharmaceutical companies show lowest sensitivity given integrated drug-device combination product margins.
Supply Chain Analysis
Cross-border freight costs from European fermentation facilities to Quebec's polymer production base influence landed cost structures for high-purity lactic acid precursors. Supply concentrates in the Netherlands through Corbion NV's fermentation infrastructure, Germany through Evonik Industries AG's biomaterials network, and domestic Quebec facilities around Montreal. Raw material dependencies include agricultural feedstocks for lactic acid fermentation, specialized catalysts for polymerization, and medical-grade packaging films. Single-source vulnerability around Corbion NV's supply chains creates structural risk given limited alternative fermentation-derived precursor availability. Distribution runs through hospital procurement committees in Toronto's university-affiliated research networks and sterilization-packaging integrators serving finished device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's resorption-byproduct toxicology requirements function as a cost-of-compliance barrier that protects validated incumbents while extending development cycles for novel entrants. This regulatory moat favors manufacturers with established ISO 10993 documentation and existing Health Canada medical device licenses.
For Market Incumbents: Acquire electrospinning production lines and solvent-based fiber formation capabilities to capture capital allocation shifting from injection molding expansion. Consolidate around full-service positioning offering validated sterilization through finished device to secure single-source hospital procurement agreements. Threat from permanent implant substitution by titanium alloys demands defensive investment in drug delivery integration capabilities. Capacity addition in Quebec's underutilized fermentation infrastructure represents the priority lever for margin protection against lactic acid feedstock volatility. For New Entrants and Emerging Players: Launch via research institution partnerships supplying small-batch specialty formulations with extensive Certificate of Analysis documentation. Target tissue engineering applications in Vancouver's biomedical research institutes where preclinical demand for specialty copolymer formulations remains underserved. Penetrate 3D printing service bureaus for patient-specific craniomaxillofacial reconstruction as the most accessible go-to-market angle given Toronto hospital network procurement channel consolidation. For Investors and Strategic Acquirers: Re-rating potential sits with custom absorbable fiber and mesh configurators given Health Canada's anticipated MDR-equivalent classification alignment forcing quality management system restructuring. Long-term viability over the next decade hinges on regulatory validation depth rather than manufacturing scale alone. Acquisition target archetype: Quebec-based electrospinning specialists with established hospital wound-closure contracts. Watch Health Canada's periodic safety update report requirements for absorbable implants as the signal for regulatory compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Validation Certificate Investment | Accelerates market authorization timelines for novel copolymer compositions entering clinical pipelines. |
| Quebec Fermentation Capacity Expansion | Captures underutilized lactic acid precursor production to reduce feedstock cost volatility exposure. |
| Electrospinning Technology Adoption | Enables sub-micron fiber architectures that accelerate tissue integration for wound-closure applications. |
| Hospital System Partnership Consolidation | Secures single-source procurement agreements with Toronto's university-affiliated research networks. |
| Drug Delivery Integration Development | Opens orthopedic and oncology applications with controlled-release functionality in resorbable carriers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Canada bioresorbable polymers market assessment. Primary interviews with biomedical engineers, hospital purchasing committee members, polymer chemists at resin converters, and Health Canada regulatory consultants combined with secondary validation from ISO 10993 documentation, Health Canada medical device licensing databases, and Quebec agricultural processing statistics. Bottom-up modeling of fermentation capacity and injection molding throughput triangulated against top-down hospital procurement expenditure patterns.
Segment-level granularity modeled product type across polylactic acid, polycaprolactone, polyhydroxyalkanoates, and copolymer formulations; application across medical devices, drug delivery, sutures, and tissue engineering; technology across injection molding, extrusion, 3D printing, and electrospinning; and end user across hospitals, research institutions, clinics, and pharmaceutical companies. CAGRs derived from surgical volume projections, regulatory approval velocity assumptions, and capital allocation trends across fabrication technologies. Forecast inputs included Health Canada alignment timelines with international harmonization initiatives and Quebec's fermentation infrastructure utilization rates.
Regulatory timeline delays, lactic acid feedstock price spikes, and permanent implant substitution acceleration are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Hydrocarbon Resins Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Polyurethanes (PU) Market