
 Tungsten Titanium Carbide Market | 2026-2036
Tungsten Titanium Carbide Market Size, Share, and Industry Trends Forecast 2026-2036
Tungsten Titanium Carbide Market Analytics
Additive manufacturing integration with conventional powder metallurgy is narrowing the performance gap between near-net-shape components and fully machined parts. Sumitomo Electric Industries leverages captive carbide production to control raw material consistency across its cutting tool portfolio. Sandvik AB anchors its position through deep R&D investment in cemented carbide microstructures. Kennametal Inc. competes by specializing in wear-resistant geometries for oil and gas drilling applications.
Tungsten titanium carbide is a binary ceramic-metal composite typically synthesized through high-temperature carburization of tungsten-titanium oxide precursors at temperatures exceeding 1,400°C, yielding a face-centered cubic crystal structure with exceptional hardness and thermal stability. Cutting tools command the largest share of application demand due to sustained aerospace and automotive machining volumes. Wear parts represent the fastest-expanding segment as mining operators prioritize equipment longevity in abrasive extraction environments. Powder formulations attract margin premiums when particle size distributions fall below one micron for thermal spray coating specifications.
REACH registration requirements in Europe and EPA hazardous air pollutant standards in the United States constrain permissible cobalt binder content and mandate dust exposure controls throughout manufacturing. China's GB standards and MIIT industrial policy directives shape export qualification thresholds for tungsten-containing materials entering Asian supply chains. Stakeholders must track evolving conflict mineral disclosure rules and binder-phase substitution research to anticipate sourcing and formulation decisions.
Market Dynamics
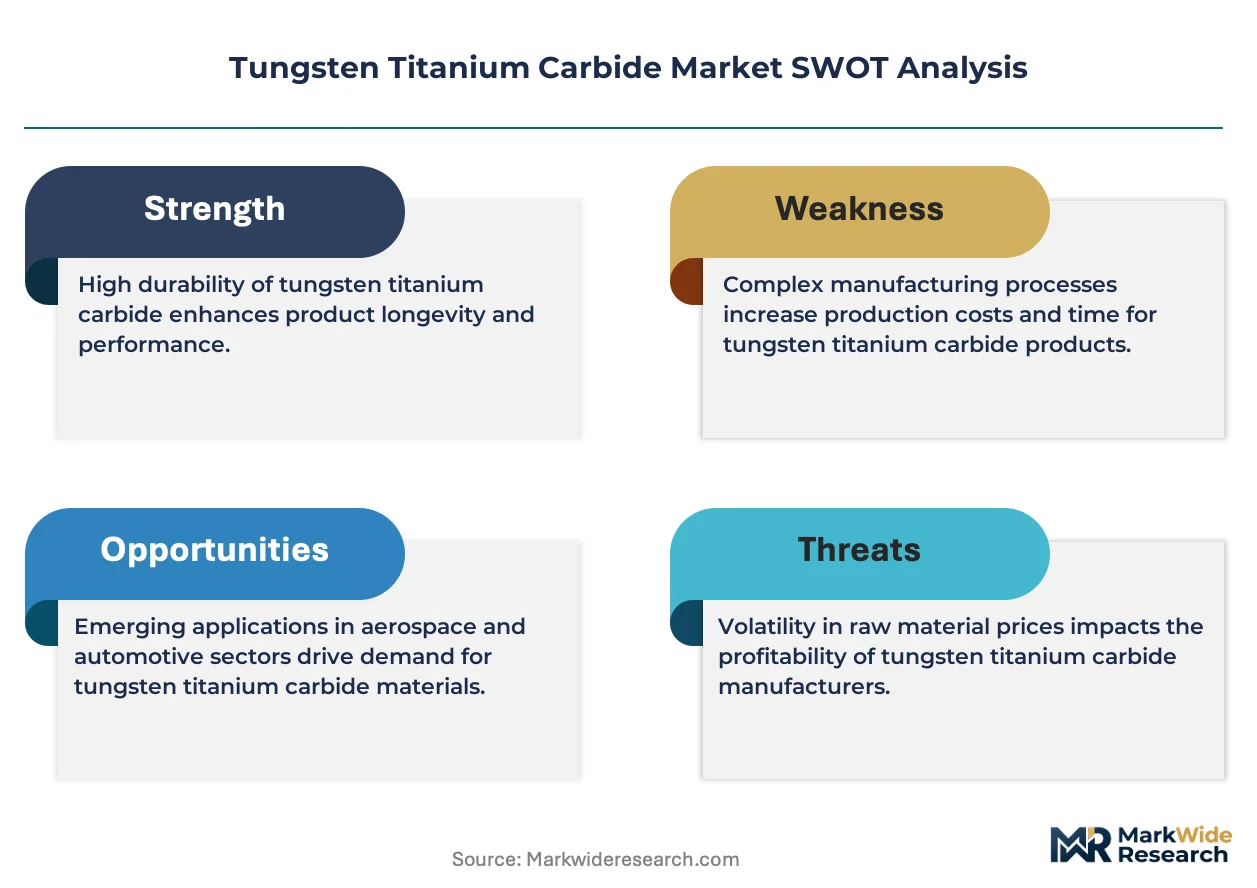
Aerospace thermal barrier specifications are compressing acceptable powder particle size distributions below one micron, forcing capital retooling across European and Asian supply bases while cemented carbide producers absorb purity compliance costs.
Growth Catalysts
- REACH Phase-In Substances:ECHA registration deadlines for tungsten compounds are accelerating binder-phase substitution R&D, opening qualification pathways for cobalt-free formulations in precision tooling.
- Abrasive Mining Environments:Copper and iron ore extraction operations in Chile and Australia are specifying extended wear part lifecycles, pulling demand for thermal-sprayed tungsten titanium carbide coatings.
- Additive Manufacturing Sintering:Binder jet and selective laser melting platforms are validating near-net-shape cemented carbide geometries previously machined from solid blanks.
Market Restraints
- Tungsten Concentrate Volatility:Chinese state reserve releases and export quota adjustments transmit price shocks through carbide powder contract structures.
- Cobalt Supply Geography:Democratic Republic of Congo dominance in mined cobalt creates conflict mineral disclosure friction under US Dodd-Frank and EU CSRD traceability mandates.
- Sintering Temperature Floor:Face-centered cubic crystal formation requires sustained thermal inputs above 1,400°C, limiting energy cost pass-through flexibility.
Strategic Opportunities
- India Machine Tool Buildout:PLI scheme incentives for capital goods manufacturing are creating first-mover advantages for carbide insert localization.
- Electric Vehicle Battery Tooling:Silicon carbide inverter machining and solid-state battery cell fabrication require ultra-hard cutting edges with thermal stability beyond conventional ceramics.
- Digital Twin Process Control:Real-time sintering atmosphere monitoring combined with predictive density modeling is reducing first-article rejection rates in powder metallurgy.
Industry Challenges
- Carbide Metallurgy Expertise:Retirement waves among European powder engineers are constraining know-how transfer for high-temperature carburization process optimization.
- Multi-Jurisdictional Certification:Simultaneous EPA hazardous air pollutant compliance, REACH SVHC screening, and China's GB standard export documentation extends qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tungsten Titanium Carbide Market |
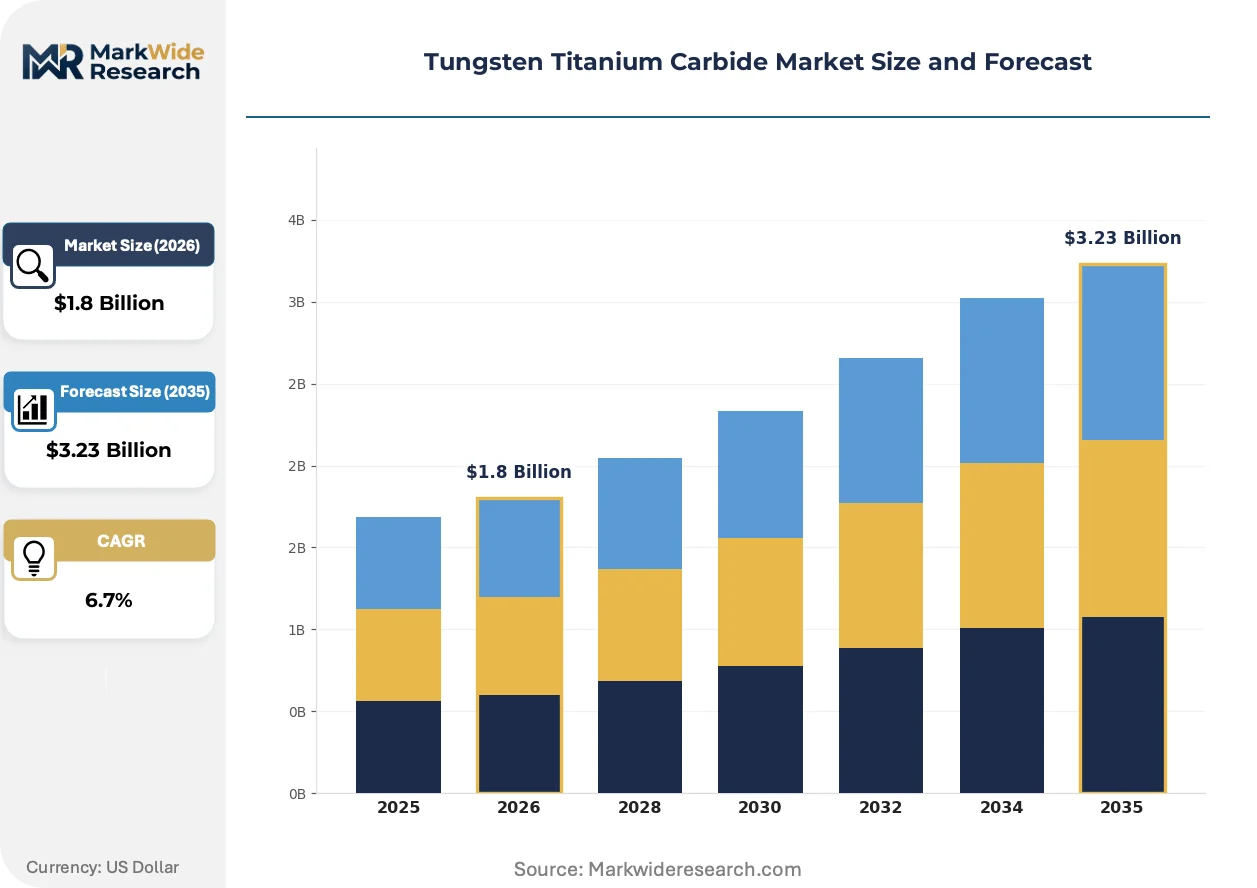
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Rods, Powders, Inserts End User: Aerospace, Defense, Manufacturing, Mining Form: Solid, Liquid, Granular, Paste Application: Cutting Tools, Abrasives, Wear Parts, Electrical Contacts |
| Companies Covered | Sumitomo Electric Industries, Xiamen Tungsten Co., Ltd., Sandvik AB, A.L.M.T. Corp., Guangdong Xianglu Tungsten Co., Ltd., Kennametal Inc., H.C. Starck GmbH, Federal Carbide Company, CERATIZIT S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tungsten Titanium Carbide Market Evolving Landscape
Process intensification in powder synthesis and regulatory pressure on hazardous binders are compressing traditional manufacturing timelines while opening substitution pathways for next-generation ceramic-metal composites.
Gas-phase carburization using tungsten-titanium oxide precursors is migrating from batch furnace operations toward continuous rotary kiln configurations. Aerospace coating applicators in Germany and Japan are qualifying these powder streams for thermal barrier deposition. The shift is compressing lot-to-lot variability premiums while elevating capital barriers for smaller toll processors.
EPA hazardous air pollutant standards for hard and brittle materials manufacturing are tightening dust exposure thresholds and mandating engineering controls across US production facilities. Cemented carbide toolmakers are responding with enclosed powder handling systems and automated press operations. The compliance burden falls heaviest on mid-volume producers serving oil and gas wear part segments.
Specification-driven procurement now dominates thermal spray coating supply relationships, with end-users in aerospace and power generation unbundling powder qualification from application service contracts. Third-party metallurgical laboratories in Stuttgart and Houston are capturing margin previously retained by integrated coating houses. This disintermediation is most pronounced in North American maintenance-repair-overhaul channels.
Tungsten Titanium Carbide Market Segmentation
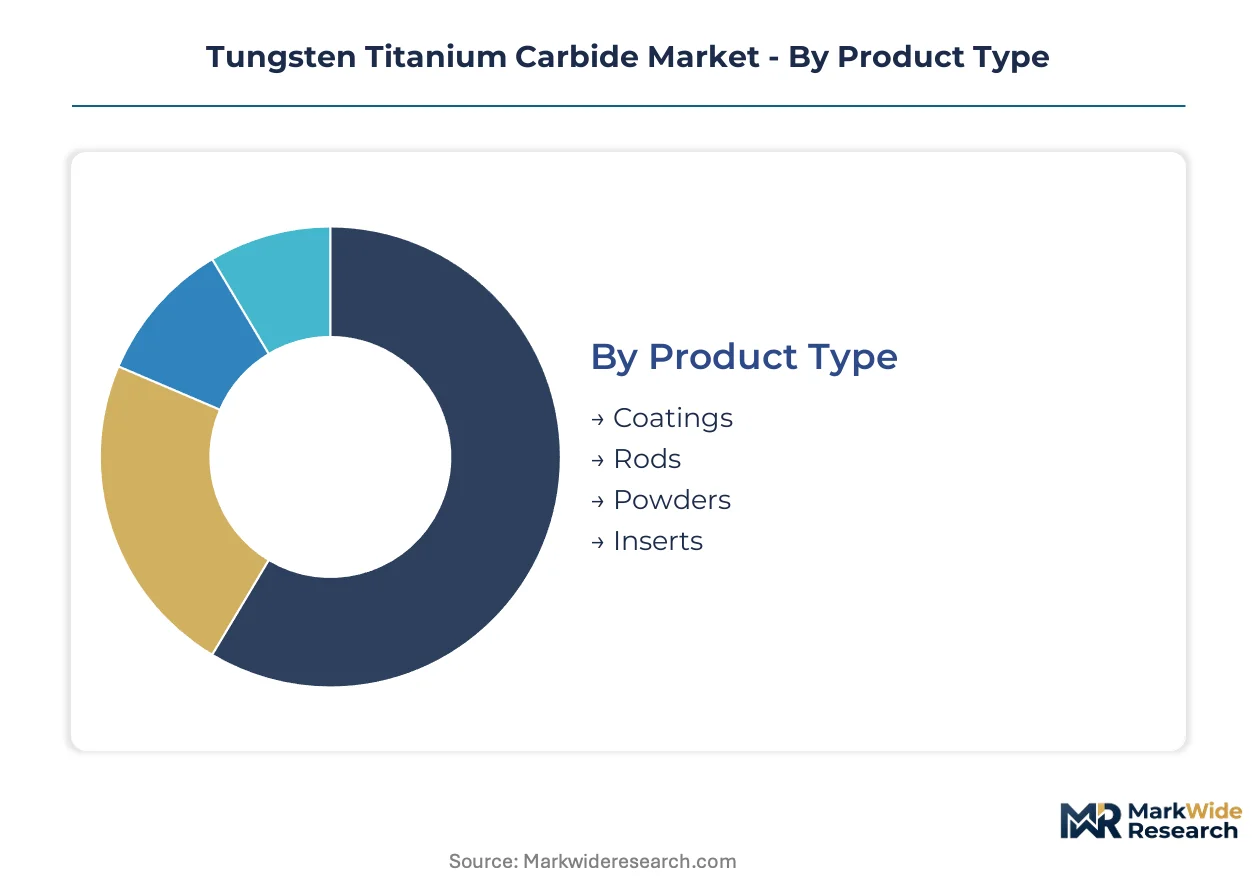
Segmentation in tungsten titanium carbide markets reveals how specification requirements fragment procurement patterns across aerospace coating applicators, precision tool manufacturers, and mining equipment operators. Each dimension—product geometry, end-use severity, physical state, and functional application—carries distinct purity thresholds and certification burdens that reshape supplier qualification timelines.
Product Type:
Cost tier separates commodity powder streams from qualified coating formulations commanding specification premiums in thermal spray and precision tooling supply chains.
- Coatings:Thermal barrier deposition specifications from aerospace engine manufacturers demand sub-micron particle size distributions with lot-to-lot variability below 3%. German applicators in Stuttgart and Japanese coating houses in Nagoya dominate qualification pathways for flight-critical turbine components.
- Powders:Gas-phase carburization yields face-centered cubic crystal structures at temperatures exceeding 1,400°C, with continuous rotary kiln migration compressing batch-to-batch inconsistency. REACH-registered powder streams attract margin premiums over toll-processed alternatives in European supply chains.
- Rods:Extruded cylindrical blanks serve solid tool fabrication for oil and gas drilling geometries requiring wear-resistant cemented carbide microstructures.
- Inserts:Indexable cutting edges for automotive and aerospace machining absorb the largest volume share of cemented carbide consumption.
Coatings hold installed capacity. Powders are rotating up the share rankings.
End User:
Application severity dictates material specification tiers, with flight-critical aerospace demands diverging sharply from bulk mining wear part requirements.
- Aerospace:Engine thermal barrier coatings require ECHA-registered powder streams with documented conflict mineral provenance under EU CSRD traceability mandates. Stuttgart-based metallurgical laboratories now capture third-party qualification revenue previously retained by integrated coating houses.
- Mining:Copper and iron ore extraction operations in Chile and Australia specify extended lifecycle wear coatings for abrasive environments, pulling demand toward thermal-sprayed tungsten titanium carbide formulations. This segment is gaining share fastest as equipment longevity prioritization displaces first-cost procurement.
- Defense:Munitions and armor applications drive demand for high-density kinetic energy penetrators with specific gravity requirements above 14 g/cm³.
- Manufacturing:General machining and metalworking consumes standardized cemented carbide inserts through distributor channels with limited specification differentiation.
Aerospace holds installed capacity. Mining is rotating up the share rankings.
Form:
Physical state determines handling infrastructure requirements and regulatory exposure thresholds across manufacturing facilities.
- Solid:Sintered blanks and finished cutting tools dominate volume consumption through conventional powder metallurgy supply chains.
- Powder:Granular and atomized formulations serve thermal spray, additive manufacturing, and press-and-sinter operations with dust exposure controls mandated by EPA hazardous air pollutant standards.
- Liquid:Suspension-based coating precursors enable electrophoretic deposition for complex geometries in aerospace component restoration.
- Paste:Binder-laden feedstocks support additive manufacturing platforms validating near-net-shape cemented carbide geometries.
Solid holds installed capacity. Powder is rotating up the share rankings.
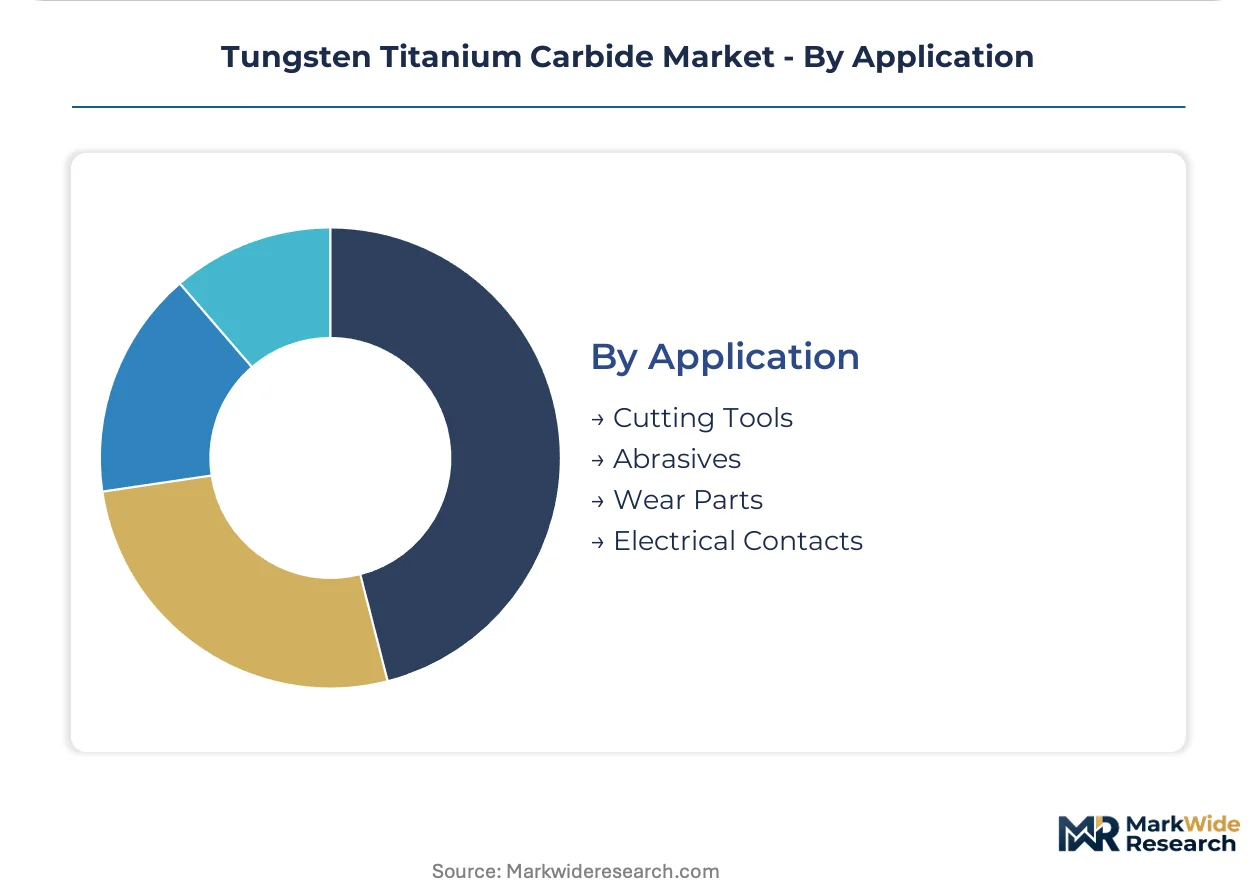
Application:
Functional use case determines performance validation protocols, with cutting tool qualification timelines extending 18-24 months for aerospace tier-one suppliers.
- Cutting Tools:Cemented carbide inserts command the largest revenue share due to sustained aerospace and automotive machining volumes. Sumitomo Electric Industries and Sandvik AB anchor supply through captive carbide production and microstructure R&D respectively.
- Wear Parts:Mining dragline buckets, crusher liners, and pump housings in abrasive extraction environments represent the steepest expansion trajectory as operators prioritize total cost of ownership over replacement frequency.
- Abrasives:Grinding wheel formulations exploit exceptional hardness for precision finishing operations in Germany's Solingen tooling cluster.
- Electrical Contacts:High-current switching applications leverage thermal stability and arc erosion resistance in power distribution equipment.
Cutting tools hold installed capacity. Wear parts are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision tooling manufacturers and aerospace coating applicators concentrate procurement authority across Germany, Japan, China, the United States, and Australia, with each geography imposing distinct purity thresholds and certification timelines on tungsten titanium carbide suppliers.
Germany
Stuttgart-based aerospace engine manufacturers drive thermal barrier coating specifications below one micron particle size. ECHA REACH registration deadlines accelerate cobalt-free binder formulation R&D across Baden-Württemberg. Solingen's precision tooling cluster absorbs REACH-registered powder streams for cemented carbide insert fabrication.
Japan
Nagoya coating houses qualify gas-phase carburization powders for flight-critical turbine components. METI industrial policy directs tungsten concentrate stockpiling strategies. Osaka-Kobe manufacturing belt integrates captive carbide production into cutting tool supply chains.
China
Xiamen and Ganzhou tungsten processing centers supply global carbide powder streams under MIIT industrial policy directives. GB standards and export quota mechanisms shape qualification thresholds for Asian supply chains. State reserve releases transmit price volatility through international contract structures.
United States
EPA hazardous air pollutant standards tighten dust exposure thresholds across hard materials manufacturing. Oil and gas drilling equipment operators in Texas specify wear-resistant cemented carbide geometries. Pittsburgh and Cleveland machining corridors source cobalt-containing inserts under Dodd-Frank conflict mineral disclosure mandates.
Australia
Copper and iron ore extraction operations in Western Australia specify extended lifecycle wear coatings for abrasive environments. Thermal-sprayed tungsten titanium carbide formulations penetrate mining maintenance-repair-overhaul channels. Perth-based equipment operators prioritize total cost of ownership over replacement frequency in procurement decisions.
Tungsten Titanium Carbide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply structures. Consolidation concentrates among Japanese and Swedish cemented carbide producers with captive raw material integration. Three archetypes dominate: vertically integrated powder-to-tool manufacturers, application-specialist coating houses, and toll-processing intermediaries. Strategic moves center on binder-phase substitution R&D and continuous rotary kiln capacity expansion.
Among Japanese electrical and materials conglomerates, Sumitomo Electric Industries and A.L.M.T. Corp. occupy positions emphasizing captive tungsten carbide production control. Swedish engineering groups represented by Sandvik AB anchor premium-tier cemented carbide microstructure development. Chinese state-affiliated processors including Xiamen Tungsten Co., Ltd. and Guangdong Xianglu Tungsten Co., Ltd. exemplify upstream concentrate-to-powder integration models. German specialty chemical and powder metallurgy players such as H.C. Starck GmbH sit within high-purity specification supply chains serving aerospace qualification pathways. US-based tooling specialists represented by Kennametal Inc. and Federal Carbide Company concentrate on wear-part geometries for extractive industries.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Xiamen Tungsten Co., Ltd. |
| Sandvik AB |
| A.L.M.T. Corp. |
| Guangdong Xianglu Tungsten Co., Ltd. |
| Kennametal Inc. |
| H.C. Starck GmbH |
| Federal Carbide Company |
| CERATIZIT S.A. |
| Others |
Value Network & Pricing Analysis
Rotary kiln undercapacity in European powder synthesis is forcing aerospace coating applicators to accept longer lead times while cemented carbide producers absorb REACH compliance premiums into contract structures. This utilization squeeze concentrates pricing power among gas-phase carburization operators with validated continuous production lines.
Pricing Analysis
Cost-plus contracts indexed to tungsten concentrate benchmarks dominate long-term powder supply agreements between Chinese processors and European tooling manufacturers. Three-tier pricing structure across REACH-registered premium, standard industrial, and toll-processed economy levels reflects certification burden and lot-to-lot variability guarantees. Cost compression in the economy tier is intensifying because mid-volume oil and gas wear part producers lack specification leverage. Mining equipment operators exhibit highest price sensitivity due to total cost of ownership procurement frameworks, while aerospace engine manufacturers accept premium tiers for thermal barrier coating qualification security.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for tungsten concentrate and carbide powder flows. Production gravity centers on China's Xiamen and Ganzhou processing hubs, with secondary concentration in Germany's Stuttgart coating cluster and Japan's Nagoya metallurgical corridor. Raw material flows draw from Congolese cobalt, Vietnamese tungsten concentrates, and Australian iron ore extraction equipment demand. Single-source vulnerability persists in sub-micron powder qualification pathways where ECHA-registered streams pass through Stuttgart-based third-party laboratories. Distribution runs through direct mill relationships for aerospace tier-one suppliers and distributor networks for general machining insert procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tungsten titanium carbide markets present a service-attach opportunity as thermal spray coating application services expand faster than commodity powder sales, with end-users unbundling qualification from hardware procurement.
For Market Incumbents: Insulate margin position by deepening captive carbide production control and accelerating cobalt-free binder formulation R&D ahead of REACH SVHC screening expansions. Cemented carbide producers should add continuous rotary kiln capacity in Baden-Württemberg to compress lot-to-lot variability premiums and defend against toll-processing disintermediation. For New Entrants and Emerging Players: India's machine tool PLI scheme incentives represent the most penetrable entry point for carbide insert localization, with Western Australia's mining maintenance-repair-overhaul channels offering secondary white-space for thermal spray service contracts. A qualification-first go-to-market angle partnering with Stuttgart metallurgical laboratories bypasses the capital barrier of integrated coating house infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous rotary kiln powder synthesis as batch furnace operations face obsolescence. Long-term viability over a multi-year horizon favors acquisition targets with ECHA-registered powder streams and aerospace qualification pathways already validated. The signal to watch is migration of thermal spray coating contracts toward specification-driven procurement with unbundled third-party metallurgical validation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Rotary Kiln Capacity Expansion | Compresses batch-to-batch inconsistency premiums for aerospace powder qualification. |
| Cobalt-Free Binder Formulation R&D | Anticipates REACH SVHC restrictions and Dodd-Frank conflict mineral disclosure friction. |
| Third-Party Metallurgical Laboratory Partnership | Captures margin from disintermediation of integrated coating house qualification revenue. |
| India Machine Tool Localization Buildout | Secures first-mover positioning under PLI scheme capital goods manufacturing incentives. |
| Digital Twin Sintering Process Control | Reduces first-article rejection rates through real-time atmosphere monitoring and predictive density modeling. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed cemented carbide producers, ECHA registration databases, and MIIT industrial policy directives. Powder metallurgy plant managers, aerospace coating applicator procurement leads, mining equipment maintenance directors, and thermal spray service technicians provided operational validation. Bottom-up segment sizing triangulates against top-down macroeconomic elasticity assumptions.
Forecast inputs include powder particle size distribution migration timelines, REACH registration deadline compliance costs, and additive manufacturing platform validation curves across the projection horizon. Segmentation dimensions model product geometry, end-use severity, physical state, and functional application tiers. CAGRs derive from elasticity-adjusted volume projections and specification-premium capture rates in thermal barrier coating supply chains.
Practitioners should monitor Chinese state reserve release schedules, ECHA SVHC candidate list expansions, and binder-phase substitution breakthroughs for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Quenched and Tempered Steel Market