
 Global Metal Injection Molding Market | 2026-2036
Global Metal Injection Molding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Injection Molding Market Foresight
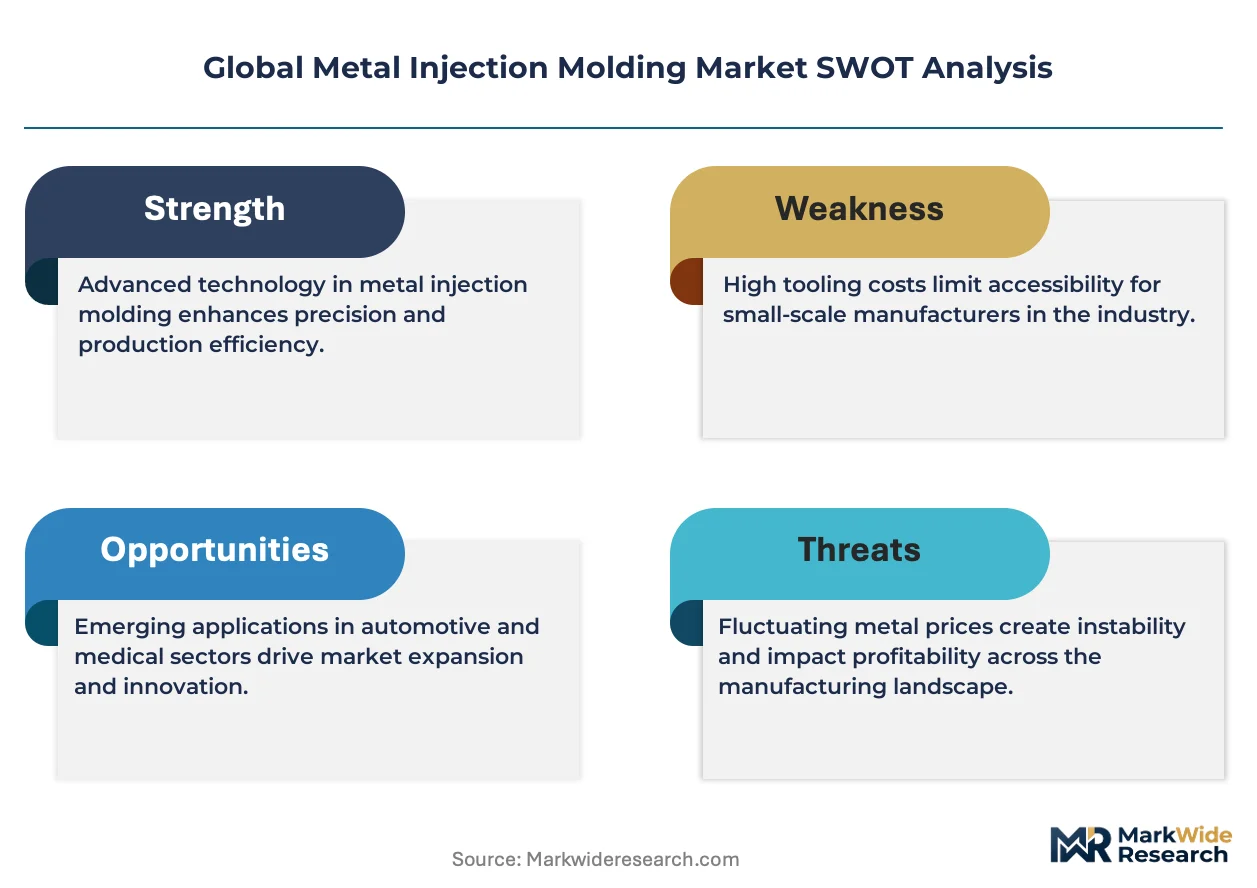
Asset-light contract manufacturing and equipment leasing arrangements is reconfiguring capital barriers for new entrants in metal injection molding, enabling smaller specialists to access multi-cavity tooling without full ownership burdens. Parmaco Metal Injection Molding AG leverages Swiss precision engineering heritage to dominate high-tolerance medical and aerospace contracts. OptiMIM sustains technology leadership through proprietary titanium alloy processing capabilities. Xometry competes via digital quoting platforms that aggregate fragmented job-shop capacity across North America and Europe.
Metal injection molding combines fine metal powders with thermoplastic binders to form complex near-net-shape components through injection, debinding, and sintering cycles, typically achieving densities exceeding 95 percent of theoretical while holding dimensional tolerances of ±0.3 percent. Stainless steel formulations occupy the largest product-type position due to corrosion resistance requirements across medical instrumentation and consumer goods. Titanium alloys represent the fastest-expanding material category, driven by aerospace component lightweighting and biocompatible medical device demand. Electronic devices applications command concentrated margin pools where miniaturization tolerances exclude conventional machining alternatives.
FDA material master file requirements and EU MDR conformity pathways shape feedstock qualification timelines and batch traceability obligations for medical device suppliers. REACH substance restrictions and evolving EPA air-emission standards for thermal debinding processes compound compliance costs for European and North American producers. Stakeholders must monitor evolving ISO 22068 sintering standards and regional carbon-border adjustments that threaten to reallocate cost advantages among Germany, China, and the United States.
Market Dynamics
Feedstock purity mandates from FDA material master file pathways and EU MDR conformity requirements are compressing supplier qualification timelines while reallocating procurement power toward vertically integrated powder producers.
Growth Catalysts
- Titanium alloy processing advances:Aerospace lightweighting requirements and biocompatible implant demand are expanding addressable component geometries beyond conventional machining limits.
- REACH substance restrictions:European feedstock purity standards are accelerating supplier consolidation toward certified master alloy producers with batch traceability infrastructure.
- German precision manufacturing clusters:Concentrated aerospace and medical device supply chains in Baden-Württemberg and Bavaria anchor volume commitments for multi-cavity tooling investments.
Market Restraints
- Thermal debinding emission controls:EPA air-emission standards and evolving MEE requirements in China are elevating capital intensity for captive thermal processing facilities.
- Master alloy supply concentration:Premium gas-atomized powder production concentrates among Japanese and German suppliers, exposing buyers to freight volatility and currency fluctuation.
- Dimensional tolerance ceilings:Sintering shrinkage variation limits MIM viability for sub-50-micron tolerance bands where CNC grinding remains dominant.
Strategic Opportunities
- Indian medical device manufacturing:CDSCO regulatory harmonization and PLI scheme incentives are attracting contract manufacturers to establish titanium MIM capacity for export markets.
- Carbon-border adjustment mechanisms:EU CBAM implementation creates first-mover advantage for European producers with renewable thermal debinding energy sourcing.
- Digital quoting platform aggregation:Job-shop capacity fragmentation across North America and Europe enables platform intermediaries to capture margin from price-transparent spot purchasing.
Industry Challenges
- Debinding process engineering talent:Specialized expertise in solvent and thermal debinding parameter optimization remains scarce relative to conventional powder metallurgy skill pools.
- ISO 22068 sintering standard alignment:Evolving international sintering standards create certification lag for producers serving multiple regulatory jurisdictions simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Injection Molding Market |
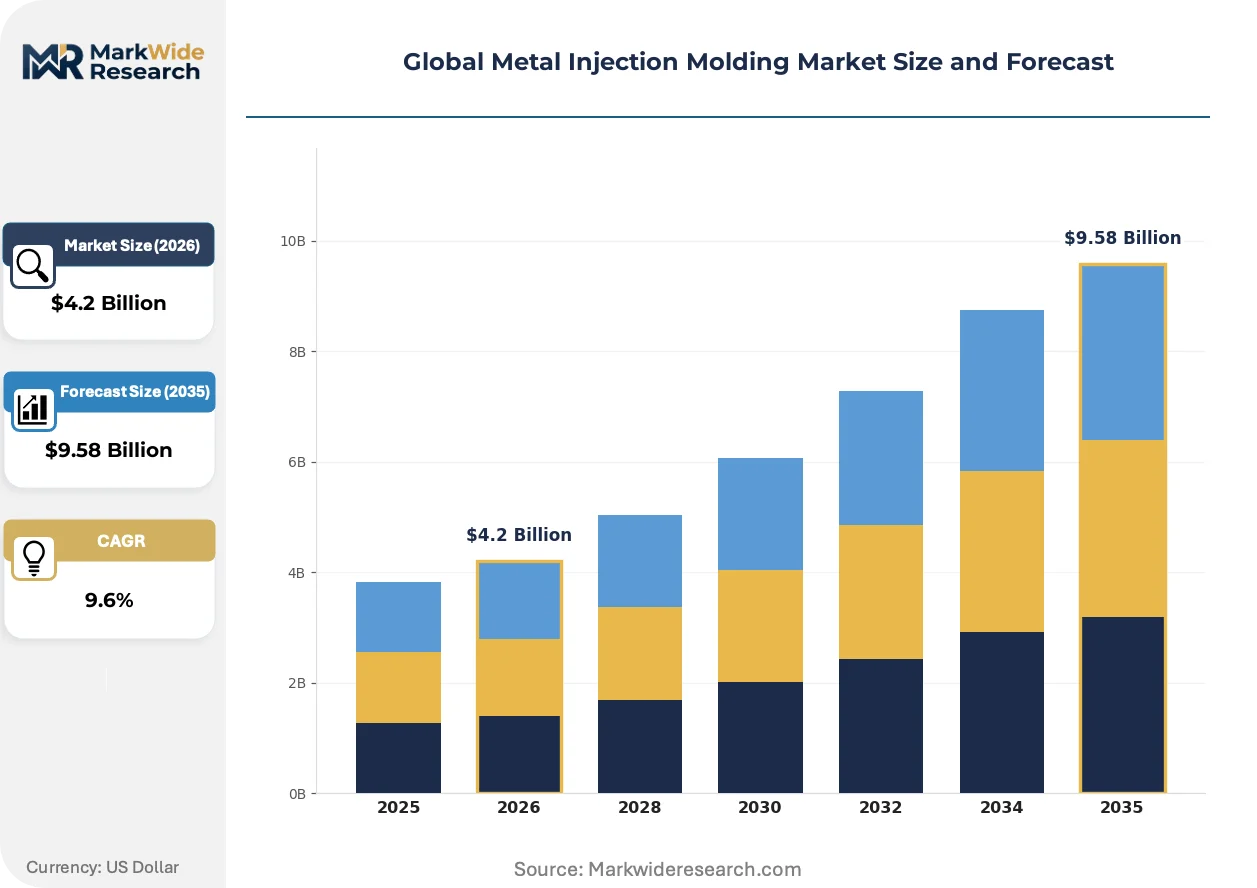
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $9.58 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Titanium, Copper Alloys, Nickel Alloys, Tool Steel Application: Aerospace Components, Electronic Devices, Industrial Machinery, Consumer Goods, Medical Instrumentation End User: Aerospace Manufacturers, Electronics Producers, Machinery Fabricators, Medical Device Makers, Consumer Product Companies Distribution Channel: Direct Sales, Distributors, OEM Partnerships, E-commerce Platforms, Technical Service Providers |
| Companies Covered | Mold-Masters, Takata Plastic, Parmaco Metal Injection Molding AG, San Technology, Inc., Flex Ltd., OptiMIM, KraussMaffei, Xometry, Hi-P International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Injection Molding Market Shifts & Advancements
Process simulation and digital twin architectures are compressing tooling iteration cycles while enabling remote process optimization across distributed manufacturing networks.
Multi-physics sintering simulation software is virtualizing traditional trial-and-error furnace parameter development. Medical device contract manufacturers in Switzerland and Germany are deploying these tools to reduce first-article qualification timelines by half. The technology is virtualizing capital allocation patterns, enabling smaller specialists to bid complex aerospace contracts without legacy furnace-hour accumulation.
EU MDR conformity assessment pathways and FDA material master file requirements are tightening batch-level traceability obligations for implantable device feedstock. Manufacturers must now document powder lot genealogy through atomization, sizing, and blending stages. Titanium spinal implant suppliers face the steepest compliance burden, driving backward integration into gas-atomization capacity.
Consolidated procurement desks at major aerospace OEMs are compressing supplier qualification cycles while demanding outcome-based quality guarantees. Tier-one contractors in the United States and Germany are replacing transactional spot purchasing with multi-year capacity reservations. This pattern concentrates volume among producers with demonstrated FDA and EASA dual certification, marginalizing uncertified job shops.
Global Metal Injection Molding Market Segmentation
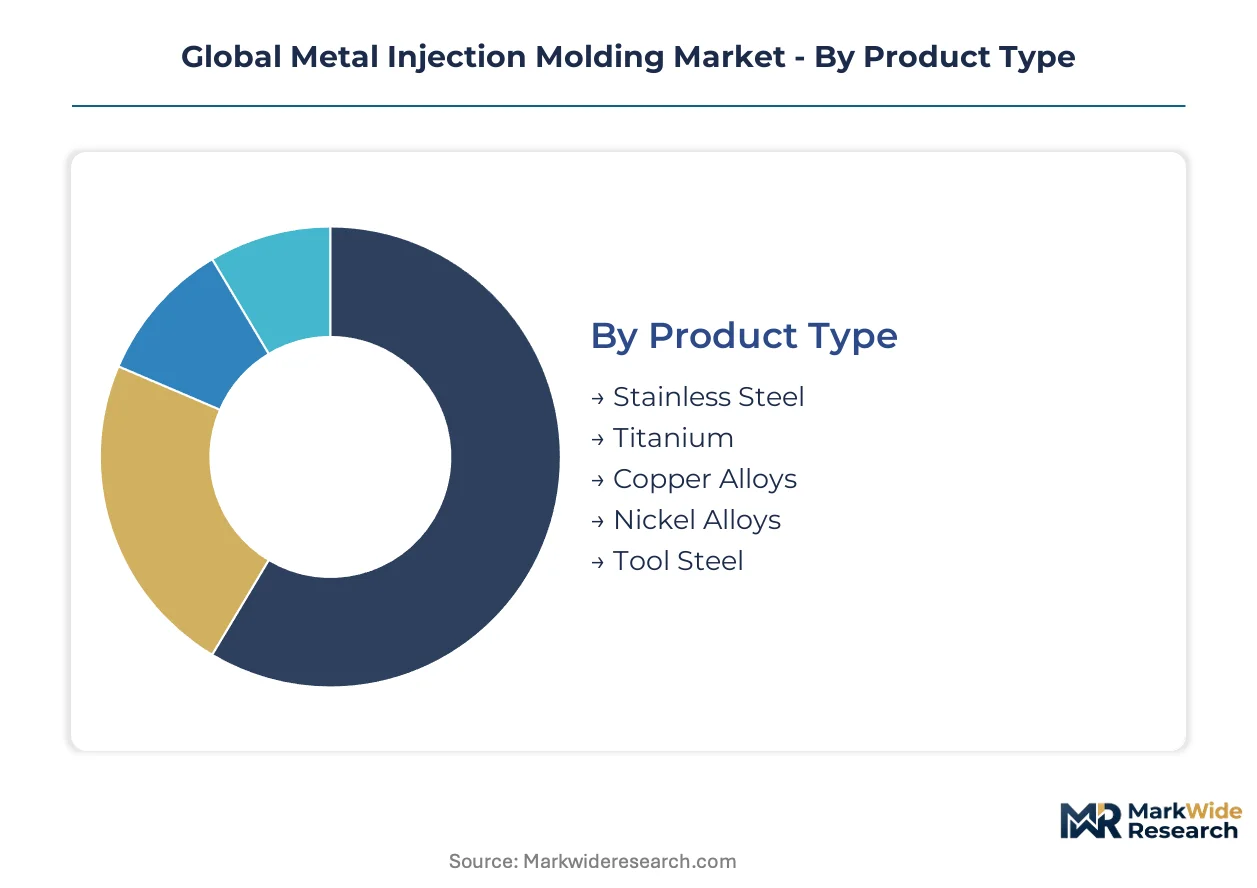
Segmentation in metal injection molding reveals how material specifications, application tolerances, and certification requirements fragment procurement patterns across aerospace, medical, and electronics verticals. Each dimension carries distinct margin structures and qualification barriers that reshape supplier competitive position.
Product Type:
After-sales service intensity varies sharply by alloy family, with titanium and medical-grade stainless steel demanding batch traceability support and failure analysis capabilities that commodity grades do not require.
- Stainless Steel:Austenitic and martensitic formulations dominate corrosion-sensitive applications. Medical instrumentation procurement in Germany and Switzerland concentrates here, driven by EU MDR conformity requirements for surgical instrument sterilization cycles.
- Titanium:Ti-6Al-4V and CP titanium grades achieve strength-to-weight ratios exceeding conventional alloys. Aerospace lightweighting mandates from Boeing and Airbus suppliers in the United States and France are accelerating demand for complex structural brackets previously machined from billet.
- Copper Alloys:High thermal conductivity grades serve heat dissipation components in power electronics.
- Nickel Alloys:Inconel and Haynes variants withstand extreme temperatures in turbine applications.
- Tool Steel:Hardenable grades support wear-resistant industrial tooling inserts.
Stainless steel holds the largest share; momentum sits with titanium.
Application:
Cost tier stratification separates aerospace and medical applications—where FDA and EASA dual certification commands premium pricing—from consumer goods competing on cycle time and unit economics.
- Aerospace Components:Structural brackets, latches, and hinge mechanisms leverage MIM's net-shape capability to eliminate machining waste. Tier-one contractors in Baden-Württemberg and Seattle anchor multi-year capacity reservations for flight-critical hardware.
- Electronic Devices:Miniaturized connectors, shielding enclosures, and thermal management components exploit MIM's ability to hold ±0.3 percent tolerances at sub-gram masses. South Korean and Japanese electronics OEMs drive volume for smartphone hinge mechanisms.
- Industrial Machinery:Wear-resistant gears and valve components serve fluid power and automation equipment.
- Consumer Goods:Watch cases, eyewear hinges, and luxury hardware compete on surface finish and plating compatibility.
- Medical Instrumentation:Surgical forceps, retractors, and implantable spinal hardware demand biocompatible surface finishes and lot-level genealogy documentation.
Electronic devices command concentrated margin pools; aerospace components are expanding most quickly.
End User:
Customer type determines contract structure, with aerospace manufacturers and medical device makers imposing multi-year qualification protocols that exclude spot-market suppliers.
- Aerospace Manufacturers:Boeing, Airbus, and their tier-one subcontractors demand AS9100 certification and statistical process control documentation. German and French supply chain consolidation favors producers with captive gas-atomization capacity.
- Electronics Producers:Samsung, Apple, and their contract manufacturers prioritize cycle time and cosmetic surface quality for visible components. Shenzhen and Seoul procurement desks compress supplier margins through competitive bidding.
- Machinery Fabricators:Industrial automation OEMs specify wear resistance and dimensional stability over cosmetic finish.
- Medical Device Makers:Stryker, Zimmer Biomet, and European implant specialists enforce FDA master file and EU MDR traceability requirements.
- Consumer Product Companies:Luxury goods and personal electronics brands emphasize plating adhesion and scratch resistance.
Medical device makers impose the steepest qualification burden; electronics producers generate the highest volume throughput.
Distribution Channel:
Supply concentration among Japanese and German master alloy producers shapes channel power, with direct relationships capturing premium grades and distributors handling commodity formulations.
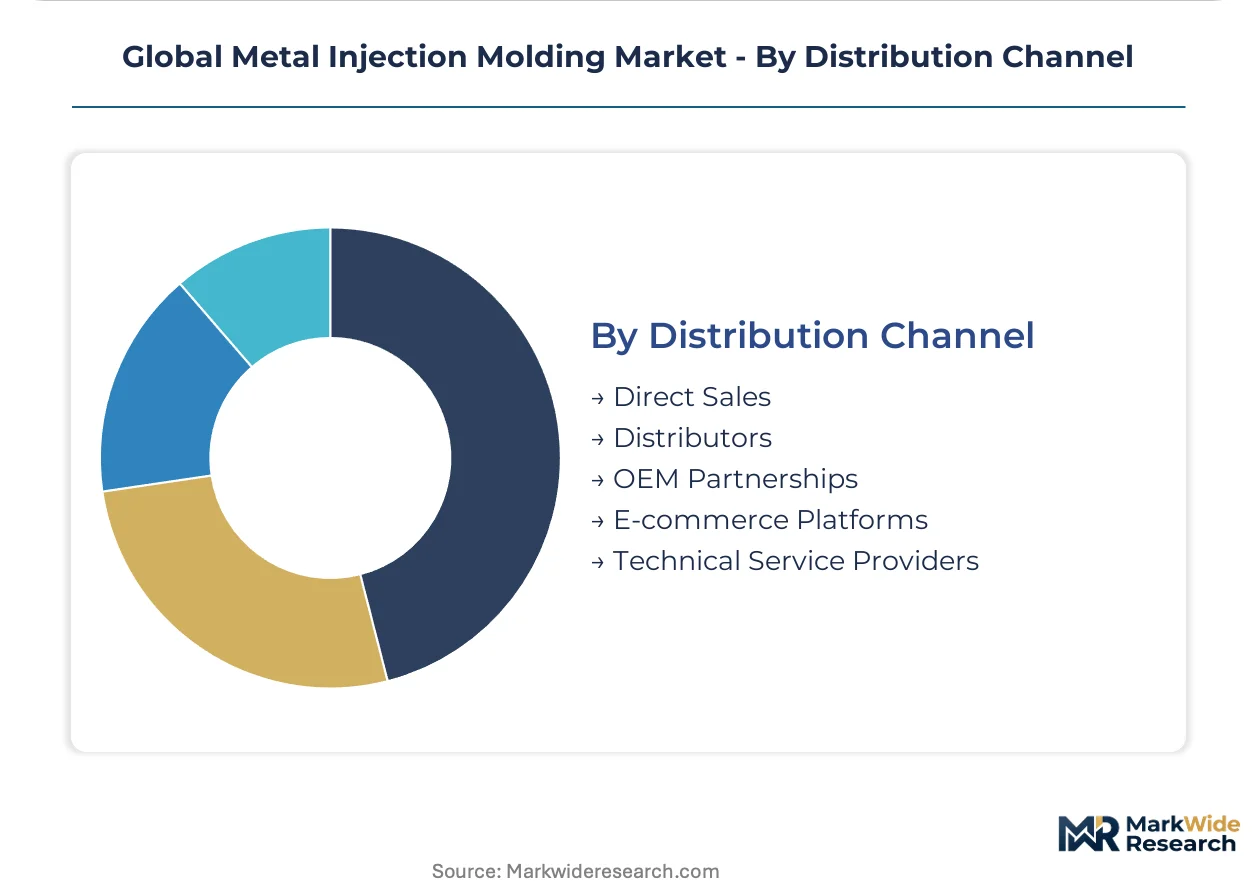
- Direct Sales:Long-term supply agreements dominate aerospace and medical procurement, embedding quality engineers at customer sites. Swiss and German specialists leverage direct relationships to defend margin against platform intermediaries.
- Distributors:Regional inventory buffers serve fragmented industrial machinery and consumer goods demand. Japanese trading houses and German industrial distributors anchor European and Asian spot purchasing.
- OEM Partnerships:Co-development contracts align MIM producers with customer design teams for application-specific alloy development.
- E-commerce Platforms:Xometry and similar aggregators commoditize prototype and low-volume production across North America.
- Technical Service Providers:Engineering consultancies bridge design-for-MIM expertise for customers transitioning from machined components.
Direct sales capture the highest value contracts; e-commerce platforms are gaining share fastest in prototyping and low-volume segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO regulatory harmonization and India's PLI scheme are redirecting medical device contract manufacturing toward Gujarat and Karnataka. REACH substance restrictions and EU MDR conformity pathways are compressing supplier qualification timelines across European precision clusters. EPA air-emission standards for thermal debinding are elevating capital intensity for US captive processing facilities.
United States
Boeing and Airbus tier-one contractors in Seattle anchor multi-year capacity reservations for flight-critical titanium brackets. EPA air-emission standards for thermal debinding processes are elevating compliance costs for captive furnace operators. Precision manufacturing clusters in Connecticut and California concentrate AS9100-certified producers serving aerospace OEM procurement desks.
Germany
Baden-Württemberg and Bavaria host concentrated aerospace and medical device supply chains demanding EU MDR conformity documentation. REACH substance restrictions on feedstock purity are accelerating supplier consolidation toward certified master alloy producers. Stuttgart-area fabricators are deploying multi-cavity tooling investments backed by multi-year automotive and aerospace contracts.
China
Shenzhen and Dongguan electronics OEMs drive volume for smartphone hinge mechanisms and miniaturized connectors. MEE air-emission requirements for thermal debinding are elevating capital intensity for captive processing facilities. Yangtze River Delta precision manufacturers are expanding titanium MIM capacity for export medical device markets.
Switzerland
Swissmedic-registered implant specialists in the Jura Arc enforce batch-level traceability obligations for spinal hardware feedstock. FDA material master file requirements are tightening genealogy documentation through atomization and blending stages. Geneva and Neuchâtel clusters leverage precision engineering heritage to dominate high-tolerance medical and aerospace contracts.
India
CDSCO regulatory harmonization and PLI scheme incentives are attracting contract manufacturers to establish titanium MIM capacity for export markets. BIS feedstock standards are aligning with ISO 22068 sintering protocols for medical device qualification. Gujarat and Karnataka industrial corridors are concentrating greenfield investments from European and US medical device suppliers.
Global Metal Injection Molding Market Competitive Landscape
On the supply side, the industry is bifurcating between vertically integrated powder-to-component specialists and asset-light platform intermediaries. Swiss and German precision engineering heritage anchors high-tolerance medical and aerospace contracts through direct customer relationships. Three archetypes dominate: captive gas-atomization producers with backward powder integration, regional job-shop aggregators leveraging digital quoting platforms, and medical-grade specialists with FDA dual-certification infrastructure. Competitive moves concentrate on multi-year capacity reservations replacing spot purchasing, and M&A activity targeting certified master alloy production capacity.
Among Swiss-registered precision specialists, Parmaco Metal Injection Molding AG exemplifies the heritage-engineering archetype serving medical and aerospace verticals. OptiMIM occupies a position within the titanium alloy processing tier, representing proprietary capabilities in biocompatible implant feedstock. Xometry anchors the platform-intermediary segment, aggregating fragmented North American and European job-shop capacity through digital quoting infrastructure.
| Leading Market Players |
|---|
| Mold-Masters |
| Takata Plastic |
| Parmaco Metal Injection Molding AG |
| San Technology, Inc. |
| Flex Ltd. |
| OptiMIM |
| KraussMaffei |
| Xometry |
| Hi-P International Ltd. |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's concentrated aerospace tooling investments anchor premium pricing power for AS9100-certified producers serving Boeing and Airbus tier-one contractors. REACH substance restrictions on gas-atomized powder purity compress supplier margins in Europe while elevating batch-traceability premiums for medical-grade titanium feedstock.
Pricing Analysis
Certification level creates the primary spread between commodity stainless steel components and FDA master file-qualified titanium implants. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-registered medical specialists from Asian electronics job shops and industrial machinery distributors. Cost compression in consumer-grade stainless steel runs through Shenzhen procurement desks demanding cycle-time concessions. Electronics OEMs exhibit the highest price sensitivity; medical device makers accept premium positioning for biocompatible surface finishes and lot-level genealogy documentation.
Supply Chain Analysis
Extended payment terms from Japanese and German master alloy producers strain working capital for North American contract manufacturers lacking supply-chain finance facilities. Gas-atomized titanium powder production concentrates in Japan, Germany, and the United States, drawing from sponge feedstock vulnerable to freight volatility and currency fluctuation. Single-source vulnerability threatens buyers dependent on premium powder grades qualified for spinal implant applications. Distribution runs through direct sales relationships for aerospace and medical contracts, with platform intermediaries handling prototype and low-volume spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized debinding process engineering expertise remains scarcer than conventional powder metallurgy skill pools, compressing expansion timelines for producers seeking FDA dual certification. This capability gap rewards early investment in simulation-enabled talent development and captive furnace-hour accumulation.
For Market Incumbents: Build regulatory certification moats by securing simultaneous FDA material master file and EU MDR conformity documentation before competitors complete qualification cycles. Add captive gas-atomization capacity in Germany or Switzerland to defend margin against powder supply concentration. Consolidate multi-year capacity reservations from Boeing and Airbus tier-one contractors to lock out uncertified job shops from flight-critical titanium bracket procurement.
For New Entrants and Emerging Players: Indian medical device manufacturing in Gujarat and Karnataka represents the most penetrable entry point given CDSCO regulatory harmonization and PLI scheme incentives for export-focused titanium MIM capacity. Carbon-border adjustment mechanism readiness in European markets offers differentiation for producers with renewable thermal debinding energy sourcing. Partner with established Swiss or German engineering consultancies to bridge design-for-MIM expertise gaps without legacy furnace-hour accumulation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated powder-to-component specialists with demonstrated dual-certification infrastructure over asset-light platform intermediaries. Long-term viability hinges on backward integration into gas-atomization capacity and multi-physics sintering simulation deployment. Watch for ISO 22068 sintering standard alignment completion as an inflection signal separating qualified producers from certification-lagged competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gas-Atomization Capacity | Backward powder integration insulates Parmaco and OptiMIM from Japanese supplier freight volatility. |
| Multi-Physics Sintering Simulation Deployment | Virtual furnace parameter development halves first-article qualification timelines for Swiss medical contract manufacturers. |
| FDA-EASA Dual Certification Investment | Simaneous FDA master file and EASA approval unlocks multi-year aerospace capacity reservations from tier-one contractors. |
| Digital Quoting Platform Expansion | Xometry's aggregation of fragmented North American job-shop capacity captures margin from price-transparent spot purchasing. |
| Renewable Thermal Debinding Energy Sourcing | EU CBAM implementation creates first-mover advantage for European producers with green furnace operations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with MIM process engineers, aerospace procurement managers, medical device regulatory affairs leads, and gas-atomization plant managers; and secondary validation against FDA material master file submissions, ECHA REACH substance restriction updates, EPA air-emission enforcement records, and ISO 22068 sintering standard development documentation. Bottom-up capacity assessments across Baden-Württemberg, Connecticut, and Shenzhen precision clusters were triangulated with top-down aerospace and medical device demand modeling.
Forecast inputs incorporated material-grade segmentation across stainless steel, titanium, copper, nickel, and tool steel formulations; application-level modeling for aerospace brackets, electronic connectors, and implantable hardware; and end-user contract structures distinguishing multi-year capacity reservations from spot purchasing. CAGRs were derived through geometric progression analysis of powder consumption volumes and component value per kilogram trends across the projection horizon. Regulatory pathway timelines and carbon-border adjustment implementation schedules fed scenario-weighted outputs.
Practitioners should monitor EPA and MEE thermal debinding enforcement intensity, EU MDR conformity assessment backlog duration, and gas-atomized powder freight rate volatility for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Quartz Kitchen Countertops Market
Advanced Alloys
Precipitation Hardening Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Metal Replacement Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Asia-Pacific Metal Casting Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Europe Aluminum Casting Market