
 Soft Magnetic Material for Electric Vehicle Market | 2026-2036
Soft Magnetic Material for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Magnetic Material for Electric Vehicle Market Insights
The capital-intensity divergence between integrated steelmakers and specialty alloy producers is reorganizing competitive tiers in soft magnetic supply. Proterial Ltd. leverages its integrated ferrite-to-core manufacturing chain to control cost positions in high-frequency applications. VACUUMSCHMELZE GmbH & Co. KG anchors European supply through its amorphous and nanocrystalline strip casting operations. Nippon Steel sustains volume leadership in oriented silicon steel for traction motor laminations.
Soft magnetic material for electric vehicle comprises alloys engineered for low coercivity and high magnetic permeability, typically silicon-iron compositions with 1-4.5% Si content or cobalt-based amorphous ribbons processed by rapid solidification, enabling efficient flux reversal at frequencies up to hundreds of kilohertz in onboard power electronics. Silicon steel sheets dominate motor laminations due to established stamping infrastructure and cost scaling, while nanocrystalline cores capture expanding share in DC-DC converters and onboard chargers where core loss minimization justifies premium positioning. Amorphous steel competes selectively in high-frequency inductor applications despite processing constraints on winding and annealing.
The EU Green Deal and F-Gas Regulation shape material selection by penalizing energy losses in power conversion stages, while China's MIIT enforces dual carbon goals through motor efficiency mandates that elevate grade requirements for electrical steel. The US EPA and NHTSA coordinate tailpipe and upstream efficiency standards that indirectly pressure OEMs to optimize every watt of traction and auxiliary power loss. Stakeholders must track how regional carbon-border adjustments recalibrate the cost advantage between domestically produced silicon steel and imported specialty alloys.
Market Dynamics
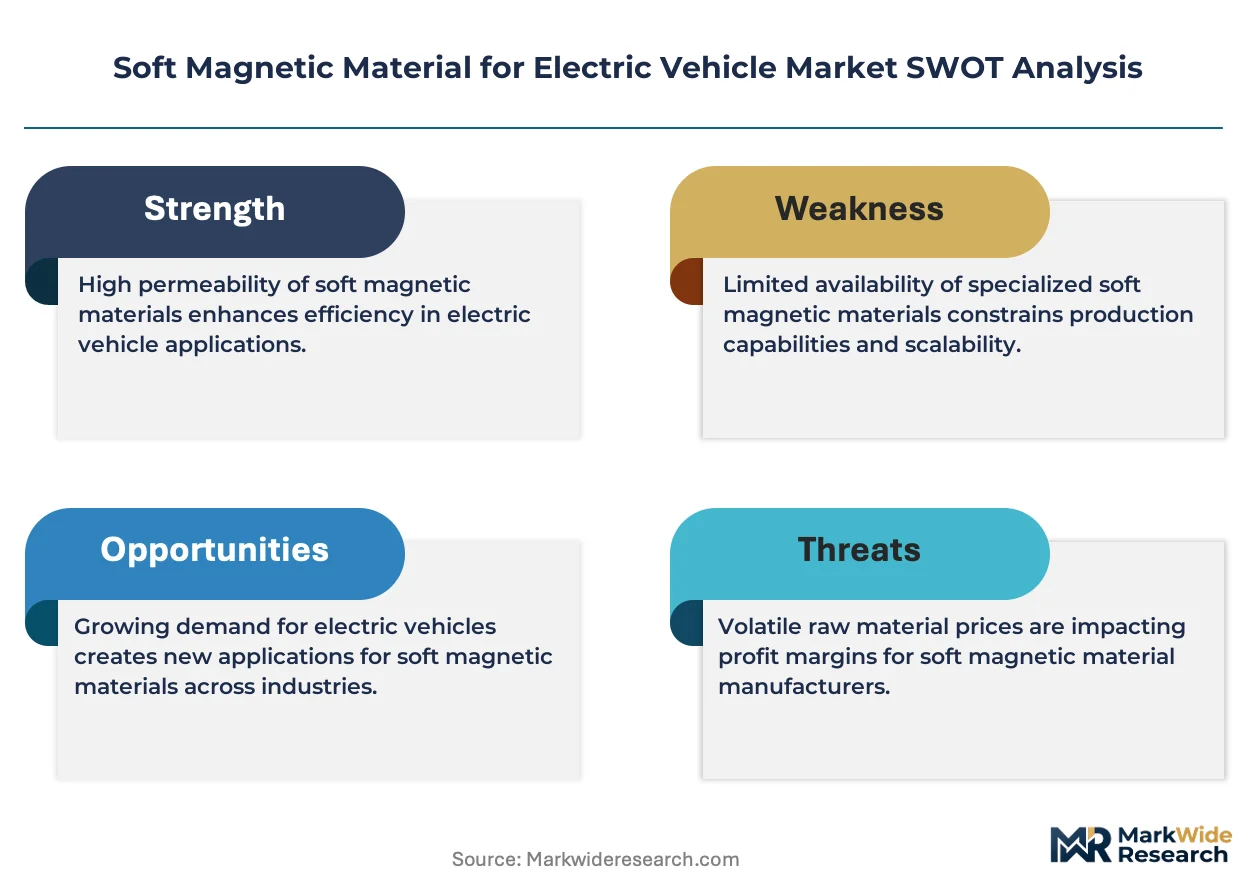
China's MIIT dual carbon goals and the EU Green Deal are tightening loss-factor requirements for magnetic components, forcing traction motor manufacturers to scale procurement of nanocrystalline cores to meet efficiency benchmarks while reorganizing supplier relationships around Stuttgart and Munich.
Growth Catalysts
- MIIT dual carbon goals:China's motor efficiency mandates elevate grade requirements for electrical steel, pulling demand toward higher-silicon laminations and rapid-solidification alloys in domestic EV production.
- EU F-Gas Regulation:Penalties on energy losses in power conversion stages accelerate replacement of conventional ferrite cores with nanocrystalline alternatives in onboard chargers and DC-DC converters.
- Stuttgart-Munich supplier belt concentration:Germany's automotive engineering cluster creates dense demand pull for amorphous strip casting capacity serving tier-1 motor and inverter manufacturers.
Market Restraints
- Cobalt and nickel price volatility:Rapid-solidification alloys depend on cobalt-based compositions, exposing specialty core producers to raw material cost swings that compress margin stability.
- Amorphous steel processing constraints:Winding brittleness and precise annealing requirements limit fabrication scalability, constraining deployment in high-frequency inductor applications despite loss advantages.
- Silicon steel stamping infrastructure lock-in:Established motor lamination supply chains resist material switching due to sunk capital in oriented silicon steel stamping dies and quality certification.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for advanced chemistry cell and EV component manufacturing create import-substitution openings for electrical steel and soft magnetic alloy producers.
- 800V architecture proliferation:Higher-voltage traction systems demand magnetic materials optimized for elevated switching frequencies, expanding addressable market for nanocrystalline and amorphous core suppliers.
- EU carbon border adjustment mechanism:Embodied carbon tariffs on imported electrical steel recalibrate cost structures, favoring European amorphous and nanocrystalline strip casting capacity over Asian silicon steel imports.
Industry Challenges
- Rapid-solidification metallurgy expertise scarcity:Strip casting of amorphous and nanocrystalline alloys requires specialized thermal processing knowledge that concentrates in a limited pool of process engineers.
- Core loss certification timeline compression:OEMs demand validated loss-factor data under IEC 60404-6 test conditions within compressed product development cycles, straining laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Magnetic Material for Electric Vehicle Market |
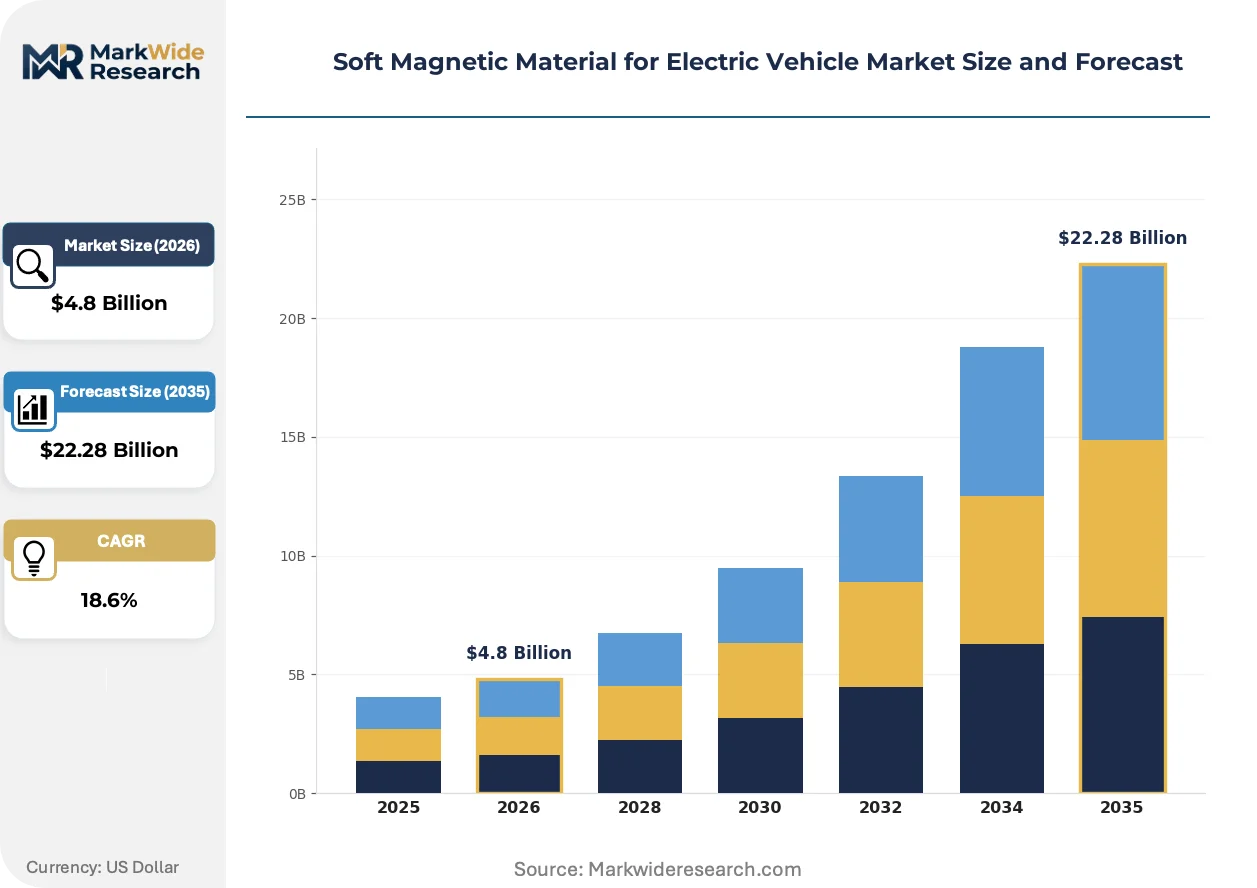
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Ferrite, Amorphous Steel, Nanocrystalline, Silicon Steel Component: Transformers, Inductors, Motors, Sensors Form: Sheets, Cores, Wires, Powders End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Proterial Ltd., TDK Corporation, JFE Steel Corporation, VACUUMSCHMELZE GmbH & Co. KG, Daido Steel Co., Nippon Steel, POSCO, Standex Electronics, Arnold Magnetic Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Magnetic Material for Electric Vehicle Market Trends and Innovations
Nanocrystalline ribbon technology is actively decomposing the traditional segmentation between motor laminations and power electronics cores, creating unified material specifications that span traction and auxiliary systems.
Nanocrystalline alloys based on iron-copper-niobium-silicon-boron compositions deliver core loss performance an order of magnitude below conventional ferrites at frequencies above 50 kHz. Tier-1 inverter manufacturers in Germany and Japan are qualifying these materials for 800V onboard chargers and DC-DC converters. This adoption is decomposing the historical separation between laminated motor steels and powder cores, enabling single-supplier strategies for magnetic components.
The EU F-Gas Regulation and embedded energy efficiency standards are tightening permissible core losses in power conversion stages, directly elevating material grade specifications. Manufacturers must now document losses under standardized temperature and frequency conditions. High-frequency inductor applications in onboard chargers face the most stringent compliance pressure, driving substitution toward cobalt-based amorphous ribbons.
Consolidated procurement by platform-focused OEMs is compressing supplier qualification timelines and collapsing the traditional tier-2 distributor layer. Tier-1 motor and inverter manufacturers now source magnetic cores through direct mill relationships, bypassing steel service centers. This channel restructuring is most advanced in Germany's automotive supplier belt, where integrated steelmakers and specialty alloy producers compete for sole-source positions on EV platform contracts.
Soft Magnetic Material for Electric Vehicle Market Segmentation
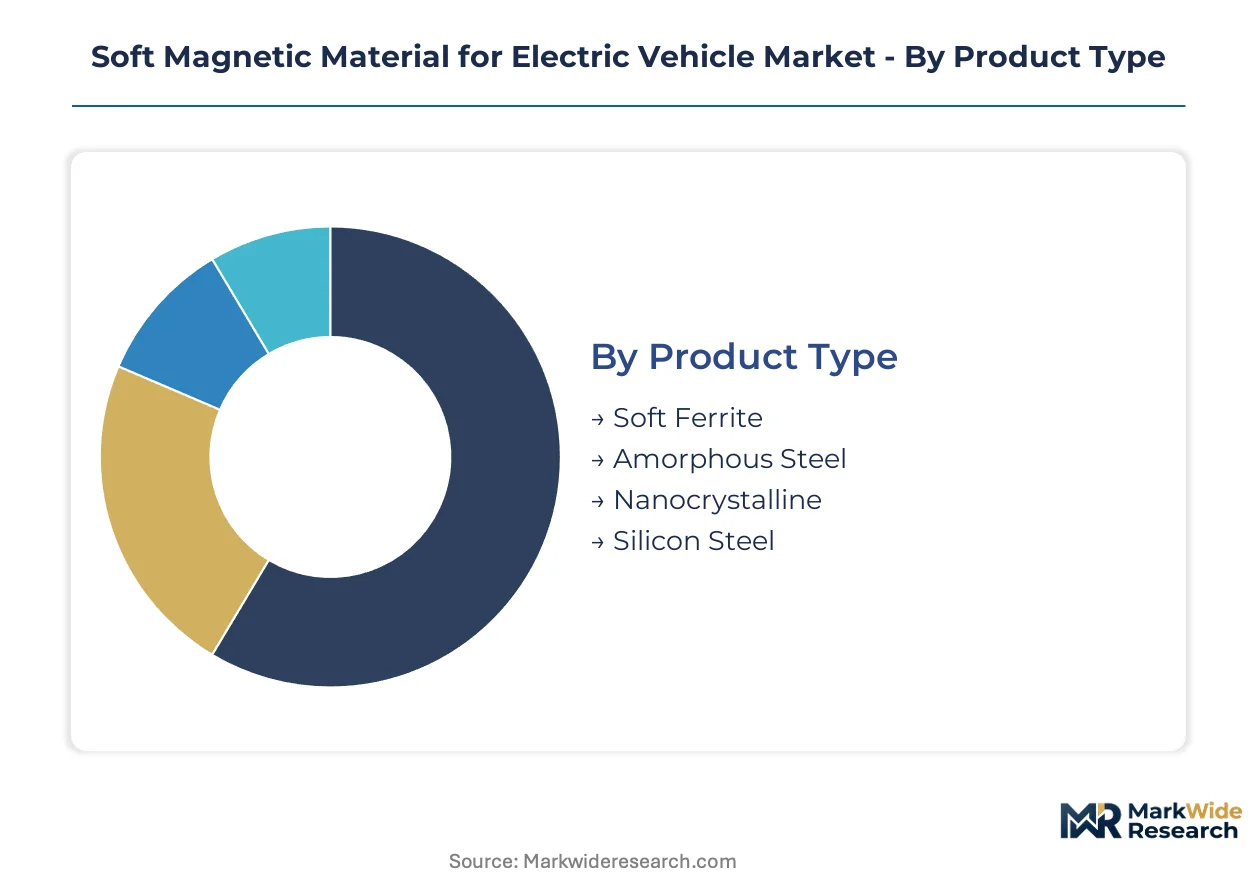
Material selection in electric vehicle magnetic systems splits across performance tiers, manufacturing constraints, and supply chain integration levels. Procurement patterns diverge sharply between high-volume motor laminations and precision-wound power electronics cores.
Product Type:
Domestic production clusters in China and Japan supply silicon steel and soft ferrite to regional EV manufacturers, while nanocrystalline and amorphous alloys flow through specialized export channels serving European and North American tier-1 suppliers.
- Silicon Steel:Oriented silicon-iron alloys with 2-4.5% Si content deliver the flux density and mechanical strength required for traction motor laminations. Demand concentrates in China's Yangtze River Delta EV manufacturing corridor, where MIIT motor efficiency mandates elevate grade specifications above conventional 35W300 grades.
- Nanocrystalline:Iron-copper-niobium-silicon-boron ribbons processed by rapid solidification achieve core losses an order of magnitude below ferrites above 50 kHz. German tier-1 inverter manufacturers in the Stuttgart-Munich belt are qualifying these materials for 800V onboard chargers and DC-DC converters.
- Soft Ferrite:Manganese-zinc and nickel-zinc ceramic compositions serve cost-sensitive inductor applications below 100 kHz, with Chinese producers dominating volume supply.
- Amorphous Steel:Cobalt-based and iron-based metallic glasses compete in high-frequency transformer applications despite winding brittleness and precise annealing requirements.
Silicon steel commands the established base. The steepest expansion runs through nanocrystalline alloys.
Component:
Cost tier separation distinguishes commodity motor laminations from premium-priced inductor cores engineered for switching frequencies above 20 kHz.
- Motors:Traction motor laminations consume the highest tonnage of soft magnetic material, with stamped silicon steel stacks comprising 60-70% of motor core mass. Japanese and Chinese steelmakers supply oriented electrical steel to EV motor plants in Shanghai, Tianjin, and Aichi Prefecture.
- Inductors:DC-DC converter and onboard charger inductors demand low-loss materials at 50-200 kHz switching frequencies. VACUUMSCHMELZE and Proterial supply nanocrystalline and amorphous cores to European and Japanese tier-1 power electronics manufacturers.
- Transformers:Galvanic isolation transformers in charging infrastructure use grain-oriented silicon steel or amorphous ribbons depending on efficiency targets.
- Sensors:Position and current sensors employ high-permeability nickel-iron alloys or specialized ferrite geometries for signal integrity.
Motor applications anchor volume demand. Inductor applications generate the fastest margin expansion.
Form:
Supply concentration varies by processing complexity, with sheet stamping infrastructure locked into established automotive supply chains while core winding and powder compaction retain specialist manufacturing.
- Sheets:Grain-oriented silicon steel in 0.2-0.35mm thicknesses feeds high-speed stamping presses at motor lamination plants. Nippon Steel and Baowu Steel supply mills in Japan, China, and through export to European stampers.
- Cores:Toroidal and C-cores wound from nanocrystalline ribbon or cut from ferrite blocks serve inductor and transformer manufacturers. Proterial's integrated ferrite-to-core chain controls cost positions in high-frequency applications.
- Wires:Fine-gauge magnetic wire for sensor windings and specialized inductor applications.
- Powders:Iron-silicon and iron-nickel powder cores for distributed gap inductors in power conversion stages.
Sheet form dominates tonnage shipments. Core form captures value concentration in power electronics.
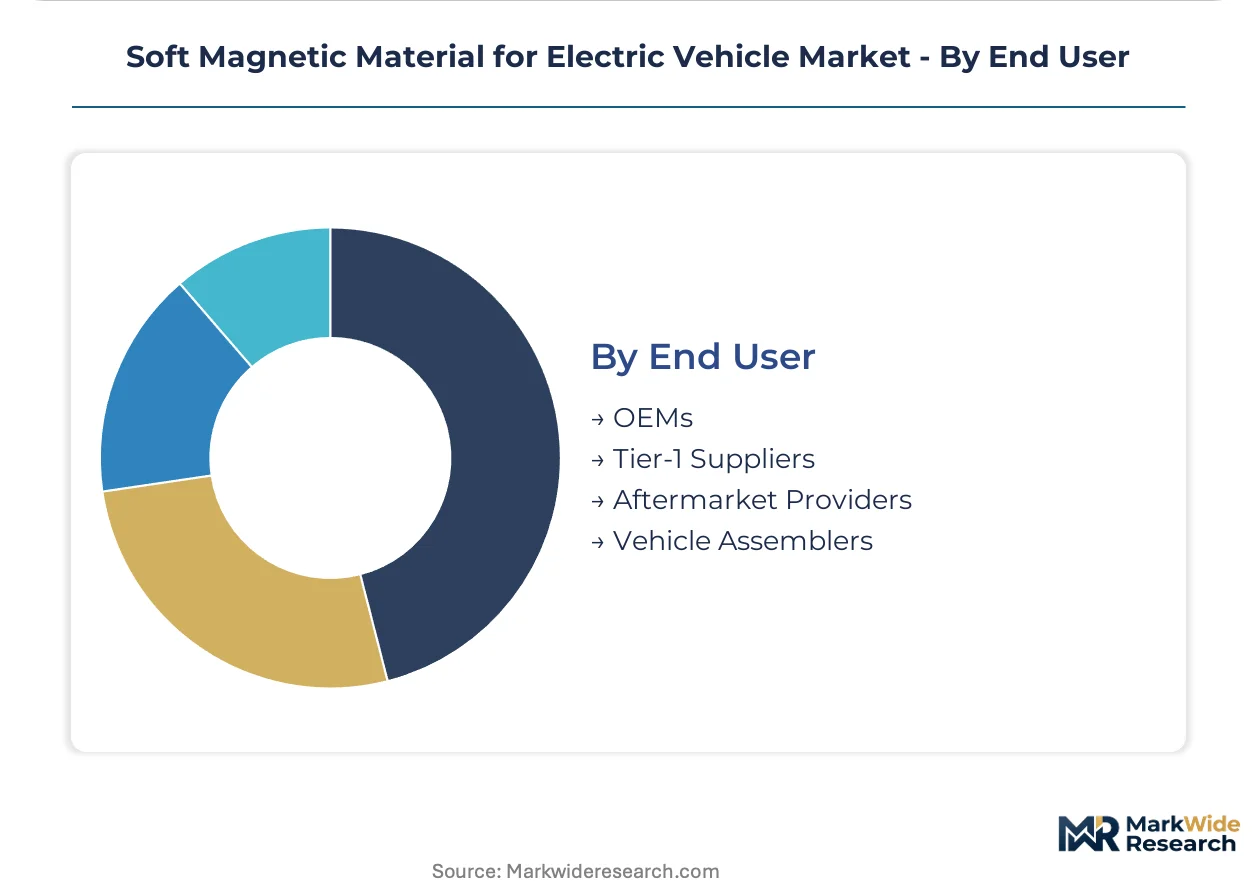
End User:
Customer type determines procurement channel structure, with platform-focused OEMs collapsing traditional distributor layers in favor of direct mill relationships.
- Tier-1 Suppliers:Bosch, Denso, and Continental source magnetic cores through direct contracts with specialty alloy producers, bypassing steel service centers. These suppliers consolidate procurement for multiple OEM platforms, compressing qualification timelines.
- OEMs:Tesla, BYD, and Volkswagen Group negotiate directly with electrical steel mills for high-volume motor lamination supply, securing grade specifications and carbon-footprint documentation for EU Green Deal compliance.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities receive specified materials through OEM-directed supply agreements.
- Aftermarket Providers:Independent repair and remanufacturing channels source replacement motors and power electronics through secondary distributors.
Tier-1 suppliers concentrate procurement leverage. OEM direct sourcing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German nanocrystalline strip casting while Chinese silicon steel mills compete on scale. This asymmetry reshapes procurement geography across EV supply chains.
China
MIIT dual carbon goals enforce motor efficiency mandates that elevate electrical steel grades above 35W300 specifications. Domestic mills in the Yangtze River Delta supply oriented silicon-iron laminations to Shanghai and Tianjin EV plants. Baowu Steel anchors volume production for BYD and CATL-directed motor manufacturers.
Germany
The Stuttgart-Munich supplier belt generates dense demand for amorphous and nanocrystalline cores serving Bosch and Continental inverter programs. EU F-Gas Regulation penalties on conversion losses accelerate material substitution in onboard chargers. VACUUMSCHMELZE strip casting operations in Hanau supply tier-1 qualifications for 800V architectures.
United States
EPA-NHTSA coordinated efficiency standards pressure OEMs to minimize traction and auxiliary power losses. Domestic motor lamination stampers in Michigan and Ohio source electrical steel through Nippon Steel export channels. Tesla negotiates directly with mills for carbon-footprint documentation supporting IRA compliance.
Japan
METI efficiency roadmaps align with automaker electrification timelines in Aichi Prefecture. JFE Steel and Nippon Steel sustain oriented silicon steel leadership for Denso and Aisin motor programs. Nanocrystalline core development in Chubu region targets next-generation DC-DC converter specifications.
India
PLI scheme incentives for advanced chemistry cell and EV component manufacturing create import-substitution openings. Domestic electrical steel capacity expansion in Gujarat and Maharashtra addresses motor lamination demand from Tata Motors and Mahindra Electric. BIS certification timelines compress as OEMs localize supply chains.
Soft Magnetic Material for Electric Vehicle Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated steelmakers dominate high-volume silicon steel laminations through scale economies in strip casting and rolling. Specialty alloy producers capture premium positioning in rapid-solidification ribbons for power electronics. Competitive moves concentrate on backward integration into raw material refining and sole-source platform contracts with tier-1 suppliers.
Among Japanese and German specialists, VACUUMSCHMELZE GmbH & Co. KG and Proterial Ltd. exemplify the integrated alloy-to-core archetype. Nippon Steel occupies a position representing scale-driven electrical steel supply. These anchors demonstrate how geographic proximity to automotive engineering clusters confers qualification advantages.
| Leading Market Players |
|---|
| Proterial Ltd. |
| TDK Corporation |
| JFE Steel Corporation |
| VACUUMSCHMELZE GmbH & Co. KG |
| Daido Steel Co. |
| Nippon Steel |
| POSCO |
| Standex Electronics |
| Arnold Magnetic Technologies |
| Others |
Pricing and Supply Chain Analysis
Strip casting capacity utilization above 85% in German and Japanese nanocrystalline operations creates asymmetric scale effects that elevate price floors for rapid-solidification alloys while compressing margins in Chinese silicon steel. This divergence concentrates supply-side bargaining power with specialty alloy producers serving 800V architectures, forcing tier-1 inverter manufacturers to accept configured-to-order premiums or risk qualification delays.
Pricing Analysis
Configured-to-order premiums for nanocrystalline cores command spreads of 40-60% above standard silicon steel laminations, driven by IEC 60404-6 certification tiers and cobalt-based composition grades. Three-tier pricing structure across premium, standard, and economy levels separates sole-source platform contracts from multi-source motor lamination supply. Pricing pressure stems from MIIT efficiency mandates accelerating grade substitution in China's Yangtze River Delta. Tier-1 suppliers exhibit lowest price sensitivity due to platform consolidation timelines, while aftermarket providers face acute cost compression.
Supply Chain Analysis
Just-in-time inventory strategies dominate silicon steel procurement for high-volume motor stampers, whereas strategic stockpiling of cobalt and niobium feedstock secures nanocrystalline ribbon output for German tier-1 qualifications. Supply concentrates in China, Japan, and Germany, with strip casting operations drawing from cobalt, silicon, and rare earth element inputs. Single-source vulnerability in rapid-solidification metallurgy expertise concentrates risk around Hanau and Chubu region facilities. Distribution runs through direct mill relationships that disintermediate steel service centers for platform-focused OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soft magnetic material for electric vehicle sits in early-cycle expansion as 800V architecture proliferation pulls nanocrystalline alloys from niche power electronics into mainstream traction applications. Penetration tailwinds from EU F-Gas Regulation compliance timelines compress supplier qualification windows, favoring pre-qualified incumbents.
For Market Incumbents: Consolidate sole-source positions on EV platform contracts by anchoring strip casting capacity in Germany's automotive supplier belt and securing backward integration into cobalt refining. Amorphous steel processing constraints and rapid-solidification expertise scarcity create defensive moats against emerging Asian entrants. Priority investment in IEC 60404-6 laboratory capacity accelerates loss-factor certification timelines that OEMs now compress. For New Entrants and Emerging Players: Technical service gaps in core loss measurement and thermal modeling support represent underserved white space where incumbents under-serve mid-tier inverter manufacturers. India's PLI scheme for automotive components offers the most penetrable geography, with BIS certification timelines creating first-mover windows for domestic electrical steel capacity. Go-to-market execution through joint qualification programs with Gujarat-based motor lamination stampers bypasses entrenched mill-direct channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated alloy-to-core specialists with captive strip casting and winding operations, as platform standardization locks in multi-year offtake agreements. Long-term viability centers on exposure to 800V and solid-state battery architectures that elevate switching frequency requirements. Acquisition targets should display rapid-solidification process IP and existing tier-1 qualifications. The signal to watch is carbon-border adjustment mechanism implementation timing, which recalibrates cost structures between European amorphous capacity and Asian silicon steel imports.| Strategic Initiative | Industry Significance |
|---|---|
| Strip Casting Capacity Expansion | VACUUMSCHMELZE and Proterial operations in Hanau anchor European nanocrystalline supply for 800V inverter programs. |
| Backward Integration into Cobalt Refining | Captive supply of cobalt-based amorphous ribbon feedstock insulates margin stability against raw material volatility. |
| IEC 60404-6 Laboratory Investment | Core loss certification capacity under standardized temperature and frequency conditions compresses OEM qualification timelines. |
| Platform Sole-Source Contracting | Direct mill relationships with Bosch and Continental collapse distributor layers and lock in multi-year volume commitments. |
| India PLI Scheme Localization | Domestic electrical steel capacity in Gujarat addresses Tata Motors and Mahindra Electric motor lamination demand. |
Research Methodology
Desk research of customs/trade data, SEC 10-K filings, and MIIT efficiency mandate documentation preceded structured interviews with tier-1 supplier procurement directors, OEM platform engineers, rapid-solidification metallurgists, and electrical steel mill technical sales leads. Primary fieldwork combined with secondary validation from IHS Markit vehicle production databases and IEA critical mineral supply reports. Bottom-up segment sizing triangulated against top-down market value estimates across material type, component application, and regional production cluster dimensions.
Variance decomposition isolates volume, price, and mix effects across the projection horizon. Segmentation dimensions modeled include material grade tier, switching frequency requirement, propulsion architecture, and regional regulatory framework. CAGRs derive from elasticity-adjusted adoption curves for 800V systems and carbon-border adjustment mechanism phase-in assumptions. Industry-specific forecast inputs incorporate MIIT motor efficiency mandate compliance timelines and EU F-Gas Regulation penalty structures.
Underlying assumptions cover sustained cobalt price volatility within historical bands and tier-1 supplier consolidation trajectories, with deviation risk concentrated in amorphous steel processing yield improvements and solid-state battery commercialization timing. Revision becomes warranted when carbon-border adjustment mechanism rates or rare earth element export restrictions cross thresholds that alter regional cost competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Forgings Market
Advanced Alloys
Nitinol Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Precipitation Hardening Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market