
 Europe Green Steel Market | 2026-2036
Europe Green Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Green Steel Market Analytics
Scrap-based steel is decoupling from virgin ore dependence as hydrogen direct reduction reaches cost parity in select European corridors. Salzgitter AG leverages its SALCOS program to anchor low-carbon flat steel output in northern Germany. Voestalpine AG sustains Austrian hub operations through integrated electric arc furnace capacity and renewable power sourcing. ArcelorMittal competes across multiple technology pathways, spanning hydrogen-based direct reduced iron and carbon capture retrofits at Belgian and Spanish sites.
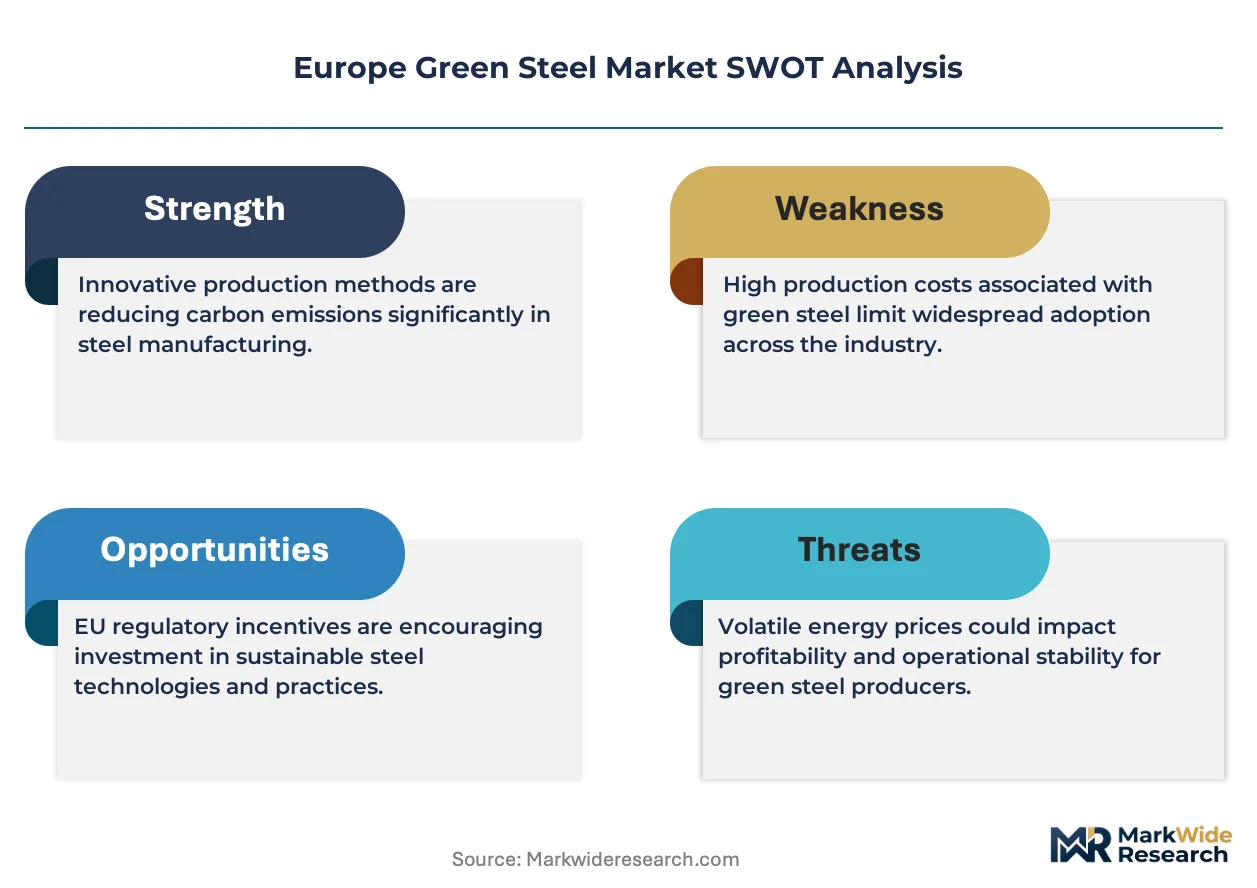
Europe green steel denotes iron and steel products manufactured with substantially reduced carbon dioxide intensity, typically below one tonne CO2 per tonne of crude steel equivalent, achieved through hydrogen reduction, biomass injection, electrolytic ironmaking, or high scrap ratios in electric arc furnaces. The primary purpose is to supply construction, automotive, and renewable energy infrastructure sectors with certifiable low-emission metal that meets EU Green Deal procurement standards and customer Scope 3 reduction targets. Hydrogen-based steel captures premium positioning as offtake agreements from automotive OEMs concentrate around this pathway. Electric arc furnace operations dominate installed capacity but face scrap availability constraints that limit margin expansion in certain geographies. Carbon capture retrofits on existing oxygen furnace assets represent a transitional segment where project economics remain sensitive to carbon price levels and storage infrastructure development.
The EU Green Deal, CBAM, and ETS frameworks collectively reshape demand by embedding carbon costs into import parity and domestic production decisions. ECHA chemical safety protocols and REACH compliance requirements influence hydrogen supply chain certification and refractory material selection for new plants. Stakeholders must monitor offtake contract structures, hydrogen pipeline buildout timelines, and national subsidy allocation mechanisms as determinants of project sequencing and regional competitive advantage.
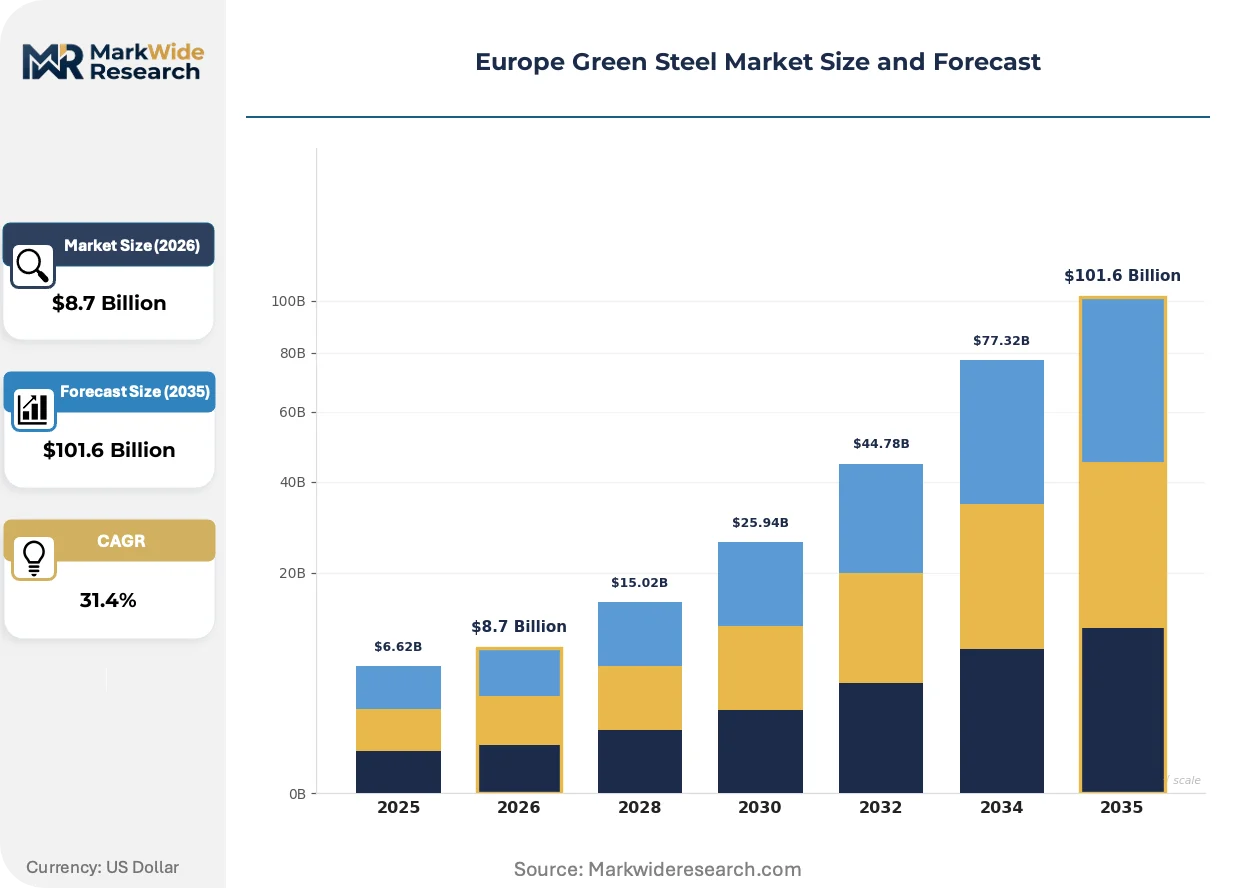
Market Dynamics
The EU Carbon Border Adjustment Mechanism is forcing a rapid recalibration of steel procurement economics, embedding carbon costs into import parity calculations and accelerating domestic green capacity investments.
Growth Catalysts
- EU Green Deal procurement standards:Public infrastructure tenders now mandate certifiable low-emission steel, creating guaranteed offtake volumes for hydrogen-based production routes.
- Automotive OEM Scope 3 targets:Vehicle manufacturers face binding emissions reduction commitments that require green steel in body panels and chassis components.
- Ruhr industrial cluster concentration:Proximity of steel plants to planned hydrogen pipeline networks and offshore wind generation reduces logistics costs for green hydrogen feedstock.
Market Restraints
- Green hydrogen cost volatility:Electrolyzer capacity buildout lags behind steel plant conversion timelines, creating input price uncertainty for direct reduction facilities.
- Scrap availability constraints:Electric arc furnace operators face feedstock competition from Turkish and Asian buyers, limiting margin expansion in southern European markets.
- Carbon capture storage infrastructure gaps:Transitional oxygen furnace retrofits depend on unbuilt CO2 pipeline networks and North Sea sequestration sites.
Strategic Opportunities
- Polish steel corridor development:Baltic hydrogen import terminals and underutilized blast furnace assets create conversion potential for low-carbon flat steel serving Central European automotive plants.
- Offshore wind tower demand:Renewable energy infrastructure requires certifiable low-emission steel for monopile foundations and transition pieces.
- CSRD supply chain disclosure:Corporate sustainability reporting mandates force mid-tier manufacturers to source traceable green steel, expanding addressable market beyond lead customers.
Industry Challenges
- Hydrogen metallurgy skill scarcity:Direct reduction plant operations require process engineers trained in gas-based reduction chemistry, a competency concentrated in limited industrial regions.
- Certification timeline compression:Third-party verification of sub-one-tonne CO2 intensity claims faces bottlenecks as audit capacity strains against project commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Green Steel Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogen-Based Steel, Biomass-Reduced Steel, Electrolytic Steel, Scrap-Based Steel End User: Construction, Automotive, Aerospace, Industrial Equipment Technology: Direct Reduced Iron, Electric Arc Furnace, Oxygen Furnace, Carbon Capture Application: Structural Beams, Vehicle Components, Machinery Parts, Renewable Energy Infrastructure |
| Companies Covered | Salzgitter AG, Voestalpine AG, ArcelorMittal, Tata Steel, Outokumpu, H2 Green Steel, SSAB AB, SSAB, Thyssenkrupp Steel, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Green Steel Market Evolving Landscape
Technology maturation and regulatory stringency are compressing the transition timeline for European steel decarbonization, with production methods and procurement patterns evolving in parallel.
Hydrogen-based direct reduction is consolidating as the dominant commercial pathway for virgin steel decarbonization. Automotive OEMs concentrate offtake agreements around this technology, prioritizing supply security over marginal cost premiums. The structural consequence is compressing investment timelines for competing carbon capture and biomass injection routes.
REACH compliance protocols are reshaping hydrogen supply chain certification requirements. ECHA chemical safety mandates now extend to electrolyzer membrane materials and storage vessel coatings, adding qualification layers to equipment procurement. Northern European project developers are responding by integrating refractory specifications earlier in engineering phases.
Long-term offtake contracting is displacing spot market purchasing for low-emission steel grades. Construction and renewable energy developers now seek five-to-ten-year supply agreements with fixed carbon intensity clauses, compressing traditional merchant sales channels. Germany and the Netherlands exhibit the most advanced contract standardization, with template agreements circulating among major project financiers.
Europe Green Steel Market Segmentation
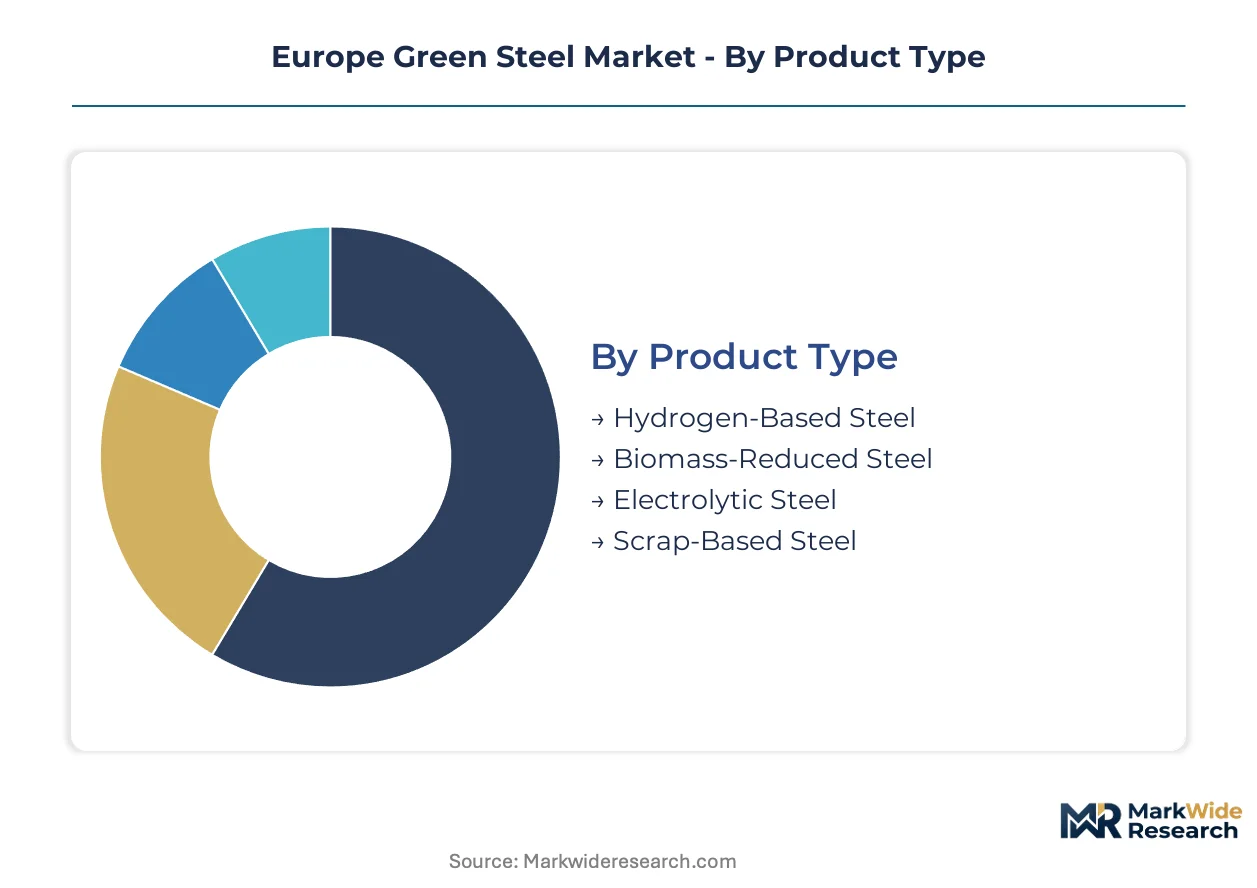
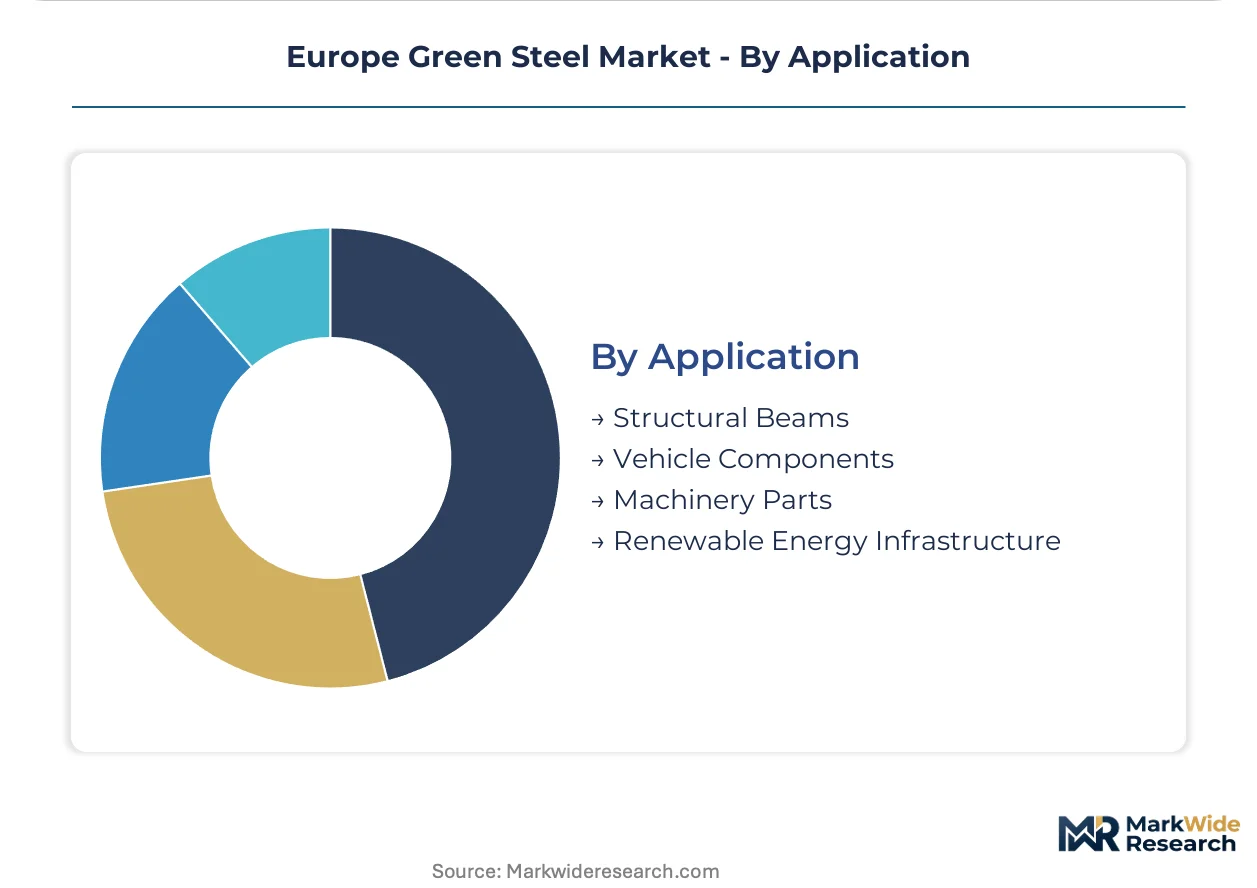
Segmentation in the Europe Green Steel Market reveals how procurement decisions split across technology maturity, carbon intensity certification, and end-use performance requirements. Buyers weigh hydrogen pathway premiums against scrap-based availability and renewable energy infrastructure deadlines.
Product Type:
Procurement teams prioritize carbon intensity thresholds over upfront capital costs when selecting production pathways.
- Hydrogen-Based Steel:Direct reduction using green hydrogen yields sub-one-tonne CO2 intensity per tonne of crude steel. German automotive OEMs anchor offtake agreements around this pathway, accepting 15-25% cost premiums for Scope 3 compliance certainty.
- Scrap-Based Steel:Electric arc furnace processing of ferrous scrap achieves the lowest embodied carbon among commercial options. Turkish export competition for shredded scrap limits margin expansion for southern European operators, particularly in Italy and Spain.
- Biomass-Reduced Steel:Charcoal injection into blast furnaces displaces metallurgical coal in select Nordic operations. SSAB's Oxelösund trials demonstrate technical feasibility at pilot scale.
- Electrolytic Steel:Molten oxide electrolysis remains pre-commercial, with Alcoa-ELYSIS partnership targeting aluminum-sector technology transfer. Energy intensity requirements constrain near-term deployment.
Hydrogen-based steel leads on scale; electrolytic steel leads on momentum.
End User:
Customer carbon disclosure obligations create divergent urgency timelines across industrial sectors.
- Automotive:EU fleet emission regulations and OEM Scope 3 targets mandate low-emission steel for body-in-white applications. Volkswagen, BMW, and Mercedes-Benz have executed multi-year offtake contracts with northern German producers.
- Construction:EU Green Deal procurement standards for public infrastructure projects now require Environmental Product Declaration verification. French and Dutch civil engineering tenders specify maximum 500kg CO2 per tonne reinforcement bar.
- Renewable Energy Infrastructure:Offshore wind monopile and transition piece fabricators face project finance conditions tied to embodied carbon limits. Danish and German North Sea developments drive demand for heavy plate with certified low-emission credentials.
- Industrial Equipment:Capital goods manufacturers adopt green steel selectively, prioritizing export-facing product lines subject to CBAM compliance pressures.
- Aerospace:Stringent metallurgical specifications for high-strength alloys limit current green steel penetration to non-structural components.
Automotive commands procurement volume; renewable energy infrastructure expands most quickly.
Technology:
Asset conversion economics hinge on residual blast furnace lifecycles and hydrogen pipeline proximity.
- Direct Reduced Iron:Hydrogen-based DRI plants anchor newbuild green steel capacity in the Netherlands, Germany, and Sweden. Voestalpine's Linz facility and ArcelorMittal's Dunkirk project exemplify this technology commitment.
- Electric Arc Furnace:Scrap-fed EAF operations dominate installed low-carbon capacity but face feedstock quality constraints for flat steel grades. Italian and Spanish long products producers operate the continent's largest EAF fleets.
- Carbon Capture:Post-combustion capture retrofits on existing oxygen furnaces represent transitional compliance pathways. Project viability depends on North Sea storage infrastructure buildout and EU ETS price trajectories.
- Oxygen Furnace:Conventional basic oxygen steelmaking retains cost advantage for virgin steel but faces mounting carbon cost exposure under CBAM phase-in schedules.
Electric arc furnace leads on scale; direct reduced iron gains share fastest.
Application:
Product form specifications determine which production pathways can satisfy mechanical performance requirements.
- Vehicle Components:Exposed body panels and chassis stampings require ultra-low carbon flat steel with precise surface quality. Hydrogen-based DRI-EAF integrated routes serve this specification tier exclusively.
- Structural Beams:Heavy sections for commercial and residential construction tolerate higher residual element content, enabling scrap-intensive EAF production. Ruhr-based producers supply German and Benelux building markets.
- Renewable Energy Infrastructure:Monopile foundations and tower sections demand thick plate with through-thickness toughness properties. Offshore wind developers in the North Sea basin source from mills with hydrogen reduction capability.
- Machinery Parts:Engineering steel bars and forgings for capital equipment face fragmented demand with varying carbon intensity specifications across export markets.
Structural beams lead on scale; vehicle components command premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial cluster anchors European green steel capacity concentration, with hydrogen pipeline networks and offshore wind generation co-locating around legacy blast furnace sites. National subsidy mechanisms and EU regulatory frameworks are driving divergent investment timelines across the continent.
Germany
Automotive OEM procurement from Volkswagen, BMW, and Mercedes-Benz mandates low-emission flat steel for body-in-white production. The national hydrogen strategy allocates EUR 9 billion to domestic electrolyzer capacity, with Salzgitter's SALCOS program converting coastal sites to hydrogen direct reduction.
Sweden
SSAB's Oxelösund trials demonstrate biomass injection feasibility, while H2 Green Steel's Boden facility targets 5 million tonnes annual hydrogen-based output. The Swedish Energy Agency's industrial transition support program underpins project finance for fossil-free steel demonstration plants.
Netherlands
Rotterdam hydrogen import terminals and North Sea offshore wind create feedstock security for ArcelorMittal's planned IJmuiden conversion. The national climate agreement imposes binding emission reduction targets on steel producers, accelerating asset replacement timelines.
Austria
Voestalpine's Linz integrated site leverages existing electric arc furnace capacity and hydroelectric power sourcing for specialty flat steel. The country's renewable electricity surplus supports marginal cost advantages for scrap-intensive production routes serving Central European automotive plants.
Spain
ArcelorMittal's Gijón complex evaluates carbon capture retrofits as a transitional pathway, pending North Sea storage infrastructure buildout. The Spanish recovery plan allocates structural funds to industrial decarbonization, with Asturian steelworkers transitioning to hydrogen metallurgy retraining programs.
Europe Green Steel Market Competitive Landscape
Global majors compete with regional champions across technology pathway diversification, with integrated steelmakers and pure-play hydrogen ventures occupying distinct strategic positions. Market structure consolidates around three archetypes: legacy integrated producers converting existing assets, greenfield hydrogen specialists securing automotive offtake, and scrap-based electric arc furnace operators defending feedstock access. Dominant competitive moves include hydrogen supply chain partnerships and long-term offtake contracting with construction and renewable energy developers.
Among German-based producers, Salzgitter AG and Thyssenkrupp Steel occupy positions within the integrated conversion archetype, while H2 Green Steel exemplifies the greenfield hydrogen-native model. Voestalpine AG represents the Austrian hub strategy combining renewable power integration with existing electric furnace infrastructure.
| Leading Market Players |
|---|
| Salzgitter AG |
| Voestalpine AG |
| ArcelorMittal |
| Tata Steel |
| Outokumpu |
| H2 Green Steel |
| SSAB AB |
| SSAB |
| Thyssenkrupp Steel |
| Others |
Value Network & Pricing Analysis
Specialized hydrogen metallurgy engineers concentrated in northern Germany and the Ruhr corridor command wage premiums that compress margin spreads between premium-certified and standard-grade green steel outputs. Labor-cost differentials across these regional skill pools directly widen pricing-tier spreads as producers compete for scarce direct reduction plant operators.
Pricing Analysis
Input-cost pass-through from green hydrogen and renewable electricity contracts dominates pricing structures across European green steel markets. Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM offtake agreements from construction procurement and spot-traded merchant volumes. Pricing pressure stems from electrolyzer capacity buildout lagging behind steel plant conversion timelines, compressing margins for hydrogen-based producers. Automotive OEMs exhibit lowest price sensitivity due to Scope 3 compliance mandates, while construction contractors face acute cost pressure from fixed-budget public tenders.
Supply Chain Analysis
Logistics and freight costs for hydrogen feedstock delivery from coastal import terminals to inland steel plants anchor supply chain economics across the continent. Production concentrates in Germany, Sweden, and the Netherlands where hydrogen pipeline networks and offshore wind generation co-locate with legacy steel assets. Raw material dependencies center on green hydrogen, high-grade iron ore pellets, and ferrous scrap feedstocks. Single-source vulnerability from limited electrolyzer manufacturers creates supply chain risk for direct reduction project timelines. Distribution runs through long-term offtake contracts with automotive OEMs and renewable energy developers, displacing traditional merchant steel trading channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Green Steel Market functions as a regulatory compounder where EU Carbon Border Adjustment Mechanism phase-in schedules accelerate demand displacement toward certifiable low-emission supply.
For Market Incumbents: Extend hydrogen supply chain partnerships into electrolyzer offtake agreements and pipeline infrastructure consortia to lock in feedstock cost visibility. Incumbent integrated producers face margin compression from pure-play hydrogen ventures securing automotive offtake at premium pricing; defensive consolidation through backward integration into renewable power generation and carbon capture storage access represents critical capacity to preserve. For New Entrants and Emerging Players: Begin with Polish and Baltic corridor development where underutilized blast furnace assets and planned hydrogen import terminals create conversion white-space for flat steel serving Central European automotive plants. The most penetrable segment sits in offshore wind tower foundations where project finance conditions mandate certified low-emission heavy plate and incumbent supply remains constrained. A focused go-to-market angle targets engineering-procurement-construction contractors with bundled steel-fabrication-installation offerings. For Investors and Strategic Acquirers: Valuations sit cheapest among scrap-based electric arc furnace operators facing Turkish export competition for shredded feedstock, yet these assets offer fastest path to positive cash flow and renewable power integration upside. Long-term viability framing across the analysis window favors hydrogen-native greenfield developers with secured automotive offtake and coastal hydrogen terminal access over transitional carbon capture retrofit plays. The signal to watch is national subsidy allocation mechanism announcements as inflection indicators for project sequencing and regional competitive advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Power | Salzgitter's SALCOS program anchors cost visibility through captive offshore wind sourcing. |
| Long-term Offtake Contracting | Volkswagen, BMW, and Mercedes-Benz multi-year agreements de-risk hydrogen DRI project finance. |
| Hydrogen Pipeline Infrastructure Consortia | Ruhr industrial cluster concentration reduces logistics costs for green hydrogen feedstock delivery. |
| Carbon Capture Retrofit Investment | ArcelorMittal's Belgian and Spanish sites preserve asset value pending North Sea storage buildout. |
| Scrap Feedstock Security Programs | Italian and Spanish EAF operators defend margin position through shredded scrap supply agreements. |
Research Methodology
Direct dialogue with steel plant operations directors, hydrogen supply chain managers, automotive OEM procurement leads, and EU regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from ETS carbon price registries, EU Green Deal procurement databases, hydrogen pipeline development trackers, and national industrial transition fund disclosures. Bottom-up capacity buildout modeling and top-down carbon intensity reduction mandates were triangulated against project finance announcement timelines.
Segment-level outputs across technology pathway, carbon intensity certification tier, end-use sector, and regional production cluster were generated through the analytical framework. Growth trajectories were derived from hydrogen electrolyzer deployment schedules, CBAM phase-in stringency curves, and automotive OEM Scope 3 target compliance deadlines. Industry-specific forecast inputs incorporated renewable power purchase agreement pricing trends and North Sea carbon storage infrastructure development milestones.
Several conditions sit outside the modeled scope, including potential EU ETS price volatility outside assumed trajectories, unanticipated breakthroughs in molten oxide electrolysis commercialization, and geopolitical disruptions to hydrogen import supply chains. Forecasts reflect documented assumptions about subsidy allocation continuity and automotive demand retention. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Global Corrosion Resistant Alloys Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Metal Replacement Market
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
Green Steel Market
Advanced Alloys
Nitinol Market