
 Aluminum Die Casting Market | 2026-2036
Aluminum Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Die Casting Market Intelligence
The ascent of electric vehicle manufacturers as a primary buyer archetype is redrawing the competitive landscape for aluminum die casters. Nemak leverages its scale and existing relationships with automotive OEMs to secure large-volume contracts for structural parts. Ryobi Limited specializes in complex, high-precision components for both automotive and electronics applications. Concurrently, GF Casting Solutions differentiates through advanced material science and large-format casting capabilities for EV battery housings.
Aluminum die casting is a manufacturing process that forces molten aluminum alloy under high pressure into a reusable steel mold, known as a die. This method produces complex, net-shape parts with high dimensional accuracy, primarily serving as lightweight structural and functional components. High-Pressure Die Casting (HPDC) remains the dominant technology, while demand for automotive components like engine parts and structural members constitutes the largest application segment. Electronic housings represent a fast-growing niche, driven by the need for thermal management in 5G infrastructure and consumer electronics.
Product quality and material specifications are governed by standards from organizations like the ISO and national bodies such as Germany's KBA for automotive parts. Environmental regulations, including the EU's REACH and China's dual carbon goals, influence alloy composition and promote the use of recycled aluminum. Supplier selection will increasingly hinge on a caster's ability to document recycled content and provide lightweighting solutions for electric mobility platforms.
Market Dynamics
The market's trajectory is defined by the automotive sector's pivot to electric mobility. This shift creates a dual mandate for die casters: produce larger, more complex structural components while simultaneously increasing the use of recycled aluminum to meet circular economy goals.
Growth Catalysts
- Vehicle Emission Standards:Regulations like the EU Green Deal and EPA mandates in the United States compel automotive OEMs to adopt lightweight aluminum components, directly stimulating demand for die cast parts to reduce overall vehicle weight and improve EV range.
- Large-Format Casting Technology:The advent of large-tonnage die casting machines enables the production of single-piece mega-castings for vehicle underbodies, consolidating parts, reducing assembly complexity, and lowering manufacturing costs for EV platforms.
- 5G Infrastructure Expansion:The rollout of 5G telecommunications requires thermally conductive and lightweight housings for base stations and network equipment, creating a significant demand stream for high-precision aluminum die cast components.
Market Restraints
- Primary Aluminum Price Volatility:The market's cost structure is highly exposed to price fluctuations on the London Metal Exchange for primary aluminum, creating margin pressure and forecasting uncertainty for die casters not secured by long-term contracts.
- Threat from Advanced Composites:In certain non-structural automotive and aerospace applications, carbon fiber-reinforced polymers and other advanced composites present a substitution threat, offering superior strength-to-weight ratios despite higher initial costs.
- Inherent Porosity Challenges:High-pressure die casting can introduce gas and shrinkage porosity within thick-walled components, a technical limitation that can compromise mechanical integrity and require costly secondary inspections or process controls.
Strategic Opportunities
- Medical Device and Equipment Housings:The medical technology sector represents an underpenetrated market, with opportunities in producing lightweight, EMI-shielded enclosures for diagnostic imaging systems, surgical robots, and patient monitoring devices.
- Recycled Aluminum Alloy Development:Developing and certifying high-performance secondary alloys presents a major opportunity, allowing casters to meet OEM and regulatory demands for sustainability, such as those outlined in the EU's CSRD, and gain a competitive edge.
- Automotive Sector Growth in Southeast Asia:Establishing casting facilities in emerging automotive manufacturing hubs like Vietnam and Thailand offers a strategic advantage to serve new EV production plants and localize supply chains for regional automakers.
Industry Challenges
- High Capital Expenditure:The acquisition of large-tonnage die casting machines and associated automation for producing structural EV components requires substantial capital investment, creating a high barrier to entry for smaller firms.
- Simulation and Tooling Expertise Gap:A shortage of skilled engineers proficient in advanced flow simulation software and complex die design hampers the ability of some casters to optimize production and minimize defects for intricate parts.
- Recycled Content Traceability:Implementing robust traceability systems to document the origin and percentage of recycled aluminum, as required for green certifications and OEM audits, presents a significant operational and logistical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Die Casting Market |
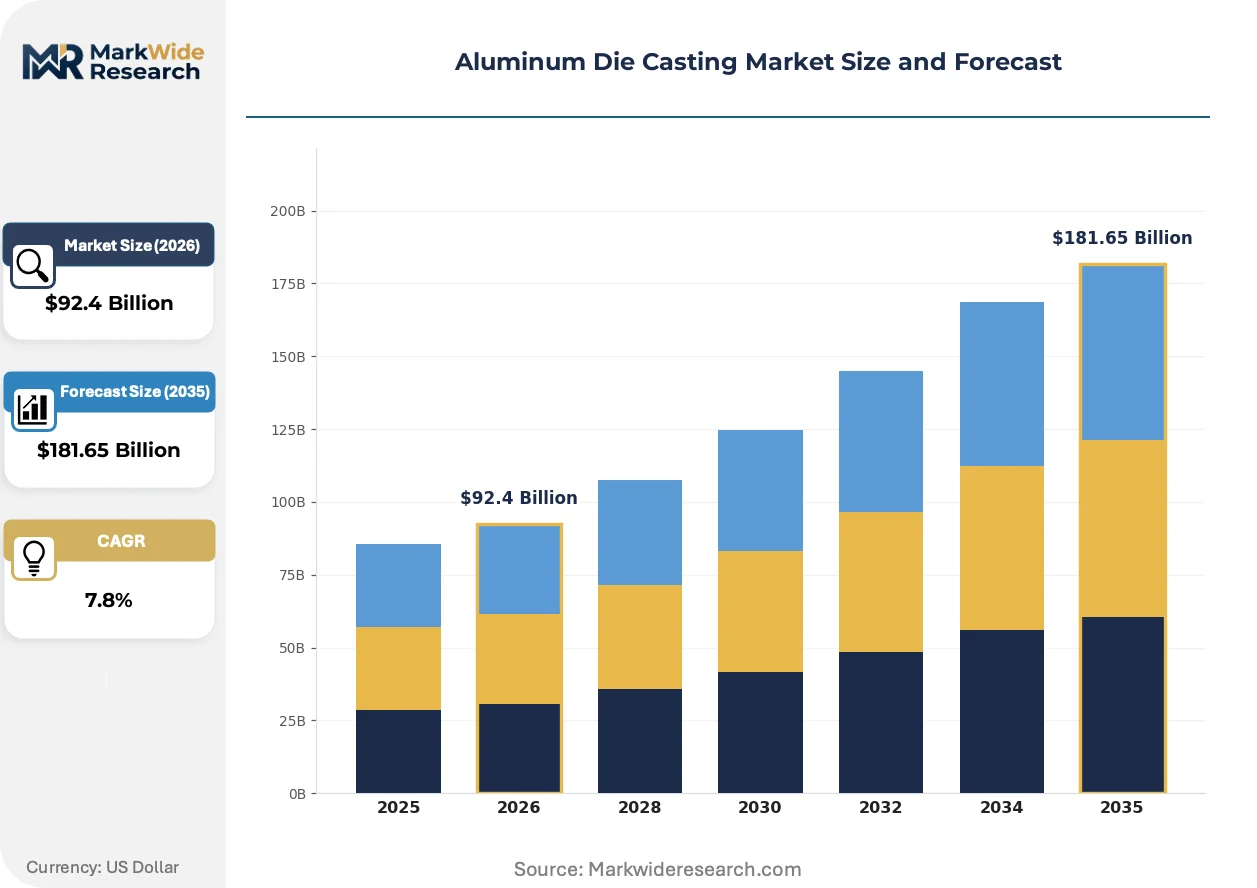
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $181.65 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Components, Electronic Housings, Industrial Equipment, Consumer Goods End User: Automotive OEMs, Electronics Manufacturers, Aerospace Industry, Home Appliances Application: Engine Parts, Heat Sinks, Structural Components, Tooling Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Gravity Die Casting, Vacuum Die Casting |
| Companies Covered | Nemak, Ryobi Limited, GF Casting Solutions, Alcoa Corporation, Dynacast International, Endurance Technologies Limited, Rheinmetall AG, Martinrea Honsel Germany GmbH, Alcast Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Die Casting Market Strategic Shifts & Innovations
Material science advancements and process digitalization are converging to redefine the performance limits of die cast components. This evolution is driven by the need for lighter, stronger, and more thermally efficient parts for next-generation electric vehicles and electronics.
Semi-Solid Metal (SSM) casting, a thixocasting process, produces components with lower porosity and superior mechanical properties compared to conventional HPDC. Automotive manufacturers are adopting SSM for critical safety and powertrain parts requiring high integrity. This technology is decomposing the traditional boundary between casting and forging, enabling cast parts to enter performance-critical applications previously reserved for more expensive wrought products.
China's "dual carbon" policy framework is accelerating the shift toward recycled aluminum and energy-efficient production within its vast die casting industry. This regulation forces foundries to invest in cleaner melting technologies and scrap processing infrastructure to meet national carbon peak and neutrality targets. The automotive supply chain in China is most affected, with OEMs now prioritizing suppliers who can provide verifiable low-carbon aluminum castings.
A shift from sourcing individual components to co-developing integrated systems is altering buyer-supplier relationships. Automotive OEMs are increasingly engaging die casters early in the design phase for large structural modules like battery trays and front-end structures. This collaborative model is most visible in the North American and European EV markets, where speed-to-market and design optimization are paramount.
Aluminum Die Casting Market Segmentation
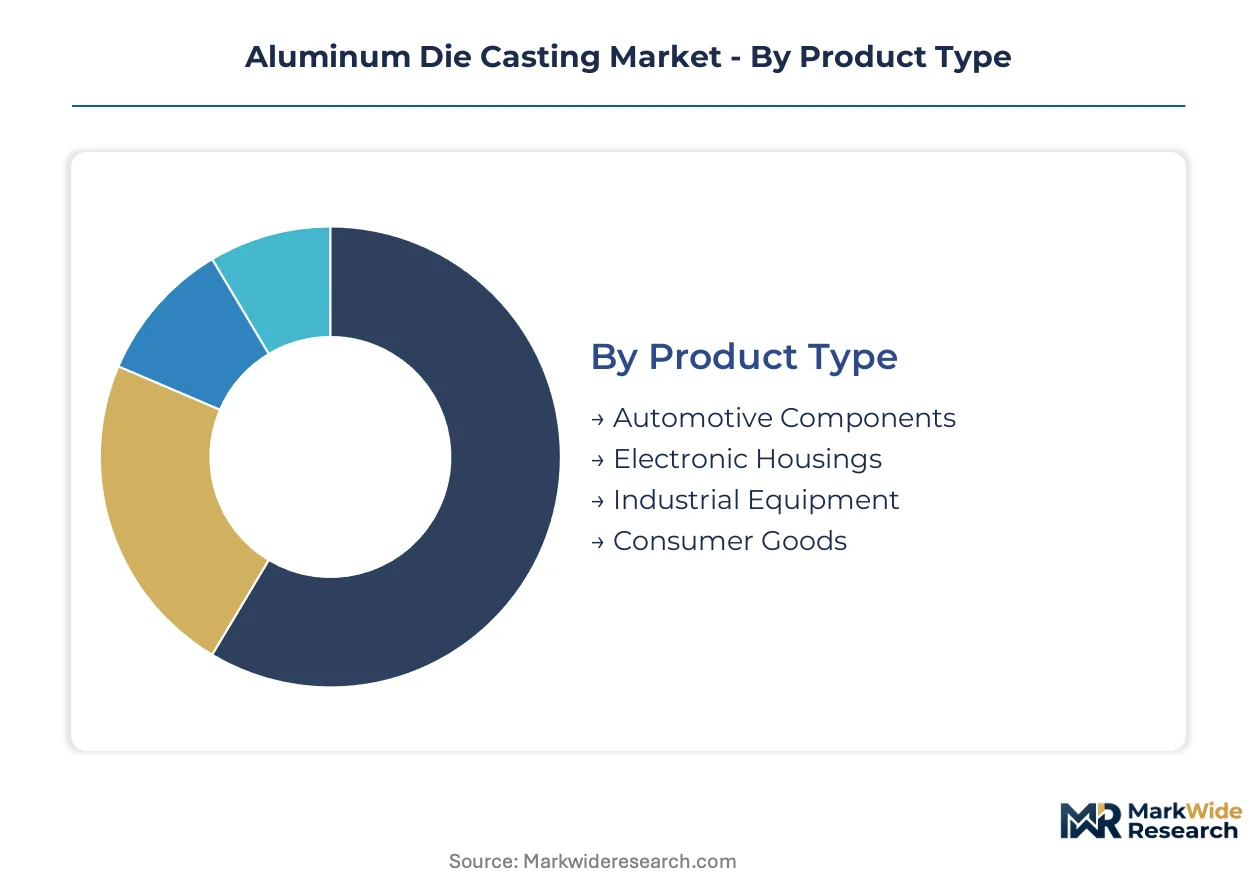
Aluminum die casting market dynamics are intricate, driven by diverse product requirements and end-user demands. Understanding these segments helps pinpoint where manufacturing capabilities and material science innovations are most impactful. This granular view reveals distinct pathways for market penetration and technology adoption across key industrial sectors.
Product Type:
The distribution channels for aluminum die cast products vary significantly, with direct OEM supply dominating for large-volume components and specialized distributors serving niche industrial applications.
- Automotive Components:These parts include engine blocks, transmission cases, and structural members, typically produced from high-strength aluminum alloys. Demand primarily resides within China's automotive manufacturing sector, driven by stringent vehicle emission standards and the shift to electric mobility platforms.
- Electronic Housings:These precision-cast enclosures provide electromagnetic shielding and thermal management for sensitive electronic devices. Growth is rapid in Germany and South Korea for 5G infrastructure and consumer electronics, necessitating intricate designs and high thermal conductivity.
- Industrial Equipment:These castings form critical parts for machinery, pumps, and valves, often requiring durability and corrosion resistance.
- Consumer Goods:Die cast aluminum finds use in appliances, power tools, and furniture, valued for its aesthetic finish and lightweight properties.
By volume, Automotive Components leads the market. By growth pace, Electronic Housings is ahead.
End User:
End-user segments often exhibit distinct cost sensitivities, influencing material selection and production process choices for aluminum die casting.
- Automotive OEMs:These manufacturers require high-volume, lightweight structural components for both internal combustion engine vehicles and electric vehicles. Procurement patterns prioritize suppliers capable of delivering mega-castings and meeting rigorous quality standards like those from Germany's KBA.
- Electronics Manufacturers:This segment demands precise, thermally efficient enclosures and heat sinks for devices ranging from smartphones to server racks. Supply chain requirements emphasize rapid prototyping and compliance with environmental directives such as the EU's RoHS.
- Aerospace Industry:This sector specifies ultra-lightweight, high-integrity castings for aircraft components, often with stringent material certifications.
- Home Appliances:Manufacturers in this segment seek cost-effective, durable die cast parts for white goods and small kitchen appliances.
Automotive OEMs represent the largest purchasing block, while Electronics Manufacturers are expanding most quickly.
Application:
The volume requirements for aluminum die casting applications vary considerably, from mass-produced engine components to specialized tooling parts.
- Structural Components:These large-format castings, like battery housings and chassis elements, are crucial for electric vehicle platforms, reducing assembly complexity. Demand is accelerating in the United States and Norway due to strong EV adoption and manufacturing investments.
- Engine Parts:These include cylinder heads, blocks, and manifolds, requiring excellent mechanical properties and thermal stability. China's automotive production continues to drive substantial demand for these traditional components.
- Heat Sinks:These components efficiently dissipate heat from electronic devices, crucial for 5G base stations and high-performance computing.
- Tooling:Die cast aluminum is used for molds, jigs, and fixtures, valued for its precision and moderate cost in manufacturing processes.
Structural Components are gaining share rapidly, while Engine Parts maintain a significant volume base.
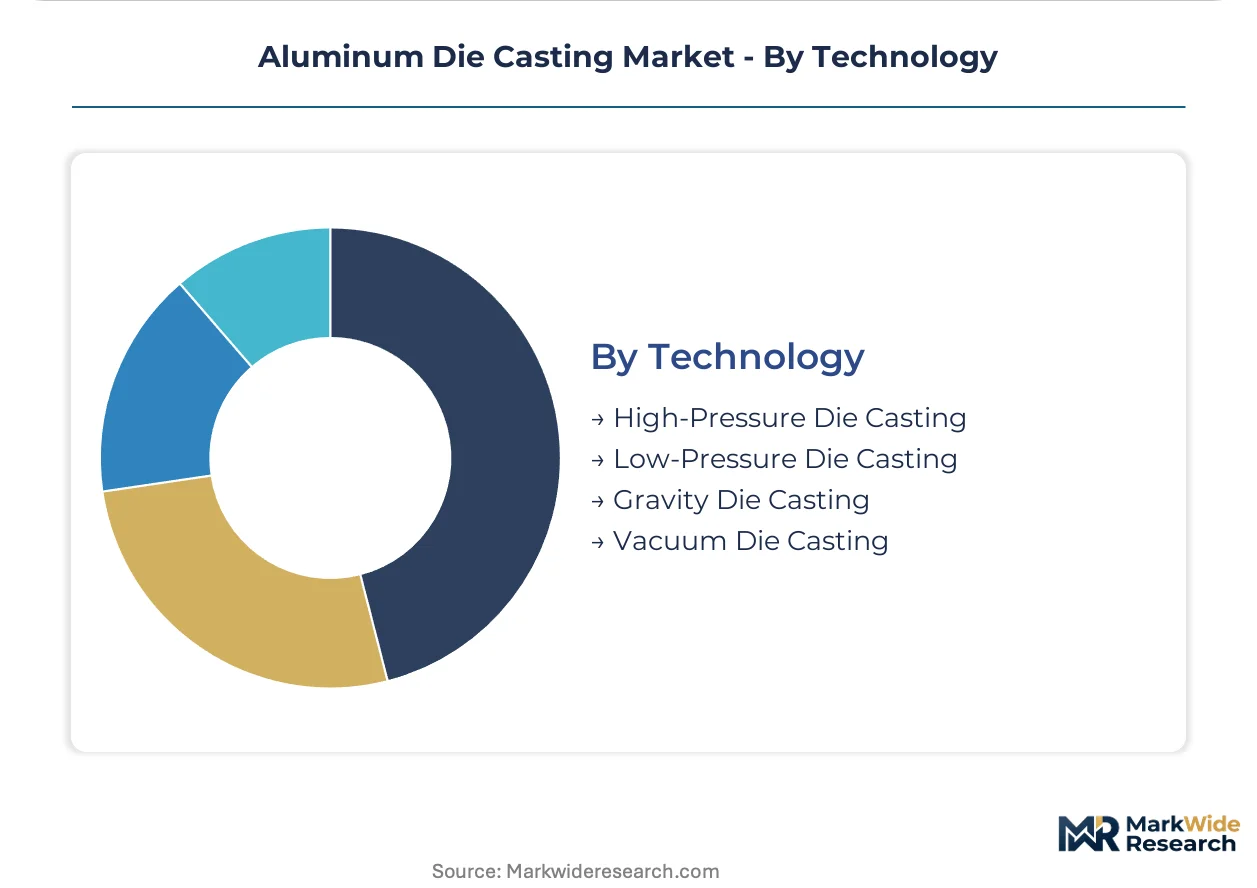
Technology:
Die casting technologies range from mature, widely adopted methods to emerging processes offering enhanced material properties and design flexibility.
- High-Pressure Die Casting:This dominant process forces molten aluminum into a die at high speed and pressure, producing complex parts with excellent surface finish. It remains the workhorse for automotive components in Germany and Japan, valued for its efficiency in mass production.
- Vacuum Die Casting:This advanced technique evacuates air from the die cavity before injection, significantly reducing porosity and improving mechanical properties. It is increasingly adopted in the United States for critical structural components in electric vehicles, where part integrity is paramount.
- Low-Pressure Die Casting:This method uses lower pressure to fill the die, resulting in denser castings suitable for wheels and complex engine parts.
- Gravity Die Casting:Also known as permanent mold casting, this process relies on gravity to fill the mold, producing high-integrity parts with superior metallurgical quality.
High-Pressure Die Casting holds the largest market share, with Vacuum Die Casting demonstrating the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs, particularly electric vehicle manufacturers, concentrate demand for aluminum die cast components across key manufacturing hubs globally. This buyer archetype drives significant investment in advanced casting technologies and sustainable material solutions. Geopolitical shifts influence regional market dynamics.
China
China's automotive manufacturing sector drives substantial demand for aluminum die castings, particularly for engine parts and structural components. The country's dual carbon goals promote recycled aluminum and energy-efficient production within its vast die casting industry. Foundries in the Yangtze River Delta are investing in cleaner melting technologies and mega-casting capabilities for EV platforms.
United States
The United States market experiences strong demand for structural components due to robust EV adoption and manufacturing investments. EPA mandates compel automotive OEMs to adopt lightweight aluminum components for improved EV range. Manufacturing clusters in Michigan and the Southeast are expanding capacity for large-format castings and vacuum die casting technologies.
Germany
Germany's automotive industry, a global leader, maintains high demand for high-pressure die cast automotive components. The EU Green Deal and KBA standards necessitate lightweighting solutions and stringent quality control for vehicle parts. Bavarian and Baden-Württemberg-based casters are innovating in advanced material science and large-format casting for EV battery housings.
Japan
Japan's mature automotive sector sustains demand for high-pressure die casting, valued for its efficiency in mass production of complex parts. METI initiatives support advanced manufacturing processes and material development for next-generation vehicles. Manufacturers in the Chubu region focus on precision components and process optimization for automotive applications.
South Korea
South Korea's electronics manufacturers and rapidly expanding EV industry generate significant demand for precision aluminum die castings. Environmental directives, such as those emphasizing sustainability, influence material selection and production processes. The Seoul Capital Area is a center for electronic housing production and advanced structural EV component development.
Aluminum Die Casting Market Key Industry Players
Player mix skews toward established industrial manufacturers and specialized casting firms. The market structure exhibits a tiered consolidation, with large-scale players dominating high-volume automotive contracts. Strategic archetypes include global diversified industrial groups, regional specialists, and technology-focused innovators. Dominant competitive moves involve significant capacity expansion for large-format castings and strategic partnerships with electric vehicle OEMs.
Within the high-volume automotive segment, Nemak represents a global leader leveraging scale and existing OEM relationships for structural parts. Japan-based Ryobi Limited exemplifies a specialist in complex, high-precision components for both automotive and electronics applications. GF Casting Solutions, a European entity, occupies a position focused on advanced material science and large-format casting capabilities for EV battery housings. These firms collectively demonstrate diverse approaches to market penetration and technological leadership across key sectors.
| Leading Market Players |
|---|
| Nemak |
| Ryobi Limited |
| GF Casting Solutions |
| Alcoa Corporation |
| Dynacast International |
| Endurance Technologies Limited |
| Rheinmetall AG |
| Martinrea Honsel Germany GmbH |
| Alcast Technologies |
| Others |
Cost & Logistics Intelligence
The substitution of primary aluminum with recycled aluminum simultaneously reshapes supply geography and pricing economics in the die casting market. This shift reduces reliance on globally traded raw materials and promotes localized scrap processing networks.
Pricing Analysis
Cost-plus contract patterns, often indexed to London Metal Exchange (LME) primary aluminum prices, define much of the market's pricing. Price differentiation stems from the quality grade, often verified by ISO or KBA standards, and the volume scale of the order. Pricing pressure stems from automotive OEMs demanding lightweighting solutions with cost efficiencies, while the need for certified recycled content adds a premium. Automotive OEMs represent the most price-sensitive buyers for high-volume, standard components, whereas electronics manufacturers prioritize precision and thermal performance.
Supply Chain Analysis
Inbound logistics costs, particularly related to port congestion and container availability on key Asian-European trade lanes, significantly impact the aluminum die casting supply chain. Supply concentration centers in China, Germany, and Japan, which are major automotive manufacturing hubs. The market draws from primary aluminum and aluminum scrap, alongside specialized alloying elements. Primary aluminum price volatility represents a structural risk. Distribution runs through direct OEM supply for large-volume contracts and specialized distributors for niche industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Co-development partnerships, particularly for large structural EV components, represent a significant service-attach opportunity. This collaborative model, offering design optimization and speed-to-market, is expanding faster than traditional component sales.
For Market Incumbents:
Secure long-term contracts with electric vehicle OEMs for mega-castings, mitigating the threat from new entrants specializing in large-format parts. Invest in advanced material science for high-performance recycled aluminum alloys to meet sustainability mandates like the EU's CSRD. This strategic lever enables casters to offer lightweighting solutions with verifiable low-carbon footprints. Expand capacity in key EV manufacturing regions like the United States and China.
For New Entrants and Emerging Players:
Advanced simulation and tooling expertise, often under-served by traditional casters, offers new entrants a significant service-layer gap. Target specialized applications such as medical device housings and 5G infrastructure components, where precision and thermal management are paramount. Focus on developing niche specialization in low-porosity casting technologies like Vacuum Die Casting or Semi-Solid Metal (SSM) casting. This go-to-market angle allows penetration into critical safety and performance-sensitive applications.
For Investors and Strategic Acquirers:
Capital is best deployed toward mid-sized casters specializing in advanced material science and large-format structural components for electric vehicles. The long-term viability of the market hinges on the global pivot to electric mobility and stringent environmental regulations. Acquisition targets should possess strong R&D capabilities in recycled aluminum alloy development or advanced process technologies. A key signal to watch is the increasing number of OEM mandates for verifiable high recycled content percentages in their supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Mega-castings | Enables production of single-piece vehicle underbodies, reducing assembly complexity for automotive OEMs. |
| Recycled Alloy Certification | Meets EU Green Deal and China's dual carbon goals, enhancing supplier selection for sustainable platforms. |
| Advanced Process Adoption (SSM/Vacuum) | Improves mechanical properties and reduces porosity for critical safety parts in electric vehicles. |
| Co-development with EV OEMs | Integrates casters early in design, optimizing battery trays and front-end structures for speed-to-market. |
| Southeast Asia Facility Investment | Localizes supply chains and serves new EV production plants in emerging automotive manufacturing hubs. |
Research Approach
The analysis maps automotive components, electronic housings, and industrial equipment sub-sectors, each validated through primary interviews with automotive OEM procurement leads and die casting plant managers. Secondary data sources include ISO standards, Germany's KBA regulations, London Metal Exchange (LME) data, and various industry association reports. This approach integrates insights from material science engineers and electronics manufacturers' supply chain heads, employing both bottom-up and top-down triangulation.
Forecast outputs underwent rigorous consistency checks against external benchmarks, including global vehicle production data and electronics manufacturing indices. The analytical framework models market dynamics across product type, end user, application, technology, and regional EV adoption rates. Compound Annual Growth Rates (CAGRs) derive from projected demand for lightweight components in electric vehicles and the expansion of 5G infrastructure. Key forecast inputs include EV production forecasts and 5G network rollout projections.
Underlying assumptions cover stable regulatory environments and consistent raw material supply, with deviation risk concentrated in primary aluminum price volatility and evolving EV adoption curves. Forecasts reflect these assumptions. Practitioners should keep alternative scenarios live as global trade policies and technological advancements in composite materials evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Asia-Pacific Metal Casting Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Nickel Boride Alloy Market
Advanced Alloys
Tungsten Titanium Carbide Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Quartz Kitchen Countertops Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
Global Shape Memory Alloys Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Ballistic Material Market