
 Nickel Superalloy Market | 2026-2036
Nickel Superalloy Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel Superalloy Market Intelligence
Modular turbine blade architectures is recalibrating procurement patterns across the supply base. Precision Castparts Corp. anchors the investment casting segment through captive foundry networks serving OEM engine platforms. Carpenter Technology differentiates via vacuum induction melting capacity for wrought superalloy bar and billet. Haynes International specializes in corrosion-resistant alloy formulations for chemical processing applications.
Nickel superalloys are precipitation-strengthened alloys containing chromium, cobalt, molybdenum, and aluminum, engineered to retain mechanical strength above 80 percent of their melting temperature through gamma-prime phase strengthening. These materials primarily enable hot-section components in gas turbine engines where operating temperatures exceed 1,000 degrees Celsius. Wrought superalloys command the largest product type position due to established forging infrastructure for rotating disk applications, while powder superalloys represent the fastest-expanding category as hot isostatic pressing yields finer grain structures for next-generation blade designs. Among fabrication technologies, investment casting retains dominance for complex airfoil geometries, though additive manufacturing is displacing traditional methods for prototype and low-volume repair components.
FAA airworthiness directives and EASA engine certification standards dictate minimum creep-rupture life thresholds for flight-critical superalloy components, effectively filtering market access to qualified suppliers. REACH chemical restrictions in Europe and EPA emissions regulations in the United States additionally constrain foundry process chemistry and recycling methodologies. Stakeholders must monitor evolving powder metallurgy qualification protocols and dual-source requirements from defense procurement agencies.
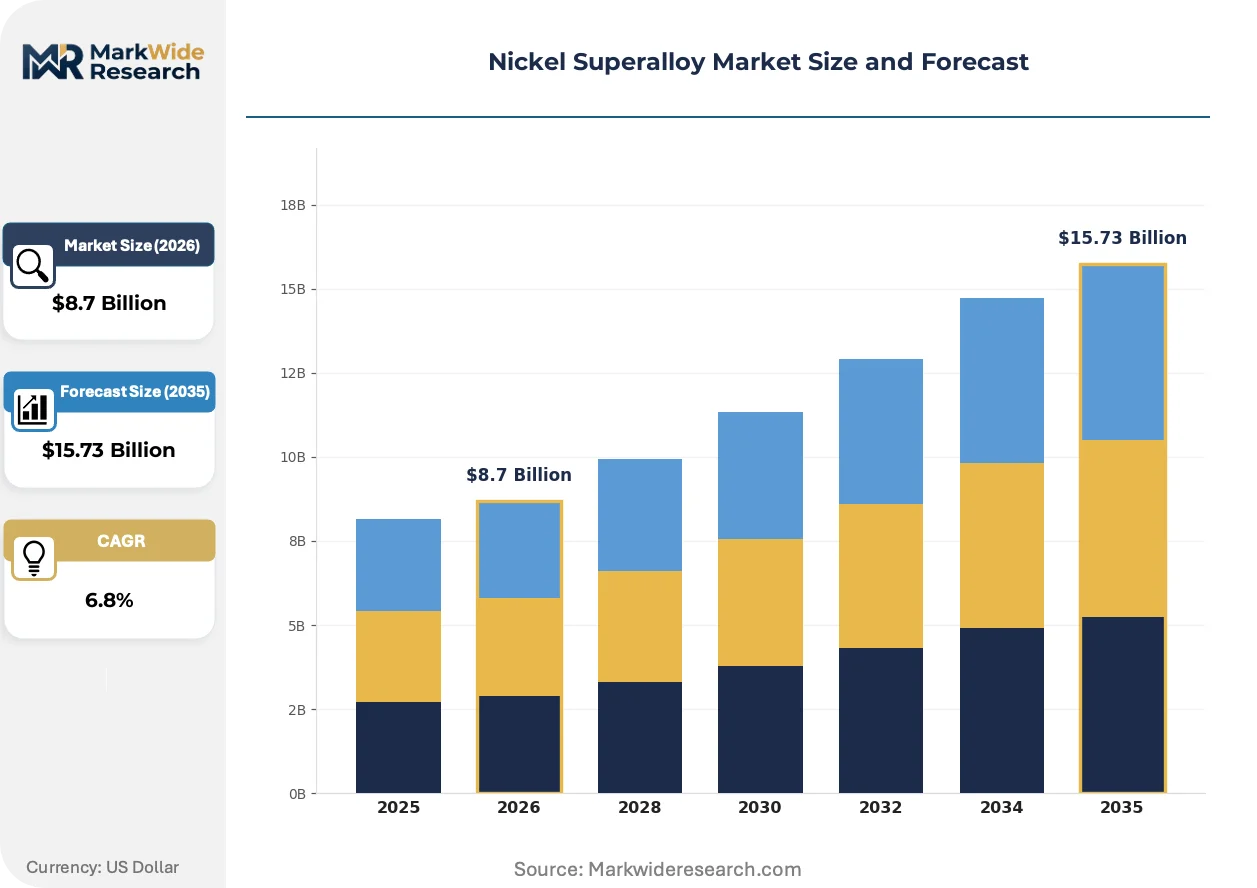
Market Dynamics
Single-crystal turbine blade architectures are recalibrating procurement patterns across the supply base, as aerospace engine manufacturers consolidate orders around qualified precision casting networks capable of meeting FAA and EASA certification thresholds.
Growth Catalysts
- REACH chemical restrictions:European EPA-equivalent constraints on foundry process chemistry are accelerating investment in closed-loop recycling systems, tightening supplier qualification barriers to entry.
- Hot isostatic pressing:Powder superalloy densification technology enables finer grain structures for next-generation blade designs, expanding addressable component geometries beyond wrought forging limits.
- German precision casting clusters:Concentrated tier-one foundry capacity around Munich and Hamburg anchors dual-source requirements from defense procurement agencies, stabilizing order visibility.
Market Restraints
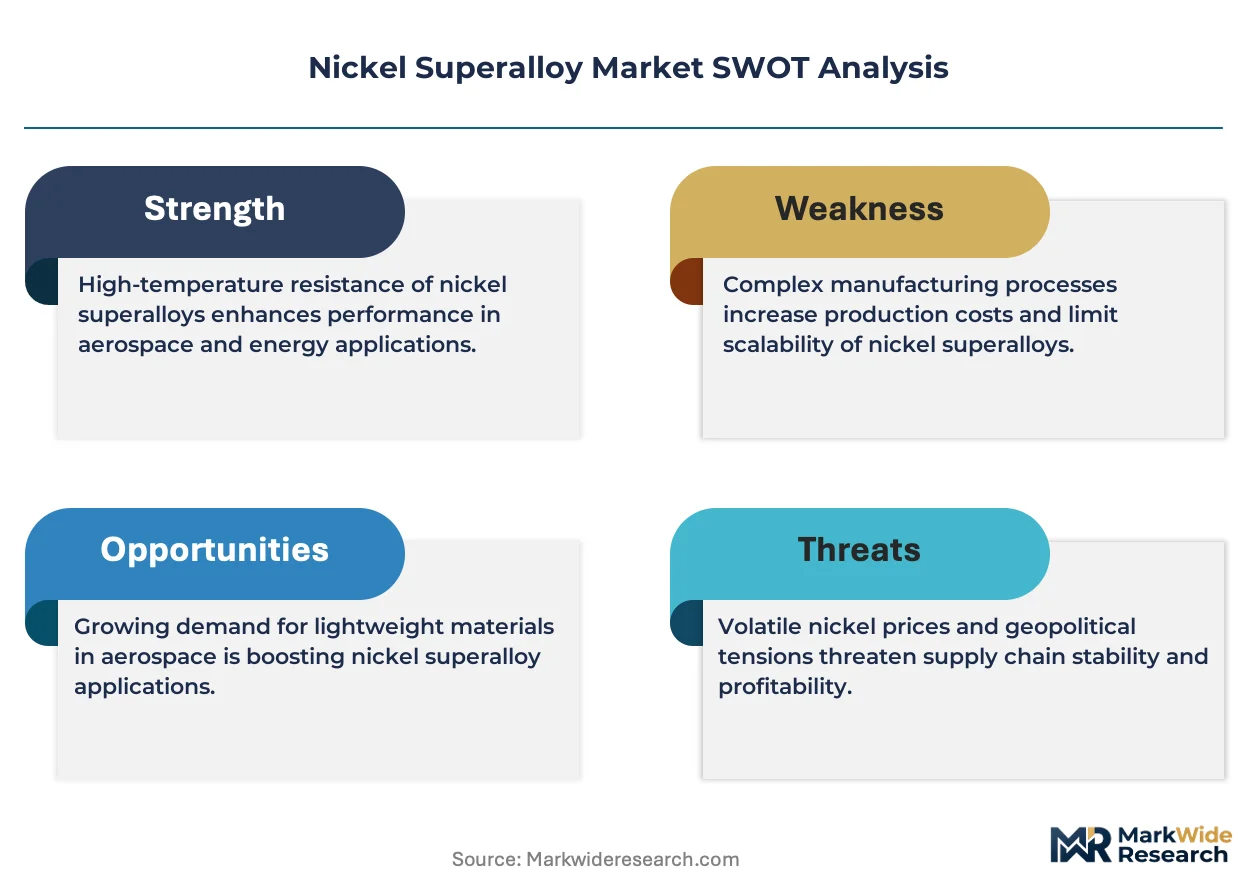
- Cobalt and rhenium price volatility:Gamma-prime strengthening elements face concentrated supply from Central African mining operations, compressing margin predictability for vacuum induction melting operators.
- Japanese vacuum induction capacity concentration:Wrought superalloy billet production clusters around three primary metallurgical groups, creating single-source vulnerability for rotating disk applications.
- Ceramic core substitution limits:Investment casting wax pattern technology remains irreplaceable for complex internal cooling channel geometries, locking process economics.
Strategic Opportunities
- India's PLI scheme for aerospace components:Production-linked incentives for precision manufacturing are attracting superalloy processing investments to Bangalore and Hyderabad industrial corridors.
- Additive manufacturing repair depots:Laser powder bed fusion technology converges with directed energy deposition for blade tip restoration, opening aftermarket service revenue streams.
- IRA clean energy tax credits:US domestic content requirements for advanced manufacturing equipment subsidize foundry modernization for hydrogen turbine compatibility.
Industry Challenges
- Dual-source qualification timelines:FAA airworthiness directives mandate parallel certification pathways for flight-critical components, extending new supplier onboarding to 18-24 months.
- Gamma-prime phase control expertise:Precipitation heat treatment protocols require metallurgists with decade-plus experience, constraining workforce scalability for powder superalloy expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel Superalloy Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Superalloys, Wrought Superalloys, Powder Superalloys, Directionally Solidified Alloys Application: Aerospace Engines, Gas Turbines, Power Generation Equipment, Chemical Processing Plants End User Industry: Commercial Aviation, Energy Production, Petrochemical Manufacturing, Defense Equipment Fabrication Technology: Investment Casting, Hot Isostatic Pressing, Additive Manufacturing, Powder Metallurgy |
| Companies Covered | Carpenter Technology Corporation, Special Metals Corporation, Allegheny Technologies Incorporated (ATI), VDM Metals GmbH, Doncasters Group, Precision Castparts Corp. (PCC), Aperam S.A., Sandvik AB, Haynes International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel Superalloy Market Strategic Shifts & Innovations
Process intensification across melting, forming, and finishing stages is compressing traditional superalloy manufacturing timelines while elevating property consistency thresholds for hot-section engine components.
Additive manufacturing for repair and prototyping is electrifying aftermarket service economics. Laser powder bed fusion enables blade tip restoration without full component replacement. Maintenance, repair, and overhaul providers at Singapore and Dubai aviation hubs are adopting hybrid repair cells. The technology is electrifying spare parts logistics by collapsing lead times from months to days.
EPA emissions regulations for foundry operations are tightening permissible volatile organic compound thresholds. US-based investment casting facilities must retrofit thermal oxidizers and regenerative thermal oxidizer systems. Powder metallurgy operations face heightened particulate matter monitoring. California Air Resources Board standards are propagating to other states through OEM supply chain audits.
Long-term offtake agreements are displacing spot market purchasing for vacuum induction melted bar stock. Tier-one engine manufacturers lock in five-year wrought superalloy supply contracts with metallurgical processors. Pricing mechanisms now index to London Metal Exchange nickel futures plus fixed conversion premiums. This contracting evolution is most visible in United States and Germany, where precision forging capacity constraints favor relationship-based procurement over transactional sourcing.
Nickel Superalloy Market Segmentation
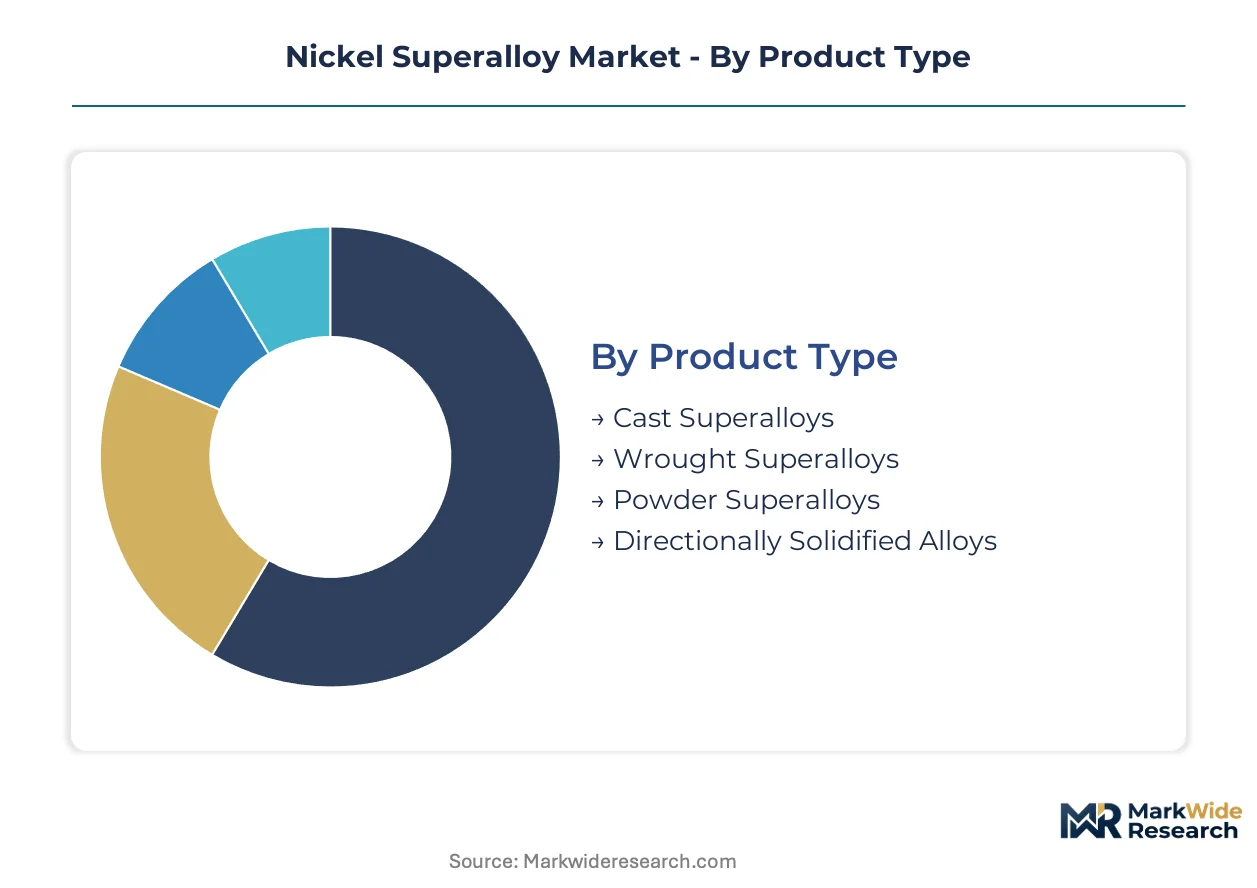
Segmentation in nickel superalloys reveals how capital intensity and technical barriers concentrate value capture among qualified suppliers. Each dimension—product form, application, end-use sector, and fabrication route—carries distinct qualification timelines and equipment thresholds that shape competitive positioning.
Product Type:
Capital intensity peaks at different process stages across these metallurgical categories, with melting infrastructure and thermal processing equipment representing the dominant fixed cost layers.
- Wrought Superalloys:Vacuum induction melting followed by electroslag remelting produces billet and bar stock for rotating disk applications. United States forging clusters around Pennsylvania and Ohio absorb the majority of demand from commercial aviation engine programs, constrained by limited qualified press capacity.
- Powder Superalloys:Argon atomization and hot isostatic pressing yield finer grain structures than conventional processing. German precision engineering hubs around Munich are expanding atomization capacity to serve next-generation blade designs with complex cooling geometries.
- Cast Superalloys:Equiaxed grain structures dominate legacy turbine component production.
- Directionally Solidified Alloys:Columnar grain alignment enhances creep resistance for intermediate-temperature airfoils.
Wrought superalloys absorb the bulk of installed capacity; powder superalloys are expanding most quickly.
Application:
Operating temperature thresholds and FAA certification requirements segment demand by component criticality and replacement frequency.
- Aerospace Engines:Hot-section components including turbine blades, vanes, and combustors operate above 1,000 degrees Celsius. United States engine OEMs in Connecticut and Ohio drive specification development, with single-crystal blade orders consolidating around qualified investment casting networks.
- Gas Turbines:Industrial power generation and mechanical drive applications require corrosion-resistant formulations for combined-cycle plants. Japanese utilities are retrofitting existing fleets with advanced thermal barrier coatings, extending component lifecycles.
- Power Generation Equipment:Steam turbine and generator components utilize lower-temperature nickel alloys.
- Chemical Processing Plants:Reactor vessels and heat exchangers demand oxidation-resistant formulations for sulfuric acid and petrochemical environments.
Aerospace engines command premium pricing tiers; gas turbines are gaining share fastest in installed base expansion.
End User Industry:
Procurement patterns diverge sharply between performance-maximizing and cost-optimizing buyer segments, with defense and commercial aviation prioritizing reliability over unit economics.
- Commercial Aviation:Narrow-body and wide-body engine programs generate recurring demand for flight-critical rotating components. FAA airworthiness directives mandate dual-source qualification, extending supplier onboarding timelines and locking incumbent relationships.
- Defense Equipment:Fighter jet and helicopter engine procurement prioritizes domestic supply chain security. United States defense agencies enforce Berry Amendment compliance, restricting foreign-sourced superalloy content for military applications.
- Energy Production:Utility-scale gas turbine operators negotiate long-term service agreements with OEMs.
- Petrochemical Manufacturing:Process plant operators source corrosion-resistant alloys through project-based contracting.
Commercial aviation anchors volume commitments; defense equipment is climbing the fastest amid geopolitical reshoring mandates.
Fabrication Technology:
Process maturity and qualification status determine which technologies can access flight-critical component markets versus repair and prototyping niches.
- Investment Casting:Ceramic core technology enables complex internal cooling channels for single-crystal turbine blades. Precision foundries in Germany and Japan maintain process expertise barriers that limit new entrant qualification.
- Hot Isostatic Pressing:Powder densification eliminates casting porosity and enables near-net-shape forming for disk applications. United States HIP capacity is expanding around Pittsburgh to support powder superalloy growth.
- Additive Manufacturing:Laser powder bed fusion and directed energy deposition are qualifying for blade tip repair and prototype production.
- Powder Metallurgy:Conventional press-and-sinter approaches serve lower-stress components outside hot-section applications.
Investment casting dominates qualified component supply; additive manufacturing is expanding most quickly in aftermarket repair depots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in metallurgical clusters serving aerospace engine programs, while consumption spreads across defense procurement agencies and commercial aviation OEMs. The United States, Germany, and Japan anchor supply-side capacity through vacuum induction melting and precision casting infrastructure. Regulatory certification requirements in each jurisdiction filter market access to qualified suppliers.
United States
Connecticut and Ohio host engine OEM specification development for hot-section components. FAA airworthiness directives mandate dual-source qualification pathways extending supplier onboarding to 18-24 months. Pittsburgh investment casting networks and Pennsylvania forging clusters absorb demand from narrow-body and wide-body engine programs.
Germany
Munich and Hamburg precision casting clusters stabilize order visibility through defense procurement dual-source requirements. REACH chemical restrictions accelerate closed-loop recycling system investments, tightening supplier qualification barriers. Bavarian foundries maintain process expertise for complex internal cooling channel geometries.
Japan
Three primary metallurgical groups concentrate vacuum induction capacity for wrought superalloy billet production. METI industrial policy supports domestic content requirements for rotating disk applications. Chubu and Kansai regions house tier-one foundry capacity serving utility-scale gas turbine retrofits.
United Kingdom
Rolls-Royce engine programs drive specification development for single-crystal turbine blade architectures. UK defense agencies enforce supply chain security protocols restricting foreign-sourced superalloy content for military applications. Midlands aerospace clusters coordinate with German precision engineering hubs on powder metallurgy qualification.
India
Bangalore and Hyderabad industrial corridors attract superalloy processing investments through PLI scheme production-linked incentives. DGFT export promotion frameworks support precision manufacturing capability buildup. Domestic aviation MRO expansion creates aftermarket demand for blade tip restoration services.
Nickel Superalloy Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across melting, forming, and finishing stages. The vendor base stratifies around captive foundry networks, vacuum induction melting operators, and corrosion-resistant alloy formulators. Three archetypes dominate: integrated engine OEM suppliers, independent metallurgical processors, and specialty alloy developers. Capacity expansion and strategic partnerships represent the primary competitive vectors as qualification timelines lock incumbent relationships.
Among North American metallurgical processors, Carpenter Technology Corporation and Special Metals Corporation exemplify vacuum induction melting capacity for wrought superalloy bar and billet. Precision Castparts Corp. anchors the investment casting segment. VDM Metals GmbH represents German precision engineering capabilities in powder superalloy atomization. Haynes International, Inc. occupies a position within corrosion-resistant alloy formulations for chemical processing environments.
| Leading Market Players |
|---|
| Carpenter Technology Corporation |
| Special Metals Corporation |
| Allegheny Technologies Incorporated (ATI) |
| VDM Metals GmbH |
| Doncasters Group |
| Precision Castparts Corp. (PCC) |
| Aperam S.A. |
| Sandvik AB |
| Haynes International, Inc. |
| Others |
Cost & Logistics Intelligence
Gamma-prime phase control expertise concentrated in German and Japanese metallurgical clusters widens pricing-tier spreads between certified aerospace-grade superalloys and industrial formulations, as labor-cost differentials compound qualification-timeline premiums for flight-critical components.
Pricing Analysis
Margin tightening in wrought superalloy bar stock reflects long-term offtake agreements indexing to London Metal Exchange nickel futures plus fixed conversion premiums. Three-tier pricing structure across premium aerospace-grade, standard industrial-grade, and economy chemical-processing-grade levels separates certified single-crystal blade material from rotating disk billet and corrosion-resistant formulations. Pricing pressure stems from cobalt and rhenium price volatility concentrated in Central African mining operations. Commercial aviation engine OEMs exhibit lowest price sensitivity due to FAA-mandated dual-source qualification requirements, while petrochemical operators negotiate aggressively on project-based contracts.
Supply Chain Analysis
Dual-source requirements mandated by FAA airworthiness directives and defense procurement agencies force tier-one engine manufacturers to qualify parallel suppliers for flight-critical components, extending new supplier onboarding to 18-24 months. Geographic supply concentrates in the United States, Germany, and Japan through vacuum induction melting and precision casting infrastructure. Raw material dependencies center on nickel, cobalt, chromium, and rhenium feedstocks. Single-source vulnerability risks emerge from Japanese vacuum induction capacity concentration around three primary metallurgical groups. Distribution runs through captive foundry networks serving OEM engine platforms and independent metallurgical processors supplying tier-two fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH chemical restrictions and EPA emissions regulations force capital-intensive environmental retrofits that weaker, undiversified foundries cannot absorb.
For Market Incumbents: Hedge against cobalt and rhenium price volatility through backward integration into secondary recycling streams and long-term offtake agreements with Central African mining consortia. Expand hot isostatic pressing capacity in Pittsburgh to capture powder superalloy growth for next-generation blade designs. Lock in 18-24 month dual-source qualification timelines as a competitive moat against emerging Indian competitors.
For New Entrants and Emerging Players: Begin with additive manufacturing repair depots at Singapore and Dubai aviation hubs, where blade tip restoration services face lower certification barriers than flight-critical component supply. Target India's PLI scheme incentives for precision manufacturing investments in Bangalore and Hyderabad industrial corridors. Pursue joint qualification pathways with established metallurgical processors to compress FAA certification timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with powder superalloy atomization specialists given hot isostatic pressing technology convergence for next-generation turbine blade designs. Long-term viability favors operators with integrated vacuum induction melting and closed-loop recycling capabilities. Watch for India's DGFT export promotion frameworks accelerating domestic capability buildup as an inflection signal for geographic supply shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Recycling | REACH-compliant closed-loop systems reduce cobalt and rhenium feedstock exposure for vacuum induction melting operators. |
| Hot Isostatic Pressing Capacity Expansion | Pittsburgh-based HIP installations serve powder superalloy densification demand from Connecticut and Ohio engine OEMs. |
| Dual-Source Qualification Investment | Parallel FAA certification pathways lock incumbent supplier relationships against emerging precision casting competitors. |
| Additive Manufacturing Repair Depot Deployment | Laser powder bed fusion cells at Singapore and Dubai aviation hubs collapse blade tip restoration lead times. |
| PLI Scheme Manufacturing Investment | India's production-linked incentives attract superalloy processing capacity to Bangalore and Hyderabad corridors. |
Research Approach
Document review covered SEC 10-K filings from metallurgical processors, ECHA REACH compliance databases, FAA airworthiness directives, and customs trade data, complemented by interviews with vacuum induction melting plant managers, aerospace engine OEM procurement leads, precision foundry technical directors, and aftermarket MRO service heads. Primary fieldwork across Connecticut, Ohio, Munich, and Pittsburgh clusters validated secondary data on capacity utilization and qualification timelines. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Historical production volume trajectories cross-referenced against expert panel inputs on technology adoption curves. Segmentation modeling spanned product form, application temperature threshold, end-use industry procurement pattern, and fabrication technology maturity. CAGRs derived from regression analysis against nickel price futures, engine OEM order backlogs, and defense procurement budget trajectories. Powder superalloy penetration rates and additive manufacturing repair adoption curves served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; wrought superalloy bar stock carries tighter precision than emerging powder metallurgy categories given established production reporting. Forecasts reflect assumptions on FAA certification timeline stability, REACH enforcement consistency, and cobalt supply chain integrity. Deviation in gamma-prime phase control workforce availability or Indian PLI scheme implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Cobalt Alloy Powder Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Lithium Nitride Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Maraging Steel Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Brazing Alloys Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Global Noble Ferroalloys Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Master Alloys Market