
 Long Steel Market | 2026-2036
Long Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Long Steel Market Intelligence
ISO 9001 certification is unwinding as a baseline gatekeeper rather than a differentiator, separating mills capable of consistent quality documentation from commodity traders. HBIS Group leverages its captive iron-ore and coking-coal assets to sustain cost leadership across rebars and wire rods. ArcelorMittal anchors European long-steel supply through its electric-arc-furnace network, while JSW Steel dominates Indian merchant-bar output via its Dolvi and Vijayanagar complexes.
Long steel encompasses elongated rolled products—rebars, merchant bars, wire rods, structural sections, and rails—typically manufactured through continuous casting followed by hot rolling, with carbon content ranging from 0.15% to 0.80% depending on grade and ductility requirements. These products carry tensile loads, reinforce concrete matrices, and form skeletal frameworks for bridges, buildings, and transport systems. Rebars command the largest revenue pool due to construction-volume scale, though high-strength steel grades are capturing margin expansion as engineering specifications tighten for seismic zones and heavy machinery. Infrastructure applications outpace shipbuilding in absolute tonnage terms, while power-transmission towers increasingly specify microalloyed grades for weight reduction.
China's MEE enforces emissions-intensity caps that favor scrap-based EAF routes over blast-furnace production, while the EU's CBAM imposes carbon-border charges on imported long-steel products beginning with embedded-emissions reporting. India's BIS mandates IS 1786 certification for earthquake-resistant rebar, directly shaping product-mix decisions at domestic mills. Stakeholders must monitor how divergent carbon-accounting rules between Beijing, Brussels, and New Delhi reshape sourcing economics and mill-location strategy.
Market Dynamics
The Long Steel Market is experiencing a fundamental restructuring as carbon-accounting frameworks in Beijing, Brussels, and New Delhi simultaneously redirect capital toward scrap-based electric-arc-furnace production while penalizing traditional blast-furnace routes.
Growth Catalysts
- India's PLI scheme for specialty steel:Production-linked incentives are channeling investment toward high-strength rebar and wire rod grades for infrastructure buildouts.
- EU CBAM carbon-border adjustments:Embedded-emissions reporting requirements are creating competitive advantage for mills with verified low-carbon production methods.
- Seismic engineering codes:Earthquake-resistant construction standards in Southeast Asian megacities are specifying microalloyed rebar grades with enhanced ductility.
Market Restraints
- Iron ore and coking coal price volatility:Input cost swings for blast-furnace operators compress margin predictability and complicate long-term contracting.
- Scrap supply concentration in developed economies:EAF feedstock availability clusters in North American and European industrial corridors, constraining greenfield EAF deployment elsewhere.
- High-strength grade technical barriers:Precise vanadium and niobium microalloying requirements demand metallurgical expertise that remains scarce outside integrated research mills.
Strategic Opportunities
- Vietnam and Indonesia infrastructure corridors:Underpenetrated Southeast Asian construction markets offer first-mover positioning for rebar and structural section suppliers.
- Power-transmission tower lightweighting:Microalloyed angle sections are displacing conventional grades in high-voltage grid expansion projects.
- Digital twin integration with rolling mill control:Real-time process optimization is converging with predictive maintenance to yield yield-rate improvements and energy savings.
Industry Challenges
- Metallurgical talent pipeline gaps:Specialized process engineers for EAF transition and microalloying design remain in short supply across emerging production centers.
- Multi-jurisdiction certification complexity:Simultaneous compliance with China's GB standards, India's BIS mandates, and EU CE marking extends product qualification timelines.
- Legacy blast-furnace asset stranding:Capital-intensive retrofit decisions confront mills with sunk-cost dilemmas amid diverging regional carbon regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long Steel Market |
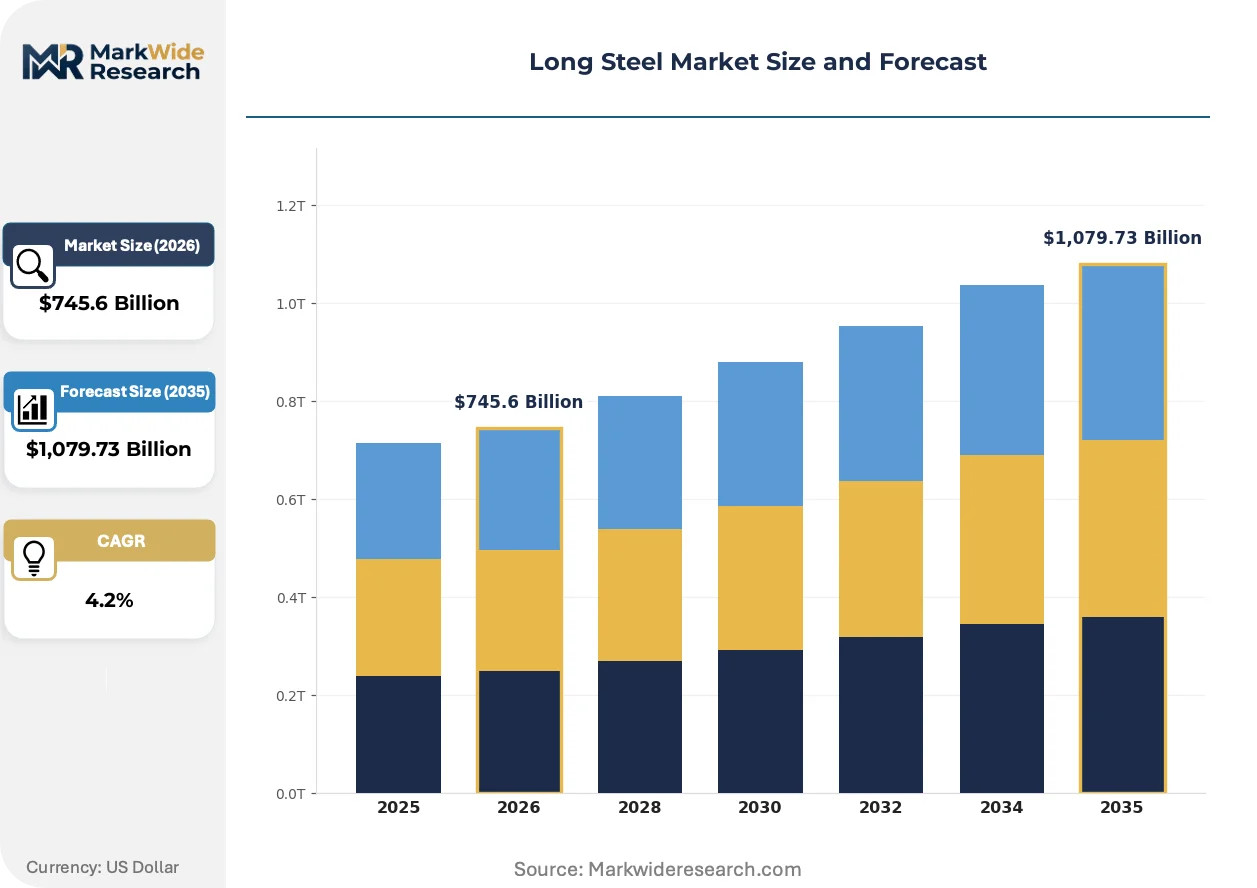
| Market Size in 2026 | $745.6 Billion |
| Market Size in 2035 | $1,079.73 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rebars, Merchant Bars, Wire Rods, Structural Sections, Rails Application: Infrastructure, Shipbuilding, Railways, Power Transmission, Heavy Machinery End User: Construction Firms, Shipyards, Rail Operators, Electrical Utilities, Equipment Manufacturers Steel Grade: Carbon Steel, Alloy Steel, Mild Steel, High Strength Steel, Microalloyed Steel |
| Companies Covered | POSCO Holdings, HBIS Group, China Baowu Group, Jianlong Group, Shagang Group, ArcelorMittal, Ansteel Group, JSW Steel, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long Steel Market Strategic Shifts & Innovations
Digital process control and emissions-verification technologies are compressing production economics while fragmenting procurement relationships across the Long Steel Market value chain.
Quenching and self-tempering (QST) thermomechanical processing is miniaturizing the microstructural grain size in high-strength rebar, delivering 500 MPa yield strengths with reduced alloy content. Bridge and high-rise contractors in seismic zones are specifying QST grades for ductility performance. The technology is compressing the cost premium between standard and high-performance grades.
China's MEE emissions-intensity caps are forcing mill operators to document carbon output per ton or face production curtailments. The policy is accelerating EAF capacity additions and scrap-import quota negotiations. Domestic construction-grade rebar output is feeling the most acute compliance pressure.
Buyers are consolidating annual tonnage into fewer, larger contracts with embedded carbon-disclosure requirements. Engineering-procurement-construction firms are displacing spot-market traders as the primary volume aggregators. India and Vietnam show the most pronounced concentration of procurement authority among national infrastructure agencies.
Long Steel Market Segmentation
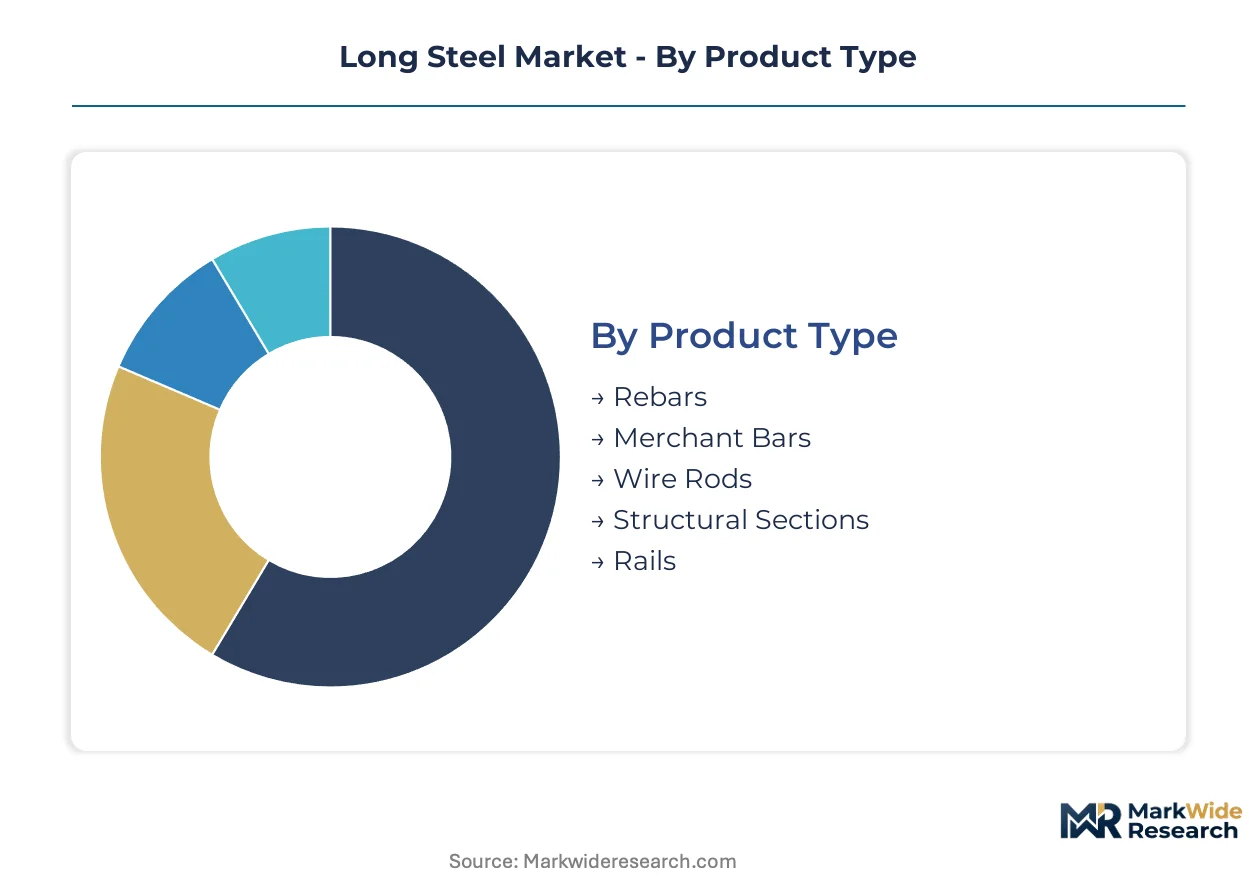
Channel economics in long steel diverge sharply by product geometry and certification burden. Rebar and merchant bars flow through construction-procurement aggregators, while structural sections and rails demand direct mill relationships with engineering-procurement-construction firms.
Product Type:
Distribution intensity varies with dimensional complexity and testing requirements, shaping whether segments reach end-users through distributors or direct mill contracts.
- Rebars:Ribbed steel bars with surface deformations for concrete bonding, typically 6-50mm diameter, manufactured through hot rolling with controlled cooling. Demand clusters in Indian national highway and metro-rail buildouts, where BIS IS 1786 certification for earthquake-resistant grades is mandatory. Procurement concentrates with state infrastructure agencies issuing multi-year framework agreements.
- Merchant Bars:Rounds, flats, angles, and channels serving general fabrication and secondary manufacturing. Shipbuilding yards in Vietnam and Indonesia absorb merchant bar tonnage for hull framing and deck structures, with specifications tightening for weldability and dimensional tolerance.
- Wire Rods:Coiled products drawn into wire for fasteners, mesh, and cable armoring. Cold heading and drawing operations in China's manufacturing clusters consume high-carbon grades for automotive and industrial applications.
- Structural Sections:I-beams, H-beams, and wide-flange profiles carrying axial and bending loads in skeletal frameworks. Bridge contractors in seismic zones specify QST-processed grades for ductility performance under cyclic loading.
- Rails:Heavy sections for railway track infrastructure, requiring controlled chemistry for wear resistance and fatigue life. Rail operators in India and Southeast Asia specify head-hardened grades for high-axle-load corridors.
Rebars dominate installed base. Structural sections are where expansion concentrates.
Application:
Cost tier stratification separates commodity-grade from performance-specified tonnage, with premium margins attaching to seismic and lightweighting applications.
- Infrastructure:Bridges, highways, tunnels, and urban transit systems absorbing the largest absolute tonnage. Southeast Asian megaprojects specify microalloyed rebar grades for seismic resilience, with procurement authority concentrating in national infrastructure agencies.
- Shipbuilding:Hull structures, deck plating, and outfitting applications requiring certified notch toughness and through-thickness ductility. Korean and Chinese yards specify TMCP-processed sections for container vessel construction.
- Railways:Track infrastructure, rolling stock frames, and station structures. Indian Rail and Southeast Asian operators are expanding electrified corridors, specifying head-hardened rails and corrosion-resistant structural grades.
- Power Transmission:Lattice towers and substation frameworks requiring high strength-to-weight ratios. Microalloyed angle sections are displacing conventional grades in high-voltage grid expansion across India and Vietnam.
- Heavy Machinery:Crane booms, mining equipment frames, and agricultural implements. Equipment manufacturers specify quenched-and-tempered alloy grades for fatigue-critical components.
Infrastructure commands volume leadership. Power transmission is climbing the fastest.
End User:
Customer type determines contract structure, with public agencies demanding carbon disclosure and private operators prioritizing availability and price predictability.
- Construction Firms:General contractors and specialized infrastructure builders procuring rebar and structural sections through annual framework agreements. India's national highway authority and metro corporations are consolidating procurement into fewer, larger contracts with embedded emissions-reporting requirements.
- Shipyards:Integrated vessel builders specifying certified material with full traceability. Korean and Chinese yards source merchant bars and sections through mill-direct relationships with qualification timelines extending 12-18 months.
- Rail Operators:National railway authorities and urban transit agencies procuring rails and structural sections through tender processes. Indian Rail and Southeast Asian operators specify lifecycle cost criteria including wear rates and maintenance intervals.
- Electrical Utilities:Grid operators and transmission developers sourcing tower sections and substation structures. India's Power Grid Corporation and Vietnam's EVN are specifying microalloyed grades for weight reduction in remote terrain.
- Equipment Manufacturers:OEMs producing mining, material handling, and agricultural machinery. These customers specify alloy grades with precise hardenability bands and through-thickness property requirements.
Construction firms anchor demand volume. Electrical utilities are gaining share fastest.
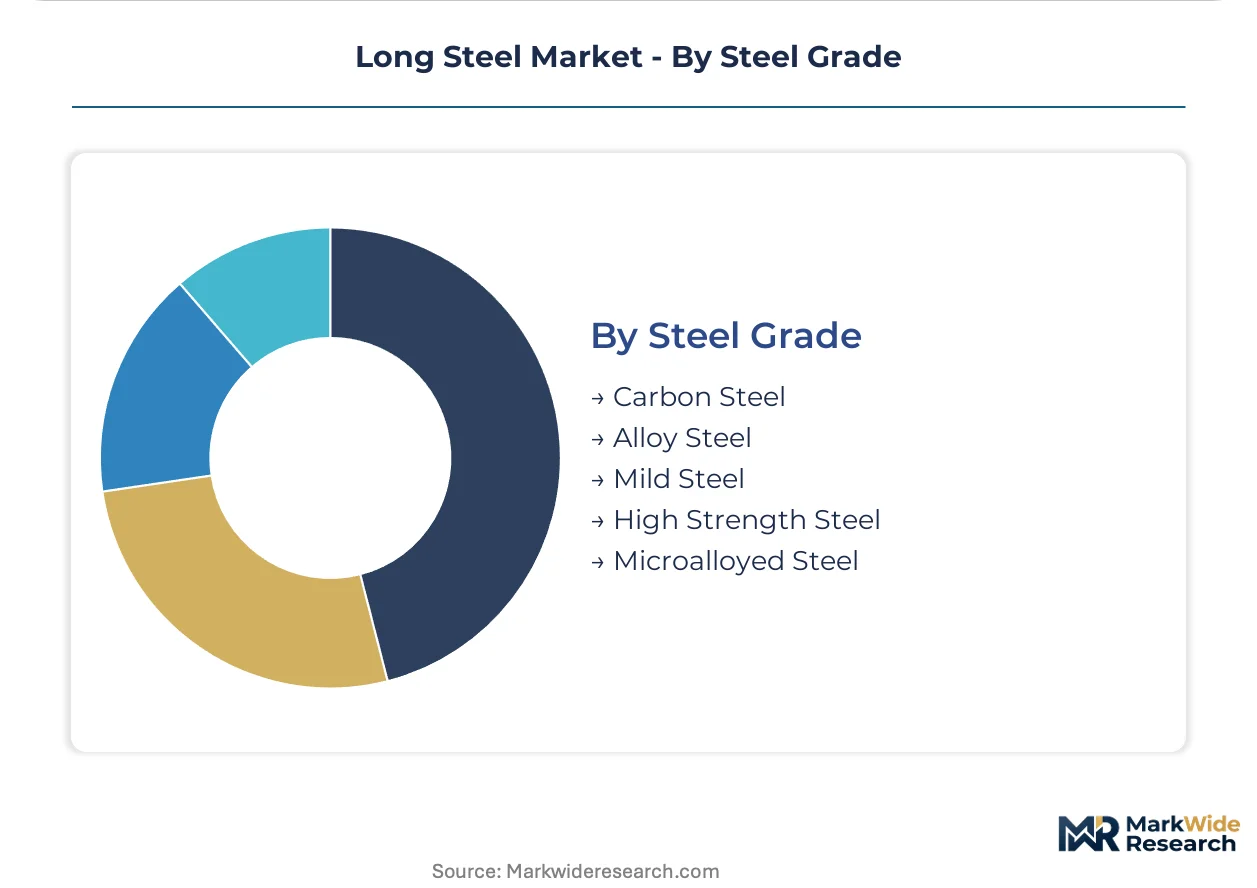
Steel Grade:
Margin structure escalates with metallurgical complexity, from commodity carbon grades to vanadium-microalloyed specifications commanding technical premiums.
- Carbon Steel:Unalloyed grades with carbon content 0.15%-0.80%, produced through basic oxygen or EAF routes. Standard rebar and merchant bar applications in non-seismic construction absorb the largest tonnage at thinnest margins.
- Alloy Steel:Grades with deliberate additions of chromium, nickel, or molybdenum for hardenability and toughness. Heavy machinery and mining equipment specifications demand these grades for fatigue-critical components.
- Mild Steel:Low-carbon grades below 0.25% carbon content, offering excellent formability and weldability. General fabrication and secondary manufacturing in emerging economies consume these grades through distributor channels.
- High Strength Steel:Grades achieving yield strengths above 355 MPa through controlled rolling or heat treatment. Bridge and high-rise contractors in seismic zones specify these grades for column and beam applications.
- Microalloyed Steel:Grades with vanadium or niobium additions below 0.1% achieving strength through grain refinement rather than carbon content. Power transmission towers and lightweight infrastructure applications specify these grades for weight reduction and weldability.
Carbon steel dominates installed base. Microalloyed steel is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE emissions-intensity caps and India's PLI scheme for specialty steel are redirecting investment toward scrap-based EAF routes and high-strength grades. Regulatory divergence between Beijing, Brussels, and New Delhi is fragmenting sourcing economics and mill-location strategy across the value chain.
China
National highway and high-speed rail buildouts absorb record rebar tonnage from Hebei and Jiangsu mill complexes. The MEE enforces carbon-output documentation per ton, accelerating EAF capacity additions in coastal provinces. Tangshan and Zhangjiakou clusters face acute compliance pressure on construction-grade rebar output.
India
Metro-rail and national highway expansion drive sustained procurement of IS 1786-certified earthquake-resistant rebar. The PLI scheme channels investment toward high-strength wire rod grades for infrastructure buildouts. Dolvi and Vijayanagar complexes in Maharashtra and Karnataka dominate merchant-bar output for domestic absorption.
Vietnam
Underpenetrated infrastructure corridors create first-mover positioning for rebar and structural section suppliers. The government prioritizes transport network expansion linking northern industrial zones to central coastal ports. Ho Chi Minh City and Hanoi construction markets specify microalloyed grades for seismic resilience.
Germany
Bridge and high-rise contractors specify QST-processed structural sections for ductility under cyclic loading. The EU CBAM imposes carbon-border charges on imported long-steel products beginning with embedded-emissions reporting. Ruhr industrial corridor mills anchor European long-steel supply through EAF network optimization.
United States
Power-transmission grid expansion specifies microalloyed angle sections for weight reduction in remote terrain. Scrap supply concentration in Great Lakes and Southeast industrial corridors constrains greenfield EAF deployment elsewhere. Texas and Gulf Coast energy infrastructure drives merchant-bar demand for fabrication and secondary manufacturing.
Long Steel Market Key Industry Players
Player mix skews toward integrated steel groups with captive raw-material positions and EAF-based regional specialists with scrap-sourcing advantages. Market structure concentrates around scale-driven producers controlling blast-furnace capacity and emerging low-carbon specialists retrofitting toward electric-arc routes. Two strategic archetypes dominate: vertically integrated miners-to-metals groups with iron-ore and coking-coal assets, and coastal EAF operators leveraging scrap-import logistics. Competitive moves center on capacity relocation toward carbon-regulatory arbitrage and portfolio shifts into high-strength microalloyed grades.
Among East Asian integrated groups, POSCO Holdings, China Baowu Group, and Nippon Steel Corporation exemplify the scale-driven archetype with multi-site mill networks spanning rebar, wire rod, and structural sections. These entities occupy positions where captive raw-material access and continuous-casting scale create defensive moats against input cost volatility. HBIS Group and Ansteel Group represent Chinese state-backed consolidators with dominant positions in construction-grade long products. ArcelorMittal anchors the European competitive set through EAF network density, while JSW Steel exemplifies the emerging-market growth archetype with coastal complex expansion in India.
| Leading Market Players |
|---|
| POSCO Holdings |
| HBIS Group |
| China Baowu Group |
| Jianlong Group |
| Shagang Group |
| ArcelorMittal |
| Ansteel Group |
| JSW Steel |
| Nippon Steel Corporation |
| Others |
Cost & Logistics Intelligence
China's MEE emissions-intensity caps gate both mill qualification and price differentiation simultaneously, forcing blast-furnace operators to absorb carbon-compliance costs while EAF-based producers capture green-steel premiums. This regulatory bifurcation concentrates pricing power with coastal scrap-based mills and fragments procurement economics across regional carbon-accounting regimes.
Pricing Analysis
Certification level creates the primary spread between commodity rebar and seismic-grade microalloyed products. Three-tier pricing structure across premium, standard, and economy levels reflects IS 1786 earthquake-resistance mandates in India, CE marking for EU CBAM compliance, and standard GB-grade construction rebar. Cost compression in commodity carbon grades intensifies because iron ore and coking coal volatility squeezes blast-furnace margins. State infrastructure agencies in India and Vietnam show lowest price sensitivity due to multi-year framework agreements, while spot-market traders in Southeast Asia face acute margin pressure.
Supply Chain Analysis
Container availability constraints on scrap-import routes from North American and European industrial corridors elevate inbound logistics costs for EAF operators in Vietnam and Indonesia. Supply concentrates in China, India, and Vietnam for rebar and structural sections, with merchant bars flowing from Korean and Japanese mill complexes. Raw material dependencies center on iron ore from Australian and Brazilian mining districts, coking coal from Mongolian and Russian sources, and ferrous scrap from developed-economy industrial corridors. Tariff exposure on carbon-intensive imports into the EU under CBAM rules creates structural risk for traditional blast-furnace exporters. Distribution runs through national infrastructure agencies consolidating annual tonnage into direct mill contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-verification services and predictive maintenance contracts are expanding faster than base steel tonnage, creating recurring-revenue layers that outpace hardware margins. Equipment OEMs and EPC firms increasingly bundle emissions-auditing and digital-twin monitoring with structural steel supply.
For Market Incumbents: Compound defensive positioning through captive scrap-sourcing agreements in North American and European corridors, insulating against feedstock concentration risk. Accelerate QST-processed capacity additions to capture seismic-grade premiums as Southeast Asian engineering codes tighten. Counter emerging EAF specialists by locking multi-year offtake with Indian and Vietnamese state infrastructure agencies before greenfield competitors qualify. For New Entrants and Emerging Players: BIS IS 1786 certification fast-track offers entry path into Indian national highway and metro-rail procurement. White-space concentrates in Vietnamese infrastructure corridors where transport network expansion outruns domestic mill capacity, and in Indonesian power-transmission tower lightweighting specifying microalloyed angles. Go-to-market leverage rests on carbon-disclosure transparency that differentiates against legacy blast-furnace incumbents in EU-facing export channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed EAF retrofit specialists holding coastal scrap-import logistics in Vietnam and Indonesia. Long-term viability favors operators with verified low-carbon production methods and qualification timelines already completed for Indian BIS and EU CE marking. Watch for inflection when China's MEE enforcement triggers production curtailments at Tangshan and Zhangjiakou blast-furnace clusters, reallocating regional supply share.| Strategic Initiative | Industry Significance |
|---|---|
| EAF Capacity Expansion | Scrap-based routes capture green-steel premiums under EU CBAM and China's MEE caps. |
| Microalloyed Grade Development | Vanadium and niobium additions meet seismic codes in Ho Chi Minh City and Hanoi construction. |
| Digital Twin Integration | Real-time rolling mill control yields yield-rate improvements and energy savings at Dolvi and Vijayanagar complexes. |
| Scrap Supply Agreements | Long-term offtake from Great Lakes and Southeast US corridors secures EAF feedstock for coastal mills. |
| Carbon Verification Services | Emissions-auditing contracts attach recurring revenue to structural steel framework agreements. |
Research Approach
Cross-validation between mill operator interviews and customs trade data anchors the qualitative findings on regional supply concentration. Primary fieldwork engaged plant managers at integrated steel complexes, procurement leads at Indian and Vietnamese state infrastructure agencies, EPC contractors specifying seismic grades, and aftermarket service heads at rolling mill technology providers. Secondary validation drew from SEC filings of listed steel groups, China customs export records, Indian BIS certification registries, and EU CBAM embedded-emissions documentation. Bottom-up capacity assessments triangulated against top-down demand modeling from national highway and metro-rail project pipelines.
Sensitivity analysis tested forecast outputs against scrap-price volatility bands, carbon-border tariff scenarios, and infrastructure project delay assumptions across the analysis window. Segmentation dimensions modeled include product geometry, steel grade metallurgy, application end-use, and regional regulatory cluster. CAGRs derived from production capacity expansion schedules, national steel consumption intensity ratios, and substitution elasticities between blast-furnace and EAF routes. Forecast inputs incorporated China's MEE enforcement trajectory and India's PLI scheme disbursement pacing.
Decision-makers should treat outputs as directional under base assumptions of sustained infrastructure buildout and progressive carbon-regulatory tightening; material deviation in scrap supply availability or trade policy would warrant model refresh. Practitioners should keep alternative scenarios live as Beijing's dual carbon implementation pace and Brussels' CBAM phase-in mechanics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Glass Facade Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Steel Sleepers Market
Building Materials
Polymer Concrete Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Plaster Accelerator Market
Building Materials
Earthen Plasters Market
Building Materials
Granite Market
Building Materials
Global Fiber Cement Siding Market