
 North America Building and Construction Sheets Market | 2026-2036
North America Building and Construction Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
North America Building and Construction Sheets Market Analytics
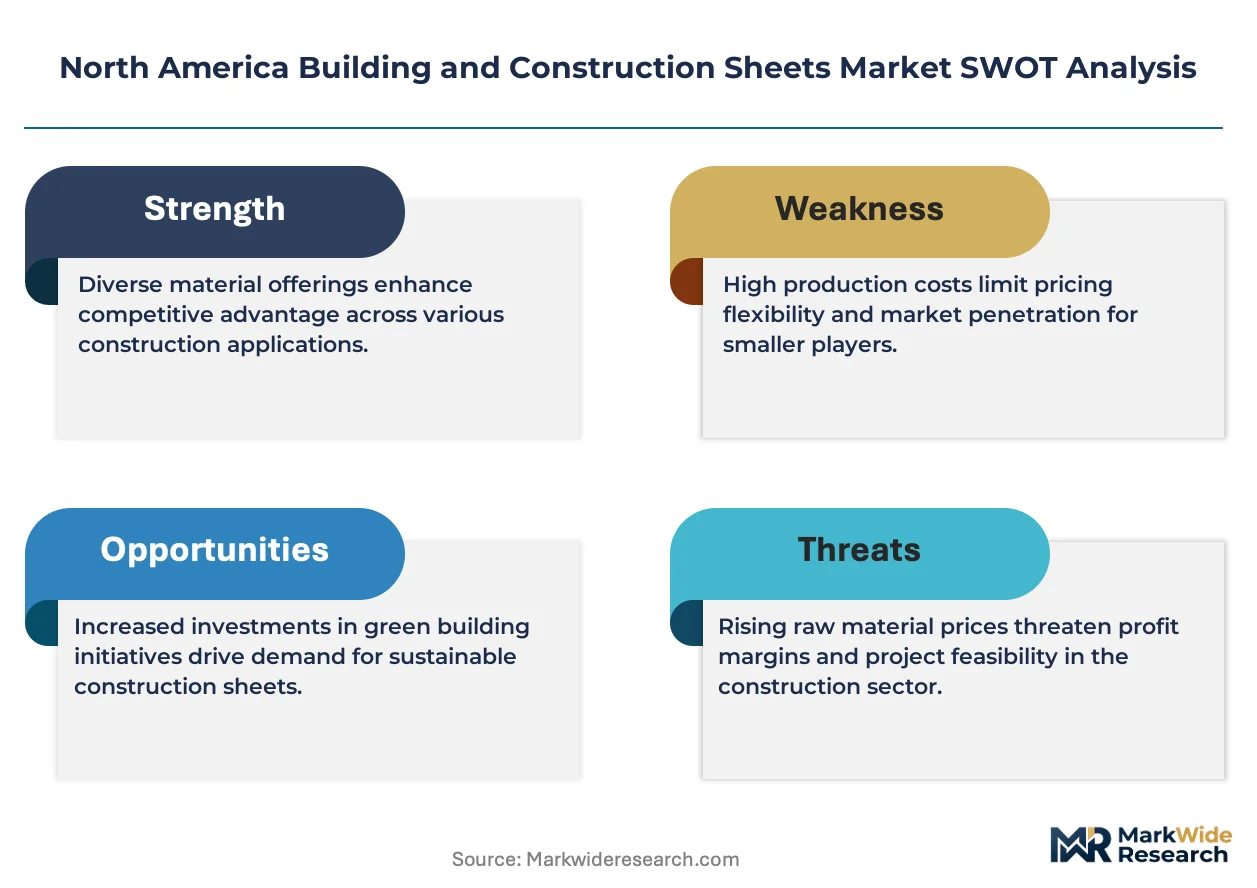
Skilled carpentry and construction craft labor availability is rotating unevenly across North America, constraining project timelines in high-growth corridors while elevating demand for prefabricated sheet systems that reduce on-site labor hours. United States Gypsum Company leverages its integrated gypsum board manufacturing network to sustain supply continuity across major metropolitan zones. Johns Manville Corporation anchors its position through mineral wool and fiberglass sheet specialization for commercial envelope applications. Owens Corning Corporation competes via technology leadership in composite roofing and wall panel systems engineered for thermal performance.
Building and construction sheets encompass flat panel materials manufactured to precise dimensional tolerances for structural, protective, or finish applications in built environments; these products typically range from 4-by-8-foot standard dimensions to engineered custom sizes, with thickness specifications calibrated to load-bearing, moisture resistance, or fire-rating requirements. Their primary purpose spans subfloor decking, roof sheathing, interior wall surfacing, and exterior cladding substrates across residential and non-residential construction. Wood-based panels including OSB and plywood dominate volume flows in residential framing, though composite and plastic sheet categories are capturing margin pools in moisture-critical commercial applications. Metal sheet demand concentrates in institutional and industrial roofing segments where lifecycle durability outweighs first-cost considerations.
EPA oversees formaldehyde emission standards under the Toxic Substances Control Act, directly governing composite wood product imports and domestic manufacturing. OSHA construction safety standards influence handling protocols and installation practices for heavy sheet goods on active job sites. Building codes adopted at state and municipal levels across the United States and Canadian provinces incorporate ICC and NBCC fire-resistance ratings that determine product eligibility for multi-story and egress applications. Stakeholders must monitor code harmonization pressures between US and Canadian jurisdictions alongside emerging embodied carbon disclosure requirements that threaten to disqualify carbon-intensive sheet manufacturing processes from publicly funded projects.
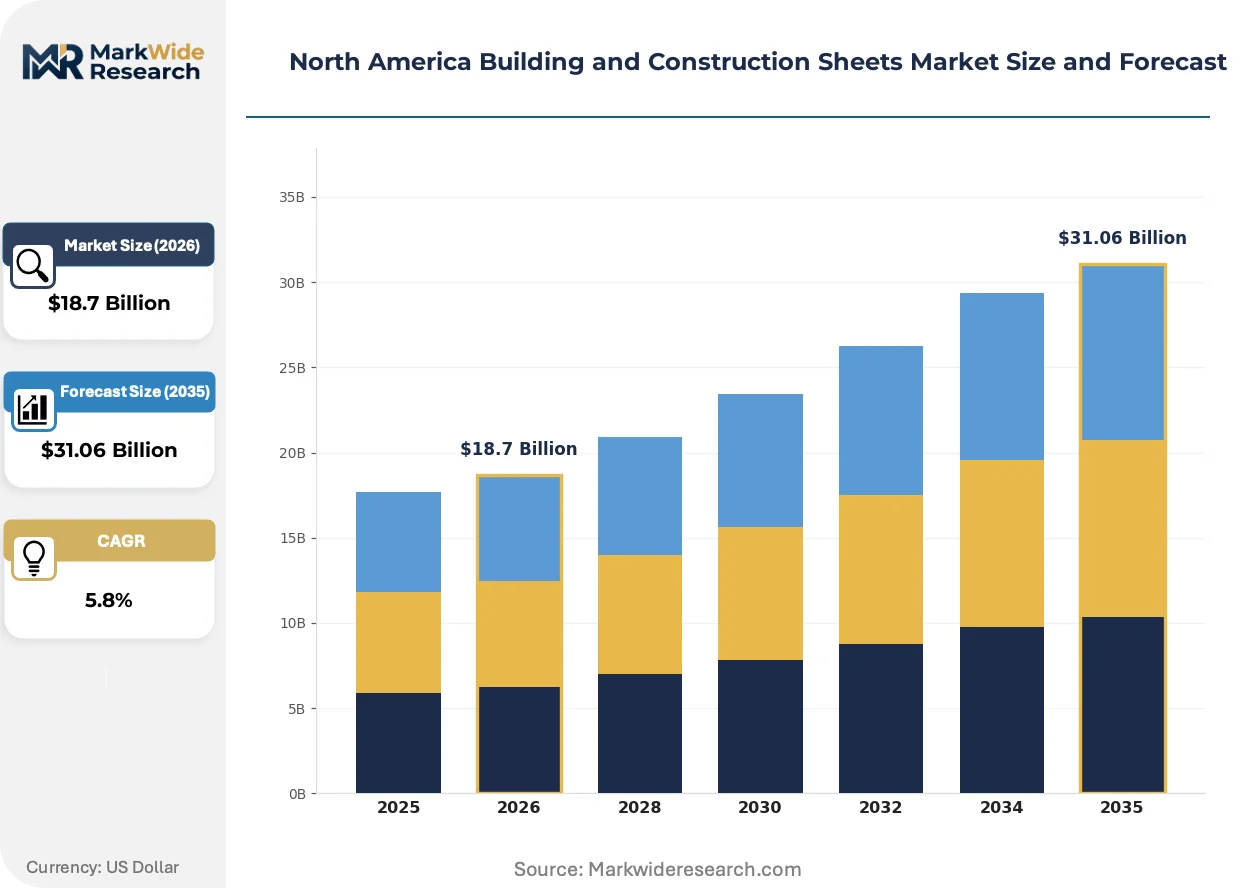
Market Dynamics
Residential retrofit activity across the United States is accelerating uptake of engineered wood and composite panel systems, tightening material specifications and reshaping supplier qualification requirements as EPA formaldehyde emission standards and evolving green building codes take hold.
Growth Catalysts
- EPA Formaldehyde Emission Standards:The Toxic Substances Control Act mandates strict limits on composite wood products, forcing domestic manufacturers and importers to upgrade adhesive formulations and testing protocols.
- Southern United States Migration:Population inflows into Texas, Florida, and Georgia are driving warehouse construction and multifamily housing starts, concentrating sheet goods demand in high-growth corridors.
- Prefabricated Panel Systems:Skilled carpentry shortages are elevating demand for factory-built wall and floor assemblies that compress on-site installation timelines.
Market Restraints
- Oriented Strand Board Price Volatility:Fluctuating timber feedstock costs and mill capacity constraints create margin compression for residential framing contractors.
- Gypsum Board Supply Concentration:United States Gypsum Company's integrated manufacturing network dominates major metropolitan zones, limiting alternative sourcing options during regional disruptions.
- Fire-Rating Technical Limitations:Standard wood-based panels face height restrictions under ICC fire-resistance ratings for multi-story egress applications.
Strategic Opportunities
- Canadian Cross-Laminated Timber:British Columbia and Quebec producers are expanding CLT capacity to capture U.S. commercial mid-rise construction seeking carbon-sequestering alternatives.
- Infrared-Reflective Roofing Sheets:Owens Corning's thermal performance technology convergence with cool roof mandates in California and Arizona creates specification advantages.
- Direct-to-Contractor Digital Channels:Building material distributors are launching e-commerce platforms that bypass traditional two-step distribution for large-volume commercial buyers.
Industry Challenges
- OSHA Heavy Lift Certification:Active job sites face compliance delays as sheet goods handling protocols require updated crane operator and rigging credentials.
- Embodied Carbon Disclosure Timelines:Publicly funded projects in California and New York are imposing data collection requirements that most suppliers cannot meet without third-party verification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Building and Construction Sheets Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, MDF, OSB, PVC End User: Residential, Commercial, Industrial, Institutional Material: Wood, Metal, Plastic, Composite Application: Flooring, Roofing, Wall Panels, Ceilings |
| Companies Covered | United States Gypsum Company, Johns Manville Corporation, CertainTeed LLC, Owens Corning Corporation, Atlas Roofing Corporation, Etex, National Gypsum Services Company, Spartech Corporation, GAF, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Building and Construction Sheets Market Evolving Landscape
Material science advances and procurement model evolution are compressing traditional specification cycles, forcing sheet manufacturers to demonstrate performance data earlier in the design phase.
Cross-laminated timber is supplanting steel and concrete in five-to-twelve-story commercial structures across the Pacific Northwest and Mountain West. Architects specify mass timber for its sequestration credentials and exposed aesthetic. The shift is compressing structural engineering timelines and requiring new fire-testing methodologies.
California's Title 24 Building Energy Efficiency Standards now mandate solar-ready roofing substrates for new commercial construction. The regulation forces membrane and composite panel suppliers to pre-certify compatibility with photovoltaic mounting systems. Warehouse developers in the Inland Empire are prioritizing single-ply TPO sheets with pre-attached insulation to meet accelerated permitting.
General contractors in Texas and Florida are consolidating purchase orders through cooperative purchasing organizations that aggregate volume across multiple development sites. This behavior fragments traditional distributor relationships and compresses payment terms to net-15. The model is most visible in build-to-rent residential verticals where institutional ownership favors standardized material packages.
North America Building and Construction Sheets Market Segmentation
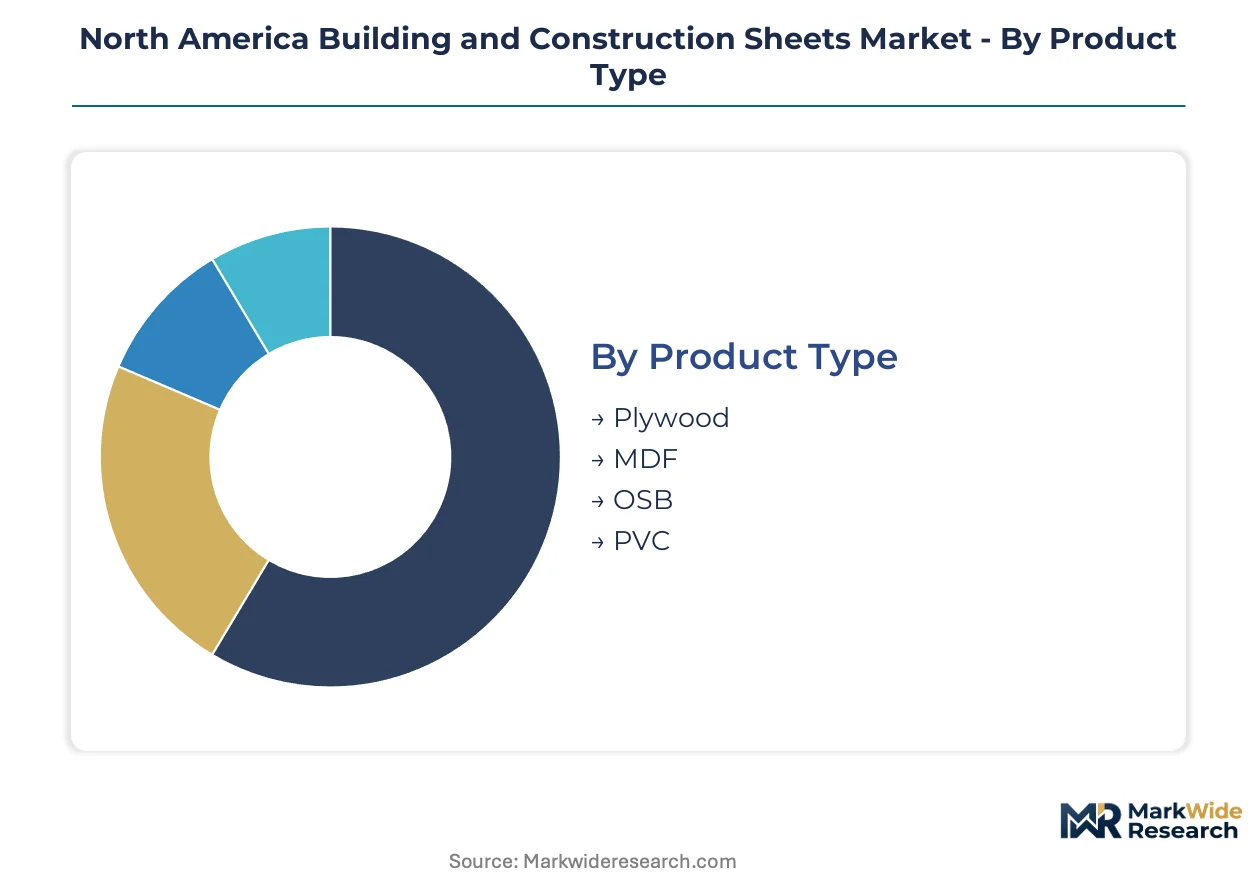
Material specification hierarchies in North American construction sheets diverge sharply across regulatory jurisdictions, with EPA formaldehyde rules, ICC fire-rating protocols, and state-level energy codes creating non-uniform qualification barriers. Procurement teams segment supplier portfolios by compliance tier rather than commodity grade alone.
Product Type:
EPA Toxic Substances Control Act emission limits and state-adopted green building codes differentiate composite panel eligibility across residential and commercial verticals.
- Plywood:Cross-laminated veneer construction delivers dimensional stability under cyclic moisture loading. Southern United States multifamily framing contractors specify structural plywood for subfloor assemblies where ICC ESR-1780 evaluation reports govern acceptance.
- OSB:Oriented strand board manufacturers press wood strands with phenol-formaldehyde or MDI binders to achieve structural parity at lower fiber input. Texas and Florida warehouse builders favor OSB roof sheathing for cost-engineered tilt-wall construction, though price volatility tied to timber feedstock availability constrains bid reliability.
- MDF:Medium-density fiberboard offers uniform surface density for millwork and interior finish applications; California CARB Phase 2 compliance thresholds restrict MDF specification in school and healthcare projects.
- PVC:Rigid polyvinyl chloride sheet systems deliver moisture immunity for exterior trim and soffit applications; Florida coastal jurisdictions specify PVC for hurricane-resistant envelope detailing.
Established volume favors OSB; emerging adoption favors PVC.
End User:
Project delivery timelines and specification authority concentrate demand patterns across customer archetypes.
- Residential:Single-family builders and multifamily developers drive commodity panel consumption through platform framing and factory-built component sourcing. Prefabricated wall panel adoption accelerates in Sun Belt corridors where carpentry labor scarcity compresses on-site schedules.
- Commercial:Office, retail, and hospitality developers specify fire-rated gypsum and composite panels under ICC IBC Chapter 26 envelope requirements. California Title 24 energy standards mandate solar-ready roofing substrates that filter membrane supplier qualification.
- Industrial:Warehouse and distribution center construction concentrates in Dallas-Fort Worth, Atlanta, and Phoenix metro zones, demanding high-span roof sheathing with reflective thermal performance.
- Institutional:School, hospital, and government projects impose prevailing wage, domestic content, and embodied carbon disclosure requirements that disqualify standard commodity suppliers.
Procurement concentration favors Residential; specification complexity favors Institutional.
Material:
Feedstock geography and manufacturing energy intensity shape regional supply positioning.
- Wood:Pacific Northwest and Southeastern softwood harvests supply OSB and plywood mills; British Columbia cross-laminated timber producers target U.S. commercial mid-rise verticals.
- Metal:Steel and aluminum roofing sheets dominate institutional and industrial segments where lifecycle durability outweighs first-cost premiums; Galvalume-coated substrates prevail in Arizona and Nevada solar installations.
- Plastic:PVC and polycarbonate sheet demand concentrates in moisture-critical envelope applications and translucent daylighting systems.
- Composite:Fiberglass-reinforced and mineral-fiber panels capture commercial envelope specifications requiring thermal resistance and fire containment in single assemblies.
Cost engineering favors Wood; performance specification favors Composite.
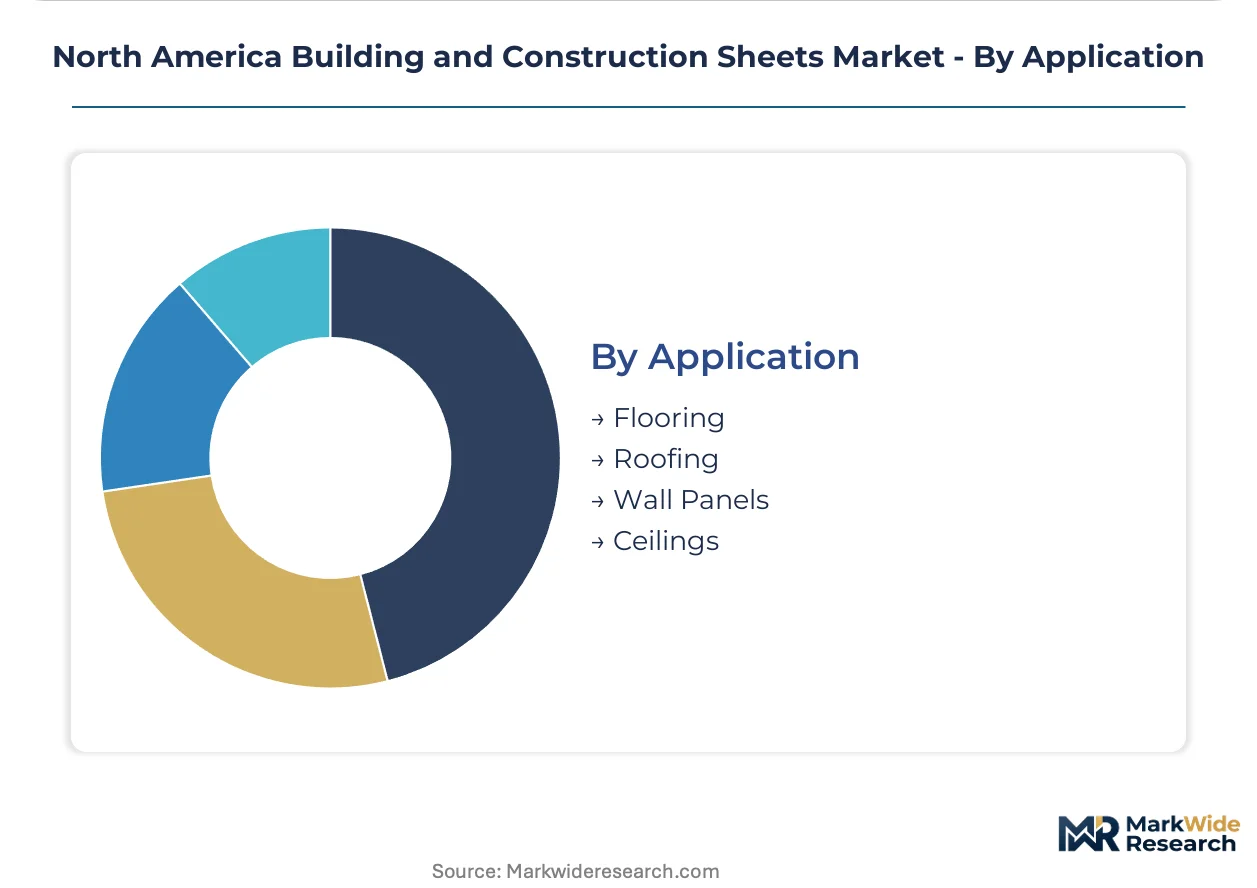
Application:
Structural loading, moisture exposure, and fire-rating requirements partition product selection by building system.
- Flooring:Subfloor decking specifications prioritize stiffness and fastener-holding capacity; AdvanTech and comparable engineered panels displace commodity OSB in high-end residential.
- Roofing:Sheathing, underlayment, and membrane systems face accelerated code evolution in California and Florida; TPO single-ply sheets with pre-attached insulation streamline Inland Empire warehouse permitting.
- Wall Panels:Structural sheathing, exterior cladding substrates, and interior finish boards span the widest material range; mass timber wall systems gain share in Pacific Northwest commercial construction.
- Ceilings:Acoustic tile and gypsum ceiling board demand concentrates in commercial tenant improvement cycles; mineral fiber specialization anchors Johns Manville positioning.
Volume scale favors Wall Panels; margin expansion favors Roofing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA formaldehyde emission standards under the Toxic Substances Control Act govern composite wood product manufacturing across the United States, while Canadian provinces operate under parallel but non-identical regulatory frameworks administered by Health Canada.
United States
Population migration into Texas, Florida, and Georgia accelerates warehouse construction and multifamily housing starts. OSHA construction safety standards mandate updated crane operator credentials for heavy sheet goods handling on active job sites. Dallas-Fort Worth and Atlanta metro zones concentrate demand for high-span roof sheathing with reflective thermal performance.
Canada
British Columbia and Quebec cross-laminated timber producers expand capacity to supply U.S. commercial mid-rise construction seeking carbon-sequestering alternatives. Health Canada and PMRA oversee chemical emissions and product safety standards for imported and domestic building materials. Vancouver and Montreal anchor mass timber engineering clusters serving Pacific Northwest and Northeast U.S. markets.
Mexico
Manufacturing investment in Nuevo León and Baja California generates demand for industrial roofing and wall panel systems in assembly plant construction. Mexico's federal consumer protection agency PROFECO monitors building material quality standards alongside local building codes. Monterrey industrial corridors absorb gypsum board and metal sheet imports for commercial envelope applications.
California
Title 24 Building Energy Efficiency Standards mandate solar-ready roofing substrates for new commercial construction, filtering membrane supplier qualification. California Air Resources Board Phase 2 compliance thresholds restrict medium-density fiberboard specification in school and healthcare projects. Inland Empire warehouse developers prioritize single-ply TPO sheets with pre-attached insulation to meet accelerated permitting timelines.
North America Building and Construction Sheets Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American building and construction sheets market. Integrated gypsum manufacturers dominate major metropolitan supply zones through captive raw material sourcing and distribution infrastructure. The competitive terrain separates into three archetypes: mineral-fiber specialists, composite panel technology leaders, and commodity-oriented strand board producers. Capacity consolidation and direct-to-contractor digital channel development represent the dominant competitive moves reshaping traditional two-step distribution.
Within the integrated manufacturing tier, United States Gypsum Company and National Gypsum Services Company exemplify scale-driven supply continuity models across major U.S. metropolitan zones. Owens Corning Corporation occupies a position representing technology-forward composite systems specialization. Johns Manville Corporation anchors the mineral wool and fiberglass sheet segment for commercial envelope applications. These three entities illustrate divergent strategic postures: captive gypsum sourcing, thermal performance engineering, and commercial specification depth respectively.
| Leading Market Players |
|---|
| United States Gypsum Company |
| Johns Manville Corporation |
| CertainTeed LLC |
| Owens Corning Corporation |
| Atlas Roofing Corporation |
| Etex |
| National Gypsum Services Company |
| Spartech Corporation |
| GAF |
| Others |
Value Network & Pricing Analysis
Mill-scale capacity utilization across southeastern OSB producers shapes both regional supply concentration and floor pricing for structural panels. Texas and Florida warehouse developers face compressed bid windows when timber feedstock volatility triggers mill curtailments, forcing contractors toward pre-negotiated annual contracts that sacrifice flexibility for cost predictability.
Pricing Analysis
Geographic price spreads between Pacific Northwest plywood mills and southeastern OSB producers widen during peak construction seasons, reflecting freight differentials and regional demand surges. Three-tier pricing structure across premium engineered panels, standard commodity OSB, and economy-grade sheathing separates performance-certified products from untreated alternatives. Cost compression in standard OSB runs through timber feedstock volatility and resin cost spikes. Residential framing contractors exhibit highest price sensitivity, while institutional buyers prioritize fire-rating certification over unit cost.
Supply Chain Analysis
The United States and Canada anchor North American panel manufacturing, with British Columbia cross-laminated timber producers and southeastern U.S. OSB mills feeding distinct end-use segments. Production draws from Pacific Northwest and southeastern softwood harvests, phenol-formaldehyde and MDI resin systems, and gypsum rock deposits concentrated in Oklahoma and Nova Scotia. Single-source vulnerability concentrates in United States Gypsum Company's integrated metropolitan distribution networks. Distribution runs through two-step building material distributors, though direct-to-contractor digital platforms are fragmenting traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified mass timber engineering talent constrains specification velocity for cross-laminated timber systems, creating asymmetric capture opportunities for firms that bridge design-assist capabilities with manufacturing scale.
For Market Incumbents: Secure captive gypsum sourcing through lease arrangements with Oklahoma and Nova Scotia mineral rights holders to insulate against raw material disruption. Defend specification position by embedding fire-testing documentation earlier in architect design phases, countering emerging composite panel substitutes that threaten traditional gypsum board share in commercial mid-rise verticals.
For New Entrants and Emerging Players: EPA TSCA certification fast-track through third-party testing laboratories offers entry pathway into California and New York school construction, where formaldehyde emission restrictions disqualify standard commodity suppliers. Target infrared-reflective roofing membrane segments in Arizona and Nevada, where Title 24 cool roof mandates create specification pull without entrenched incumbent relationships. Lead with solar-ready substrate compatibility to bypass traditional two-step distribution.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mineral-fiber specialists with established commercial envelope specification depth over commodity-oriented strand board producers facing structural margin compression. Five-to-ten-year viability hinges on embodied carbon disclosure readiness, with acquisition focus on firms possessing third-party verified EPDs and Health Product Declarations. Watch California Buy Clean procurement mandates as inflection indicator for carbon-intensive manufacturing process disqualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive phenol-formaldehyde supply insulates OSB manufacturers against petrochemical cost volatility. |
| Mass Timber Engineering Certification Program | CLT producers in British Columbia and Quebec accelerate U.S. commercial specification through design-assist capabilities. |
| Direct-to-Contractor Digital Platform Launch | E-commerce bypass of traditional distribution compresses payment terms and fragments incumbent channel control. |
| Embodied Carbon Disclosure System Investment | Third-party EPD verification positions suppliers for California and New York publicly funded project eligibility. |
| Solar-Ready Roofing Substrate Pre-Certification | Membrane compatibility with photovoltaic mounting systems filters supplier qualification under Title 24 standards. |
Research Methodology
The analysis maps engineered wood panels, gypsum board systems, mineral-fiber commercial envelopes, and composite roofing substrates, each validated through plant managers at OSB and plywood mills, procurement leads at national homebuilders, distribution channel partners, and specification writers at commercial architecture firms. Primary interview findings triangulate against customs and trade data, EPA TSCA compliance filings, SEC 10-K disclosures from listed building material manufacturers, and ICC-ES evaluation report databases. Bottom-up volume estimates from mill capacity and utilization rates reconcile with top-down construction spending allocations across residential, commercial, and institutional verticals.
Consistency checks against McGraw-Hill Construction Dodge data, Census Bureau construction spending reports, and Forest Economic Advisors timber product forecasts validate volume and value outputs across the projection horizon. The analytical framework segments by material type, end-use vertical, application system, and regional regulatory cluster, with CAGRs derived from regression modeling of historical construction starts against panel consumption intensity. Forecast inputs incorporate skilled labor availability indices, green building code adoption timelines, and cross-laminated timber capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained southern U.S. population migration, stable timber harvest access, or continued EPA formaldehyde enforcement would require recalibration. Forecasts reflect documented assumptions regarding material substitution rates and code harmonization pressures. Recalibration cycles align with material shifts in embodied carbon disclosure mandates and mass timber fire-testing methodology evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Pozzolan Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Natural Stone Market
Building Materials
Europe Fiber Cement Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
Drywall Joint Tape Market
Building Materials
Europe Cement Market
Building Materials
China Cement Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Blind Bolts Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Steel Products Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
North America Architectural Coatings Market
Building Materials
Global Glass Fiber Reinforced Concrete Market