
 Mexico Architectural Coatings Market | 2026-2036
Mexico Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Architectural Coatings Market Foresight
Buyer concentration among Mexico's largest property developers is consolidating specification power across residential and commercial projects. The Sherwin-Williams Company leverages its distribution network to sustain national coverage in tier-one and tier-two cities. PPG Industries Inc. anchors its position through manufacturing scale at its Monterrey operations, while Corev de México differentiates via specialized water-based formulations for the central Mexico climate.
Mexico architectural coatings encompass pigmented liquid and powder systems applied to building substrates for protection, decoration, and functional performance, with water-based acrylic emulsions typically containing 30-50% solids by volume and achieving dry-film thickness of 2-4 mils per coat. These formulations serve to extend building envelope durability against UV degradation, moisture intrusion, and thermal cycling in subtropical to arid climate zones. Exterior coatings lead volume due to Mexico's intense solar exposure and monsoon patterns, while water-based technology captures expanding share as solvent-based systems face tightening volatile organic compound limits. Primers represent a concentrated margin pool where contractors prioritize substrate adhesion assurance over unit cost.
SEMARNAT enforces environmental compliance through NOM-085-SEMARNAT-2011 limiting VOC emissions in architectural coatings, while PROFECO monitors labeling accuracy under consumer protection statutes. The national standardization body certifies product quality under NMX standards that builders reference in public procurement. Stakeholders must monitor forthcoming amendments to Mexico's General Law of Climate Change that will likely extend carbon accounting requirements to imported resin feedstocks.
Market Dynamics
Buyer consolidation among Mexico's largest property developers is compressing specification cycles and tilting procurement power toward volume-scale contractors who demand technical compliance documentation and extended warranty terms.
Growth Catalysts
- NOM-001-SECRE-2010:Tightening thermal performance standards for exterior building envelopes are mandating higher-specification coatings in new residential towers across Jalisco and Nuevo León.
- Water-based emulsion technology:Reformulation investments are capturing specification share as SEMARNAT enforcement of VOC limits accelerates solvent system phase-out in commercial renovation projects.
- Monsoon-driven substrate protection:Intensifying precipitation patterns in Mexico City's metropolitan corridor are extending recoating cycles and expanding primer volumes for moisture-resistant envelope systems.
Market Restraints
- Petrochemical resin feedstock volatility:Acrylic emulsion costs fluctuate with imported propylene derivatives, compressing margin stability for domestic formulators serving price-sensitive contractor segments.
- Concentrated import dependency:Specialty additives and titanium dioxide supply routes through Veracruz port infrastructure create bottleneck exposure during customs clearance surges.
- Climate-zone formulation fragmentation:Subtropical coastal humidity versus central plateau aridity forces SKU proliferation that dilutes production run efficiency for national distributors.
Strategic Opportunities
- Querétaro industrial corridor expansion:Manufacturing facility construction is generating specification-grade demand for high-durability exterior systems in a historically underpenetrated central market.
- Carbon accounting mandate preparation:Anticipated amendments to Mexico's General Law of Climate Change will reward early adopters of imported resin feedstock documentation and lifecycle assessment capabilities.
- Direct contractor platform distribution:Digital procurement portals are disintermediating traditional distributor networks for large developer accounts seeking consolidated specification management.
Industry Challenges
- Certified applicator workforce scarcity:NMX-compliant installation training programs lag project growth, creating quality assurance gaps in high-performance coating specification fulfillment.
- PROFECO labeling compliance timeline:Accelerated consumer protection audits demand reformulated packaging and technical data sheet revisions that disrupt inventory rotation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Architectural Coatings Market |
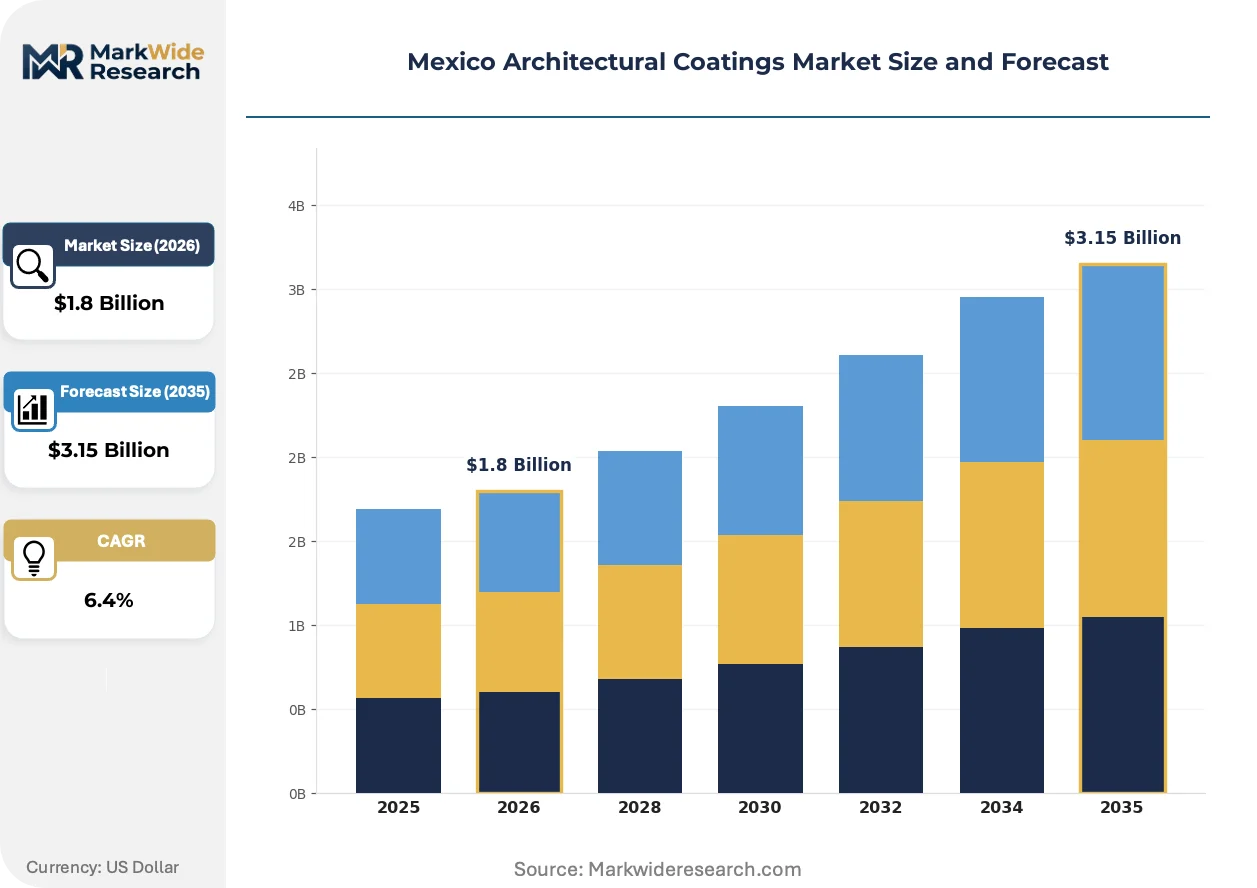
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exterior Coatings, Interior Coatings, Primers, Sealants Application: Residential, Commercial, Industrial, Institutional Technology: Water-Based, Solvent-Based, Powder Coatings, UV-Cured End User: Contractors, Architects, DIY Users, Property Developers |
| Companies Covered | RPM International Inc., Jotun, The Sherwin-Williams Company, Champion Coat Pinturas y Recubrimientos, Pinturas Berel SA de CV, PPG Industries Inc., Masco Corporation, Corev de México, Benjamin Moore & Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Architectural Coatings Market Shifts & Advancements
Formulation chemistry and procurement digitization are converging to reshape how coatings are specified, distributed, and validated across Mexico's construction value chain.
Ceramic microsphere additives are absorbing infrared radiation in exterior wall coatings, reducing thermal transfer through building envelopes by 15-20% compared to conventional pigmented systems. Large residential developers in Nuevo León are specifying these systems for LEED-equivalent project certification, compressing payback periods for premium material upgrades.
SEMARNAT's pending NOM-085-SEMARNAT-2011 amendments will tighten VOC emission thresholds for interior architectural coatings below current solvent-based product capabilities. Industrial consequence includes forced reformulation investment or product line retirement for formulators dependent on alkyd resin systems. The commercial renovation segment is responding fastest, with Mexico City property managers accelerating water-based specification transitions ahead of enforcement windows.
Large developer procurement departments are consolidating specification authority previously dispersed across project architects and general contractors. Regional distributor relationships are being displaced by direct technical service agreements with manufacturers who provide substrate testing, warranty administration, and applicator certification. This concentration is most visible in Guadalajara's residential tower market, where three developers control specification for 60% of annual coating volumes.
Mexico Architectural Coatings Market Segmentation
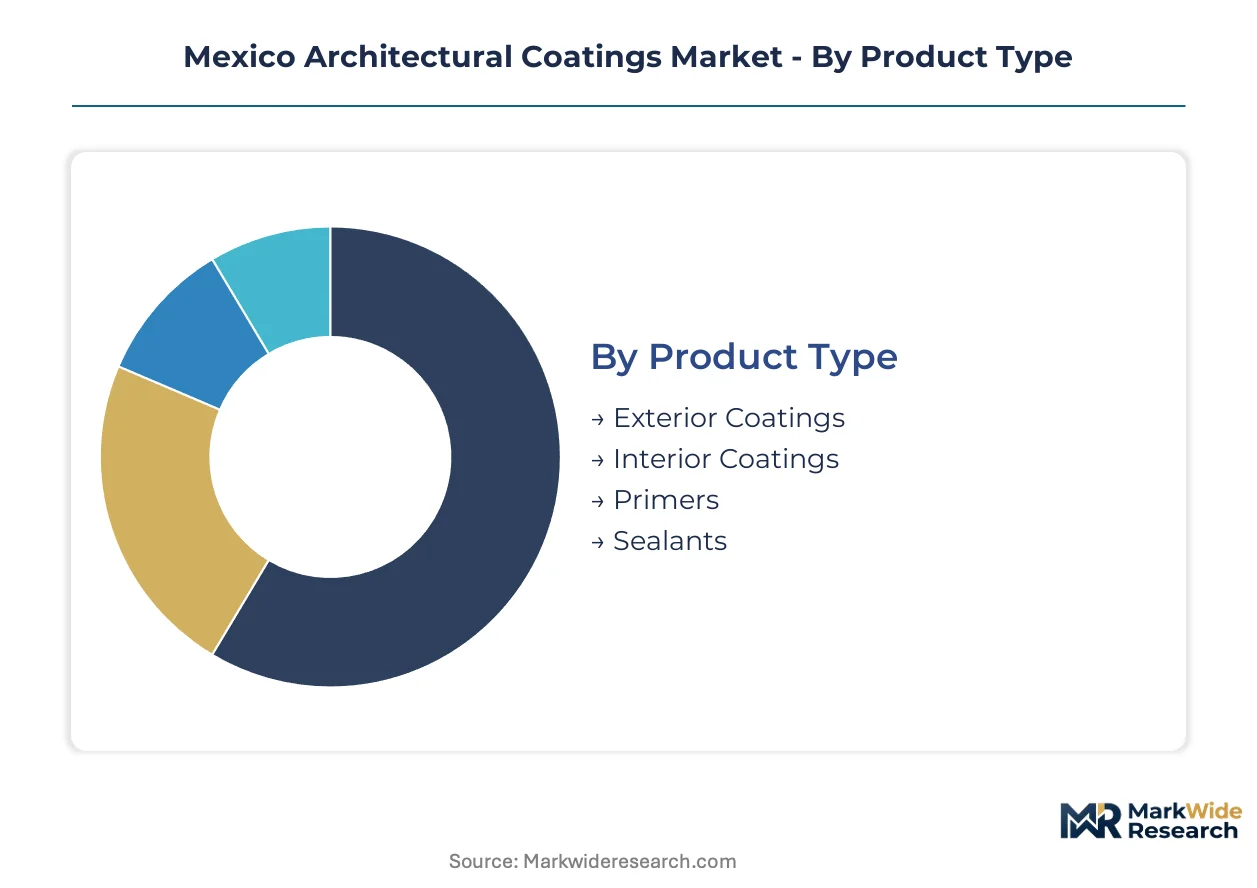
Architectural coatings in Mexico fragment across regulatory compliance tiers, with SEMARNAT's VOC limits and NMX certification requirements creating divergent specification burdens for each segment. Understanding these certification pathways enables suppliers to align R&D investments with enforcement timelines and procurement authority concentration.
Product Type:
SEMARNAT's NOM-085-SEMARNAT-2011 imposes graduated VOC thresholds across product categories, with exterior systems facing distinct thermal performance documentation under NOM-001-SECRE-2010.
- Exterior Coatings:Acrylic emulsion systems with 30-50% solids content dominate specification for Jalisco and Nuevo León residential towers. NOM-001-SECRE-2010 thermal performance mandates are consolidating demand around ceramic microsphere-enhanced formulations in these states.
- Interior Coatings:Water-based latex formulations capture specification share as SEMARNAT enforcement accelerates solvent system phase-out. Mexico City commercial renovation cycles drive volume for low-VOC interior systems ahead of pending threshold reductions.
- Primers:Moisture-resistant alkyd and acrylic sealer systems serve substrate adhesion assurance in monsoon-exposed construction zones.
- Sealants:Elastomeric joint compounds complete envelope protection specifications for high-performance building assemblies.
Leading the category by volume: Exterior Coatings. Growing fastest: Interior Coatings.
Application:
Cost tier stratification separates specification-grade projects with NMX-compliant documentation from price-sensitive segments where contractor certification gaps persist.
- Residential:Large property developers in Guadalajara and Monterrey consolidate procurement authority for multi-tower projects. NOM-001-SECRE-2010 thermal standards mandate higher-specification coating systems in new construction.
- Commercial:Mexico City metropolitan corridor renovation cycles sustain specification-grade interior volumes. PROFECO labeling audits accelerate compliance investment for property managers.
- Industrial:Querétaro manufacturing facility construction generates demand for high-durability exterior systems.
- Institutional:Public procurement under NMX standards requires documented quality certification for government building envelopes.
Residential commands the largest volume share. Commercial renovation is expanding most quickly.
Technology:
Margin structure diverges sharply between established water-based production and reformulation investments required for regulatory survival.
- Water-Based:Acrylic emulsion technology captures specification share across residential and commercial segments. Corev de México and domestic formulators prioritize these systems for central Mexico climate adaptation.
- Solvent-Based:Alkyd resin formulations face forced phase-out as SEMARNAT's pending amendments tighten interior VOC thresholds below current product capabilities.
- Powder Coatings:Zero-VOC systems serve specialized metal substrate applications in industrial construction.
- UV-Cured:Rapid-cure technology addresses niche commercial renovation timelines demanding minimal disruption.
Water-Based technology leads by volume. UV-Cured systems are gaining share fastest.
End User:
Customer type determines procurement channel configuration, with large developer direct agreements displacing traditional distributor relationships.
- Contractors:Volume-scale builders demand extended warranty terms and technical compliance documentation. NMX-certified applicator workforce scarcity creates quality assurance gaps in specification fulfillment.
- Property Developers:Three Guadalajara developers control specification for sixty percent of annual residential coating volumes. Direct technical service agreements with manufacturers are replacing regional distributor relationships.
- Architects:Specification authority is consolidating into developer procurement departments, reducing independent architect influence.
- DIY Users:Retail channel dependence concentrates in standard-grade interior products with PROFECO-mandated labeling accuracy.
Property Developers lead procurement volume. Contractor consolidation is accelerating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large property developers in Jalisco and Nuevo León are consolidating procurement authority for residential towers. SEMARNAT's VOC enforcement and NOM-001-SECRE-2010 thermal standards are reshaping specification requirements across Mexico's construction corridors.
Mexico City Metro
Commercial renovation cycles drive specification-grade interior coating volumes in the metropolitan corridor. PROFECO labeling audits accelerate compliance investment for property managers. Intensifying monsoon patterns expand primer demand for moisture-resistant envelope systems in the Valley of Mexico.
Nuevo León
Residential construction among large property developers concentrates demand for ceramic microsphere-enhanced exterior systems. NOM-001-SECRE-2010 thermal performance mandates consolidate specification around higher-grade coatings. Monterrey anchors manufacturing scale for national distribution networks serving northern markets.
Jalisco
Guadalajara's residential tower market sees three developers control specification for sixty percent of annual coating volumes. Direct technical service agreements with manufacturers displace regional distributor relationships. The state's subtropical climate forces specialized water-based formulations for substrate protection.
Bajío Region
Querétaro industrial corridor expansion generates specification-grade demand for high-durability exterior systems in an underpenetrated central market. Manufacturing facility construction drives new specification cycles. The region's arid plateau conditions require distinct formulation profiles from coastal markets.
Northern Border States
Cross-border supply chain integration creates import dependency for specialty additives through Veracruz port infrastructure. Customs clearance surges expose bottleneck risks for titanium dioxide feedstocks. Industrial construction in Tijuana and Ciudad Juárez sustains demand for zero-VOC powder coating systems.
Mexico Architectural Coatings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue water-based specialization and climate-adapted formulations. The market structure concentrates around multinational manufacturers with integrated distribution networks and domestic formulators with regional climate expertise. Two archetypes dominate: scale-driven nationals leveraging manufacturing footprint, and specialized locals optimizing formulations for central Mexico aridity. Competitive moves center on direct technical service agreements with large developers and digital procurement portal development for contractor consolidation.
Among multinational coatings manufacturers, The Sherwin-Williams Company, PPG Industries Inc., and RPM International Inc. exemplify the scale-driven archetype with integrated national coverage. Corev de México occupies a position within the specialized domestic tier, representing formulators who differentiate through water-based systems adapted to central plateau conditions. Jotun and Benjamin Moore & Co. sit within the premium specification segment, anchoring positions where technical compliance documentation and extended warranty terms determine procurement outcomes. Champion Coat Pinturas y Recubrimientos and Pinturas Berel SA de CV represent mid-scale Mexican formulators navigating the transition from solvent-based to low-VOC portfolios.
| Leading Market Players |
|---|
| RPM International Inc. |
| Jotun |
| The Sherwin-Williams Company |
| Champion Coat Pinturas y Recubrimientos |
| Pinturas Berel SA de CV |
| PPG Industries Inc. |
| Masco Corporation |
| Corev de México |
| Benjamin Moore & Co. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap formulators dominate Mexico's architectural coatings supply base, anchoring production discipline through generational capital structures that resist short-term margin compression. Their ownership concentration enables coordinated raw material procurement while limiting price volatility transmission to contractor segments.
Pricing Analysis
Volume-scale residential developers extract standard-tier pricing through consolidated procurement authority, while specification-grade commercial projects absorb premium coatings with extended warranty bundling. NMX certification tiers create sharp price differentiation between compliant and non-compliant product lines. Cost compression in solvent-based alkyd formulations is intensifying because SEMARNAT's pending VOC amendments will force product line retirement. DIY retail channels exhibit highest price sensitivity, whereas institutional buyers under public procurement statutes prioritize documented quality over unit cost.
Supply Chain Analysis
Reverse-logistics flows for architectural coatings remain minimal given the consumable nature of liquid systems, though container return programs for bulk industrial deliveries operate through Monterrey distribution hubs. Feedstock supply draws from US Gulf Coast propylene derivatives, Chinese titanium dioxide pigment, and German specialty additives. Single-source vulnerability concentrates in Veracruz port customs clearance for imported resin feedstocks. Distribution runs through manufacturer-direct technical service agreements with large developers, displacing traditional regional distributor networks in Guadalajara and Mexico City corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's architectural coatings sector occupies a forced technology-transition phase as water-based acrylic emulsions displace solvent-based alkyd systems under SEMARNAT enforcement timelines.
For Market Incumbents: Deploy direct technical service agreements to lock specification authority with consolidated developer accounts. Sherwin-Williams and PPG Industries should accelerate NMX-certified applicator training programs to close quality assurance gaps threatening warranty fulfillment. Backward integration into acrylic emulsion production hedges propylene derivative cost volatility from US Gulf Coast supply routes. For New Entrants and Emerging Players: Begin with climate-adapted water-based formulations targeting Querétaro's underpenetrated industrial corridor, where manufacturing facility construction generates specification-grade demand without entrenched incumbent relationships. A go-to-market angle anchored in carbon accounting documentation capabilities anticipates General Law of Climate Change amendments rewarding early compliance adopters. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized domestic formulators with regional climate expertise in central Mexico's arid plateau conditions, where reformulation capabilities for water-based systems create defensive moats. The signal to watch is SEMARNAT enforcement acceleration triggering solvent-dependent product line retirements and forced seller dynamics among alkyd-reliant mid-caps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion Production | Captive resin supply insulates margin stability against US Gulf Coast propylene volatility. |
| NMX-Certified Applicator Training Program | Workforce scarcity in compliant installation creates competitive differentiation for warranty-backed specifications. |
| Carbon Accounting Documentation Capability | Early adoption of imported resin feedstock lifecycle assessment anticipates General Law of Climate Change amendments. |
| Direct Technical Service Agreements | Large developer procurement consolidation rewards bypass of traditional distributor networks in Guadalajara and Monterrey. |
| Ceramic Microsphere Additive Formulation | Infrared-absorbing exterior systems capture NOM-001-SECRE-2010 thermal compliance premiums in Nuevo León residential towers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant managers at Monterrey manufacturing facilities, procurement leads at Jalisco property developers, distribution channel partners serving Mexico City commercial renovation, and technical R&D directors formulating for central plateau climate conditions. Bottom-up volume estimates from application-level consumption patterns reconciled with top-down value projections derived from customs import records and SEC 10-K disclosures of multinational coatings manufacturers.
Data-stream reconciliation across shipment volumes, raw material import values, and construction permit aggregations informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, technology platform, and regional climate zone. CAGRs emerged from regression analysis against construction output indices and regulatory enforcement timelines. Feedstock cost indices for propylene derivatives and titanium dioxide pigment informed margin compression scenarios.
SEMARNAT enforcement acceleration, petrochemical feedstock price spikes, and customs clearance disruptions at Veracruz port are the dominant revision risks to forecast outputs. Practitioners should monitor these triggers for early signals of specification-grade demand shifts or supply bottleneck emergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
UK Aluminum Door and Window Market
Building Materials
Global White Cement Market
Building Materials
Indonesia Architectural Coatings Market
Building Materials
India Cement Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Sprayed Concrete Market
Building Materials
Low-E Construction Glass Market
Building Materials
Solar Control Window Film Market
Building Materials
United States Architectural Coatings Market
Building Materials
Cement Tiles Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Construction Glass Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Aluminum Door and Window Market
Building Materials
Door Frame Metal Market