
 Germany Architectural Coatings Market | 2026-2036
Germany Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Architectural Coatings Market Foresight
The price-performance gap between premium architectural coatings and commodity-grade alternatives is hardening across Germany's distribution channels. Brillux GmbH & Co. KG leverages its captive retail network and color-matching infrastructure to dominate the premium renovation segment. DAW SE anchors its position through deep backward integration into raw material production and sustained investment in waterborne technology platforms.
Germany architectural coatings encompass film-forming liquid or paste systems applied to building substrates for protection, decoration, or functional modification, typically comprising binders, pigments, solvents or water carriers, and additives engineered to achieve specific dry-film thickness, adhesion, and durability parameters. Waterborne formulations now lead volume growth as regulatory pressure on solvent emissions intensifies, while the residential buildings end-use segment commands the largest share of consumption due to Germany's substantial stock of post-war housing requiring cyclical refurbishment. Low-VOC and high-performance formulations represent the fastest-expanding margin pools as building certification schemes tighten indoor air quality thresholds.
KBA vehicle type-approval frameworks indirectly influence industrial facility coating specifications, while REACH and the EU Green Deal directly constrain permissible chemical constituents and mandate carbon footprint disclosure across the supply chain. The German federal building code and state-level energy ordinances progressively require reflective or thermally active exterior coatings as efficiency measures. Stakeholders must monitor evolving EU taxonomy criteria for sustainable construction materials, as these classification standards will determine access to green financing instruments and public procurement eligibility without reference to specific calendar milestones.
Market Dynamics
Renovation cycles in Germany's post-war housing stock are compressing as energy efficiency mandates under the EU Green Deal force simultaneous envelope and interior upgrades, creating synchronized demand spikes for low-VOC decorative finishes.
Growth Catalysts
- Building energy ordinances:German federal and state-level codes now mandate thermally reflective exterior coatings as retrofit requirements, pulling forward replacement demand in multi-family housing.
- Munich-Stuttgart corridor:Commercial construction permits in these southern metropolitan zones remain elevated, concentrating specification-grade volume for premium waterborne systems.
- REACH chemical restrictions:Progressive solvent limits under ECHA frameworks are redirecting formulation investment toward waterborne platforms ahead of compliance deadlines.
Market Restraints
- Titanium dioxide volatility:White pigment supply concentration in Chinese production creates input cost instability for decorative white base formulations.
- Specialty additive sourcing:Biocidal film preservatives face tightening EU BPR approval timelines, constraining shelf-life performance in humid interior applications.
- Application labor scarcity:Certified spray-applicator shortages in eastern German states limit throughput for large-scale commercial facade projects.
Strategic Opportunities
- Carbon footprint disclosure mandates:EU Green Deal supply-chain reporting requirements favor early movers with lifecycle-assessed product portfolios in public procurement channels.
- Rhineland-Palatinate housing stock:Underpenetrated 1960s-1970s residential districts present concentrated renovation opportunity as energy retrofit subsidies expand.
- Smart coating integration:Convergence of photocatalytic air-purifying binders with IoT-enabled building management systems opens specification pathways in certified commercial developments.
Industry Challenges
- Color-matching infrastructure:Real-time spectrophotometry integration across decentralized retail networks demands capital intensity that mid-tier distributors struggle to fund.
- EU taxonomy alignment:Evolving sustainable construction material classification standards create certification timeline uncertainty for product portfolio planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Architectural Coatings Market |
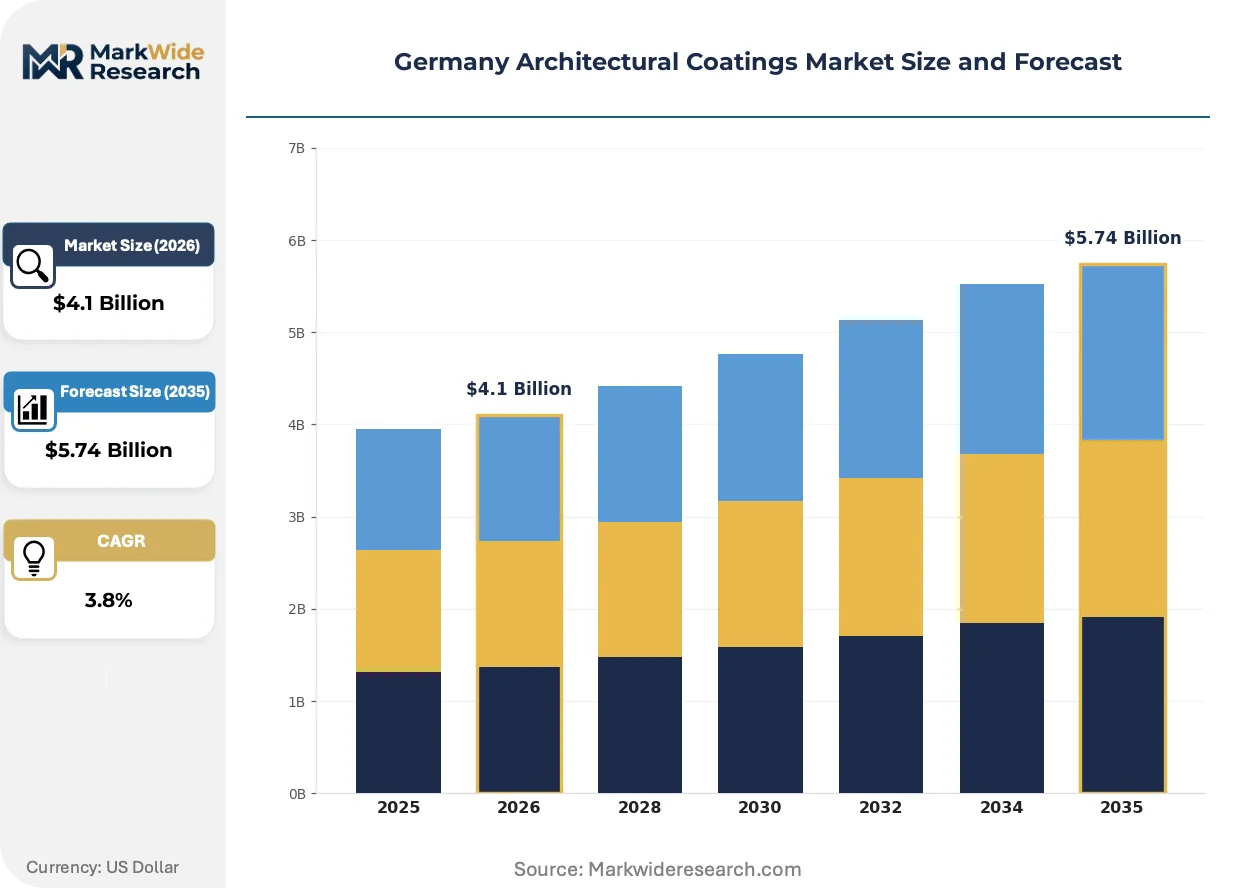
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylics, Alkyds, Polyurethanes, Waterborne Coatings End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Institutional Buildings Application: Interior, Exterior, Primers, Finishes Formulation: Solvent-Based, Water-Based, High-Performance, Low-VOC |
| Companies Covered | Brillux GmbH & Co. KG, DAW SE, PPG Industries, Inc., Sto SE & Co. KGaA, AkzoNobel N.V., BASF Coatings GmbH, Axalta Coating Systems, Asian Paints, Hempel A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Architectural Coatings Market Shifts & Advancements
Formulation chemistry and specification workflows are converging as digital color systems and performance-assured coatings reshape how architects and contractors select and apply finishes across German building projects.
Hybrid waterborne-UV curing technology is unifying rapid drying characteristics with low-emission profiles in on-site wood coating applications. Flooring contractors in Bavarian commercial fit-out projects are adopting these systems to compress installation schedules. The technology is unifying previously separate primer and topcoat application steps into single-pass workflows that reduce labor hours per square meter.
REACH authorization procedures for chromium trioxide in corrosion-resistant metal primers are forcing formulation pivots toward alternative passivation chemistries. Industrial facility maintenance divisions in North Rhine-Westphalia chemical corridors face accelerated substrate protection testing. Specification engineers are responding by qualifying silicon-modified alkyd systems that trade some durability for compliance certainty.
Specification behavior is fragmenting as large housing associations centralize coating procurement through framework agreements while individual renovators demand single-can convenience. The traditional trade-counter channel faces disintermediation from direct-to-contractor digital platforms. This pattern is most visible in Berlin's dense rental housing market where property management groups consolidate volume for negotiated pricing.
Germany Architectural Coatings Market Segmentation
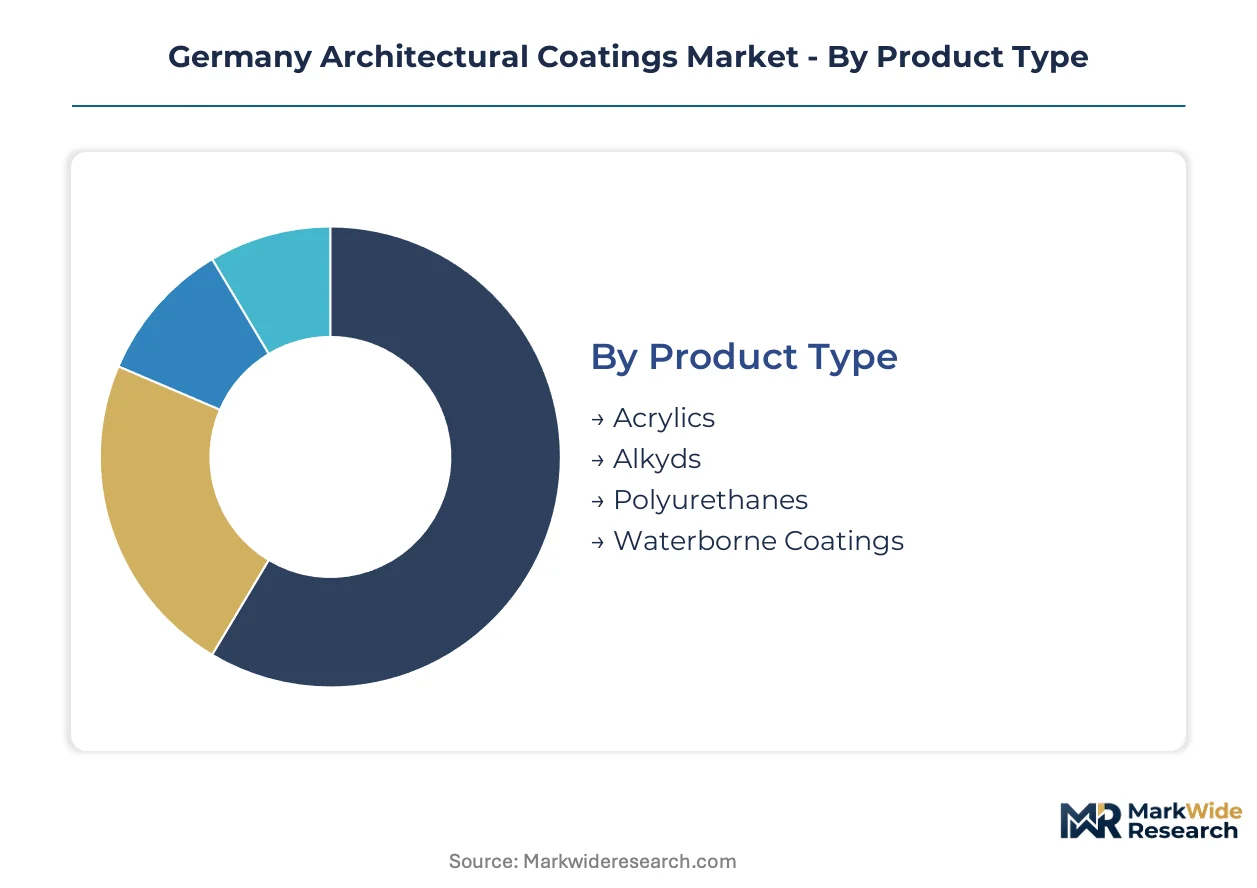
Germany's architectural coatings market segments along formulation chemistry, end-use construction type, and application environment, with each division carrying distinct REACH registration burdens and energy-efficiency certification requirements. Understanding these segment boundaries clarifies where KBA facility standards intersect with EU Green Deal procurement rules.
Product Type:
REACH authorization timelines and VOC emission classifications determine which resin chemistries face formulation restrictions versus grandfathered compliance pathways.
- Acrylics:Thermoplastic binders formed through emulsion polymerization of acrylic and methacrylic esters, delivering rapid drying and UV resistance for exterior facades. Demand concentrates in Bavarian commercial retrofit projects where reflective white specifications dominate, driven by state-level thermal ordinances mandating solar reflectance index thresholds.
- Alkyds:Polyester-modified drying oil systems that cure through oxidative crosslinking, prized for gloss retention and substrate penetration on heritage timber structures. Specification volume clusters in Rhineland-Palatinate 1960s housing renovation where moisture-vapor permeability requirements override waterborne alternatives, constrained by ECHA biocidal preservative approval delays affecting humid-climate durability.
- Polyurethanes:Isocyanate-cured systems offering abrasion resistance and chemical tolerance for high-traffic flooring and industrial maintenance.
- Waterborne Coatings:Latex and dispersion-based systems with sub-50 g/L VOC content, now default specification for federal public procurement under EU Green Deal carbon disclosure mandates.
Waterborne coatings sit at the top of the volume ranking, with acrylics climbing the fastest as reflective roof specifications multiply under German building energy ordinances.
End User:
Customer procurement scale determines whether coating selection flows through centralized framework agreements or decentralized trade-counter purchasing.
- Residential Buildings:Single-family and multi-family housing stock encompassing both new construction and cyclical refurbishment cycles. Munich-Stuttgart corridor rental associations are consolidating specification-grade volume through negotiated procurement platforms, displacing traditional distributor relationships.
- Commercial Buildings:Office, retail, and hospitality fit-out projects requiring LEED-equivalent indoor air quality certification. Berlin property management groups are driving demand for low-VOC interior systems through consolidated purchasing power, compressing margins for mid-tier applicators.
- Industrial Facilities:Manufacturing plants and logistics centers subject to KBA facility standards and corrosion protection specifications.
- Institutional Buildings:Schools, hospitals, and government structures with extended durability requirements and public procurement transparency obligations.
Residential buildings command the largest consumption share, while commercial buildings are expanding most quickly as southern German metropolitan construction permits sustain elevated levels.
Application:
Substrate exposure conditions dictate performance testing protocols and warranty term structures across the segment map.
- Interior:Wall and ceiling finishes subject to humid-room biocidal preservation requirements under EU BPR frameworks. Kitchen and bathroom specifications in North Rhine-Westphalia social housing are driving demand for mold-resistant formulations with extended shelf-life stability.
- Exterior:Facade and roof coatings exposed to freeze-thaw cycling and UV degradation. Thermally reflective specifications are becoming mandatory in Baden-Württemberg energy retrofit subsidies, redirecting specification toward solar-reflective pigment packages.
- Primers:Bonding and sealing layers engineered for specific substrate porosity and alkalinity conditions.
- Finishes:Decorative and protective topcoats delivering color stability and cleanability performance.
Exterior applications generate the highest per-square-meter value, with interior finishes gaining share fastest as post-war housing envelope upgrades trigger synchronized interior refurbishment demand.
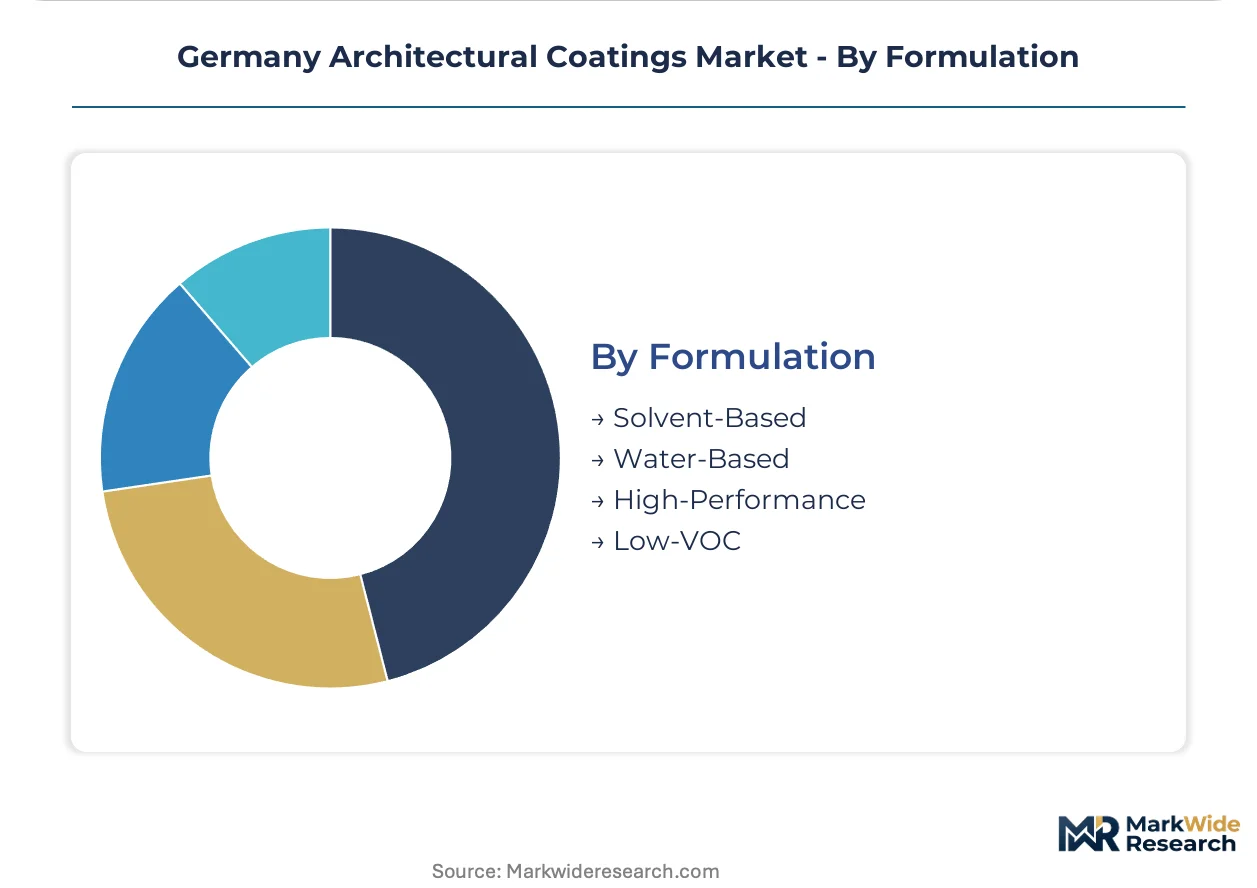
Formulation:
Regulatory pressure intensity and carbon accounting granularity separate premium positioning from commodity substitution risk.
- Solvent-Based:Hydrocarbon-thinned systems with superior flow and leveling on complex substrates. Industrial maintenance divisions in chemical corridor facilities continue specifying these for corrosion protection where waterborne alternatives lack equivalent film build, though ECHA solvent emission quotas are compressing permissible application windows.
- Water-Based:Aqueous dispersion systems dominating new construction and residential renovation. Federal building codes are progressively mandating these for public projects, with lifecycle carbon assessments now required under EU Green Deal supply-chain disclosure rules.
- High-Performance:Engineered systems with extended durability warranties and specialized functional properties.
- Low-VOC:Formulations meeting sub-30 g/L emission thresholds for certified green building programs.
Water-based formulations lead volume consumption, with low-VOC systems showing the steepest expansion trajectory as EU taxonomy criteria tighten indoor air quality thresholds for green financing eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's certified applicator workforce concentrates in Bavaria and Baden-Württemberg, anchoring specification-grade coating demand in southern metropolitan corridors. Regional divergence reflects uneven housing stock age, energy retrofit subsidy allocation, and commercial construction permit velocity.
Bavaria
Munich's commercial fit-out boom and single-family renovation cycles drive waterborne coating consumption. State-level thermal ordinances mandate solar reflectance index thresholds for roof specifications. The Munich-Stuttgart corridor concentrates premium-grade volume through consolidated housing association procurement.
Baden-Württemberg
Stuttgart's automotive supplier ecosystem spills into architectural specification networks, favoring performance-assured systems. Federal building energy codes accelerate thermally reflective exterior coating mandates. The Stuttgart metropolitan zone sustains elevated commercial construction permits for LEED-equivalent developments.
North Rhine-Westphalia
Chemical corridor industrial maintenance divisions anchor solvent-based corrosion protection demand despite REACH emission quotas. ECHA biocidal preservative approval delays constrain humid-climate interior formulations. The Rhine-Ruhr agglomeration faces certified spray-applicator shortages limiting large-scale facade project throughput.
Rhineland-Palatinate
Underpenetrated 1960s-1970s housing stock presents concentrated renovation opportunity as federal energy retrofit subsidies expand. KBA facility standards indirectly influence industrial coating specifications in automotive-adjacent manufacturing plants. Mainz and Ludwigshafen clusters show rising low-VOC interior finish specification rates.
Berlin-Brandenburg
Dense rental housing markets drive property management group consolidation of coating procurement through direct-to-contractor digital platforms. EU Green Deal carbon disclosure mandates redirect public project specifications toward lifecycle-assessed waterborne systems. The capital region exhibits fastest trade-channel disintermediation as framework agreements displace traditional distributors.
Germany Architectural Coatings Market Competitive Landscape
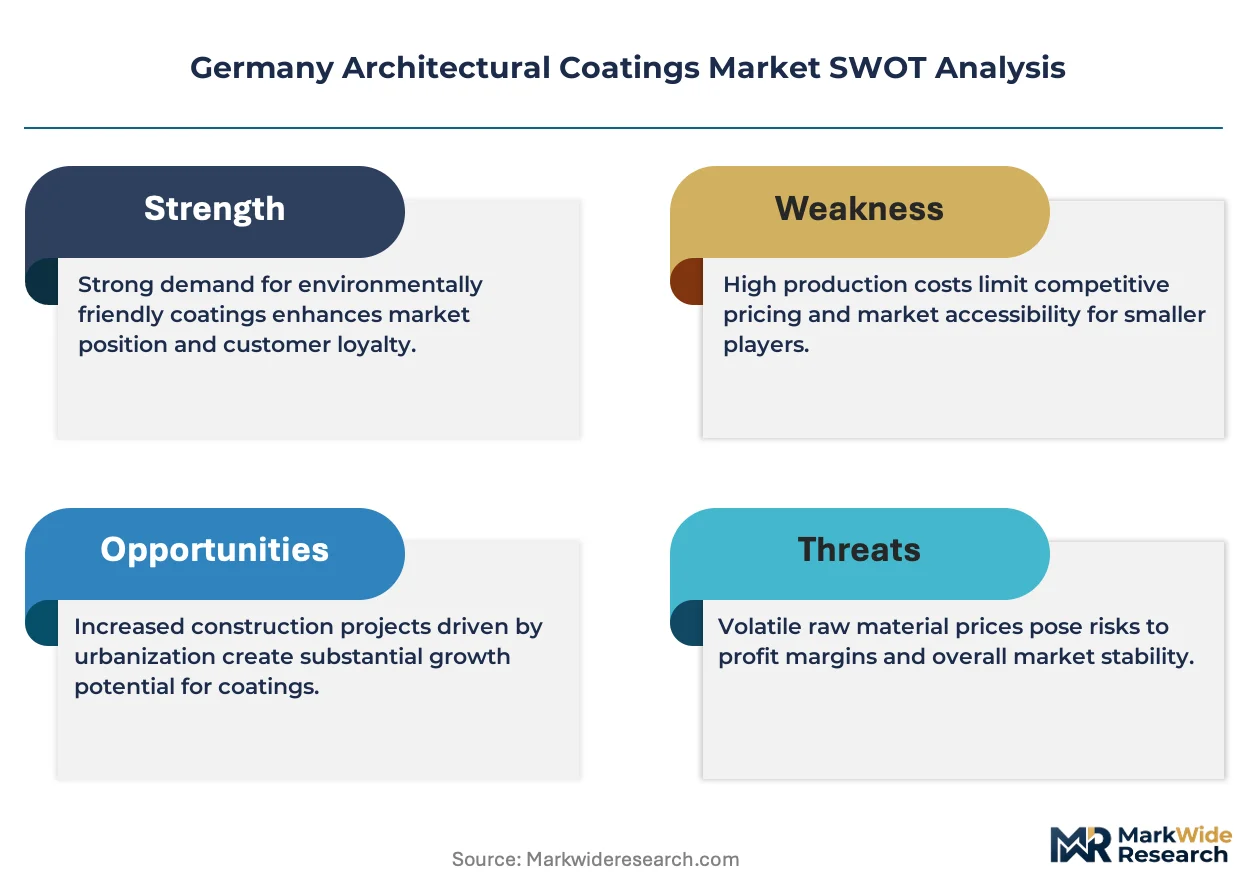
Top-tier vendors anchor premium specification networks, while mid-tier distributors struggle to fund color-matching infrastructure investments. The vendor base stratifies across captive retail networks, backward-integrated raw material producers, and import-dependent commodity suppliers. Three archetypes dominate: vertically integrated German family enterprises, multinational coating conglomerates with local formulation facilities, and Asian import specialists serving price-sensitive renovation segments. Competitive moves concentrate on M&A to secure distribution density and strategic partnerships to embed carbon accounting capabilities ahead of EU taxonomy deadlines.
Within the German family enterprise tier, Brillux GmbH & Co. KG and DAW SE exemplify divergent defensive strategies. Brillux leverages its captive retail footprint and spectrophotometry infrastructure to dominate premium renovation specification. DAW SE anchors its position through in-house production of key raw materials and sustained waterborne technology investment. PPG Industries, Inc. represents the multinational archetype with local formulation adaptability to REACH compliance timelines.
| Leading Market Players |
|---|
| Brillux GmbH & Co. KG |
| DAW SE |
| PPG Industries, Inc. |
| Sto SE & Co. KGaA |
| AkzoNobel N.V. |
| BASF Coatings GmbH |
| Axalta Coating Systems |
| Asian Paints |
| Hempel A/S |
| Others |
Supply & Pricing Matrix
The performance-certification gap between EU Green Deal-compliant formulations and legacy solvent-based systems is widening across German distribution channels, compressing margins for mid-tier distributors while rewarding backward-integrated producers with captive raw material supply. This bifurcation manifests in procurement patterns where housing associations negotiate framework pricing on lifecycle-assessed waterborne systems, while independent renovators absorb premium markups for single-can convenience at trade counters.
Pricing Analysis
The bundled-versus-unbundled service split dominates pricing architecture across German architectural coatings. Project-based contracting with certified applicator networks commands premium positioning, while transactional trade-counter sales face commodity pressure. Price differentiation hinges on REACH compliance tier and carbon disclosure granularity under EU Green Deal mandates. Cost compression in the standard tier is intensifying because titanium dioxide supply volatility from Chinese production concentrates input risk. Small-scale residential renovators exhibit highest price sensitivity, whereas consolidated housing associations in Munich-Stuttgart corridors leverage volume for fixed-price agreements.
Supply Chain Analysis
Captive retail networks anchored by German family enterprises handle specification-grade demand, while independent distributors serve price-sensitive renovation segments. Raw material supply concentrates in Germany, China, and Belgium for titanium dioxide, acrylic emulsions, and specialty additives. Formulation chemistry rests on petrochemical derivatives and bio-based binder alternatives facing ECHA authorization timelines. Single-source vulnerability in white pigment supply creates margin instability for decorative base formulations. Distribution runs through manufacturer-owned color-matching studios, wholesale trade counters, and emerging direct-to-contractor digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's architectural coatings market offers margin expansion through premium-tier consolidation as energy retrofit mandates synchronize demand for certified low-VOC systems. Cost-down drivers include backward integration into emulsion polymerization and spectrophotometry infrastructure amortization across captive retail footprints.
For Market Incumbents: Cement specification-grade positioning by deepening captive supply of acrylic emulsions and expanding spectrophotometry-equipped retail studios in Bavaria and Baden-Württemberg. Threat from Asian import specialists in price-sensitive segments demands accelerated carbon footprint disclosure to secure public procurement eligibility. Channel control through housing association framework agreements is the critical defensive lever against trade-counter disintermediation. For New Entrants and Emerging Players: Launch via direct-to-contractor digital platforms targeting Berlin-Brandenburg property management groups with consolidated low-VOC interior finish procurement. Rhineland-Palatinate's underpenetrated 1960s-1970s housing stock presents the most penetrable geography for energy retrofit-triggered renovation demand. Go-to-market angle should emphasize lifecycle carbon assessment transparency to qualify for EU Green Deal-linked subsidy flows. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier distributors possessing regional color-matching infrastructure but lacking capital for spectrophotometry network expansion. Long-term viability over the coming decade favors acquisition targets with established applicator certification relationships and waterborne formulation adaptability. Signal to watch is ECHA biocidal preservative approval timelines affecting humid-climate interior product shelf stability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion Production | Captive supply secures margin stability against titanium dioxide volatility from Chinese producers. |
| Spectrophotometry Network Expansion | Real-time color-matching infrastructure locks in premium renovation specification across southern German metropolitan zones. |
| Carbon Footprint Disclosure Certification | Lifecycle assessment compliance unlocks EU Green Deal public procurement eligibility and green financing access. |
| Direct-to-Contractor Digital Platform Launch | Bypasses traditional trade-counter intermediation to capture consolidated housing association volume in dense rental markets. |
| Biocidal Preservative Formulation Pivot | Alternative chemistries address ECHA BPR approval delays constraining humid-climate interior product durability. |
Research Methodology
Direct dialogue with plant managers at German coating formulation facilities, procurement leads at housing associations, distribution channel partners in Bavaria and North Rhine-Westphalia, and technical R&D directors specializing in waterborne polymer systems grounded the qualitative foundation. Secondary validation drew from ECHA REACH registration databases, EU Green Deal implementation tracking, German federal building code amendments, and customs trade data on titanium dioxide imports. Bottom-up segment sizing triangulated against top-down construction permit and housing stock age projections.
Segment-level value and volume trajectories across the analysis window reflect disaggregated modeling by formulation chemistry, end-use construction type, application environment, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to renovation cycle compression rates and energy retrofit subsidy allocation patterns. Key inputs included KBA facility standard adoption timelines and EU taxonomy criteria evolution for sustainable construction material classification.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA solvent restriction timelines or prolonged titanium dioxide supply disruption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Pozzolana Cement Market
Building Materials
Global Metal Cladding Market
Building Materials
Granite Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
United States Construction Materials Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
Brick Adhesive Market
Building Materials
Malaysia Architectural Coatings Market
Building Materials
HDG Steel Pipe Market
Building Materials
Aluminum Door and Window Market
Building Materials
Fly Ash Bricks Market
Building Materials
Europe Cement Market
Building Materials
US Cement Tiles Market
Building Materials
China Architectural Coatings Market
Building Materials
Geocells Market