
 Precast Construction Market | 2026-2036
Precast Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Precast Construction Market Intelligence
The divergence in automated manufacturing capacity and logistics network scale is bifurcating the competitive landscape. LafargeHolcim leverages its extensive material science R&D to develop specialized concrete mixes for high-performance precast elements. In contrast, Skanska AB specializes in integrating precast solutions within its large-scale construction project management services, while CRH plc sustains its market position through a vast network of local production facilities catering to regional demand.
Precast construction involves manufacturing structural components off-site in a controlled factory environment. These elements, such as wall panels and beams, are produced to precise specifications, often achieving specific compressive strengths and finishes before being transported for on-site assembly. Infrastructure projects represent the fastest-growing application due to the demand for standardized bridge and tunnel components. Within product types, pre-stressed floor slabs and columns command significant volume, particularly in commercial and residential building construction.
Compliance with standards like ISO 9001 for quality management and CE marking in Europe governs market access and product acceptance. In the United States, building codes set by state and local authorities, alongside guidelines from the Precast/Prestressed Concrete Institute, define structural requirements. Future competitiveness will depend on a firm's ability to integrate digital design tools like BIM with automated production to meet demands for customization and sustainability.
Market Dynamics
The convergence of digital design tools with advanced material science is the central force shaping the market. This integration allows for mass customization, pushing precast beyond standardized components toward architecturally complex, high-performance building envelopes that meet stringent sustainability criteria.
Growth Catalysts
- EU Green Deal:The framework's emphasis on circular economy principles and resource efficiency is boosting demand for precast elements, which can be designed for disassembly and reuse in future projects.
- Indian Urbanization:Government-led initiatives like the "Housing for All" scheme require rapid and scalable construction solutions, making precast a preferred method for large-scale residential developments across the country.
- BIM Integration:The adoption of Building Information Modeling (BIM) in project planning enables precise off-site fabrication, significantly reducing material waste and accelerating construction timelines for complex infrastructure.
Market Restraints
- Logistical Constraints:The transportation of large, heavy precast elements is expensive and geographically limited, restricting a plant’s effective service area and increasing project costs for remote sites.
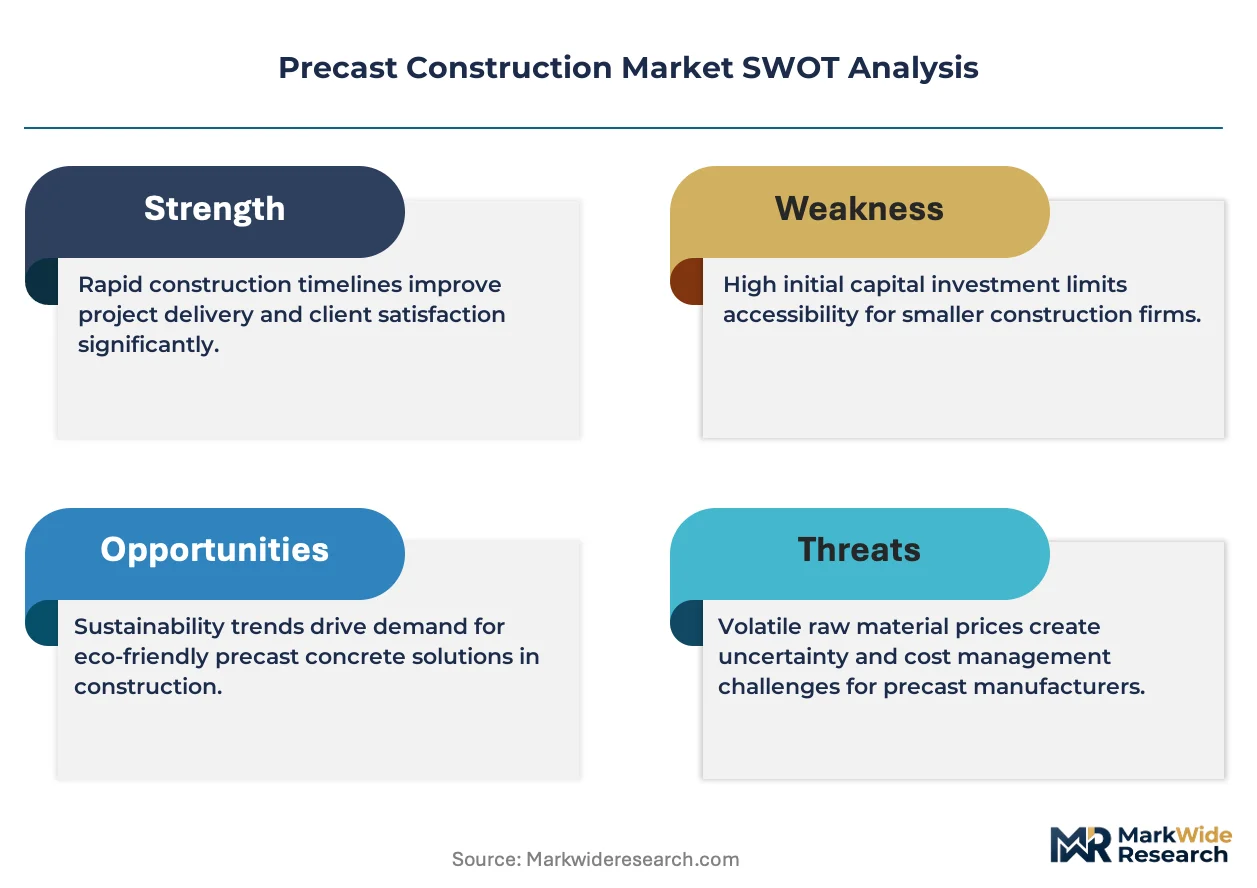
- High Capital Investment:Establishing automated precast manufacturing facilities requires substantial upfront capital for machinery and factory space, posing a significant barrier to entry for smaller firms.
- Design Inflexibility:Once production molds are created, late-stage design changes are costly and difficult to implement, creating rigidity compared to traditional on-site construction methods.
Strategic Opportunities
- Data Center Modules:Developing standardized, pre-engineered precast modules for data center construction offers a significant growth avenue, capitalizing on the sector's need for rapid deployment and consistent quality.
- Emerging Economies:Markets in sub-Saharan Africa and Southeast Asia with significant infrastructure deficits present opportunities for introducing cost-effective and durable precast systems for housing and transport.
- Smart Components:Embedding sensors into precast panels during fabrication allows for the creation of smart structural elements capable of real-time health monitoring for critical infrastructure like bridges.
Industry Challenges
- Skilled Labor Deficit:A shortage of technicians skilled in operating robotic fabrication equipment and designers proficient in BIM for manufacturing creates a critical operational bottleneck for fabricators.
- Code Harmonization:The lack of uniform international building codes for precast structures complicates design and compliance, requiring adaptation to disparate standards like those from the US-based Precast/Prestressed Concrete Institute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precast Construction Market |
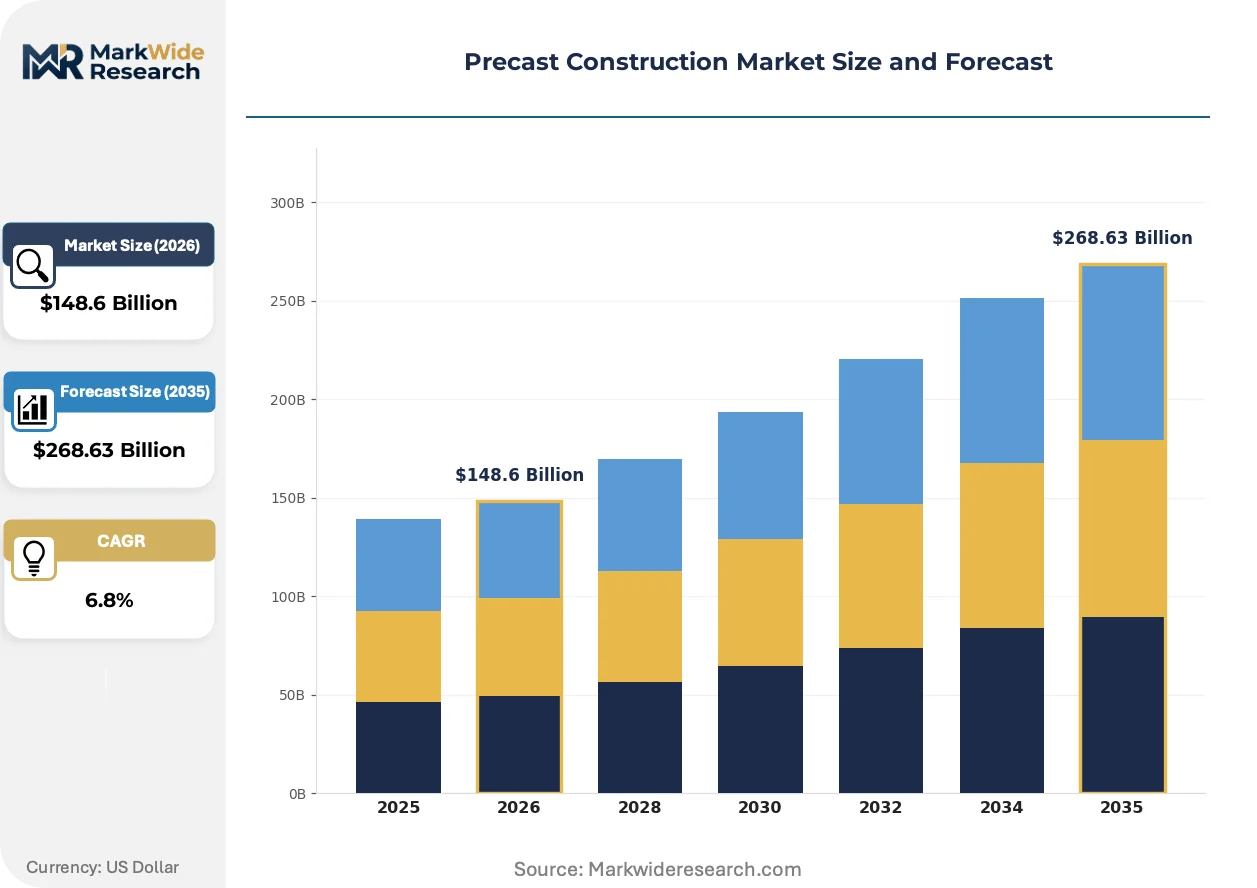
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Floor Slabs, Beams, Columns Application: Residential Buildings, Commercial Structures, Industrial Facilities, Infrastructure Projects Material: Concrete, Steel Reinforced Concrete, Lightweight Concrete, Others Installation Method: Wet Installation, Dry Installation, Hybrid Installation, Pre-assembled |
| Companies Covered | LafargeHolcim Ltd., CRH plc, CEMEX S.A.B. de C.V., Boral Limited, Oldcastle Infrastructure, Bouygues Construction, Forterra Inc., Skanska AB, Tindall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precast Construction Market Strategic Shifts & Innovations
Digitalization and sustainability are transforming precast construction from a commodity product into an engineered system. This evolution prioritizes lifecycle performance and material efficiency, moving beyond simple structural functions to create integrated building solutions.
Specialized concrete mixes with supplementary cementitious materials (SCMs) deliver enhanced durability and a lower carbon footprint. Infrastructure developers are specifying these materials to meet environmental targets and extend asset lifespans in projects across Europe and North America. The availability of these advanced options is fragmenting the traditional concrete supply chain into distinct performance and sustainability tiers.
The European Union's Corporate Sustainability Reporting Directive (CSRD) compels greater transparency in the construction supply chain. This mandate requires companies to report on the environmental impact of their products, including embodied carbon in building materials. Precast manufacturers targeting the EU must now provide verifiable lifecycle assessment (LCA) data to remain competitive.
A shift toward collaborative contracting models like design-build alters the role of precast suppliers. Instead of bidding on a finished design, manufacturers are engaged early to co-develop solutions with architects, optimizing for manufacturability. This trend is most advanced in complex hospital and airport projects in the United States and Germany.
Precast Construction Market Segmentation
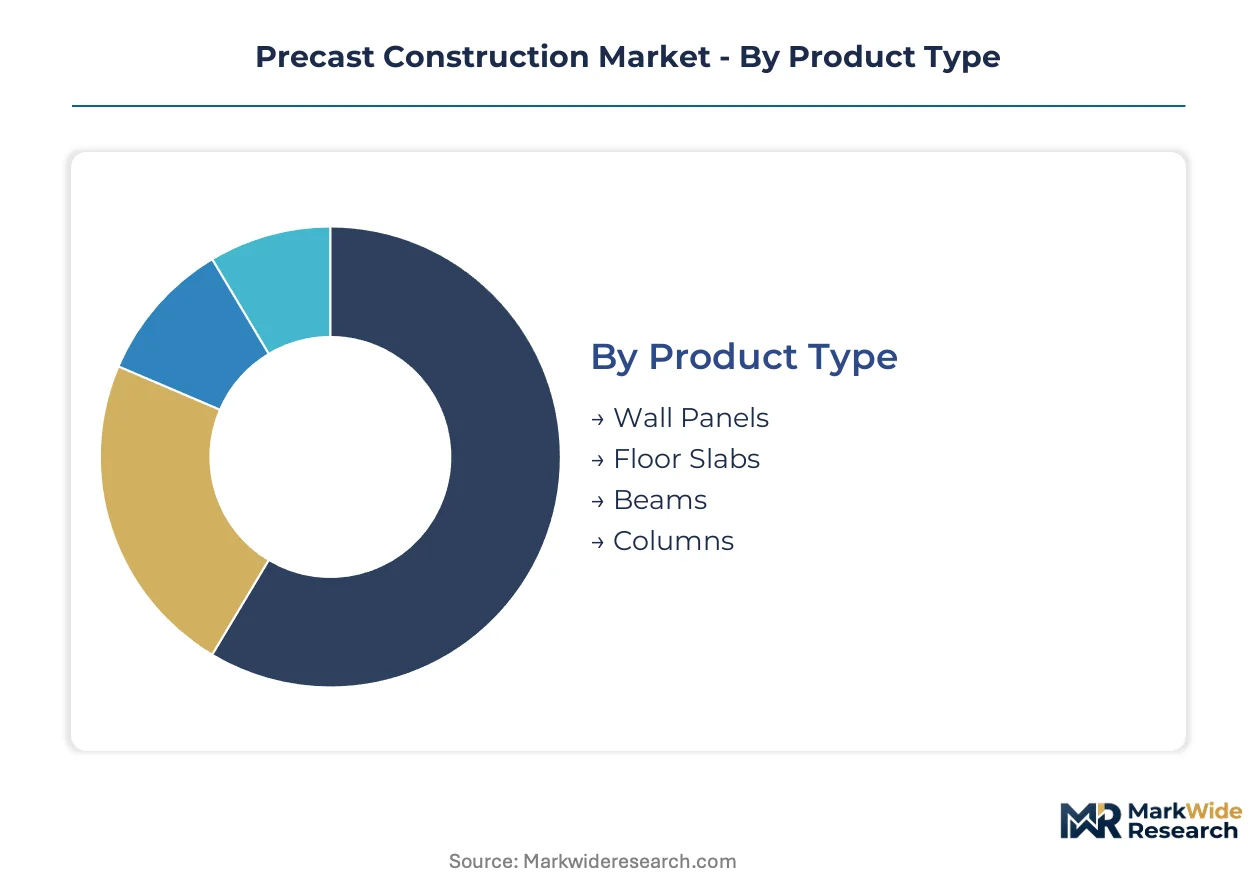
Segmentation provides a granular understanding of the Precast Construction Market, highlighting distinct demand patterns and technological preferences across various product types and end-use applications. This detailed breakdown helps identify areas of concentrated value and emerging opportunities for specialized solutions.
Product Type:
Margin pools within the product type category often concentrate in specialized, high-performance elements requiring advanced engineering and precise manufacturing.
- Floor Slabs:Pre-stressed concrete elements provide large, clear spans for multi-story buildings, enabling rapid construction. Demand concentrates in commercial and residential building construction across Europe due to accelerated assembly requirements.
- Beams:Structural members designed to support vertical loads, often pre-stressed or pre-tensioned for enhanced strength. Infrastructure projects in India drive demand for standardized bridge and tunnel components, leveraging precast efficiency.
- Wall Panels:Large, prefabricated concrete sections form exterior or interior building envelopes, offering thermal insulation and aesthetic finishes.
- Columns:Vertical structural elements transfer loads from beams and slabs to foundations, providing essential structural integrity.
The dominant share belongs to Floor Slabs, while Beams are closing the gap fastest due to infrastructure development.
Application:
Cost tier considerations heavily influence product selection within this category, balancing upfront investment with long-term operational efficiency and project scalability.
- Infrastructure Projects:These applications involve large-scale public works like bridges, tunnels, and highways, requiring durable and standardized components. Demand for standardized elements in Germany and the United States drives the segment's expansion.
- Residential Buildings:Precast elements form structural frameworks and exterior facades for multi-family housing and affordable homes, enabling rapid deployment. India's "Housing for All" scheme requires rapid construction solutions, boosting precast use.
- Commercial Structures:Office buildings, retail centers, and hotels utilize precast for rapid enclosure, aesthetic finishes, and structural integrity.
- Industrial Facilities:Factories, warehouses, and power plants employ precast for durable, fire-resistant structures that meet specific operational demands.
Volume concentration is highest in Residential Buildings, with Infrastructure Projects showing the most significant recent expansion.
Material:
Application requirements dictate the choice of material, directly impacting structural performance, durability, and compliance with environmental standards.
- Steel Reinforced Concrete:This material combines concrete's compressive strength with steel's tensile strength, forming robust structural elements for demanding applications. Demand for high-performance precast in complex hospital projects in the United States leverages this material for enhanced resilience.
- Lightweight Concrete:Incorporates lightweight aggregates to reduce density, offering thermal insulation, reduced dead load, and easier handling. Germany's focus on energy-efficient building envelopes drives its use in facade systems.
- Concrete:Standard concrete forms basic precast elements for non-structural or less demanding applications, offering cost-effective solutions.
- Others:This segment includes specialized mixes like ultra-high performance concrete or fiber-reinforced concrete, tailored for specific engineering properties.
The foundational material is Steel Reinforced Concrete, while Lightweight Concrete is experiencing increasing specification for specialized needs.
Installation Method:
Efficiency and site constraints heavily influence the selection of installation methods, affecting project timelines, labor costs, and overall construction quality.
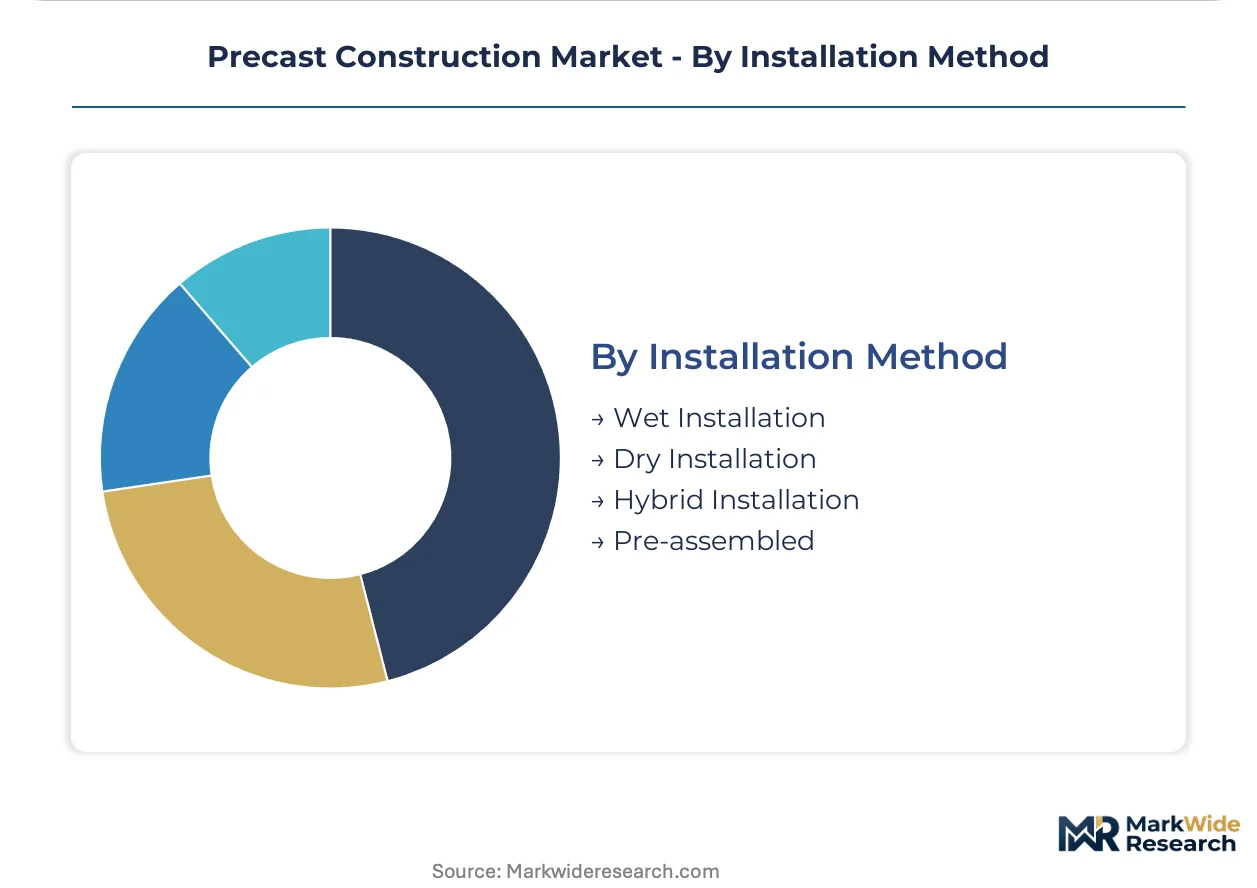
- Dry Installation:Components are connected using mechanical fasteners or grouted joints without extensive wet concrete pouring on site, minimizing curing times. This method accelerates construction in urban environments like London, reducing on-site disruption.
- Pre-assembled:Larger modules or sub-assemblies are fabricated off-site, transported, and directly placed, significantly reducing on-site labor and time. Data center construction in Ireland utilizes this method for rapid deployment and consistent quality.
- Wet Installation:Traditional method involving casting concrete on-site to connect precast elements, often used for structural continuity.
- Hybrid Installation:Combines elements of both wet and dry methods, optimizing for specific structural requirements and project logistics.
Traditional approaches remain significant, but innovative methods like Dry Installation are gaining traction for speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for precast components often diverges, with mature markets like Germany exhibiting strong value capture for specialized elements, while emerging economies such as India prioritize cost-effectiveness for mass housing. This regional asymmetry influences material selection and installation methodologies across diverse project scales. Infrastructure development in various nations drives demand for standardized precast solutions.
India
Accelerated urbanization and government-led initiatives drive substantial demand for precast construction solutions. The "Housing for All" scheme specifically mandates rapid and scalable construction methods for residential developments. This policy framework supports the expansion of precast manufacturing hubs in major cities like Mumbai and Delhi, addressing critical housing deficits. Indian infrastructure projects also increasingly utilize precast for standardized components.
Germany
Demand for energy-efficient building envelopes and high-performance infrastructure components fuels the German precast market. National building codes and the EU Green Deal's sustainability mandates influence material specifications, favoring lightweight concrete and specialized mixes. Production facilities in regions like Bavaria and North Rhine-Westphalia focus on engineering complex, custom precast elements for commercial and industrial applications.
United States
Large-scale infrastructure projects and complex commercial developments underpin precast demand across the United States. Compliance with state and local building codes, alongside guidelines from the Precast/Prestressed Concrete Institute, ensures structural integrity and market access. Major metropolitan areas like New York City and Los Angeles leverage precast for accelerated construction schedules and reduced on-site disruption in dense urban environments.
United Kingdom
Urban development and the need for rapid assembly methods drive precast adoption in the United Kingdom. National building regulations and evolving sustainability targets influence material choices and design specifications. London's construction sector particularly benefits from dry installation techniques for precast elements, minimizing disruption and accelerating project timelines in congested areas.
Ireland
The burgeoning data center sector significantly boosts demand for pre-engineered precast modules in Ireland. EU building regulations and the need for rapid deployment and consistent quality shape construction practices. Precast manufacturing in areas around Dublin and Cork supplies these specialized modules, ensuring swift and efficient project completion for critical digital infrastructure.
Precast Construction Market Key Industry Players
Concentration sits with large, integrated construction material suppliers and diversified construction groups, while specialized precast fabricators cater to niche applications. The market structure exhibits a tiered consolidation, where global players command extensive supply chains and regional firms focus on localized demand. Competitive moves include strategic partnerships for project execution and continuous investment in automated production capacities.
Within the global construction materials sector, LafargeHolcim Ltd. exemplifies a materials science-driven approach, developing specialized concrete mixes for high-performance precast elements. Skanska AB, a prominent construction and development company, integrates precast solutions directly into its large-scale project management services, leveraging its extensive project portfolio. CRH plc sustains its market position through a vast network of local production facilities, anchoring regional demand across diverse geographies.
| Leading Market Players |
|---|
| LafargeHolcim Ltd. |
| CRH plc |
| CEMEX S.A.B. de C.V. |
| Boral Limited |
| Oldcastle Infrastructure |
| Bouygues Construction |
| Forterra Inc. |
| Skanska AB |
| Tindall Corporation |
| Others |
Cost & Logistics Intelligence
Advanced concrete mixes with supplementary cementitious materials are displacing traditional concrete, simultaneously reshaping supply geography towards specialized producers and introducing sustainability-linked pricing premiums.
Pricing Analysis
Configured-to-order precast elements command a premium over standardized components, reflecting the customization-premium spread in the market. Project-based contracts define the dominant pricing model for large infrastructure and commercial ventures. Price differentiation stems from engineering complexity and compliance with certifications like CE marking in Europe. Cost compression in standard precast elements intensifies due to high capital investment for automated facilities. Infrastructure projects exhibit lower price sensitivity compared to residential developers focusing on cost-effective housing solutions.
Supply Chain Analysis
India and China anchor global precast material production, drawing heavily from localized sand and aggregate resources. The market's raw material dependencies include cement and steel reinforcement for structural integrity. Logistics chokepoints for transporting large, heavy precast elements represent a significant structural risk. Distribution primarily runs through direct-to-project site delivery, often managed by integrated construction firms or specialized precast fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Precast Construction Market presents a service-attach opportunity, with digital design integration and real-time monitoring expanding faster than core component sales.
For Market Incumbents:Consolidate fragmented regional operations to achieve economies of scale, mitigating margin pressure from commodity-grade components. Invest in advanced material science research and development for specialized concrete mixes. Acquire specialized software firms to enhance BIM integration capabilities, countering emerging digital design platforms. Capacity addition in Indian urban centers leverages government housing initiatives.
For New Entrants and Emerging Players:CE marking fast-track certification offers a rapid entry point for firms specializing in sustainable precast elements. Target white-space opportunities in data center modules and smart components with embedded sensors. The most penetrable segment lies in specialized, high-performance elements for European commercial projects. Collaborative contracting models provide a strong go-to-market angle for early engagement in project design.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors technology-driven specialists with strong intellectual property in automation. Long-term viability is strong, driven by urbanization and infrastructure deficits over the next decade. Mid-sized fabricators with advanced BIM integration capabilities represent an attractive acquisition target. Increased government spending on smart city initiatives serves as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Addresses rapid urbanization and government housing initiatives in India. |
| Digital Design Integration | Enhances efficiency and customization for complex projects in Germany. |
| Sustainable Material R&D | Aligns with EU Green Deal mandates for circular economy principles. |
| Specialized Module Development | Captures growth in data center construction, particularly in Ireland. |
| Collaborative Contracting Models | Optimizes manufacturability and reduces project timelines for US infrastructure. |
Research Approach
A standing panel of precast engineers, construction project managers, material scientists, and urban planners provided ongoing calibration for market trends. Primary interviews with these industry stakeholders informed qualitative insights and validated market dynamics. Secondary validation drew from industry association reports, government infrastructure spending reports, and corporate sustainability disclosures, ensuring a robust bottom-up and top-down triangulation.
Consistency checks validated market volume and value outputs against external benchmarks from national construction statistics. The analytical framework modeled market segmentation across product type, application, material, installation method, and regional regulatory frameworks over the projection horizon. Compound annual growth rates were derived from historical data analysis and projected demand, incorporating urbanization rates and infrastructure investment indices as key forecast inputs.
Underlying assumptions cover stable regulatory environments and sustained infrastructure spending, with deviation risk concentrated in raw material price volatility. Forecasts reflect these assumptions, acknowledging potential shifts from unforeseen economic downturns or policy changes. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Vietnam Construction Market
Building Construction
North America Construction Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Global Modular Fabrication Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
Middle East Building Construction Market
Building Construction
Egypt Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Saudi Arabia Construction Market
Building Construction
Tanzania Construction Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Egypt Residential Construction Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Guatemala Construction Market
Building Construction
Thailand Construction Market