
 Lightweight Precast Wall Panel Market | 2026-2036
Lightweight Precast Wall Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Lightweight Precast Wall Panel Market Foresight
Prefabricated installation services is consolidating around equipment-leasing and site-coordination packages that shift project risk from contractors to panel suppliers. Xella Group leverages its aerated concrete expertise to anchor specification decisions among architects specifying passive-house envelopes. Elematic competes through automation-intensive production lines that sustain delivery precision across multi-phase Scandinavian developments. Cemex controls raw material flows into captive precast operations, extending cost visibility from cement batching through panel curing.
Lightweight precast wall panels are factory-cast concrete elements with reduced density achieved through expanded polystyrene cores, autoclaved aerated concrete, or engineered hollow sections, typically weighing 30-50% less than conventional precast while maintaining structural load capacity for mid-rise construction. Their primary purpose is to accelerate building envelope assembly, reduce crane capacity requirements, and improve thermal performance in climates with stringent energy codes. Insulated panels lead specification volumes in residential and commercial structures where thermal bridging penalties now shape building permit approvals. Solid panels dominate industrial facilities requiring fire-rated separation walls without complex core fabrication. Decorative panels command margin premiums in architect-driven commercial structures where facade expressiveness determines competitive bidding outcomes.
The EU Green Deal and national implementations of the Energy Performance of Buildings Directive shape product standards across member states, with ECHA REACH compliance governing resin and additive chemistries in panel binders. Germany's KBA and federal building codes, alongside Nordic passive-house certification protocols, create multi-layer compliance requirements that filter market access for non-European suppliers. Buyers and specifiers must monitor how the EU AI Act and emerging digital product passport mandates alter documentation burdens for cross-border panel procurement within the European single market.
Market Dynamics
The EU Green Deal's tightening operational carbon limits for buildings is compressing specification timelines and forcing residential developers toward thermally efficient envelope systems that accelerate permit approvals.
Growth Catalysts
- EU Green Deal carbon limits:Tightening operational carbon thresholds for buildings in Germany and Scandinavia are accelerating procurement of insulated precast panels over conventional masonry.
- Passive house standards:Nordic markets with extended heating seasons are structurally preferring thermally efficient panels that eliminate thermal bridging penalties in building permit processes.
- Automation-intensive production:Precision manufacturing lines are sustaining delivery reliability across multi-phase Scandinavian residential developments where schedule certainty commands premium pricing.
Market Restraints
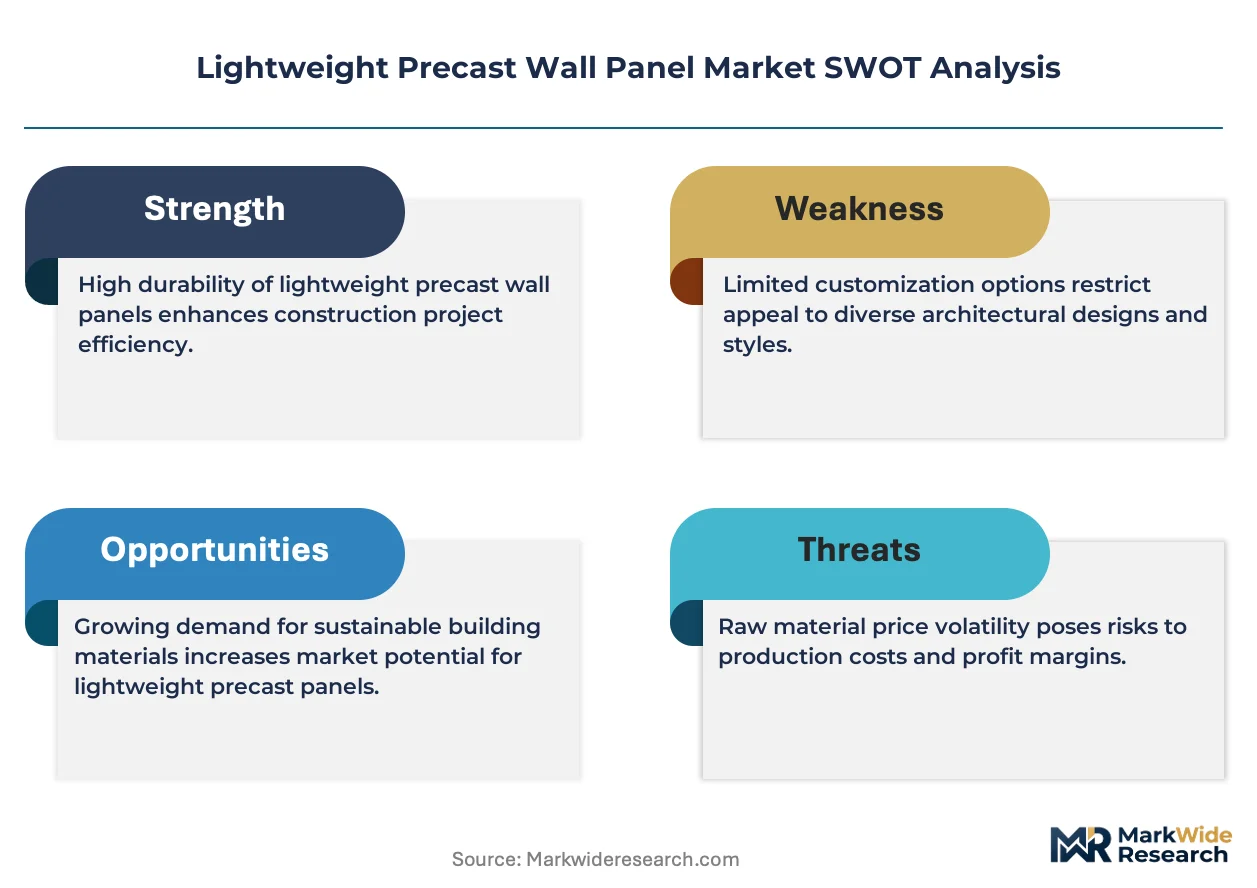
- Raw material cost volatility:Cement and expanded polystyrene core inputs face price instability that compresses margin visibility for panel manufacturers without captive supply arrangements.
- ECHA REACH compliance:Resin and additive chemistries in panel binders face multi-layer documentation requirements that filter market access for non-European suppliers.
- Crane capacity substitution:On-site cast-in-place alternatives with lower transport costs retain specification share in markets without strict thermal performance mandates.
Strategic Opportunities
- Digital product passport mandates:Emerging EU documentation requirements for cross-border procurement create first-mover advantages for suppliers with integrated traceability systems.
- Industrial fire-rated separation walls:Solid panel categories without complex core fabrication face underpenetrated demand in logistics and manufacturing facilities requiring rapid compartmentalization.
- Architect-driven commercial facades:Decorative panel specifications in commercial structures command margin premiums where facade expressiveness determines competitive bidding outcomes.
Industry Challenges
- Passive-house certification timelines:Multi-layer compliance requirements across Germany's KBA, federal building codes, and Nordic certification protocols extend pre-qualification cycles for new entrants.
- Site-coordination skill gaps:Equipment-leasing and risk-shifting installation packages require project management capabilities that contractor networks in peripheral markets have not yet developed.
- EU AI Act documentation burdens:Cross-border panel procurement within the European single market faces evolving algorithmic transparency requirements that complicate automated specification tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightweight Precast Wall Panel Market |
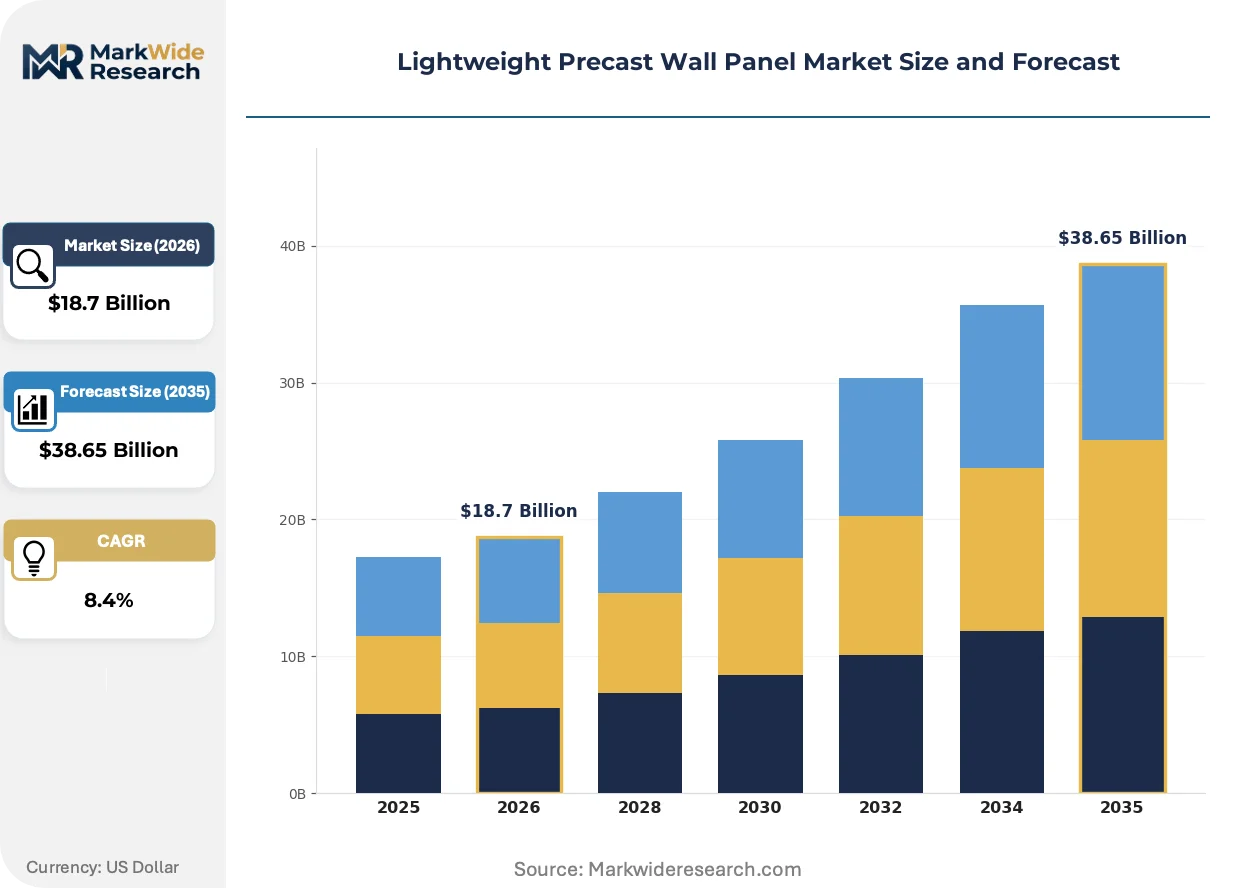
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Panels, Solid Panels, Decorative Panels, Structural Panels Application: Residential Buildings, Commercial Structures, Industrial Facilities, Infrastructure Projects End User: Contractors, Architects, Developers, Builders Installation Method: Traditional, Modular, Prefabricated, Innovative Systems |
| Companies Covered | Clear Corporation, RASTRA, Xella Group, Betoniluoma, Elematic, CSR Limited, K Block Technology, Dukane Precast, Cemex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightweight Precast Wall Panel Market Shifts & Advancements
Factory-cast concrete elements with reduced density are reshaping competitive positioning around thermal performance credentials rather than structural capacity alone. Specification decisions increasingly hinge on envelope energy modeling outputs.
Autoclaved aerated concrete and engineered hollow sections are consolidating specification authority in mid-rise residential construction. German and Scandinavian developers are adopting these systems at accelerating pace to meet passive-house certification thresholds. The technology is compressing market share for conventional masonry by eliminating thermal bridging penalties that now shape permit approvals.
ECHA REACH compliance and the EU AI Act are layering new documentation obligations onto resin chemistries and cross-border procurement workflows. Industrial consequence includes extended pre-qualification timelines for suppliers without integrated traceability infrastructure. Nordic markets with stringent passive-house protocols are responding fastest by consolidating procurement around established European suppliers with compliant supply chains.
Equipment-leasing and site-coordination packages are displacing traditional contractor risk allocation in panel installation. Multi-phase Scandinavian developments are leading this shift by demanding delivery precision that only supplier-controlled logistics can guarantee. Germany's federal building code enforcement is amplifying the preference for integrated service contracts that bundle thermal performance warranties with structural supply.
Lightweight Precast Wall Panel Market Segmentation
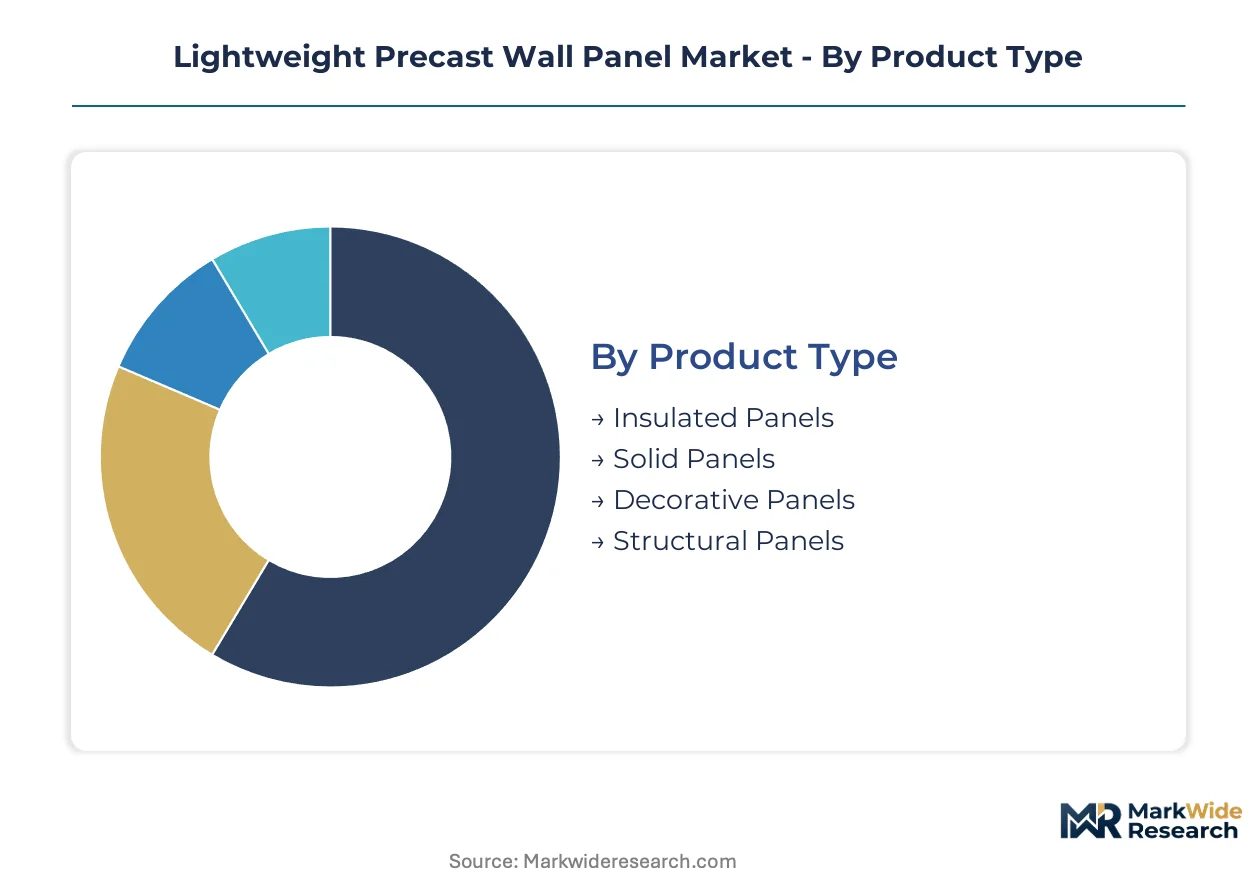
Segmentation in the lightweight precast wall panel market reveals how thermal performance mandates, installation complexity, and specification authority fragment demand across distinct buyer profiles. Understanding these divisions exposes where margin concentration and volume scale diverge.
Product Type:
Buyers differentiate primarily by thermal performance requirements versus structural load demands, with envelope energy modeling now filtering specification authority.
- Insulated Panels:Factory-cast concrete elements with expanded polystyrene or mineral wool cores achieve 30-50% weight reduction while eliminating thermal bridging penalties. German and Scandinavian residential developers specify these systems to compress passive-house certification timelines under EU Green Deal carbon limits.
- Solid Panels:Dense concrete formulations without core fabrication prioritize fire-rated separation and acoustic dampening over thermal efficiency. Industrial facilities in logistics and manufacturing clusters specify solid panels for rapid compartmentalization where operational carbon thresholds do not constrain permit approvals.
- Decorative Panels:Architecturally finished surfaces command specification in commercial facades where expressiveness determines competitive bidding outcomes.
- Structural Panels:Load-bearing configurations integrate reinforcement for mid-rise construction without secondary framing systems.
Volume sits with insulated panels; growth tilts toward decorative panels as commercial facade competition intensifies.
Application:
Specification cycles compress where building codes enforce operational carbon limits, extending timelines where thermal performance remains optional.
- Residential Buildings:Multi-phase Scandinavian developments demand delivery precision that automation-intensive production lines sustain. Passive-house standards in Nordic markets structurally prefer thermally efficient panels over conventional masonry due to extended heating seasons.
- Commercial Structures:Architect-driven bidding processes prioritize facade expressiveness and envelope energy modeling outputs. Germany's federal building code enforcement amplifies preference for integrated service contracts bundling thermal performance warranties with structural supply.
- Industrial Facilities:Fire-rated separation walls without complex core fabrication face underpenetrated demand in logistics and manufacturing sectors.
- Infrastructure Projects:Public procurement timelines and crane capacity requirements filter specification toward standardized panel dimensions.
Residential commands current volume; commercial applications are climbing the fastest as permit approval pressures mount.
End User:
Risk allocation preferences separate buyers who control installation logistics from those who delegate site coordination to suppliers.
- Contractors:Equipment-leasing and site-coordination packages shift project risk from traditional contractor networks to panel suppliers, demanding project management capabilities that peripheral markets have not yet developed.
- Architects:Specification authority concentrates among passive-house envelope specialists who anchor decisions through aerated concrete expertise and thermal bridging elimination credentials.
- Developers:Procurement timelines compress as EU Green Deal carbon limits tighten, forcing consolidation around suppliers with compliant supply chains and integrated traceability infrastructure.
- Builders:On-site assembly skill gaps in modular and prefabricated methods constrain uptake in markets without established installation networks.
Developers drive procurement volume; architects are gaining share fastest as envelope energy modeling shapes permit outcomes.
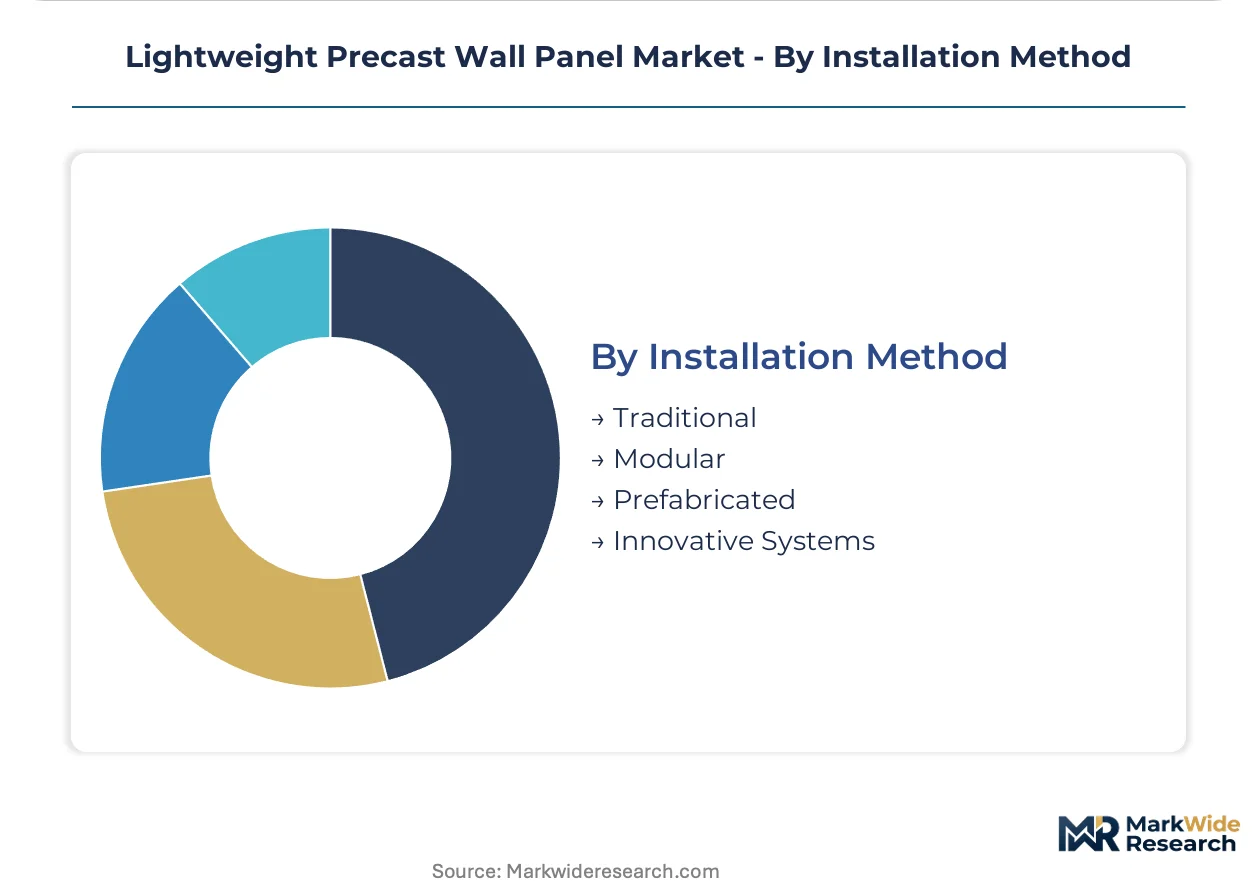
Installation Method:
Delivery precision requirements and crane capacity constraints fragment adoption across markets with varying logistics infrastructure maturity.
- Traditional:Crane-dependent placement with on-site adjustment retains specification share where transport costs favor local cast-in-place alternatives.
- Modular:Pre-integrated envelope systems reduce on-site labor but require supplier-controlled logistics that only established European networks guarantee.
- Prefabricated:Equipment-leasing packages displace contractor risk allocation in multi-phase Scandinavian developments demanding schedule certainty.
- Innovative Systems:Emerging automated positioning and digital twin coordination face extended pre-qualification cycles under evolving EU AI Act documentation burdens.
Prefabricated methods capture expanding share; innovative systems face steepest expansion trajectory once algorithmic transparency requirements stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European precast panel demand, with Dortmund-based fabricators supplying thermally efficient envelope systems to passive-house developments across North Rhine-Westphalia. Automation-intensive production lines in this cluster sustain delivery precision for multi-phase residential projects.
Germany
Residential developers in Bavaria and Baden-Württemberg are expanding procurement of insulated precast panels as KBA enforcement tightens operational carbon limits. The EU Green Deal's national implementation through federal building codes compresses specification timelines toward thermally efficient systems. Stuttgart's architectural practices anchor specification decisions for passive-house envelopes across southwestern industrial clusters.
Sweden
Extended heating seasons in Nordic markets structurally prefer thermally efficient panels over conventional masonry for mid-rise residential construction. National implementations of the Energy Performance of Buildings Directive filter procurement toward suppliers with ECHA REACH-compliant supply chains. Stockholm's developer consortiums consolidate procurement around integrated service contracts bundling thermal performance warranties with structural supply.
Finland
Passive-house certification protocols in Helsinki and Tampere metropolitan areas accelerate specification of autoclaved aerated concrete panels. ECHA REACH compliance requirements for resin chemistries extend pre-qualification cycles for non-European suppliers. The Oulu industrial corridor concentrates fabrication capacity serving Arctic climate envelope demands.
Norway
Building permit processes in Oslo and Bergen now hinge on envelope energy modeling outputs that eliminate thermal bridging penalties. EU Green Deal carbon thresholds compress procurement timelines for thermally efficient envelope systems. Trondheim's construction clusters demand delivery precision that automation-intensive production lines guarantee across multi-phase developments.
Denmark
Copenhagen's residential developers face stringent energy code enforcement that accelerates adoption of factory-cast concrete elements with expanded polystyrene cores. Nordic passive-house standards create multi-layer compliance requirements filtering market access. Aarhus manufacturing zones supply thermally efficient panels to cross-border developments in southern Sweden.
Lightweight Precast Wall Panel Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market consolidating around equipment-leasing and site-coordination packages. Integrated cement-to-panel manufacturers control raw material flows through captive supply arrangements, while specialized envelope fabricators anchor specification authority through aerated concrete expertise. Two strategic archetypes dominate: vertically integrated building materials conglomerates and automation-focused precast specialists. Competitive moves center on backward integration into cement batching operations and geographic expansion through multi-phase Scandinavian development contracts.
Among European-based fabricators, Xella Group and Elematic occupy positions within the automation-intensive tier, while Cemex represents the vertically integrated archetype extending cost visibility from upstream materials through panel curing. These three companies exemplify how distinct capital structures—specialized precast technology versus captive raw material control—compete for specification authority in thermally efficient envelope markets.
| Leading Market Players |
|---|
| Clear Corporation |
| RASTRA |
| Xella Group |
| Betoniluoma |
| Elematic |
| CSR Limited |
| K Block Technology |
| Dukane Precast |
| Cemex |
| Others |
Supply & Pricing Matrix
Passive-house certification timelines in Germany and Scandinavia are compressing procurement cycles toward suppliers with captive cement operations and integrated thermal performance warranties, concentrating pricing power among vertically integrated producers while squeezing asset-light fabricators.
Pricing Analysis
Cost-down pressure on insulated panel tiers accelerates because ECHA REACH compliance investments and automation-intensive production lines concentrate supply among established European producers. Pricing stratifies across premium certified passive-house systems, standard code-compliant envelopes, and economy-grade solid panels without core fabrication. Brand premiums attach to aerated concrete specialists with documented thermal bridging elimination credentials. Buyers in industrial solid panel segments exhibit highest price sensitivity where fire-rated separation lacks energy code mandates.
Supply Chain Analysis
Dual-sourcing mandates from Stockholm and Copenhagen developer consortiums require panel suppliers to maintain qualified backup fabrication capacity across Germany, Sweden, and Finland. Raw material flows draw from captive cement batching operations, expanded polystyrene core suppliers, and autoclaved aerated concrete mineral feedstocks. Single-source vulnerability concentrates in Nordic markets where Arctic climate specifications limit qualified supplier pools. Distribution runs through project-specific equipment-leasing packages bundling site-coordination with structural delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lightweight precast wall panel market sits in a technology-transition phase where autoclaved aerated concrete and engineered hollow sections displace conventional masonry in thermally regulated envelopes.
For Market Incumbents: Deepen backward integration into cement batching operations to defend margin visibility against raw material volatility. Expand automation-intensive production capacity in the Ruhr corridor and Oulu industrial cluster to sustain delivery precision for multi-phase Scandinavian developments. Anchor specification authority through aerated concrete expertise as passive-house certification protocols tighten. For New Entrants and Emerging Players: Enter via industrial solid panel segments in logistics and manufacturing facilities where fire-rated separation demand remains underpenetrated and thermal performance mandates do not constrain permit approvals. Target Central European markets with equipment-leasing service packages that shift project risk from contractor networks to suppliers. Qualify ECHA REACH-compliant supply chains before attempting Nordic procurement. For Investors and Strategic Acquirers: The window for entry favors automation-focused precast specialists with established passive-house certification credentials over vertically integrated building materials conglomerates with legacy masonry exposure. Long-term viability hinges on digital product passport infrastructure readiness under emerging EU mandates. The signal to watch is consolidation velocity among Scandinavian developer consortiums demanding integrated service contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cement Operations | Cemex extends cost visibility from raw material batching through panel curing. |
| Automation-Intensive Production Expansion | Elematic sustains delivery precision across multi-phase Scandinavian residential developments. |
| Passive-House Certification Investment | Xella Group anchors specification authority among architects specifying thermally efficient envelopes. |
| Equipment-Leasing Service Bundling | Supplier-controlled logistics displace traditional contractor risk allocation in Nordic markets. |
| Digital Product Passport Infrastructure | Integrated traceability systems create first-mover advantages under emerging EU documentation mandates. |
Research Methodology
Independent corroboration across primary interviews with plant managers, procurement leads at residential developers, technical R&D directors, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from EU Green Deal implementation documents, ECHA REACH compliance filings, federal building code amendments, and Nordic passive-house certification protocols. Bottom-up demand modeling triangulates against top-down production capacity assessments across the analysis window.
Comparable-period anchoring to historical envelope energy modeling adoption rates and thermal performance code enforcement timelines structures the forecast framework. Segmentation dimensions span product type, application, end user, and installation method. CAGRs derive from installed base evolution and replacement cycle dynamics in thermally regulated construction markets. Industry-specific inputs include cement price indices, crane capacity utilization rates, and passive-house certification velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA regulatory amendments or EU AI Act documentation requirement accelerations. Model assumptions reflect current EU Green Deal implementation trajectories and Nordic building code enforcement patterns. A model refresh is warranted upon material change in federal carbon limit thresholds or digital product passport mandate effective dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
Global Builders Joinery and Carpentry of Wood Market
Building Materials
Composite Rebar Market
Building Materials
Natural Stone Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Foam Bricks Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Polymer Concrete Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Global Building Panels Market
Building Materials
Latin America Aluminum Door and Window Market