
 Global Fiber Cement Siding Market | 2026-2036
Global Fiber Cement Siding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiber Cement Siding Market Analysis
The capital-intensity divergence between integrated manufacturers and regional assemblers is collapsing as automated pressing lines lower entry thresholds for mid-scale entrants. James Hardie Industries plc leverages captive cellulose sourcing and proprietary curing technology to sustain margin leadership across North American distribution. Etex Group anchors its European position through dense regional plant networks that compete effectively on logistics costs against imports. Nichiha Corporation differentiates via architectural-grade surface finishes that occupy premium specification channels in Japanese commercial construction.
Fiber cement siding comprises a composite building material manufactured from Portland cement, silica sand, cellulose fibers, and water, pressed into sheets or boards under high pressure and autoclave-cured to achieve dimensional stability and moisture resistance. Its primary commercial purpose is to provide durable, fire-resistant exterior cladding that mimics wood grain or stucco aesthetics while requiring minimal maintenance over multi-decade service lives. Pre-formed panels lead product type volumes in commercial applications where large facade areas demand efficient installation, while boards dominate residential replacement cycles driven by contractor familiarity and retrofit compatibility. The residential application segment sustains the deepest demand pool as homeowners prioritize wildfire and moisture resilience, though institutional projects represent the fastest-growing specification channel for extended warranties and lifecycle cost accounting.
The EPA regulates silica dust exposure during fiber cement cutting through OSHA Permissible Exposure Limits, while the EU Green Deal's embodied carbon reporting requirements under CSRD are forcing manufacturers to document kiln energy inputs and transport emissions across supply chains. California's Title 24 Building Energy Efficiency Standards and the International Wildland-Urban Interface Code collectively mandate non-combustible exterior cladding in designated fire hazard zones, directly expanding addressable demand for fiber cement systems. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional wildfire code expansions to determine capacity allocation between standard and fire-rated product lines.
Market Dynamics
Automated pressing line diffusion is collapsing capital barriers between integrated manufacturers and regional assemblers, redrawing competitive boundaries across production scale tiers. This technology democratization is compressing margin premiums historically captured by proprietary curing systems and captive cellulose supply chains.
Growth Catalysts
- Wildfire-resistant building codes:California's Title 24 and the International Wildland-Urban Interface Code mandate non-combustible exterior cladding in designated hazard zones, directly expanding specification volume for fiber cement systems in high-risk residential zones.
- OSHA silica exposure limits:The EPA's Permissible Exposure Limits for respirable crystalline silica during fiber cement cutting are redirecting contractor workflows toward pre-cut panel systems and dust-controlled installation methods.
- Hurricane-prone coastal construction:Residential developers in Florida and Gulf Coast states are specifying impact-resistant fiber cement cladding to meet stringent wind-load requirements and insurance mitigation incentives.
Market Restraints
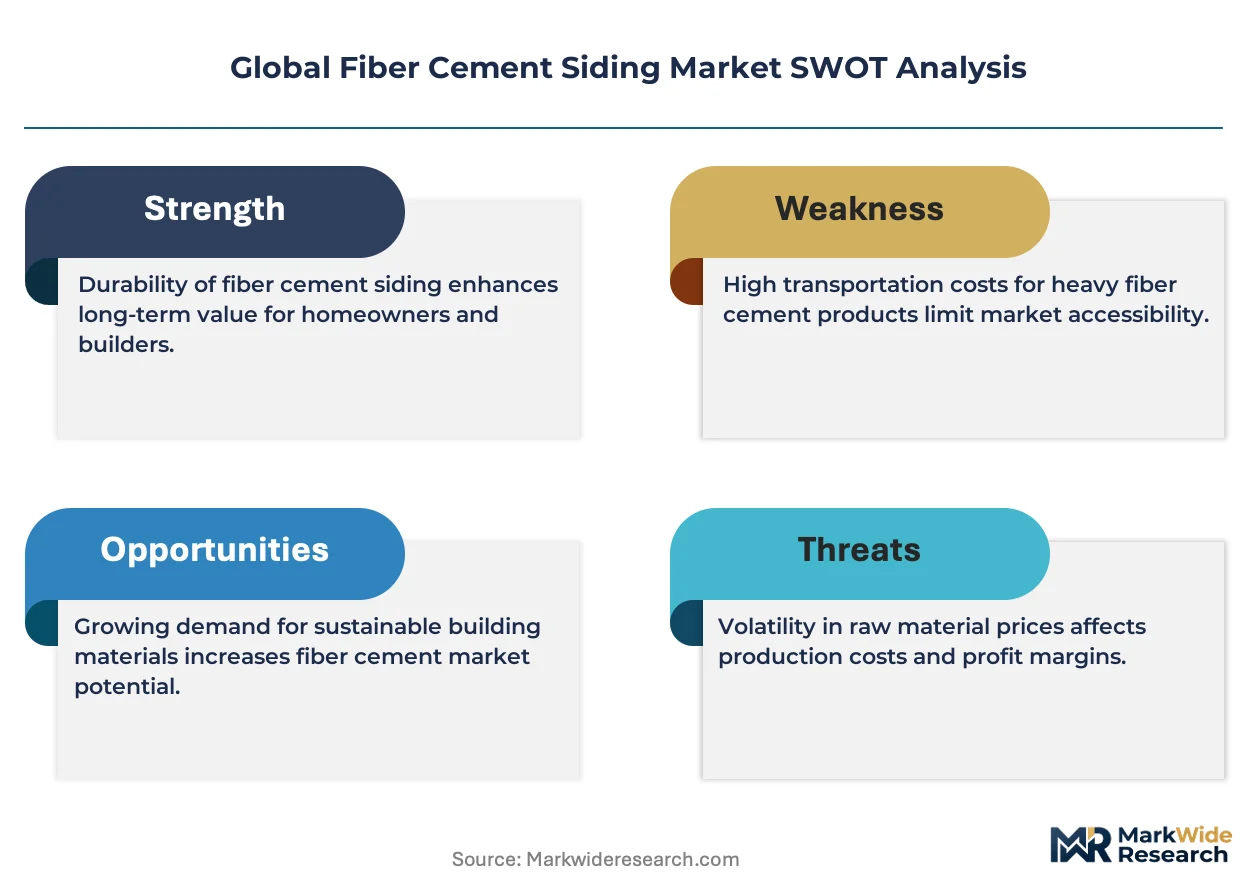
- Portland cement price volatility:Energy-intensive kiln operations and carbon border adjustment exposure in European trade corridors are compressing input cost predictability for manufacturers without backward integration into clinker production.
- Cellulose fiber supply concentration:Specialty pulp sourcing remains concentrated among Nordic and North American suppliers, creating vulnerability to freight cost spikes and trade flow disruptions.
- Silica dust litigation exposure:Contractor liability frameworks in the United States are elevating insurance costs and slowing adoption among small-scale residential installers without capital for dust suppression equipment.
Strategic Opportunities
- EU Green Deal embodied carbon reporting:The CSRD's supply chain disclosure requirements are creating first-mover advantage for manufacturers with documented kiln energy efficiency and transport emission transparency.
- Prefabricated modular construction:Offsite panel manufacturers in Germany and the Netherlands are integrating fiber cement cladding into factory-built envelope systems, opening specification channels outside traditional contractor relationships.
- Commercial facade lifecycle contracting:Institutional buyers in Japanese and Australian markets are shifting toward extended warranty and performance-guarantee procurement models that favor fiber cement's multi-decade durability claims.
Industry Challenges
- Autoclave curing technician scarcity:Specialized kiln operation and pressure-vessel maintenance expertise is concentrating among aging workforces in mature manufacturing regions, constraining plant expansion timelines.
- Multi-jurisdiction certification complexity:Fire-rated product lines require parallel testing to UL 263, EN 13501, and JIS A 1304 standards, extending product development cycles and fragmenting R&D allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiber Cement Siding Market |
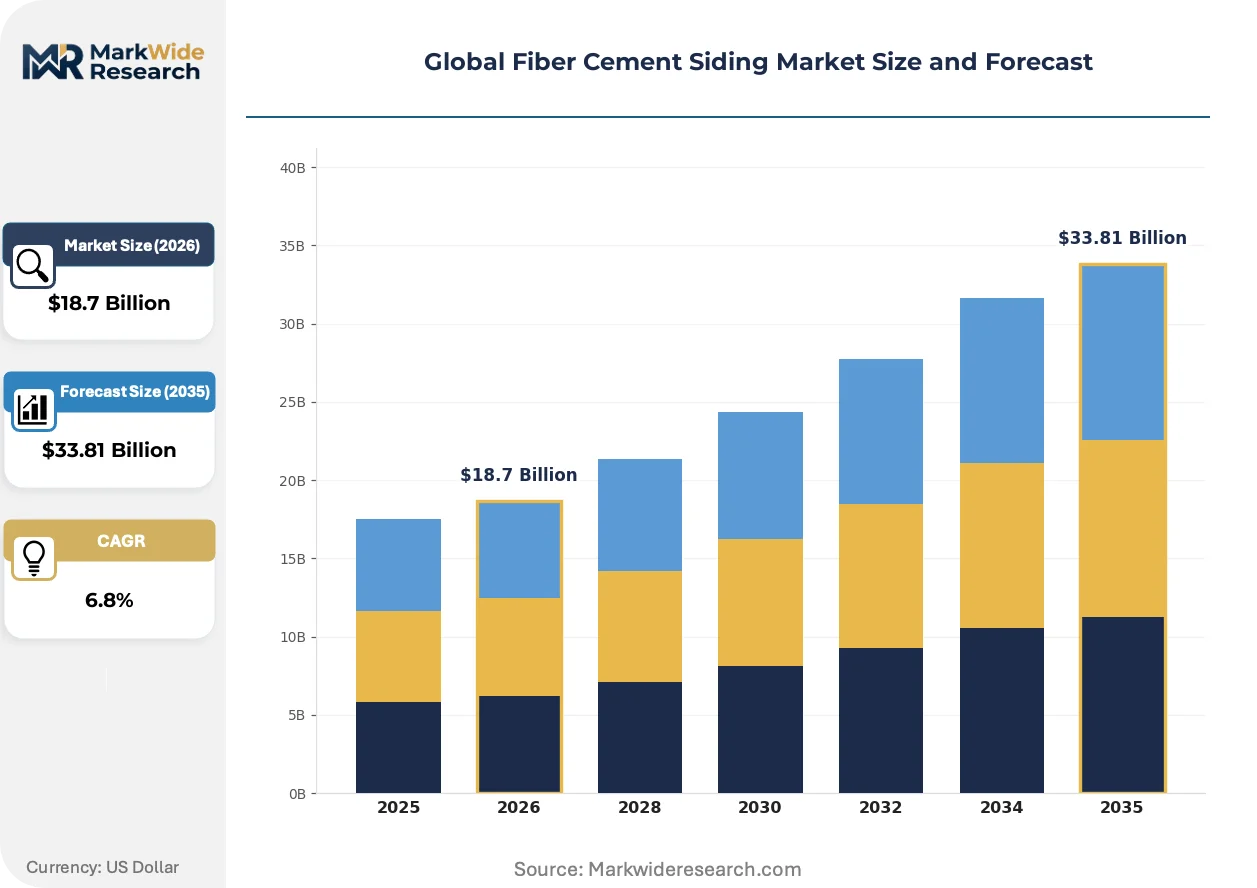
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-formed Panels, Boards, Backer Boards, Trim Application: Residential, Commercial, Industrial, Institutional End User: Contractors, Builders, Architects, DIY Enthusiasts Connection Type: Direct, Overlap, Tongue and Groove, Others |
| Companies Covered | James Hardie Industries plc, Etex Group, Nichiha Corporation, CSR Limited, Saint-Gobain, Allura, CertainTeed, The Siam Cement Public Company Limited, Swisspearl Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiber Cement Siding Market Emerging Trajectories
Surface finishing technology and curing process automation are splitting the market into architectural-grade specification channels and commodity residential replacement flows. This divergence is reshaping how manufacturers allocate capital between premium aesthetics and volume throughput.
Digital printing and through-color fiber cement formulation is bifurcating product positioning. High-end commercial developers in Japan and Australia are specifying architectural-grade surface finishes that replicate natural stone and wood grain with UV-stable mineral pigments. This technology compression is eroding premium capture for traditional pre-painted systems while opening specification channels previously dominated by natural materials.
The EU Green Deal's embodied carbon reporting requirements under CSRD are forcing kiln energy disclosure across supply chains. Manufacturers with documented renewable energy inputs in Nordic production corridors are securing preferred supplier status in Dutch and German public procurement frameworks. This regulatory pressure is accelerating capital allocation toward electric curing and biomass heat recovery systems.
Contractor procurement patterns are consolidating around pre-cut panel systems and direct-to-job-site logistics. Large residential developers in Florida and Texas are bypassing traditional distributor markups through volume direct agreements with manufacturers. This channel compression is most visible in hurricane-prone zones where just-in-time delivery and impact-rated product bundling reduce field labor exposure.
Global Fiber Cement Siding Market Segmentation
Fiber cement siding demand fragments across installation formats, building types, and procurement channels. Each segment carries distinct margin profiles and regulatory exposure that reshape manufacturer capacity allocation.
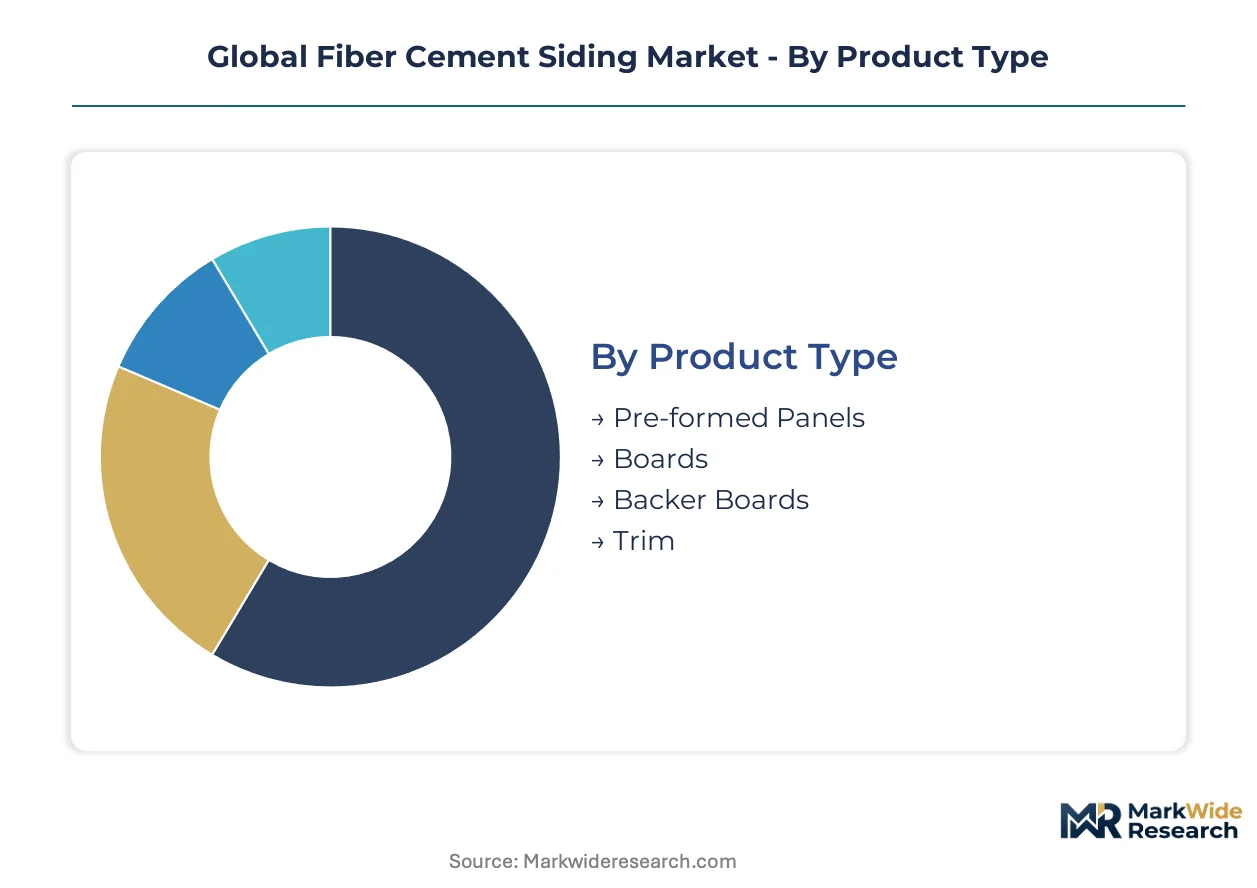
Product Type:
Domestic production dominates boards and backer boards, while pre-formed panels flow through specialized export corridors serving modular construction hubs.
- Pre-formed Panels:Factory-cured sheets with integrated fastening channels reduce field labor exposure in commercial facades. Demand concentrates in German and Dutch offsite manufacturing clusters where dust-controlled panel integration accelerates envelope assembly timelines.
- Boards:Long-format planks with wood-grain embossing constitute the volume backbone of residential replacement cycles. California and Colorado wildfire codes mandate non-combustible exterior finishes, redirecting contractor specification toward cement-board systems over vinyl alternatives.
- Backer Boards:Thin-profile underlayment panels provide moisture-resistant substrates for tile and stone veneers in wet-zone construction.
- Trim:Pre-molded corner and fascia components complete aesthetic systems with color-matched finishes.
Boards hold the largest share; momentum sits with pre-formed panels.
Application:
Cost tier separation runs deepest here: residential replacement competes on installed price, while institutional procurement optimizes lifecycle cost accounting.
- Residential:Single-family and multifamily exterior cladding sustains the deepest demand pool through hurricane and wildfire resilience priorities. Florida developers specify impact-rated fiber cement to meet insurance mitigation incentives and stringent wind-load requirements.
- Commercial:Office and retail facades favor large-format panels with architectural-grade surface finishes. Japanese commercial construction channels absorb premium specification volumes through extended warranty procurement models.
- Industrial:Warehouse and manufacturing envelope systems prioritize durability over aesthetics in high-particulate environments.
- Institutional:Schools, hospitals, and government buildings represent the steepest expansion trajectory as lifecycle contracting displaces lowest-bid procurement.
Residential commands volume leadership; institutional procurement is climbing the fastest.
End User:
Customer type determines channel economics: contractors capture distributor markups, while direct-to-builder agreements compress margins in exchange for volume certainty.
- Contractors:Small-scale residential installers drive replacement-cycle throughput but face elevated insurance costs from silica dust litigation exposure.
- Builders:Large developers in Texas and Florida bypass traditional distribution through volume direct agreements with manufacturers, securing just-in-time delivery and impact-rated product bundling.
- Architects:Specification influence concentrates in Japanese and Australian commercial markets where surface finish technology opens channels previously dominated by natural materials.
- DIY Enthusiasts:Home improvement retailers serve maintenance-conscious homeowners with pre-cut panel systems and dust-suppressed cutting accessories.
Builders absorb the largest volume; architects drive premium specification share.
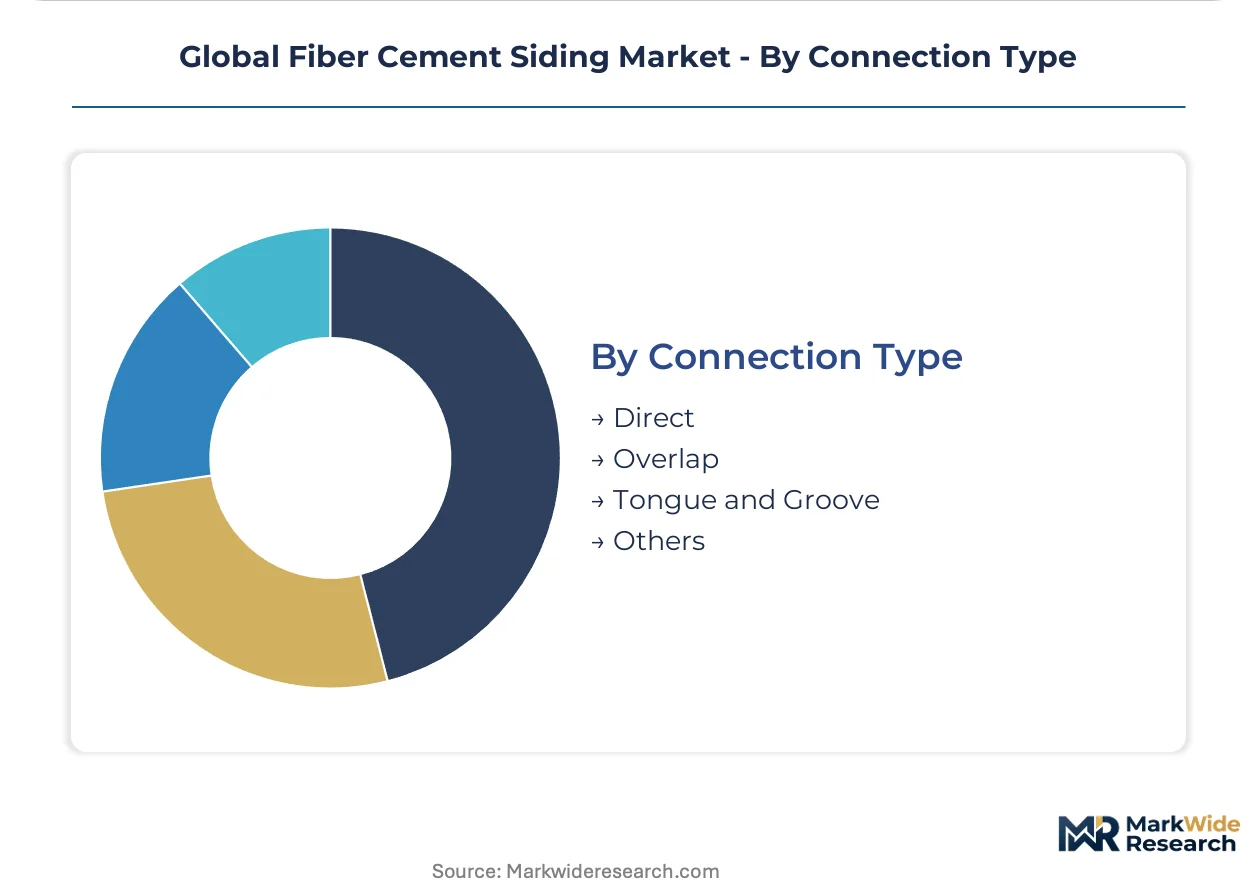
Connection Type:
Installation method selection tracks regional contractor training and code enforcement stringency.
- Direct:Face-fastened systems dominate North American residential retrofit where familiarity and tool availability accelerate crew productivity.
- Overlap:Shiplap-style horizontal installation provides weather resistance in coastal zones with pronounced wind-driven rain exposure.
- Tongue and Groove:Interlocking vertical edges reduce fastener visibility and improve thermal bridging performance in high-efficiency building envelopes.
- Others:Clip-mounted and concealed-fastener systems serve architectural-grade commercial applications requiring clean sightlines.
Direct fastening retains the largest installed base; tongue and groove systems are gaining specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in European corridors by a substantial margin, driven by wildfire code mandates and hurricane insurance incentives that compress buyer price sensitivity. German and Dutch markets compete primarily on logistics efficiency and embodied carbon transparency, eroding margin premiums available elsewhere.
United States
California's Title 24 Building Energy Efficiency Standards and the International Wildland-Urban Interface Code mandate non-combustible exterior cladding in designated fire hazard zones. The EPA's Lead-Safe Renovation, Repair and Painting Rule redirects contractors toward full fiber cement replacement systems. Florida developers in Miami-Dade and Tampa Bay corridors specify impact-rated cladding to meet stringent wind-load requirements and secure insurance mitigation incentives.
Germany
Offsite modular construction hubs in the Ruhr region and Bavaria absorb pre-formed panel volumes for factory-built envelope systems. The EU Green Deal's embodied carbon reporting requirements under CSRD force kiln energy disclosure, favoring manufacturers with documented renewable inputs. Eindhoven-adjacent Dutch-German border clusters integrate fiber cement into prefabricated facade assemblies for just-in-time delivery to Benelux commercial projects.
Japan
Commercial construction channels in Tokyo and Osaka prioritize architectural-grade surface finishes with extended warranty procurement models. METI-backed building efficiency standards elevate lifecycle cost accounting over lowest-bid selection. Nagoya-based manufacturing corridors supply premium specification volumes through dense regional plant networks competing on logistics costs against imports.
Australia
Institutional buyers in Sydney and Melbourne shift toward performance-guarantee contracting that favors multi-decade durability claims. The country's national building regulator enforces non-combustible cladding mandates in high-rise residential zones following facade fire incidents. Queensland coastal developers specify impact-resistant systems for cyclone-prone construction zones.
China
Dual carbon goals under national climate commitments pressure kiln energy intensity in Shandong and Jiangsu production corridors. The Ministry of Ecology and Environment monitors silica dust exposure limits in manufacturing operations. Yangtze River Delta clusters serve domestic commercial facade demand while facing carbon border adjustment exposure in European export channels.
Global Fiber Cement Siding Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary curing systems and captive cellulose supply chains sustaining margin premiums for integrated manufacturers while automated pressing lines democratize entry for mid-scale regional assemblers. The market structure concentrates around three tiers: multinational integrated producers with backward integration into specialty pulp, regional plant networks competing on logistics density, and automated mid-scale entrants exploiting collapsed capital barriers. Dominant competitive moves include capacity expansion in wildfire-code expansion zones and strategic partnerships with offsite modular construction hubs.
Within the integrated multinational tier, James Hardie Industries plc and Etex Group exemplify divergent geographic anchoring strategies, with the former representing North American captive sourcing models and the latter embodying European logistics-density competition. Nichiha Corporation occupies a position within the architectural-grade specialization vector, serving premium commercial specification channels through surface finish differentiation. Among these archetypes, technology licensing and regional plant network densification represent the primary vectors for competitive positioning.
| Leading Market Players |
|---|
| James Hardie Industries plc |
| Etex Group |
| Nichiha Corporation |
| CSR Limited |
| Saint-Gobain |
| Allura |
| CertainTeed |
| The Siam Cement Public Company Limited |
| Swisspearl Group |
| Others |
Supply Flow & Price Mechanics
Autoclave curing capacity utilization above 85 percent in Nordic and North American corridors creates margin leverage for integrated manufacturers while forcing regional assemblers toward price-competitive commodity tiers. This scale asymmetry concentrates pricing power among producers with captive cellulose sourcing and proprietary kiln technology, compressing returns for mid-scale entrants dependent on spot pulp markets.
Pricing Analysis
The customization-premium spread separates architectural-grade surface finishes from standard residential boards by a factor reflecting certification tier and warranty duration. Three-tier pricing structure across premium, standard, and economy levels tracks UL 263 fire ratings, JIS A 1304 compliance, and volume scale. Cost compression in the economy tier is intensifying because automated pressing lines democratize entry for regional assemblers. Large residential developers in Florida and Texas exhibit lowest price sensitivity due to insurance mitigation incentives, while small-scale contractors in replacement cycles face acute margin pressure from silica dust compliance costs.
Supply Chain Analysis
The United States and Germany anchor fiber cement production through James Hardie Industries plc and Etex Group plant networks, while China serves domestic commercial facade demand from Shandong and Jiangsu corridors. Specialty cellulose pulp draws from Nordic and North American suppliers, Portland cement rests on clinker production in energy-intensive kiln operations, and silica sand feeds from regional quarries. Single-source vulnerability concentrates in specialty pulp sourcing, where freight cost spikes disrupt margin predictability. Distribution runs through direct-to-builder agreements in hurricane-prone zones and traditional distributor networks in residential replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized autoclave curing expertise is concentrating among aging workforces, constraining plant expansion timelines and creating acquisition leverage for holders of technical talent pipelines. This capability bottleneck favors early movers in kiln automation and pressure-vessel maintenance training.
For Market Incumbents: Secure captive cellulose supply through long-term offtake agreements with Nordic pulp producers to insulate against freight volatility. Expand autoclave curing capacity in California and Colorado wildfire-code expansion zones before regional assemblers achieve scale. Channel control through direct-to-builder agreements in Florida and Texas defends margin position against distributor markups. For New Entrants and Emerging Players: Dust-controlled installation services represent an under-served layer where incumbents lack dedicated contractor support infrastructure. Target institutional procurement channels in Japan and Australia through extended warranty bundling and lifecycle cost accounting tools. A go-to-market angle through offsite modular construction hubs in Germany and the Netherlands bypasses traditional contractor relationships entirely. For Investors and Strategic Acquirers: Regional plant networks with dense logistics coverage in European corridors offer consolidation leverage against import competition. Long-term viability hinges on embodied carbon transparency under CSRD disclosure requirements, favoring targets with documented renewable energy inputs. The signal to watch is carbon border adjustment mechanism implementation in European trade corridors, which would revalue domestic production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Curing Automation | Reduces labor dependency while compressing cycle times for mid-scale entrants. |
| Captive Cellulose Supply Agreements | Insulates margin structure from Nordic pulp freight volatility and trade flow disruptions. |
| Wildfire-Code Zone Capacity Expansion | Captures California and Colorado mandate-driven demand before competitor saturation. |
| Embodied Carbon Certification Investment | Secures preferred supplier status under EU Green Deal public procurement frameworks. |
| Offsite Modular Construction Partnerships | Opens specification channels in German and Dutch factory-built envelope clusters. |
Methodological Framework
Initial hypotheses were tested against primary input from plant operations directors, procurement leads at residential developers, distribution channel partners, and technical R&D directors in surface finishing, then refined through secondary validation. Bottom-up and top-down triangulation combined regulatory filings from EPA and METI, customs and trade data on cellulose pulp flows, SEC 10-K disclosures from listed manufacturers, and building code adoption tracking from California Title 24 and the International Wildland-Urban Interface Code.
Variance decomposition across the projection horizon isolates volume drivers by product type, application segment, end-user archetype, and regional regulatory cluster. CAGRs derive from installed base modeling, replacement cycle frequency, and code mandate expansion trajectories. Industry-specific forecast inputs include wildfire hazard zone mapping, hurricane insurance mitigation incentive programs, and embodied carbon disclosure compliance timelines under CSRD.
Underlying assumptions cover continued wildfire code expansion in western United States corridors, sustained Portland cement price volatility, and stable Nordic pulp trade flows, with deviation risk concentrated in carbon border adjustment implementation and silica dust litigation exposure. Recalibration cycles align with material shifts in building code adoptions, kiln energy disclosure requirements, and automated pressing line diffusion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Composite Rebar Market
Building Materials
GRC Cladding Market
Building Materials
Global Pozzolan Market
Building Materials
Mass Timber Construction Market
Building Materials
Qatar Cement Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Geocells Market
Building Materials
North America Concrete Admixtures Market
Building Materials
North America Cement Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Roof Cover Boards Market
Building Materials
Qatar Facade Market
Building Materials
India Concrete Admixtures Market
Building Materials
Recycled Construction Aggregates Market