
 US Steel Merchant and Rebar Market | 2026-2036
US Steel Merchant and Rebar Market Size, Share, and Industry Trends Forecast 2026-2036
US Steel Merchant and Rebar Market Intelligence
Data center construction is restructuring demand patterns within the US steel merchant and rebar sector, pulling tonnage toward hyperscale facilities and their supporting power infrastructure. Nucor Corporation leverages its electric arc furnace network to serve this surge with lower-carbon product lines. Steel Dynamics anchors Southwest and Southeast supply corridors through its Texas and Alabama mill complexes. Commercial Metals Company extends its vertical reach from recycling through fabrication, capturing margin at multiple value chain points.
Steel merchant and rebar encompasses semi-finished and finished long steel products—merchant bars in angles, channels, and flats; rebar in grades 40, 60, and 75 with specified yield strengths; wire rods for downstream drawing; and sheet piles for earth retention—produced via electric arc or basic oxygen furnace routes and rolled to ASTM A615, A706, or A992 specifications. Rebar commands the largest volume share within product type segmentation due to its irreplaceable role in concrete reinforcement across vertical and horizontal structural elements. High-strength steel grades within material grade segmentation attract premium positioning as engineers specify Grade 80 and Grade 100 rebar to reduce congestion in high-load columns and seismic zones. The contractor end user segment dominates procurement volume, though industrial manufacturers represent a more stable, contract-backed demand pool with less cyclical exposure.
OSHA workplace safety mandates and ASTM International material standards govern mill operations and product certification, while the Buy America provisions of the Infrastructure Investment and Jobs Act restrict federal project eligibility to domestically melted and poured steel. EPA emissions regulations under the Clean Air Act push producers toward scrap-based electric arc furnace routes and carbon capture retrofits at integrated mills. Stakeholders must monitor evolving EPA greenhouse gas performance standards and state-level low-embodied-carbon procurement rules that will reshape supplier qualification criteria and capital allocation priorities across the forecast horizon.
Market Dynamics
Federal infrastructure spending under the Infrastructure Investment and Jobs Act is restructuring steel merchant and rebar demand toward domestic melt-and-pour sourcing, while electric arc furnace technology adoption compresses production costs and carbon intensity among domestic mills.
Growth Catalysts
- IIJA highway and bridge mandates:Federal project eligibility rules under the Buy America provisions require domestically melted and poured steel, locking in rebar volume for federally funded construction through 2026 and beyond.
- Data center power infrastructure:Hyperscale facility construction across Texas, Virginia, and Arizona is pulling merchant bar tonnage toward electrical substation foundations and transmission tower fabrication.
- Seismic retrofit codes:California and Pacific Northwest building standards are specifying Grade 80 and Grade 100 high-strength rebar to reduce column congestion in high-load zones.
Market Restraints
- Scrap price volatility:Electric arc furnace operators face margin compression when shredded auto scrap and busheling prices spike above $400 per gross ton.
- Gulf Coast supply concentration:Over half of domestic electric arc furnace long steel capacity sits within 300 miles of Houston, creating hurricane exposure and logistics bottlenecks.
- Carbon capture retrofit costs:Integrated mills with basic oxygen furnaces face $150-300 million capital outlays to meet emerging EPA greenhouse gas performance standards.
Strategic Opportunities
- State-level low-embodied-carbon procurement:California Buy Clean rules and New York CLCPA implementation are creating premium market tiers for EAF-produced rebar with verified carbon intensity below 0.5 tons CO2 per ton steel.
- Microgrid and battery storage foundations:Merchant bar demand is emerging from utility-scale lithium-ion and flow battery installations requiring specialized anchoring systems.
- Direct-to-contractor digital platforms:Fabricators are bypassing traditional distributor networks through proprietary e-procurement portals that bundle cutting, bending, and jobsite delivery.
Industry Challenges
- Certified welder and rebar detailer shortages:ACI certification backlogs and aging craft workforce are extending project lead times for complex seismic and high-rise applications.
- ASTM A706 weldability compliance:Chemistry control for low-carbon equivalent rebar requires tighter scrap segregation and ladle metallurgy investments that strain mid-tier mill capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Steel Merchant and Rebar Market |
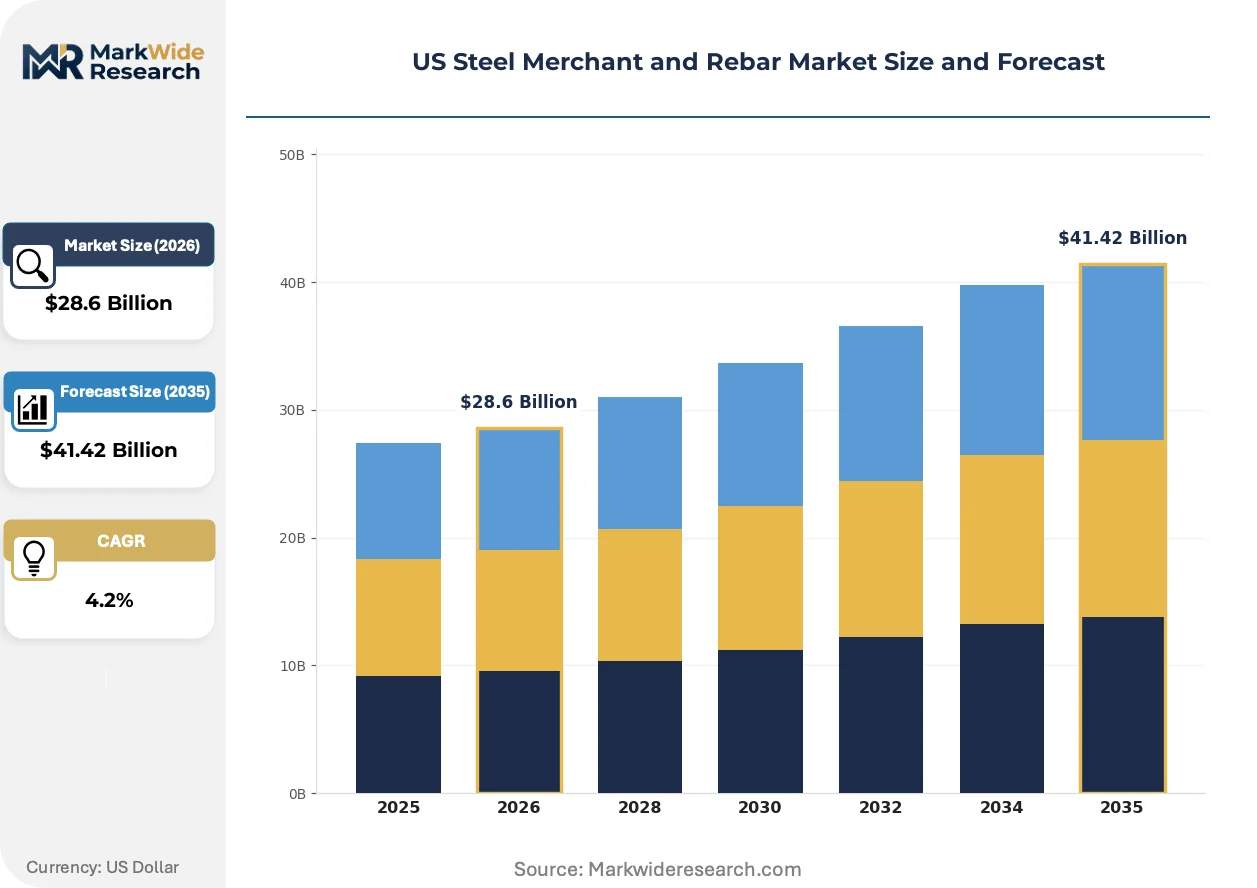
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $41.42 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Merchant Bars, Rebar, Wire Rods, Sheet Piles Application: Construction, Infrastructure, Manufacturing, Mining End User: Contractors, Industrial Manufacturers, Fabricators, Retailers Material Grade: Low-Alloy Steel, High-Strength Steel, Carbon Steel, Stainless Steel |
| Companies Covered | Nucor Corporation, Commercial Metals Company, Steel Dynamics, Gerdau North America, U.S. Steel Corporation, EVRAZ North America, ArcelorMittal USA, NIPPON STEEL CORPORATION, Radius Recycling, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Steel Merchant and Rebar Market Strategic Shifts & Innovations
Electrification of construction equipment and carbon accounting transparency are rewriting material specifications and procurement protocols across the US steel merchant and rebar value chain.
High-strength low-alloy rebar is expanding into data center and logistics warehouse construction as structural engineers specify Grade 80 and Grade 100 products to reduce rebar congestion in high-load columns. General contractors on hyperscale projects in Northern Virginia and Phoenix are accepting 15-20% material cost premiums for these grades. The technology is expanding into mid-rise commercial and industrial segments previously served by conventional Grade 60 rebar.
EPA greenhouse gas performance standards under the Clean Air Act are forcing integrated mills to accelerate electric arc furnace transitions or install carbon capture systems at basic oxygen furnace complexes. The industrial consequence is a bifurcation in domestic supply between scrap-based EAF producers and carbon-intensive integrated mills facing compliance deadlines. Rebar procurement teams at state DOTs and federal agencies are responding with embodied carbon scoring requirements that favor EAF-sourced material.
Contractor procurement teams are consolidating vendor relationships around fabricators offering in-house rebar detailing, BIM integration, and just-in-time delivery rather than sourcing raw bar through multiple distributor tiers. The channel being disrupted is the traditional two-step distribution model of mill-to-distributor-to-contractor. This consolidation is most visible in Texas and Florida where megaproject volume justifies direct mill-fabricator partnerships bypassing regional steel service centers.
US Steel Merchant and Rebar Market Segmentation
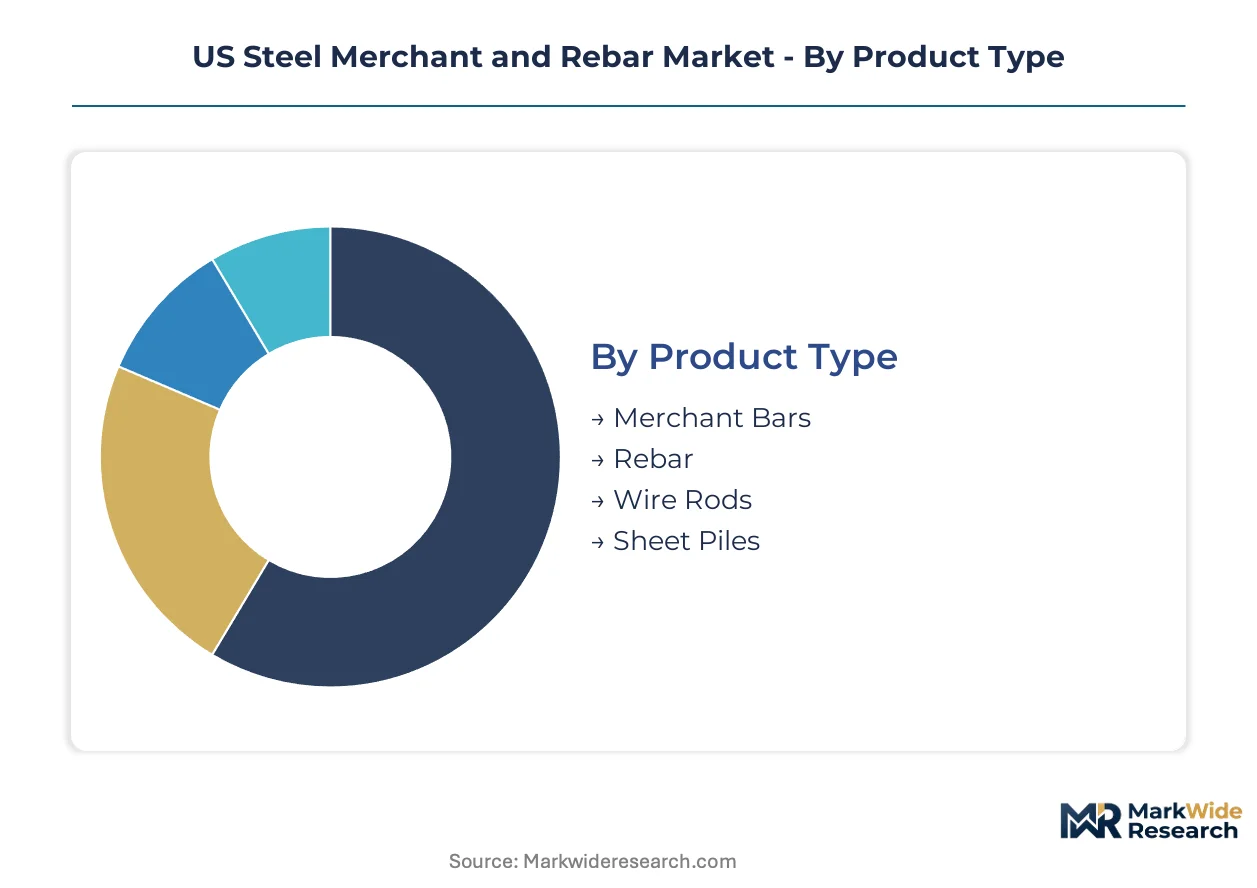
Steel merchant and rebar segmentation reveals divergent capital requirements across product types, with electric arc furnace investments reshaping competitive economics. Material grade specifications and end-user procurement patterns determine margin capture and capacity allocation priorities for domestic producers.
Product Type:
Merchant bars demand the heaviest rolling mill capital, while rebar production benefits from standardized geometries that compress equipment costs per ton.
- Merchant Bars:Angles, channels, flats, and rounds rolled to ASTM A36 and A529 specifications serve structural fabrication and equipment manufacturing. Demand concentrates in Texas and Ohio where machinery builders and metal fabricators cluster near mill complexes, driven by just-in-time delivery requirements from industrial OEMs.
- Rebar:Deformed steel bars in grades 40, 60, 75, 80, and 100 per ASTM A615 and A706 dominate concrete reinforcement applications. Federal highway and bridge projects across Florida and California absorb volume under Buy America sourcing mandates, with seismic retrofit codes accelerating Grade 80 and 100 adoption.
- Wire Rods:Coiled semi-finished products in 5.5-14mm diameters feed downstream drawing operations for fasteners, wire mesh, and prestressed concrete strand.
- Sheet Piles:Interlocking Z-section and U-section profiles for earth retention and marine bulkhead construction require specialized rolling stands and heat treatment.
Rebar absorbs the bulk of installed capacity; merchant bars are expanding most quickly amid data center and logistics construction surges.
Application:
Construction applications generate the steadiest volume throughput, while infrastructure projects carry the longest contract visibility and credit-backed payment terms.
- Construction:Vertical and horizontal concrete elements in commercial, residential, and industrial buildings specify rebar by the ton for foundations, columns, and floor slabs. Texas and Florida megaprojects pull tonnage toward high-rise and warehouse applications, with contractors consolidating procurement around fabricators offering BIM-integrated detailing.
- Infrastructure:Highway bridges, rail transit, and water treatment facilities under IIJA funding require domestic melt-and-pour certification. State DOTs in California and New York are imposing embodied carbon scoring that favors electric arc furnace material, reshaping supplier qualification pools.
- Manufacturing:Merchant bars and wire rods supply machinery frames, agricultural equipment, and automotive components with tighter dimensional tolerances than construction grades.
- Mining:Sheet piles and high-strength merchant bars serve shaft lining, ground support, and material handling structures in extraction operations.
Construction commands the greatest volume share; infrastructure is climbing the fastest on federal spending acceleration.
End User:
Contractor procurement behavior determines pricing power, with industrial manufacturers offering more stable, contract-backed demand pools.
- Contractors:General and specialty contractors on commercial and infrastructure projects purchase rebar through fabricators or direct mill relationships. Megaproject developers in Northern Virginia and Phoenix are bypassing traditional distributors for bundled cutting, bending, and delivery services.
- Industrial Manufacturers:Machinery builders, agricultural equipment producers, and automotive suppliers source merchant bars and wire rods under annual contracts with volume commitments and specification locks.
- Fabricators:Rebar detailers and benders capture margin between mill and jobsite, with OSHA-certified shops extending project lead times amid welder shortages.
- Retailers:Hardware chains and metal service centers stock standard merchant bar sizes for maintenance, repair, and small-scale construction.
Contractors absorb the bulk of tonnage; fabricators are gaining share fastest through direct-to-contractor digital platforms.
Material Grade:
High-strength grades command premium positioning but require tighter chemistry control and ladle metallurgy investments that strain mid-tier mill capabilities.
- Low-Alloy Steel:Microalloyed compositions with vanadium or niobium additions achieve strength through thermomechanical processing rather than heavy alloying, reducing welding complexity for field fabrication.
- High-Strength Steel:Grade 80 and Grade 100 rebar with yield strengths of 80 ksi and 100 ksi reduce congestion in high-load columns and seismic zones. California and Pacific Northwest building codes are specifying these grades for mid-rise commercial projects previously served by Grade 60.
- Carbon Steel:Conventional grades 40 and 60 per ASTM A615 dominate volume applications where weldability and ductility requirements are less stringent.
- Stainless Steel:Corrosion-resistant rebar and merchant bars serve marine environments, chemical plants, and bridge decks exposed to de-icing salts.
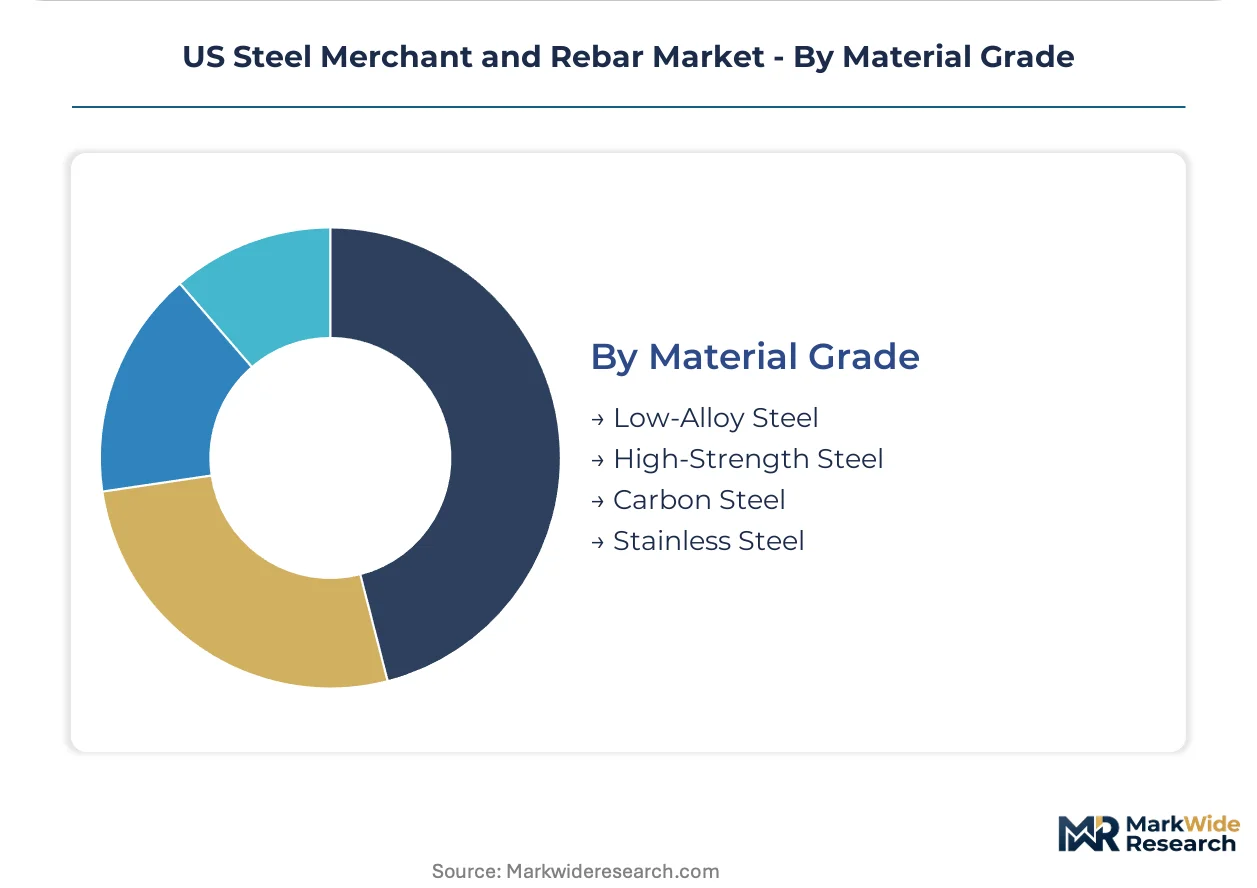
Carbon steel holds the greatest capacity allocation; high-strength steel is expanding most quickly on engineering specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Opportunity Zone tax incentives and state-level infrastructure accelerators are concentrating electric arc furnace capacity within 300 miles of Houston, reshaping domestic supply geography.
Texas Gulf Coast
Hyperscale data center construction across Dallas-Fort Worth and Austin is pulling merchant bar tonnage toward electrical substation foundations and transmission infrastructure. Buy America provisions under the Infrastructure Investment and Jobs Act lock in rebar volume for federally funded highway projects. The Beaumont-Port Arthur industrial corridor hosts concentrated EAF mill complexes serving both construction and energy sector demand.
Florida Peninsula
Seawall rehabilitation and bridge replacement programs are accelerating high-strength rebar consumption under state DOT specifications. Florida Department of Transportation mandates domestic melt-and-pour certification for all federal-aid projects, filtering supplier pools. The Miami-Orlando-Tampa triangle concentrates fabrication capacity serving coastal high-rise and infrastructure applications.
California
Seismic retrofit codes specifying Grade 80 and Grade 100 rebar are reducing column congestion in Los Angeles and San Francisco high-rises. California Air Resources Board Buy Clean rules create premium tiers for EAF-produced steel with verified carbon intensity below 0.5 tons CO2 per ton steel. The Central Valley logistics warehouse boom is pulling merchant bar demand toward distribution center foundations.
Midwest Manufacturing Belt
Automotive and agricultural equipment manufacturers in Ohio and Michigan source merchant bars under annual contracts with tighter dimensional tolerances than construction grades. EPA greenhouse gas performance standards are forcing integrated mills to accelerate EAF transitions or install carbon capture systems. The Chicago-Gary industrial corridor retains basic oxygen furnace capacity serving heavy fabrication and industrial OEMs.
Pacific Northwest
Bridge deck replacement and marine bulkhead construction in Washington and Oregon specify corrosion-resistant rebar grades for de-icing salt exposure. State procurement rules increasingly favor low-embodied-carbon material, reshaping supplier qualification pools. The Portland-Seattle corridor concentrates specialized fabrication serving seismic and marine applications.
US Steel Merchant and Rebar Market Key Industry Players
Top-tier vendors anchor integrated EAF-to-fabrication networks, while mid-tier operators concentrate on regional rebar supply and specialty merchant bar grades. The vendor base stratifies across three tiers: national-scale EAF producers with captive scrap supply, regional long steel specialists serving single-state markets, and fabrication-integrated distributors capturing margin through detailing and just-in-time delivery. Two dominant competitive moves define current positioning: backward integration into scrap recycling to secure feedstock cost control, and forward integration into rebar detailing and BIM-integrated fabrication services.
Among EAF-based national producers, Nucor Corporation and Steel Dynamics exemplify the scale-driven archetype with multi-state mill networks and vertical control from scrap through finished bar. Commercial Metals Company occupies a distinct position through its integrated recycling-to-fabrication model, capturing margin at multiple value chain points. These three companies represent the competitive template reshaping procurement relationships across Texas, Florida, and California megaprojects.
| Leading Market Players |
|---|
| Nucor Corporation |
| Commercial Metals Company |
| Steel Dynamics |
| Gerdau North America |
| U.S. Steel Corporation |
| EVRAZ North America |
| ArcelorMittal USA |
| NIPPON STEEL CORPORATION |
| Radius Recycling |
| Others |
Cost & Logistics Intelligence
Family-owned scrap processors and regional rebar fabricators anchor pricing discipline through captive shredding capacity and direct mill relationships, compressing margin capture for distributors caught between volatile shredded auto scrap costs and fixed-price highway contracts.
Pricing Analysis
Premium pricing for Grade 80 and Grade 100 rebar with sub-30-day lead times contrasts with spot-market discounts on standard Grade 60 inventory held at Gulf Coast service centers. Three-tier pricing structure across premium, standard, and economy levels separates EAF-produced low-carbon rebar certified under California Buy Clean rules from conventional BOF material and import alternatives. Cost compression in standard grades is intensifying because mid-tier mills lack ladle metallurgy investments to meet ASTM A706 chemistry control. Industrial manufacturers sourcing merchant bars under annual contracts exhibit the least price sensitivity, while small contractors on spot procurement face the most volatility.
Supply Chain Analysis
Shredded auto scrap supply rests on domestic automotive shredder operators concentrated in Ohio, Indiana, and Texas, with busheling feedstock drawing from Great Lakes manufacturing clusters. Electric arc furnace long steel production hinges on consistent shredded scrap flows, graphite electrode availability from Chinese and Indian producers, and ferroalloy additions for grade control. Single-source vulnerability runs through Gulf Coast EAF complexes exposed to hurricane disruption and barge logistics bottlenecks. Distribution runs through mill-direct fabricator partnerships bypassing traditional two-step distributors in Texas and Florida megaproject corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric arc furnace capacity constraints along the Gulf Coast prop rebar pricing power, with certified welder shortages extending project lead times and locking in fabricator margins.
For Market Incumbents: Hedge feedstock cost exposure through backward integration into scrap recycling or long-term shredding agreements with auto dismantlers. Accelerate ladle metallurgy investments to capture Grade 80 and Grade 100 specification upgrades displacing conventional rebar in seismic zones. Defensive positioning against import pressure requires Buy America certification maintenance and EPA emissions compliance ahead of emerging greenhouse gas performance standards. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer the most penetrable route around entrenched distributor networks in Texas and Florida. Target battery storage foundation and microgrid anchoring systems as white-space applications with specialized merchant bar specifications and limited incumbent focus. Go-to-market positioning should bundle BIM-integrated detailing with just-in-time delivery to capture fabricator margin. For Investors and Strategic Acquirers: California Air Resources Board enforcement actions against high-carbon intensity suppliers are the leading indicator that low-embodied-carbon procurement tiers will reshape supplier qualification pools and premium capture. Long-term viability favors EAF-based producers with verified carbon intensity below 0.5 tons CO2 per ton steel and captive scrap supply. Acquisition targets include regional fabricators with OSHA-certified shops and rebar detailing capabilities facing generational ownership transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Recycling | Captive shredded auto scrap supply locks in EAF feedstock cost control against Gulf Coast volatility. |
| Ladle Metallurgy Investment | ASTM A706 compliance enables Grade 80 and Grade 100 rebar premium capture in California seismic markets. |
| Direct-to-Contractor Digital Platform | BIM-integrated e-procurement bypasses distributor tiers in Texas and Florida megaproject corridors. |
| Low-Embodied-Carbon Certification | California Buy Clean and New York CLCPA compliance opens premium procurement tiers at state DOTs. |
| Fabricator Network Acquisition | OSHA-certified shops with detailing capabilities capture margin between mill and jobsite in supply-constrained markets. |
Research Approach
Document review covered EIA electricity consumption data, EPA Clean Air Act enforcement records, and FHWA Buy America compliance guidance, complemented by interviews with EAF plant managers, rebar fabricator operations heads, state DOT procurement officers, and general contractor supply chain directors. Secondary validation drew from SEC 10-K filings of listed steel producers, ACI certification databases, and ASTM standards documentation. Bottom-up capacity and demand modeling triangulated against top-down infrastructure spending allocation analysis.
Segment-level projections across product type, material grade, application, and end user dimensions were generated through econometric modeling of construction spending, infrastructure appropriations, and manufacturing activity indices across the analysis window. CAGRs were derived from regression analysis of historical demand elasticities and forward-looking capacity expansion announcements. Key forecast inputs included IIJA obligation rates by state, data center power infrastructure construction pipelines, and EAF technology adoption curves.
The model holds under sustained federal infrastructure funding and stable scrap supply conditions; deviation in hurricane frequency, trade remedy actions, or EPA emissions compliance deadlines would shift capacity utilization and pricing trajectories. Forecasts embed assumptions regarding certified welder workforce availability and state-level low-carbon procurement rule implementation. A small set of named triggers—Gulf Coast weather disruption, California Buy Clean enforcement intensity, and scrap export tariff adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
USA and Canada Fence Screen Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Europe Particle Board Market