
 Thermoplastic Composite Exterior Clips and Brackets Market | 2026-2036
Thermoplastic Composite Exterior Clips and Brackets Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Composite Exterior Clips and Brackets Market Insights
ISO 9001 and IATF 16949 qualification cycles are redrawing supplier eligibility across the thermoplastic composite exterior clips and brackets landscape. Nifco leverages its deep R&D intensity in resin formulation to secure long-term OEM contracts. ARaymond anchors European supply through captive manufacturing in France and strategic proximity to Renault and Stellantis assembly plants.
Thermoplastic composite exterior clips and brackets are injection-molded or over-molded fastening elements combining continuous or chopped fiber reinforcement with engineered polymer matrices, typically achieving 40-60% weight reduction versus stamped steel equivalents while maintaining clamp loads above 500 N. Their primary purpose is to secure exterior automotive panels and trim without galvanic corrosion or thermal expansion mismatch. Glass-fiber reinforced compositions dominate current volume owing to cost-performance balance, while carbon-fiber reinforced grades command premium positioning in electric vehicle architectures where every kilogram of mass reduction extends range. Push clips lead unit volume across application categories, though clamp brackets capture disproportionate margin pools due to structural load-bearing requirements and lower substitution threat from conventional materials.
EPA fuel-economy standards and the EU Green Deal's embodied carbon benchmarks are tightening simultaneously, forcing Tier-1 suppliers to document lifecycle emissions from resin pellet to molded component. NHTSA crashworthiness protocols further constrain material selection by mandating retention of exterior attachments under pedestrian-impact and low-speed collision scenarios. Stakeholders must monitor how forthcoming revisions to REACH substance restrictions and state-level zero-emission vehicle mandates in California reshape material qualification timelines and regional sourcing strategies.
Market Dynamics
Automotive OEMs are dismantling metal-centric fastening architectures as EPA fuel-economy mandates and EU Green Deal embodied-carbon benchmarks force material substitution at the component level.
Growth Catalysts
- EU Green Deal embodied-carbon benchmarks:Tier-1 suppliers must document lifecycle emissions from resin pellet to molded component, accelerating displacement of stamped steel brackets in exterior panel assemblies.
- Electric vehicle platform architectures:Range-extension imperatives prioritize every kilogram of mass reduction, elevating carbon-fiber reinforced grades to premium positioning in battery-electric vehicle programs.
- Germany's automotive manufacturing corridor:Concentrated OEM assembly activity around Stuttgart and Wolfsburg generates localized demand density that supports dedicated thermoplastic composite fastener production.
Market Restraints
- Resin and fiber input cost volatility:Polyamide and glass-fiber pricing fluctuates with petrochemical feedstock cycles, compressing margin predictability for injection molders operating on annual OEM price-down agreements.
- Tooling capex intensity:Multi-cavity molds for structural bracket geometries require hardened steel tooling investments that amortize poorly below 500,000-unit annual volumes.
- Galvanic corrosion substitution limits:Aluminum-intensive vehicle architectures retain metal fastening in high-thermal-load zones where polymer creep resistance remains insufficient.
Strategic Opportunities
- Carbon-fiber grade penetration in luxury EVs:Premium electric vehicle programs accept 3-4x material cost premiums for 15-20% additional mass reduction versus glass-fiber equivalents.
- REACH substance restriction revisions:Anticipated ECHA expansions to SVHC candidate list will disqualify certain metal coating chemistries, widening the addressable substitution window for polymer alternatives.
- Over-molding process convergence:Integration of continuous fiber inserts with chopped-fiber housings enables hybrid brackets that capture structural loads while maintaining snap-fit assembly economics.
Industry Challenges
- IATF 16949 certification timeline compression:OEM qualification cycles for new fastening platforms now demand 18-month PPAP completion, straining supplier engineering bandwidth.
- Resin formulation IP fragmentation:Proprietary glass-fiber sizing chemistries and impact-modifier packages create licensing friction between compounders and Tier-1 molders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Composite Exterior Clips and Brackets Market |
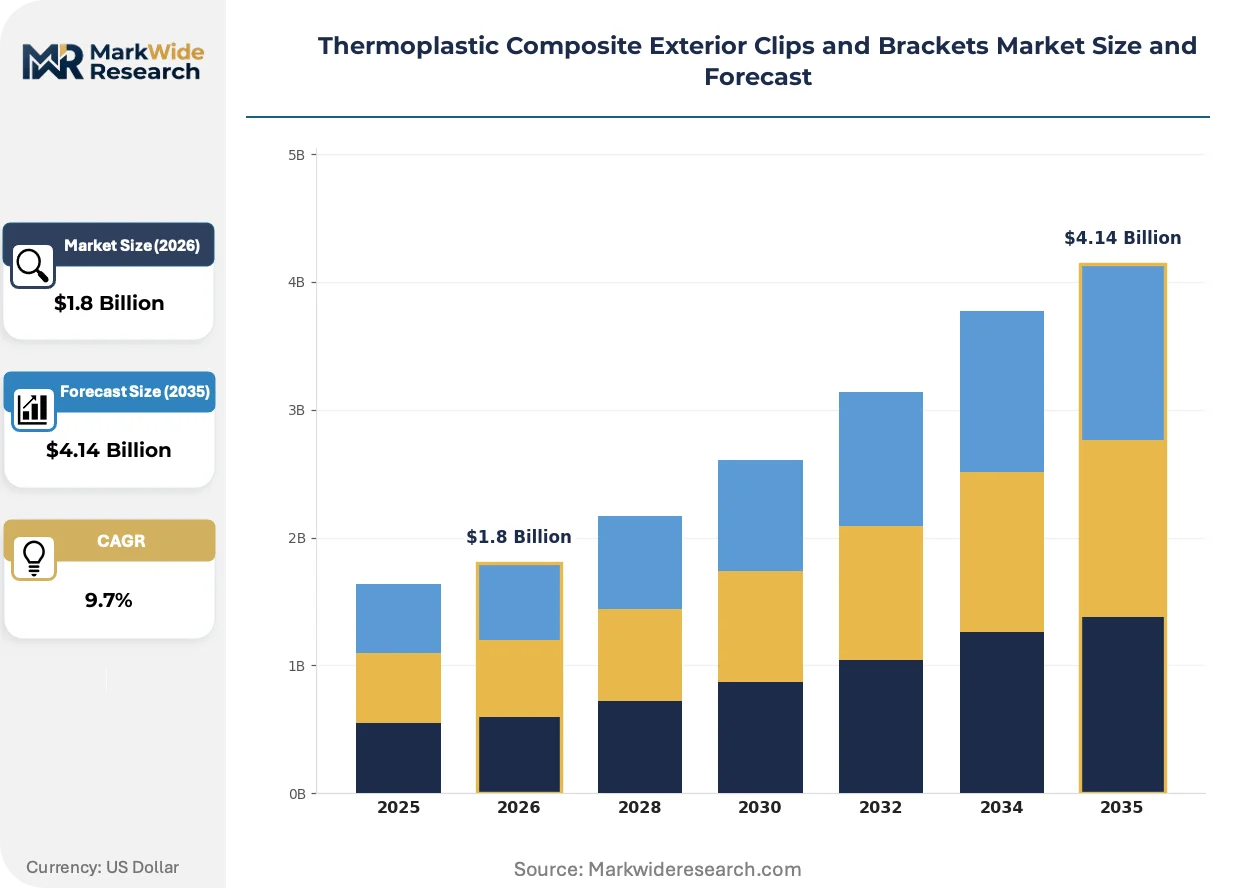
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push Clips, Screw Grommets, Spacer Clips, Clamp Brackets, Hook Clips Material Composition: Glass-Fiber Reinforced, Carbon-Fiber Reinforced, Mineral-Filled, Nylon-Based, Polypropylene-Based Application: Body Panels, Door Assemblies, Roof Molding, Window Frames, Fender Attachments End User Industry: OEM Manufacturers, Auto Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Nifco, ARaymond, ITW Automotive, Magna International, Flex-N-Gate, SMP Automotive, Novares, Tri-Mack Plastic Manufacturing, AVANKO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Composite Exterior Clips and Brackets Market Trends and Innovations
Material-process combinations are proliferating beyond commodity glass-fiber polyamide as OEMs segment fastening requirements by structural load, thermal exposure, and assembly automation compatibility.
Continuous fiber-reinforced thermoplastic (CFRTP) tapes are fragmenting the structural bracket category by enabling localized strength concentration in high-stress zones while maintaining injection-molding cycle economics for complex geometries. Battery-electric vehicle programs in Germany and California are adopting CFRTP hybrid brackets for bumper beam and fender attachment points. This technology is fragmenting the traditional glass-fiber dominated supply base into specialized tape suppliers, hybrid molding specialists, and commodity resin compounders with diverging capability investments.
ECHA REACH compliance is redrawing material qualification roadmaps by accelerating substitution away from hexavalent chromium-coated metal brackets toward polymer alternatives with documented substance safety dossiers. Automotive OEMs now mandate full material disclosure to 0.1% threshold for exterior fasteners, extending qualification timelines but locking in long-term thermoplastic composite share gains. European suppliers with captive resin formulation capabilities capture disproportionate contract renewals under this regulatory regime.
Consolidated procurement through OEM platform engineering teams is compressing supplier qualification from multi-year validation to single-source nomination with annual cost-reduction targets. Tier-1 fastening suppliers respond by offering design-to-cost engineering services that embed material selection and mold-flow optimization into early program development. This behavioral shift is most pronounced in German and US Midwest automotive manufacturing clusters where platform commonality spans multiple nameplates.
Thermoplastic Composite Exterior Clips and Brackets Market Segmentation
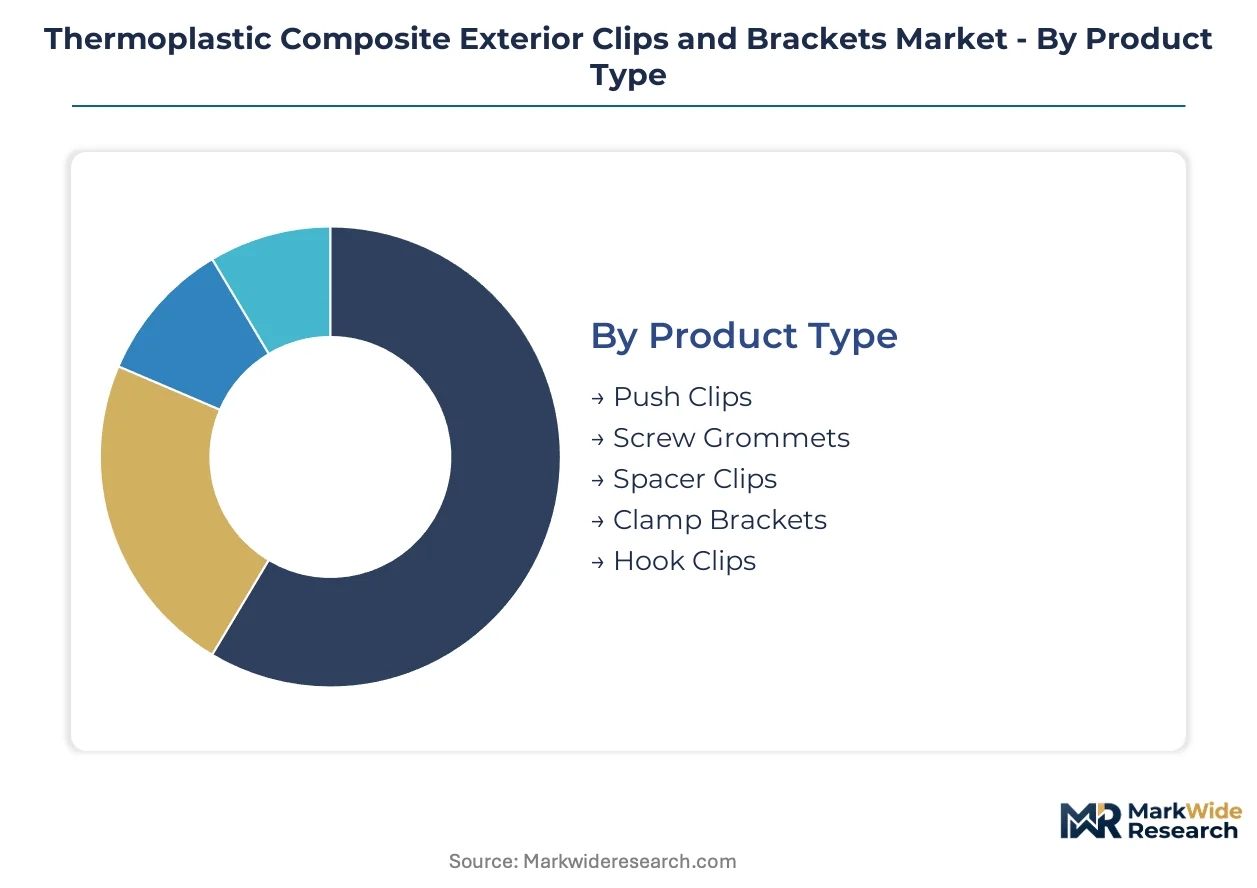
Thermoplastic composite exterior clips and brackets serve heterogeneous fastening requirements across vehicle architectures, from high-volume commodity push clips to structural load-bearing brackets. Segmentation reveals where material premiums command pricing power versus where resin cost minimization dominates supplier selection.
Product Type:
Margin pools concentrate in structural brackets that bear mechanical loads, while high-unit-volume clips compete on tooling efficiency and cycle-time economics.
- Push Clips:Injection-molded snap-fit fasteners combining chopped glass-fiber polyamide with flexible hinge geometries for tool-free panel attachment. Demand concentrates in German OEM assembly plants where automated clip installation reduces labor content per vehicle.
- Clamp Brackets:Structural fastening elements with continuous fiber reinforcement in high-stress zones, achieving clamp loads above 500 N for bumper beam and underbody shield retention. Stuttgart-area electric vehicle programs specify carbon-fiber grades for maximum mass reduction.
- Screw Grommets:Threaded inserts molded into composite housings for metal screw retention without galvanic corrosion.
- Spacer Clips:Standoff elements maintaining panel gap tolerances during thermal cycling.
- Hook Clips:J-shaped retention features for temporary assembly alignment before permanent fastening.
Clamp brackets hold installed capacity. Push clips are rotating up the share rankings.
Material Composition:
Cost tiers separate commodity glass-fiber formulations from carbon-fiber grades that capture 3-4x material premiums in luxury electric vehicle programs.
- Glass-Fiber Reinforced:Chopped E-glass in polyamide or polypropylene matrices delivering 40-50% weight reduction versus steel at mid-range cost. Wolfsburg-based volume manufacturers specify these grades for fender and door panel attachments where cost-performance balance prevails.
- Carbon-Fiber Reinforced:Continuous or long-fiber carbon in high-performance thermoplastics enabling 50-60% mass reduction for range-critical battery-electric architectures. California-based luxury EV assemblers absorb premium pricing to extend vehicle range.
- Mineral-Filled:Talc or calcium carbonate loading for dimensional stability and acoustic damping.
- Nylon-Based:Polyamide 6 and 66 formulations with moisture-resistant grades for underhood exposure.
- Polypropylene-Based:Lower-density options for interior-facing exterior trim with reduced thermal load requirements.
Glass-fiber reinforced compounds dominate current volume. Carbon-fiber reinforced grades are climbing the fastest.
Application:
Application segmentation tracks where thermal exposure, structural load, and cosmetic visibility create divergent material specifications.
- Body Panels:Large-surface exterior closures requiring uniform fastening density to prevent oil-canning and wind noise. ECHA REACH substance restrictions are accelerating displacement of metal brackets in Stuttgart-manufactured vehicles.
- Door Assemblies:Multi-point retention systems integrating water management channels and wiring harness routing.
- Roof Molding:Low-profile clips with UV-stabilized finishes for cosmetic trim retention.
- Window Frames:Precision-tolerance fasteners maintaining glass alignment across temperature extremes.
- Fender Attachments:Quick-release features for collision repair accessibility in insurance-regulated markets.
Body panels capture the broadest specification range. Door assemblies are expanding most quickly.
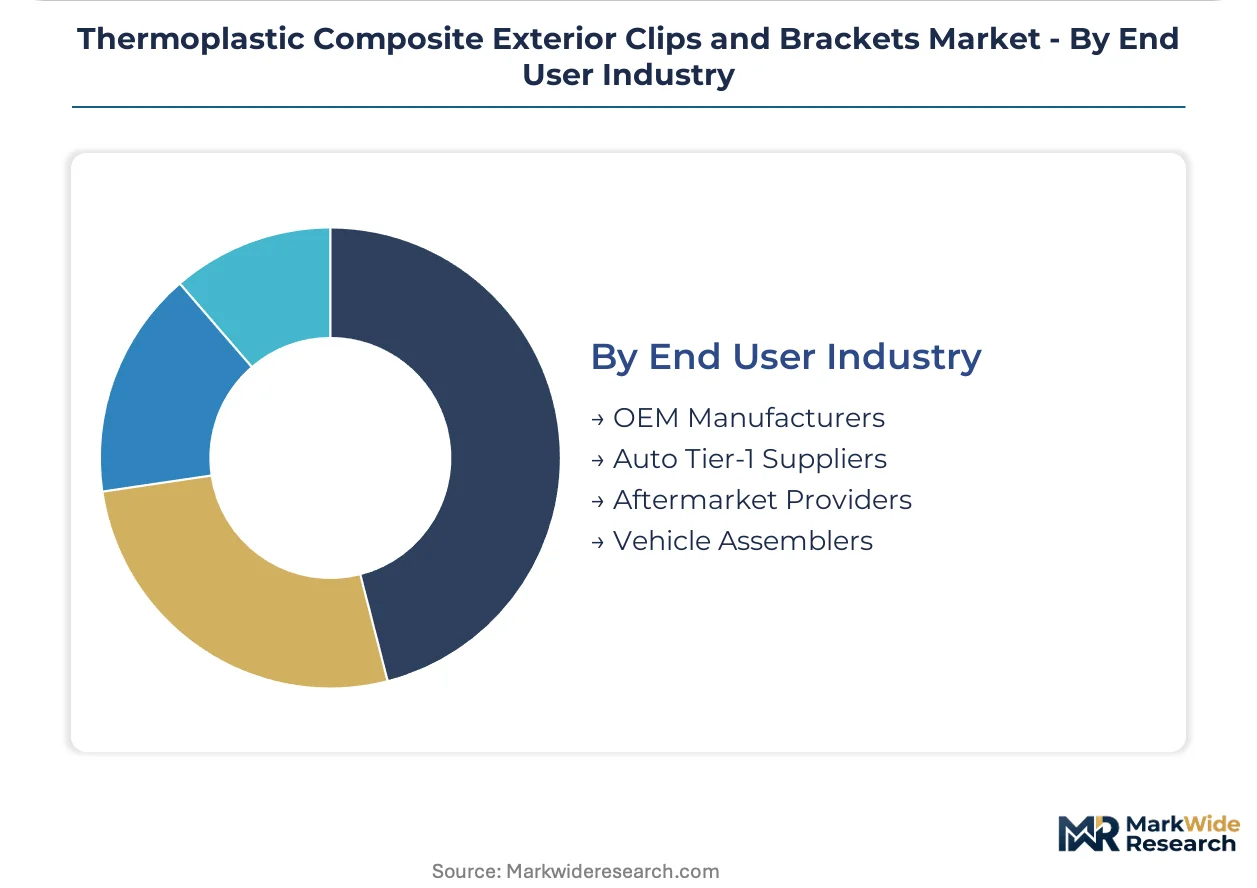
End User Industry:
Customer type determines qualification intensity, with OEM direct contracts demanding IATF 16949 certification and multi-year PPAP cycles.
- OEM Manufacturers:Vehicle brand owners specifying fastening platforms across nameplate families with design-to-cost engineering requirements. German OEMs now mandate full material disclosure to 0.1% threshold for exterior fasteners.
- Auto Tier-1 Suppliers:Integrated module builders consolidating procurement through platform engineering teams with annual price-down targets.
- Aftermarket Providers:Independent distributors serving collision repair and vehicle customization channels.
- Vehicle Assemblers:Contract manufacturing operations executing build-to-print specifications from OEM engineering.
OEM manufacturers hold design authority. Auto Tier-1 suppliers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA fuel-economy mandates and EU Green Deal embodied-carbon benchmarks are accelerating thermoplastic composite adoption across automotive manufacturing corridors worldwide. Germany's automotive belt and Stuttgart cluster anchor European demand density. California's zero-emission vehicle mandates and China's dual carbon goals are reshaping regional sourcing strategies for exterior fastening components.
Germany
Stuttgart and Wolfsburg manufacturing corridors generate concentrated demand for lightweight exterior fasteners as OEMs pursue range extension in electric vehicle platforms. ECHA REACH substance restrictions are disqualifying hexavalent chromium-coated metal brackets, widening substitution windows for polymer alternatives. Baden-Württemberg-based suppliers with captive resin formulation capabilities capture disproportionate contract renewals under this regulatory regime.
United States
NHTSA crashworthiness protocols mandate retention of exterior attachments under pedestrian-impact scenarios, constraining material selection for bumper beam and fender applications. California's state-level zero-emission vehicle mandates are accelerating carbon-fiber grade penetration in luxury electric vehicle programs. The Midwest automotive manufacturing cluster around Detroit and Chicago supports dedicated thermoplastic composite fastener production for platform-common nameplates.
China
MIIT dual carbon goals and new energy vehicle production targets are elevating mass reduction priorities across domestic OEM engineering teams. GB standards for automotive exterior components are tightening material disclosure requirements to 0.1% substance thresholds. The Yangtze River Delta manufacturing belt around Shanghai anchors injection molding capacity for glass-fiber reinforced grades serving both domestic brands and joint-venture assembly plants.
Japan
METI carbon neutrality roadmaps are pressuring automakers to document lifecycle emissions from resin pellet to molded component. JIS standards for automotive fasteners are incorporating thermal expansion mismatch criteria that favor thermoplastic composites over metal alternatives in mixed-material vehicle architectures. The Aichi Prefecture cluster around Toyota City maintains specialized molding capacity for hybrid brackets combining continuous fiber inserts with chopped-fiber housings.
Thermoplastic Composite Exterior Clips and Brackets Market Competitive Landscape
Listed leaders compete with private specialists across certification intensity and resin formulation depth. The supplier base organizes into three tiers: multinational Tier-1 integrators with IATF 16949 platform coverage, regional molders with captive compounder relationships, and specialized hybrid molding boutiques serving carbon-fiber grade niches. Dominant competitive moves include backward integration into resin formulation and design-to-cost engineering services embedded in early program development.
Within the multinational integrator tier, Nifco and ARaymond occupy positions shaped by geographic proximity to OEM assembly corridors. Nifco exemplifies the R&D-intensive archetype with deep resin formulation capabilities securing long-term contracts. ARaymond anchors European supply through captive manufacturing in France with strategic positioning near Renault and Stellantis plants. ITW Automotive represents the scale-driven end with broad platform engineering reach across North American and European OEMs.
| Leading Market Players |
|---|
| Nifco |
| ARaymond |
| ITW Automotive |
| Magna International |
| Flex-N-Gate |
| SMP Automotive |
| Novares |
| Tri-Mack Plastic Manufacturing |
| AVANKO Group |
| Others |
Pricing and Supply Chain Analysis
Sixty-day resin pellet lead times from Baden-Württemberg compounders to Stuttgart molders concentrate pricing power with suppliers possessing captive polyamide formulation, while annual OEM price-down agreements compress margins for non-integrated Tier-1s. This inventory-to-pricing nexus rewards backward integration into resin production and penalizes molders dependent on spot-market polymer sourcing.
Pricing Analysis
Certification level (IATF 16949 versus ISO 9001-only) creates the primary spread between premium and standard tiers, with PPAP-qualified suppliers commanding 15-25% unit premiums over commodity molders. Three-tier pricing structure across carbon-fiber structural brackets, glass-fiber standard grades, and mineral-filled economy clips reflects material cost stratification. Cost compression in glass-fiber polyamide segments is intensifying because annual OEM price-down agreements outpace resin efficiency gains. Aftermarket distributors exhibit highest price sensitivity, while OEM platform engineering teams prioritize qualification speed over unit cost.
Supply Chain Analysis
Forty-five-day tool steel lead times from German and Japanese suppliers constrain rapid capacity scaling for multi-cavity mold programs. Supply concentrates in Germany, China, and Japan, with Baden-Württemberg and Aichi Prefecture hosting specialized hybrid molding capacity. Polyamide 6 and 66 pellets, continuous carbon-fiber tape, and hardened mold steels constitute critical input dependencies. Single-source vulnerability around certified resin compounders with proprietary glass-fiber sizing chemistries threatens supply continuity. Distribution runs through OEM platform engineering teams consolidating procurement across nameplate families.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Design-to-cost engineering services now generate recurring revenue streams expanding faster than hardware unit sales, as OEM platform teams outsource material selection and mold-flow optimization to qualified suppliers. This service-attach layer transforms transactional fastener supply into multi-year engineering partnerships.
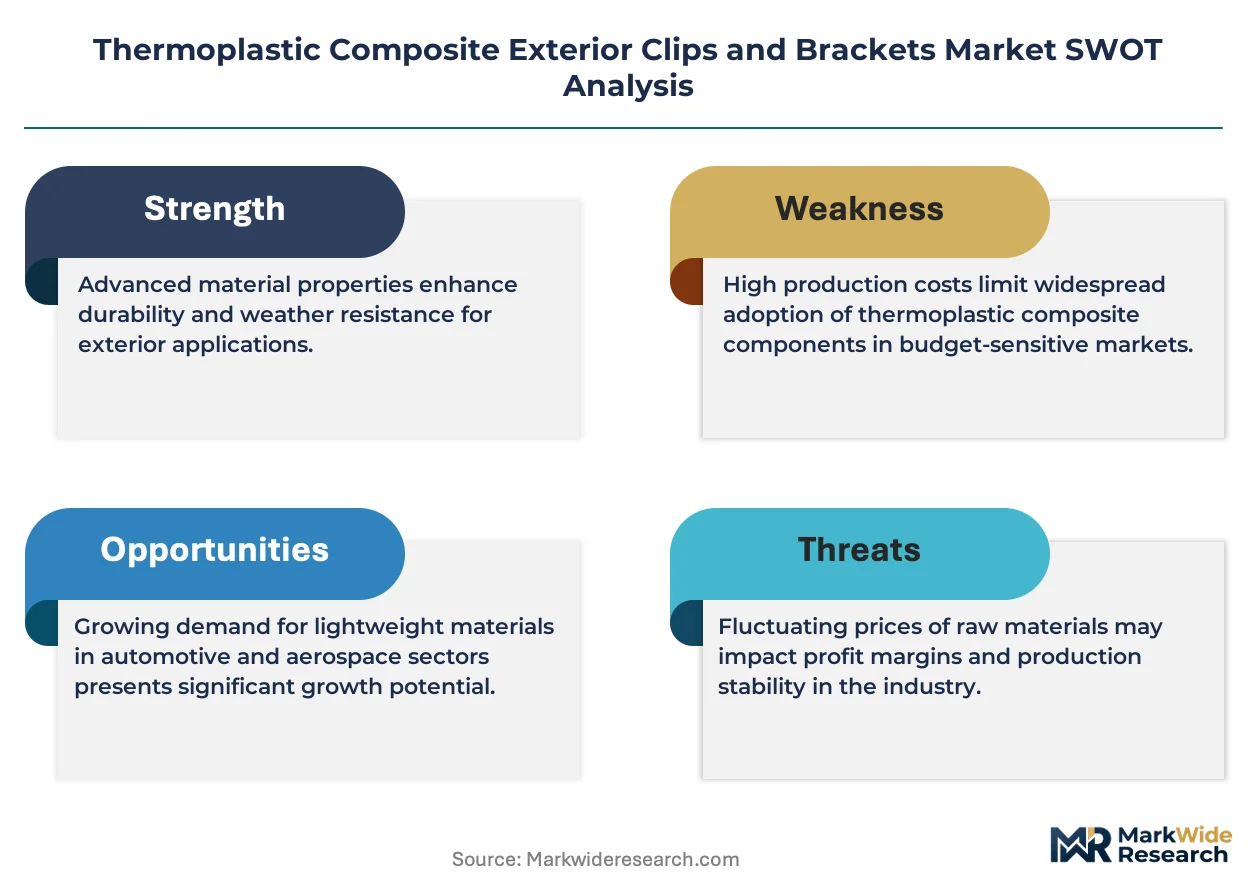
For Market Incumbents: Secure long-term resin formulation IP through exclusive licensing agreements with compounders, insulating margin pools from polyamide price volatility. Expand captive hybrid molding capacity in the Stuttgart corridor to defend against emerging CFRTP specialists. IATF 16949 certification timeline compression threatens supplier switching costs; accelerate PPAP completion bandwidth through dedicated program engineering cells. For New Entrants and Emerging Players: Rapid collision-repair clip qualification services represent a service-layer gap where incumbents under-serve independent aftermarket distributors. Target carbon-fiber bracket niches in California luxury EV programs where material cost premiums face lowest procurement scrutiny. Partner with regional compounders lacking molding assets to bypass capital-intensive tool steel investments. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because ECHA REACH substance restrictions and EPA fuel-economy mandates structurally expand polymer substitution windows regardless of commodity resin cycles. Acquisition candidates include mid-cap molders with captive resin formulation and existing IATF 16949 platform coverage. Monitor California zero-emission vehicle mandate acceleration as inflection signal for carbon-fiber grade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive polyamide compounding locks in margin pools against petrochemical feedstock volatility. |
| Hybrid Molding Capacity Expansion | CFRTP tape insertion capabilities capture structural bracket premiums from Stuttgart EV programs. |
| Design-to-Cost Engineering Services | Early program embedding with OEM platform teams secures multi-year contract visibility. |
| REACH Compliance Documentation Systems | Full material disclosure to 0.1% threshold qualifies suppliers for European OEM renewal cycles. |
| Aftermarket Qualification Partnerships | Collision repair channel access diversifies revenue beyond OEM price-down agreements. |
Research Methodology
Operator-level perspectives from Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and resin compounder technical directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC filings, IHS Markit vehicle production databases, ECHA SVHC candidate list updates, and customs trade data. Bottom-up unit economics triangulated against top-down OEM platform content assumptions.
Sensitivity analysis tested volume and value outputs across material substitution rates, resin price volatility bands, and regulatory acceleration scenarios. Segmentation dimensions modeled include product type (push clip versus structural bracket), material composition (glass-fiber versus carbon-fiber), vehicle propulsion architecture, and regional production cluster. CAGRs derived from installed capacity utilization curves and OEM platform rollout schedules, with electric vehicle content-per-vehicle assumptions calibrated against MIIT and EPA target disclosures.
Underlying assumptions cover sustained EPA fuel-economy enforcement, ECHA REACH expansion timelines, and polyamide feedstock cost stability, with deviation risk concentrated in aluminum-intensive vehicle architecture resurgence and alternative lightweight material breakthroughs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Roofing and Insulation Market
Building Materials
Global Pozzolan Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
Iron and Steel Slag Market
Building Materials
Concrete Market
Building Materials
Long Steel Market
Building Materials
Drywall Joint Tape Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
India Concealed Cistern Market
Building Materials
Steel Sleepers Market
Building Materials
Construction Materials Market
Building Materials
Shotcrete Market
Building Materials
Global Building Panels Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
Precast Concrete Retaining Walls Market