
 Offshore Pipeline Infrastructure Market | 2026-2036
Offshore Pipeline Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Pipeline Infrastructure Market Intelligence
The DNV-OS-F101 submarine pipeline systems standard is collapsing the qualification barrier between regional service providers and large-scale EPC contractors. TechnipFMC leverages its integrated engineering and manufacturing capabilities for complex deepwater projects. Bechtel Corporation competes with its extensive global project management experience in large-scale energy infrastructure. Bonatti S.p.A. specializes in challenging onshore-to-offshore transition zones and pipeline construction.
Offshore pipeline infrastructure comprises networks of subsea conduits designed for the high-pressure transport of fluids from production platforms to processing facilities. These pipelines typically feature multi-layer corrosion-resistant coatings and concrete weight coatings to ensure stability and integrity on the seabed. Gas transport applications command the largest share of new projects, driven by the global energy transition away from coal. While steel remains the dominant pipe material, advanced composites are gaining traction in niche applications requiring high corrosion resistance.
Project approvals and operational standards are governed by a mix of national and international bodies, including the US Environmental Protection Agency (EPA) and standards from the International Organization for Standardization (ISO). In Europe, the EU Green Deal framework influences long-term investment decisions and decommissioning liabilities for aging assets. Stakeholders must now decide whether to invest in retrofitting existing pipelines for hydrogen transport or to focus solely on new natural gas infrastructure.
Market Dynamics
The imperative to expand gas transport networks while preparing for a low-carbon future is the central force shaping the offshore pipeline market. This creates a dual track where operators invest in deepwater gas projects while also evaluating hydrogen compatibility for new infrastructure.
Growth Catalysts
- Energy Transition Mandates:Policies like the EU Green Deal and China's dual carbon goals accelerate the shift from coal to natural gas for power generation, requiring significant investment in new gas transport pipeline networks.
- Deepwater Exploration:New project investment is concentrating in deepwater basins, particularly off the coast of Brazil and in the Eastern Mediterranean, to access large, untapped natural gas and oil reserves.
- Industrial and Power Demand:Expanding industrial economies require reliable energy sources, supporting the business case for new offshore pipelines that connect production fields to onshore processing facilities and power plants.
Market Restraints
- High Input Costs:The price volatility of high-grade steel and specialized corrosion-resistant coating materials creates significant budget uncertainty for large-scale pipeline projects, acting as a structural deterrent to investment.
- Technical Complexity:Deepwater and ultra-deepwater projects present extreme engineering challenges, including high external pressures and complex seabed topographies, which increase costs and limit the pool of qualified contractors.
- Protracted Approval Cycles:Stringent environmental reviews and permitting processes from bodies like the US Environmental Protection Agency (EPA) can add years to project timelines, increasing financing costs and project risk.
Strategic Opportunities
- Hydrogen Transport Retrofitting:The potential to repurpose existing natural gas pipelines for transporting hydrogen presents a significant opportunity for engineering firms and service providers to develop new asset life extension services.
- Advanced Composite Materials:Development of non-metallic pipes, such as thermoplastic composites, opens new applications in corrosive environments or where lightweight installation provides a cost advantage over traditional steel.
- New Gas Infrastructure in Asia:Rapid industrialization in Southeast Asian nations creates an opportunity to build out new offshore gas pipeline infrastructure to displace coal and support economic growth.
Industry Challenges
- Skilled Labor Shortages:A scarcity of welders, engineers, and project managers with experience in complex deepwater pipeline construction and advanced materials poses a significant operational bottleneck for contractors.
- High Capital Intensity:The immense capital required to build, maintain, and operate a fleet of specialized pipelaying vessels and support equipment creates high barriers to entry and financial risk.
- Standardization Gaps:Harmonizing international standards like DNV-OS-F101 with varying national regulations complicates project execution and material procurement for cross-border pipeline systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Pipeline Infrastructure Market |
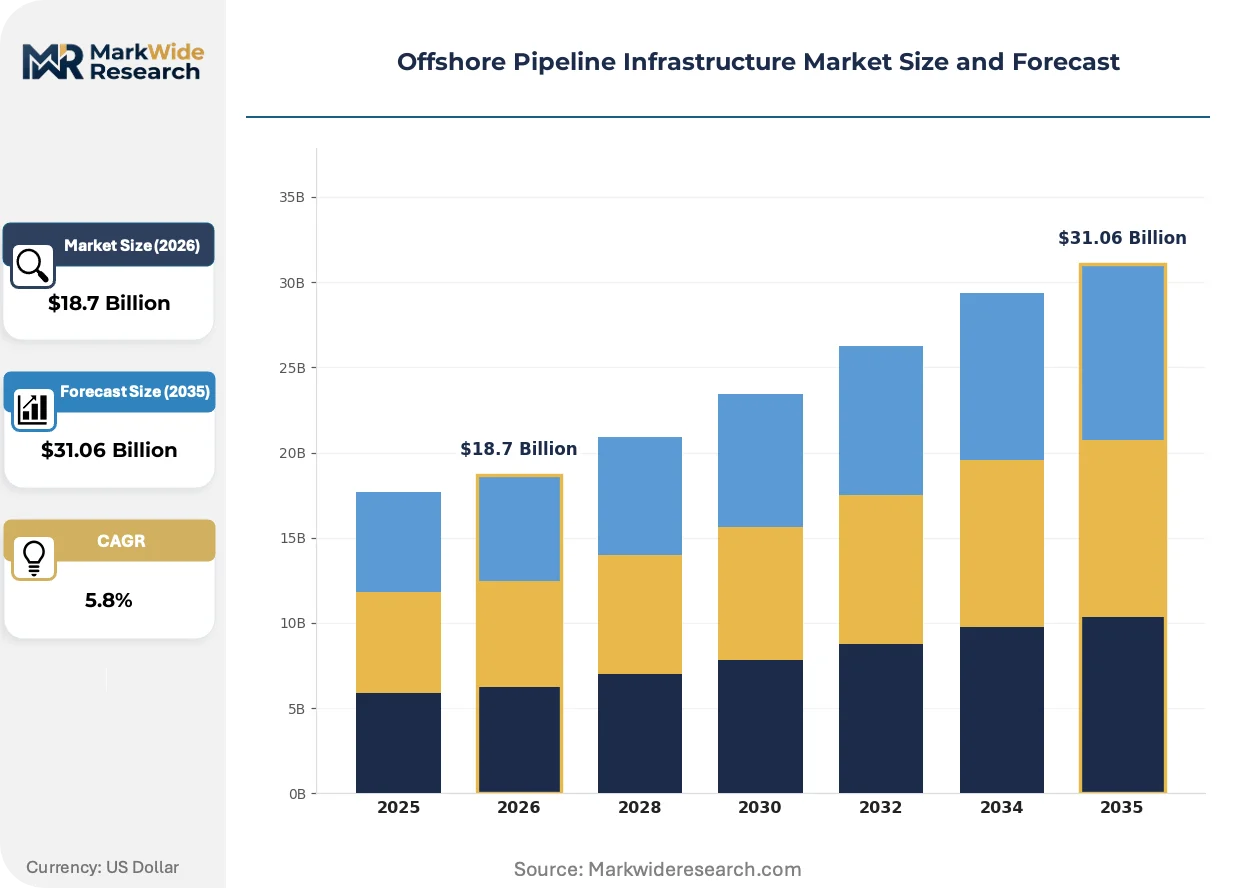
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pipe Material: Steel, Composite, HDPE, PVC Installation Method: Suction, Reel-Lay, J-Lay, S-Lay Application Type: Oil Transport, Gas Transport, Water Injection, Multi-Utility End User: Energy Companies, Construction Firms, Government Agencies, Contractors |
| Companies Covered | TC Energy, Kinder Morgan, Inc., TechnipFMC plc, Woodside Energy Group, PJSC Transneft, Bechtel Corporation, Pembina Pipeline Corporation, QatarEnergy, Bonatti S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Pipeline Infrastructure Market Strategic Shifts & Innovations
The market is navigating a fundamental transition, balancing the construction of infrastructure for current energy needs with the technical and commercial requirements of future energy systems like hydrogen and carbon capture.
Advanced composite pipes offer superior corrosion resistance and reduced weight compared to conventional alternatives. Operators are adopting these materials for specific applications like chemical injection lines, flowlines, and risers in highly corrosive production environments. This technology is displacing traditional corrosion-resistant steel alloys in niche segments where lifecycle cost and integrity management are primary drivers.
Regulatory frameworks, including the EU Green Deal, are imposing stricter environmental performance requirements on energy infrastructure projects. This directly impacts pipeline design, mandating considerations for carbon footprint during construction and operational phases, as well as future decommissioning liabilities. Projects in the North Sea and Mediterranean are most affected, with new tenders often including specifications for hydrogen-readiness.
A notable shift is occurring from discrete, project-based contracts to integrated, long-term service agreements that bundle engineering, procurement, construction, and installation. This model disrupts the traditional transactional approach, favoring contractors who can manage the entire asset lifecycle. The trend is most prominent in complex deepwater developments, such as those in Brazil, where operators seek to transfer long-term operational risk.
Offshore Pipeline Infrastructure Market Segmentation
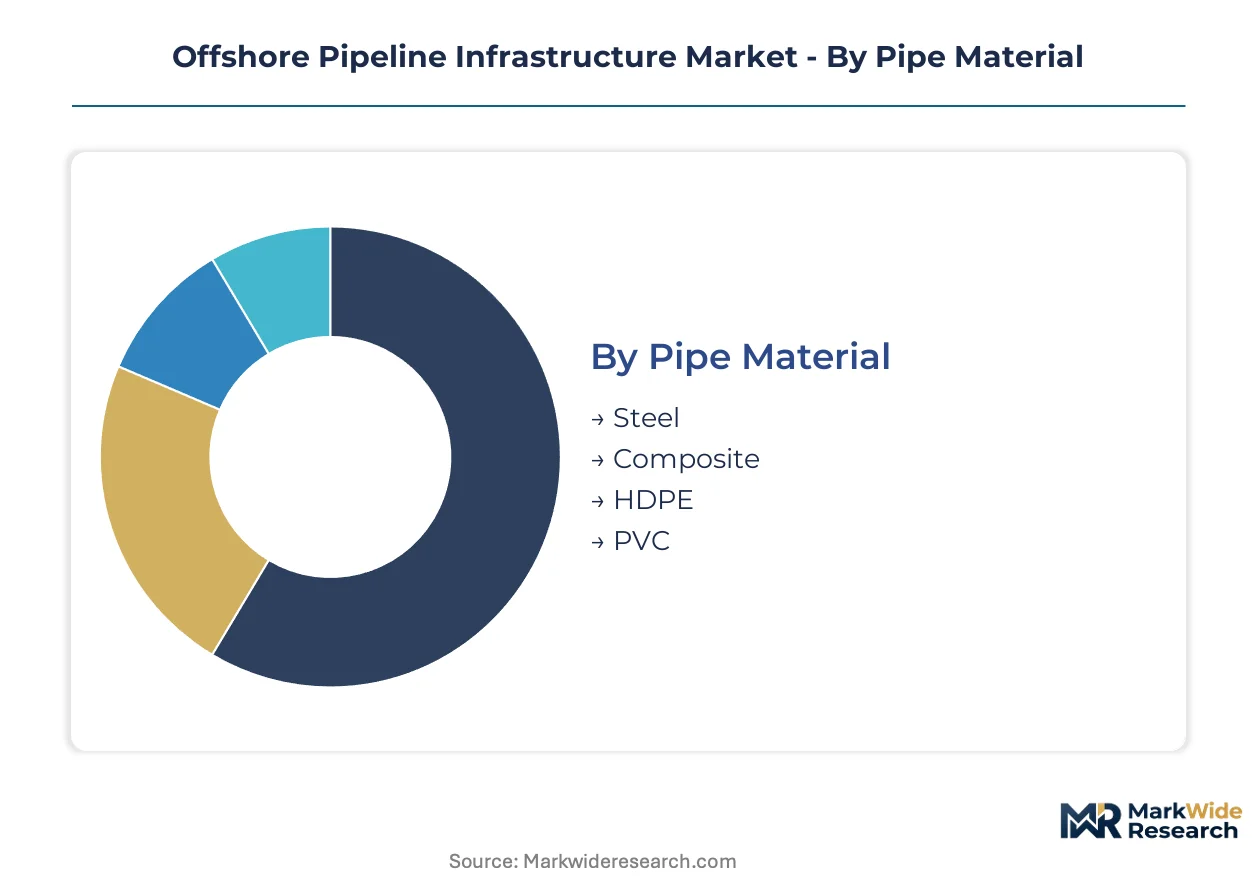
The offshore pipeline infrastructure market segments across key dimensions, offering a granular view of material choices, installation techniques, application areas, and primary end-users. Understanding these distinctions is crucial for stakeholders to align investment strategies with evolving energy demands and regulatory shifts.
Pipe Material:
Regulatory differentiation significantly influences pipe material selection, with national and international standards dictating performance requirements for subsea infrastructure.
- Steel:These pipelines, primarily carbon steel with corrosion-resistant alloys, form the backbone of global offshore transport networks due to their high strength and proven reliability in high-pressure gas and oil applications. Demand concentrates in deepwater basins off Brazil and the Eastern Mediterranean for new gas field developments.
- Composite:Advanced composite pipes, often thermoplastic or fiber-reinforced, offer superior corrosion resistance and reduced weight, making them suitable for challenging environments like chemical injection lines and highly corrosive production fluids. Operators in the North Sea adopt these materials for enhanced lifecycle integrity management.
- HDPE:High-density polyethylene pipes provide flexibility and resistance to chemical degradation, commonly used for smaller diameter flowlines, water injection, and non-critical utility lines in shallower waters. Their ease of installation reduces project timelines for short-distance connections.
- PVC:Polyvinyl chloride pipes find application in low-pressure, smaller diameter systems, often for ancillary services or temporary installations due to their cost-effectiveness and chemical inertness.
Established volume favors Steel; emerging adoption favors Composite.
Installation Method:
The technical complexity of seabed conditions and pipeline specifications drives the choice of installation method, impacting project feasibility and cost efficiency.
- Reel-Lay:This method involves spooling pre-fabricated pipeline onto a large reel on a vessel, then unspooling it directly onto the seabed, optimizing for speed and efficiency in long, continuous sections. Complex deepwater projects in the Gulf of Mexico utilize this technique for rapid deployment.
- J-Lay:J-Lay involves welding pipeline sections vertically at the stern of a vessel and lowering them in a near-vertical "J" shape, ideal for ultra-deepwater installations where high tension is required to manage pipeline weight. This method is critical for projects off the coast of Brazil.
- Suction:Suction anchors and piled foundations are crucial for securing pipelines and other subsea structures to the seabed, providing stability against currents and seismic activity. This technique is essential for anchoring complex manifolds and risers.
- S-Lay:S-Lay involves welding pipe sections horizontally on a vessel and laying them in an "S" curve from the stern, suitable for shallower to medium-depth waters and large diameter pipelines.
Installation speed is a critical differentiator, with Reel-Lay offering rapid deployment and J-Lay enabling extreme depth capabilities.
Application Type:
Demand for specific application types reflects the global energy mix and the strategic importance of various fluid transport requirements.
- Gas Transport:These pipelines facilitate the high-pressure movement of natural gas from offshore production platforms to onshore processing facilities, representing the largest share of new projects due to the global energy transition away from coal. Southeast Asian nations require significant gas transport infrastructure.
- Oil Transport:Offshore oil pipelines move crude oil and refined products from production sites to refineries or storage terminals, remaining a critical component of global energy supply chains. Deepwater fields off West Africa rely on extensive oil transport networks.
- Water Injection:Pipelines for water injection transport treated seawater or produced water back into oil reservoirs to maintain pressure and enhance oil recovery, extending the economic life of mature fields. North Sea operators frequently employ water injection for enhanced recovery.
- Multi-Utility:Multi-utility pipelines carry various fluids, including chemicals, control fluids, and smaller volumes of hydrocarbons, supporting complex subsea production systems and enabling efficient field operations.
Current demand heavily favors Gas Transport, while Water Injection supports asset life extension.
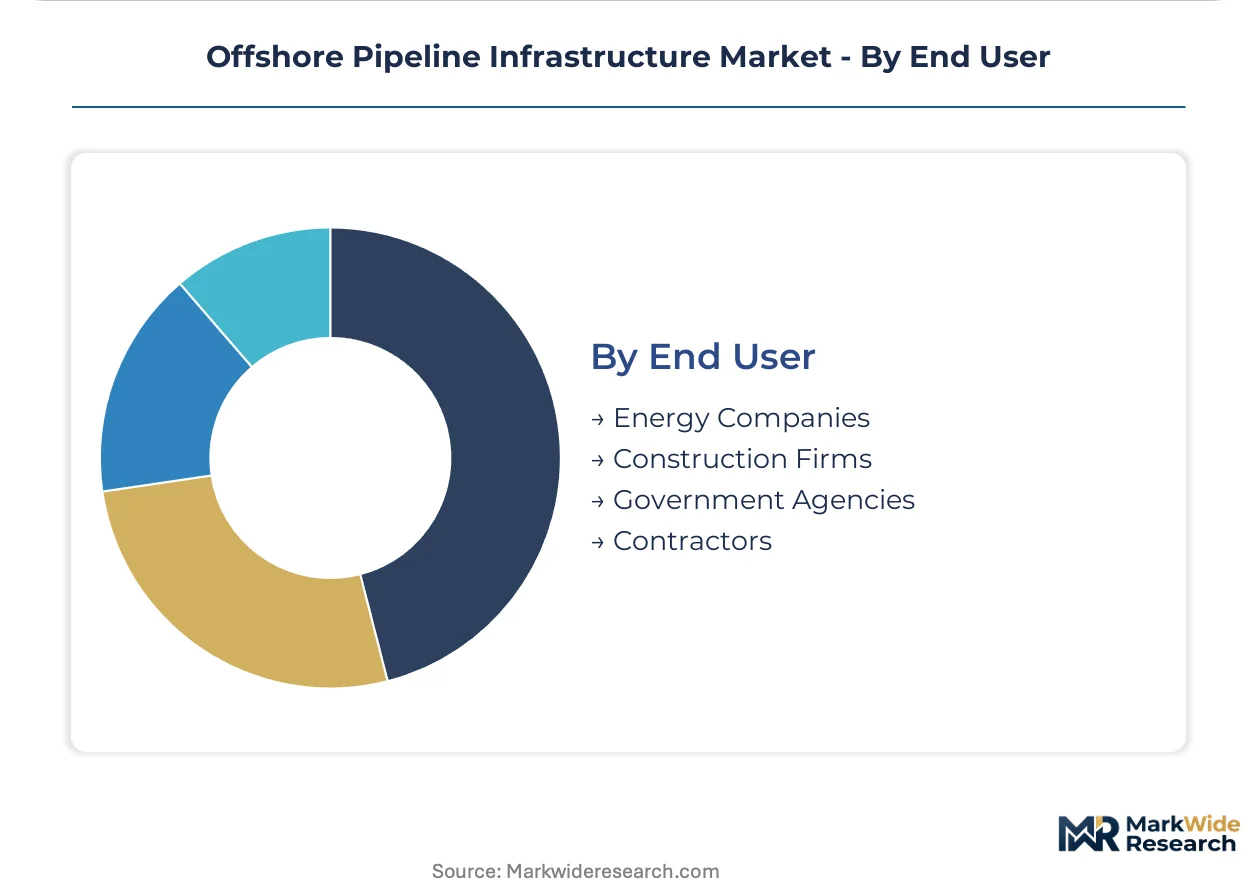
End User:
The end-user landscape reflects the diverse entities involved in financing, planning, executing, and operating offshore pipeline projects.
- Energy Companies:Major integrated oil and gas companies, along with national oil companies, drive investment in offshore pipelines as primary asset owners and operators for hydrocarbon extraction and transport. Petrobras in Brazil is a significant energy company investing in deepwater infrastructure.
- Contractors:Engineering, Procurement, Construction, and Installation (EPCI) contractors are responsible for the physical execution of pipeline projects, encompassing design, material sourcing, fabrication, and installation. TechnipFMC provides integrated contracting services.
- Government Agencies:National government bodies and state-owned enterprises often initiate and regulate large-scale energy infrastructure projects, particularly for strategic national energy security or economic development. China's state-owned energy firms drive significant offshore development.
- Construction Firms:Specialized construction firms provide services such as trenching, rock dumping, and subsea tie-ins, supporting the broader EPCI contractors in specific phases of pipeline development.
Project ownership resides primarily with Energy Companies, while Contractors execute the physical works.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy transition mandates and the drive for energy security are shaping offshore pipeline infrastructure investments across key global regions. National policies and economic incentives are directly influencing project approvals and the selection of advanced materials for new and retrofitted pipeline systems.
Brazil
Demand for deepwater gas and oil transport drives significant investment in Brazil's offshore pipeline sector. The country's national oil and gas agency, ANP, regulates exploration and production activities, influencing infrastructure development. Petrobras leads major projects in the Santos and Campos Basins, requiring complex subsea systems for hydrocarbon evacuation.
Norway
Stringent environmental mandates and the EU Green Deal framework influence new pipeline projects in Norway's North Sea. The Norwegian Petroleum Directorate sets high standards for operational integrity and environmental performance. Operators like Equinor are evaluating hydrogen readiness for new infrastructure off the coast of Stavanger.
China
China's dual carbon goals accelerate the need for offshore gas transport networks to displace coal in power generation. The National Energy Administration guides strategic energy infrastructure development and project approvals. State-owned energy firms are expanding offshore gas fields and connecting pipelines near Shanghai and Shenzhen.
United States
Deepwater exploration in the Gulf of Mexico generates consistent demand for new offshore pipelines in the United States. The US Environmental Protection Agency (EPA) implements rigorous environmental reviews and permitting processes. Energy companies based in Houston are expanding gas and oil transport networks to support onshore processing facilities.
Egypt
Major gas discoveries in the Eastern Mediterranean basin position Egypt as a regional energy hub, driving pipeline infrastructure development. The Ministry of Petroleum and Mineral Resources oversees gas export agreements and domestic supply network expansion. The Zohr gas field, off the coast of Port Said, exemplifies significant subsea pipeline investment.
Offshore Pipeline Infrastructure Market Key Industry Players
Player mix skews toward large-scale engineering, procurement, construction, and installation (EPCI) contractors and specialized service providers. Strategic archetypes include globally integrated engineering firms, project management specialists, and niche construction experts for challenging environments. Dominant competitive moves involve forming strategic partnerships for complex deepwater projects and diversifying portfolios to include hydrogen-compatible infrastructure solutions.
Specialists in integrated engineering and project execution, such as TechnipFMC plc, leverage in-house capabilities for complex subsea developments. Bechtel Corporation exemplifies extensive global project management experience, competing on its ability to deliver large-scale energy infrastructure projects worldwide. Bonatti S.p.A. occupies a position among firms specializing in challenging onshore-to-offshore transition zones and complex pipeline construction across diverse geographies.
| Leading Market Players |
|---|
| TC Energy |
| Kinder Morgan, Inc. |
| TechnipFMC plc |
| Woodside Energy Group |
| PJSC Transneft |
| Bechtel Corporation |
| Pembina Pipeline Corporation |
| QatarEnergy |
| Bonatti S.p.A. |
| Others |
Cost & Logistics Intelligence
Project-based contracts for offshore pipeline infrastructure lock in both supply access and price visibility for complex deepwater developments. This model mitigates risk for energy companies and EPCI contractors over multi-year execution timelines.
Pricing Analysis
Cost-plus contracts, often indexed to raw material prices like steel and specialized coatings, dominate offshore pipeline project pricing. Technical complexity in deepwater environments and the use of corrosion-resistant alloys drive significant price differentiation. Pricing softness stems from high input costs and extended regulatory approval timelines, which increase project financing expenses. Energy companies typically exhibit lower price sensitivity for critical gas transport infrastructure, while smaller contractors are more susceptible to material price fluctuations.
Supply Chain Analysis
Port congestion in key manufacturing hubs and specialized vessel availability impact inbound logistics costs for offshore pipeline components. Supply concentrates in China for steel pipe manufacturing, with Europe and Japan providing advanced coatings and specialized equipment. The market relies heavily on high-grade steel, specialized corrosion-resistant coatings, and advanced composite resins. Commodity price volatility for steel creates significant supply chain risk for EPCI contractors, whose distribution typically runs through direct procurement from specialized fabricators to project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The offshore pipeline infrastructure market is experiencing high-growth disruption driven by energy transition mandates, particularly the EU Green Deal and China's dual carbon goals. This regulatory inflection point necessitates significant investment in hydrogen-ready infrastructure.
For Market Incumbents:Shield core market share by diversifying service portfolios to include hydrogen transport retrofitting and new hydrogen pipeline infrastructure. Energy companies must invest in advanced composite materials R&D to counter the threat from non-metallic pipe providers and meet stricter environmental mandates. Leveraging integrated engineering capabilities for complex deepwater projects in Brazil and the Eastern Mediterranean provides a strong defense. This approach helps maintain competitiveness against specialized niche players.
For New Entrants and Emerging Players:Differentiate on specialized material solutions and installation expertise for challenging environments. New entrants can target niche applications for advanced composites, such as chemical injection lines in the North Sea, where superior corrosion resistance is critical. Focusing on onshore-to-offshore transition zones in Southeast Asia presents a penetrable segment for specialized construction firms. A go-to-market angle emphasizing enhanced lifecycle integrity management and reduced maintenance costs will resonate with operators.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors integrated EPCI contractors with proven deepwater execution capabilities. Long-term viability remains strong over the next 5-10 years, driven by global energy security needs and the low-carbon transition. Investors should seek acquisition targets with specialized advanced composite material expertise or established hydrogen retrofitting solutions. An increasing volume of project tenders specifying hydrogen-readiness in Europe serves as a key inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Diversify into Hydrogen Infrastructure | Positions energy companies for future low-carbon energy transport and extends asset life. |
| Invest in Advanced Composites | Reduces lifecycle costs for operators and improves pipeline integrity in corrosive environments. |
| Form Deepwater Project Alliances | Mitigates technical and financial risks for complex projects off Brazil and the Eastern Mediterranean. |
| Enhance Digital Project Management | Optimizes project timelines and cost control for EPCI contractors in challenging offshore conditions. |
| Expand in Southeast Asian Gas Markets | Captures demand from industrialization and coal displacement for new gas transport networks. |
Research Approach
Initial hypotheses were tested against primary input from energy company project managers, EPCI contractor engineers, subsea technology specialists, and regulatory compliance officers. This primary research was cross-referenced with secondary validation from national energy agency reports, ISO standards, and environmental impact assessments. A comprehensive bottom-up analysis of project-specific data was triangulated with top-down market trends. This approach ensured robust market sizing and forecast accuracy.
Variance decomposition isolated the impact of key drivers on market growth across the analysis window. The analytical framework modeled market segments by pipe material, installation method, application type, end user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical growth patterns and projected investment flows. Global energy demand projections and deepwater exploration budgets served as critical forecast inputs.
Material uncertainties — including geopolitical shifts, commodity price shocks, and unforeseen technological breakthroughs — sit outside the modeled envelope. Forecasts reflect baseline assumptions on regulatory stability and global economic growth. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Oman Transportation Infrastructure Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Bahrain Construction Market
Infrastructure Construction
Belgium Data Center Construction Market
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Global Transportation Infrastructure Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
APAC Data Center Construction Market