
 Global Magnesia Chrome Brick Market | 2026-2036
Global Magnesia Chrome Brick Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnesia Chrome Brick Market Foresight
Project finance tied to integrated steel complex expansions is fragmenting the competitive landscape for magnesia chrome brick supply. RHI Magnesita leverages captive raw material sourcing in Austria and Brazil to sustain margin stability across volatile mineral cycles. Calderys competes through application engineering services bundled with refractory packages, while HarbisonWalker International anchors North American demand through long-term furnace maintenance contracts with integrated steel producers.
Magnesia chrome brick combines periclase (MgO) and chrome ore (Cr₂O₃) in ratios typically ranging from 60:40 to 70:30, fired at temperatures exceeding 1700°C to form direct-bonded microstructures resistant to thermal shock and slag corrosion in basic steelmaking environments. High purity magnesia chrome brick leads value capture in electric arc furnace hot spots where Cr₂O₃ content above 20% extends campaign life, while semi-fused variants gain share in ladle furnace applications where thermal cycling frequency demands intermediate performance at lower unit cost. Chromite-based magnesia brick occupies the economy tier for non-critical blast furnace zones where replacement intervals align with scheduled reline cycles.
EPA air toxics standards for chromium emissions and EU REACH restrictions on hexavalent chromium compounds compel reformulation toward bonded magnesia-spinel alternatives or encapsulated chrome microstructures. China's MEE enforces stricter refractory waste classification rules that elevate recycling infrastructure requirements for steel mill procurement teams. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which product architectures will retain market access across their installed base.
Market Dynamics
Integrated steel capacity expansion in India and China's Hebei province is concentrating demand pull for high-performance refractories, while REACH-driven reformulation mandates in Europe force simultaneous product architecture shifts across the value chain.
Growth Catalysts
- EPA air toxics standards:Chromium emission caps in US steelmaking regions accelerate replacement cycles for legacy furnace linings, creating pull for compliant magnesia chrome formulations.
- Electric arc furnace hot spots:High-purity magnesia chrome brick with Cr₂O₃ above 20% extends campaign life in EAF operations, anchoring premium segment demand.
- Hebei province steel clusters:Integrated complex expansions in China's northern industrial corridor concentrate procurement volumes for direct-bonded refractory systems.
Market Restraints
- Chromite supply concentration:South African and Kazakh ore deposits dominate raw material sourcing, exposing margins to export duty volatility and logistics bottlenecks.
- REACH hexavalent chromium restrictions:ECHA-mandated reformulation timelines compress product development cycles and elevate R&D overhead for European market access.
- Magnesia-spinel substitution:Chrome-free alternatives gain technical acceptance in non-critical ladle applications, ceding addressable volume in mid-performance tiers.
Strategic Opportunities
- India's PLI scheme for specialty steel:Production-linked incentives for high-grade steel capacity create embedded demand for campaign-extending refractory packages.
- Refractory waste recycling infrastructure:China's MEE waste classification rules position closed-loop material recovery as a procurement differentiator for mill maintenance contracts.
- Digital furnace monitoring integration:IoT-enabled thermal profiling converges with predictive maintenance platforms, enabling performance-guaranteed supply agreements.
Industry Challenges
- Refractory engineer talent scarcity:Specialized expertise in high-temperature material behavior and slag chemistry limits application engineering scale-up.
- Dual certification complexity:Simultaneous EPA, REACH, and GB standard compliance extends product validation timelines and fragments regional SKU portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnesia Chrome Brick Market |
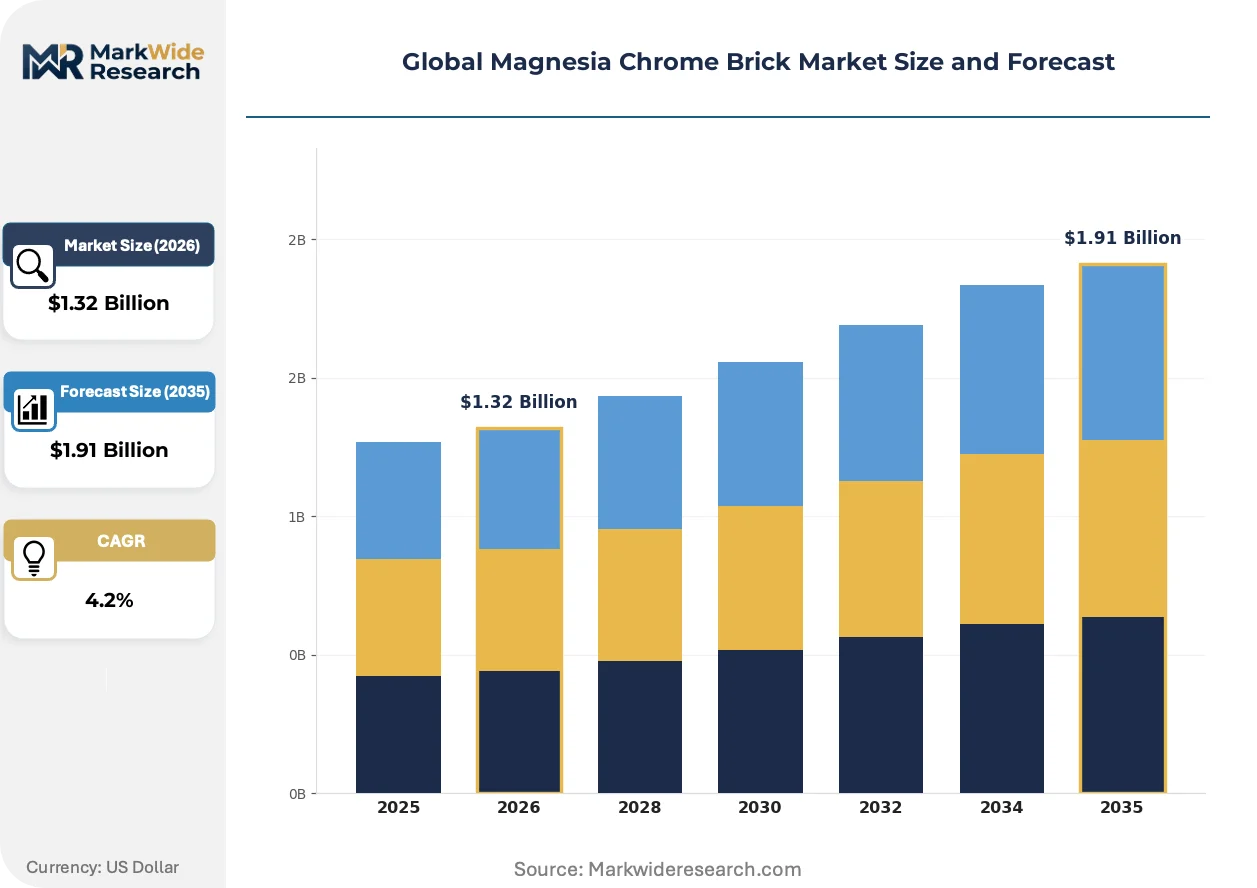
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $1.91 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Magnesia Chrome Brick, High Purity Magnesia Chrome Brick, Semi-Fused Magnesia Chrome Brick, Chromite-Based Magnesia Brick Application: Electric Arc Furnace, Blast Furnace, Ladle Furnace, Steel Casting End User Industry: Steel Mills, Foundries, Metal Fabricators, Smelting Plants Distribution Channel: Direct Sales, Distributors, E-Commerce, Industrial Suppliers |
| Companies Covered | RHI Magnesita, Calderys, HarbisonWalker International, Vesuvius, Shinagawa Refractories, Magnezit Group, Chosun Refractories, KT Refractories, Mayerton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnesia Chrome Brick Market Shifts & Advancements
Refractory supply models are pivoting from commodity transactions to performance-based partnerships, with digital monitoring and regulatory compliance bundling reshaping how buyers evaluate total cost of ownership.
Encapsulated chrome microstructures is virtualizing the traditional trade-off between corrosion resistance and environmental compliance. European EAF operators are piloting these architectures ahead of REACH enforcement deadlines. The technology is virtualizing legacy supply chains by collapsing the distinction between premium performance and regulatory-safe formulations into single-product platforms.
EU REACH restrictions on hexavalent chromium compounds are forcing bonded magnesia-spinel alternatives into technical qualification cycles. Steel mills in Germany and Poland face compressed timelines to validate substitute materials without campaign life penalties. High-purity magnesia chrome brick with modified microstructures retains market access in premium EAF segments where performance thresholds exclude full substitution.
Steel mill procurement teams are unbundling refractory supply from installation and maintenance services, creating discrete vendor categories for material, application engineering, and furnace monitoring. This pattern concentrates in China's state-owned steel groups, where centralized procurement platforms disintermediate traditional bundled suppliers. Indian integrated producers are replicating this model, separating refractory material sourcing from Calderys-style technical service contracts.
Global Magnesia Chrome Brick Market Segmentation
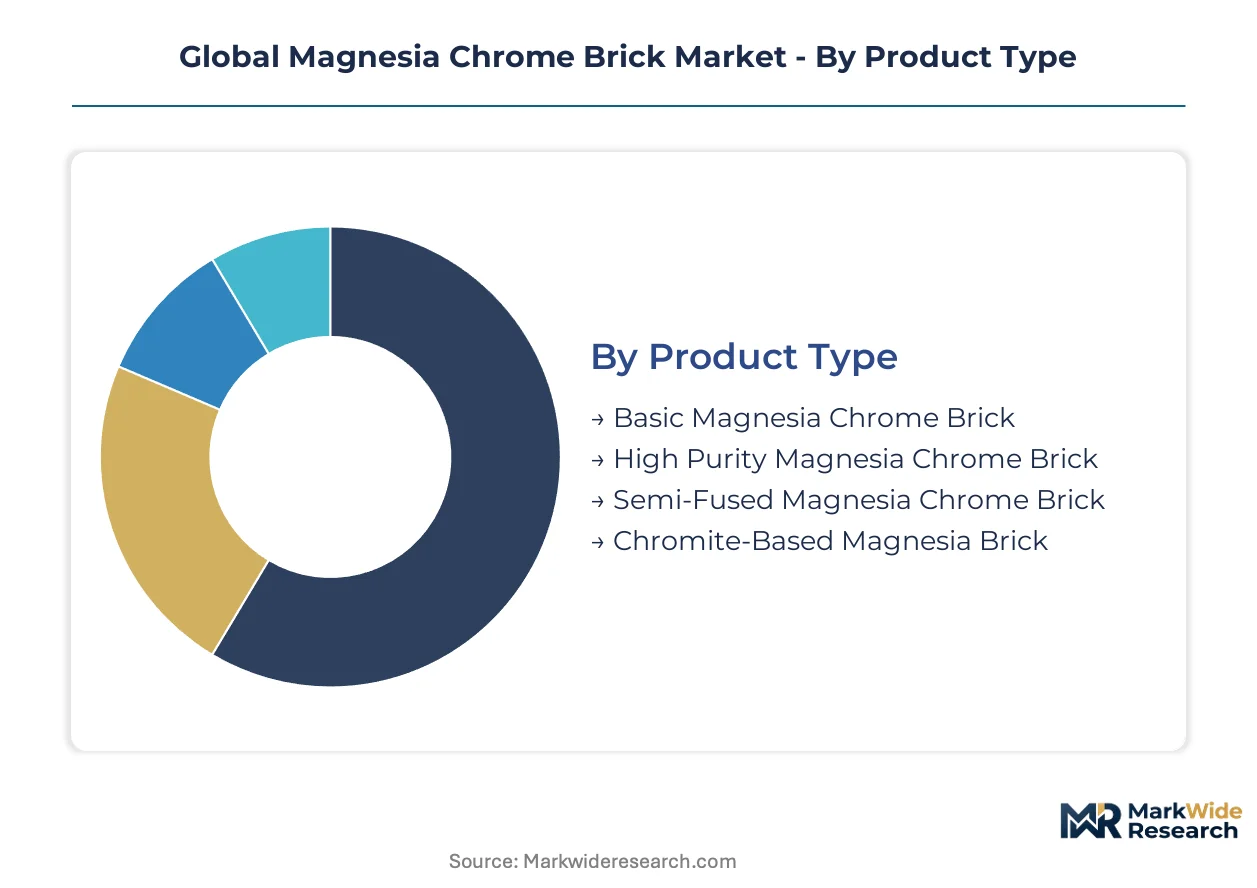
Segmentation in magnesia chrome brick markets maps directly to furnace lifecycle economics and regulatory exposure. Procurement teams weight technical performance against reformulation timelines, while supply channel choices reflect maintenance contract bundling strategies.
Product Type:
After-sales service intensity varies sharply across product tiers, with high-purity formulations demanding thermal monitoring partnerships and economy grades operating on spot replacement models.
- High Purity Magnesia Chrome Brick:Periclase and chrome ore ratios exceeding 70:30 with Cr₂O₃ content above 20%, fired above 1700°C to achieve direct-bonded microstructures. Demand concentrates in electric arc furnace hot spots across India's expanding integrated steel complexes, where campaign life extension justifies premium unit economics against frequent reline downtime.
- Basic Magnesia Chrome Brick:Standard 60:40 MgO-Cr₂O₃ formulations serving intermediate thermal shock requirements. Procurement volumes cluster in China's Hebei province steel clusters, where EPA-aligned export specifications and domestic GB standard compliance create dual certification overhead for maintenance contractors.
- Semi-Fused Magnesia Chrome Brick:Partially fused grain structures balancing thermal cycling resistance with cost efficiency for ladle furnace sidewalls.
- Chromite-Based Magnesia Brick:Economy-tier formulations with reduced magnesia content for non-critical blast furnace zones scheduled around planned reline cycles.
High purity magnesia chrome brick holds the largest share; momentum sits with semi-fused variants as ladle furnace thermal cycling frequency intensifies.
Application:
Cost tier stratification across furnace zones determines refractory specification, with hot spot applications commanding three-to-five times the unit economics of peripheral lining sections.
- Electric Arc Furnace:High-heat zones requiring Cr₂O₃-rich formulations resistant to slag corrosion and thermal shock. India's PLI scheme for specialty steel is embedding demand for campaign-extending refractory packages in new EAF capacity at JSW Steel and Tata Steel installations.
- Ladle Furnace:Intermediate thermal cycling environments where semi-fused magnesia chrome brick gains technical acceptance. Chinese state-owned steel groups in Jiangsu and Shandong provinces are unbundling material supply from Calderys-style technical service contracts, reshaping procurement patterns.
- Blast Furnace:Large-volume lining applications with scheduled reline cycles accommodating chromite-based economy grades.
- Steel Casting:Tundish and continuous casting operations requiring thermal stability through rapid temperature transitions.
Electric arc furnace applications dominate value capture; ladle furnace deployments are expanding most quickly as secondary steelmaking capacity scales.
End User Industry:
Customer type fragmentation separates integrated producers with captive engineering teams from foundries relying on bundled application services.
- Steel Mills:Integrated producers with direct procurement platforms and long-term furnace maintenance contracts. RHI Magnesita anchors relationships through captive raw material sourcing from Austria and Brazil, sustaining margin stability across mineral price cycles.
- Foundries:Smaller-scale operations dependent on distributor networks and technical service bundling. India's foundry sector in Coimbatore and Rajkot clusters faces refractory engineer scarcity that limits application engineering scale-up.
- Metal Fabricators:Secondary processing operations with intermittent furnace utilization patterns.
- Smelting Plants:Non-ferrous applications including copper and nickel processing with specialized slag chemistry requirements.
Steel mills command the dominant procurement volume; foundries represent the steepest expansion trajectory as India's PLI scheme disperses capacity beyond integrated majors.
Distribution Channel:
Supply concentration in refractory manufacturing clusters shapes channel economics, with direct sales leveraging proximity to steel mill complexes and distributors serving fragmented geographic demand.
- Direct Sales:Manufacturer-to-mill relationships dominating high-volume contracts. HarbisonWalker International anchors North American demand through long-term furnace maintenance agreements with integrated producers.
- Distributors:Regional inventory positioning for maintenance, repair, and operations procurement. European distributors face compressed timelines from ECHA-mandated REACH reformulation deadlines.
- E-Commerce:Emerging platform procurement for standardized grades in China's state-owned steel centralized purchasing systems.
- Industrial Suppliers:Bundled maintenance, repair, and operations providers serving mid-scale foundry operations.
Direct sales channels hold the largest share; e-commerce platforms are gaining share fastest as Chinese steel groups centralize procurement on digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for magnesia chrome brick track raw material dependency against finished refractory trade flows. South African chromite ore dominates upstream supply, while finished brick exports concentrate near steel manufacturing clusters in Asia and Europe.
China
Hebei province steel complexes anchor domestic consumption for direct-bonded refractory systems. MEE waste classification rules elevate recycling infrastructure requirements for mill procurement teams. Tangshan and Handan clusters drive specification volumes for high-purity formulations in electric arc furnace installations.
India
JSW Steel and Tata Steel EAF expansions embed demand for campaign-extending refractory packages under the PLI scheme for specialty steel. BIS standards compliance shapes import substitution strategies for domestic refractory manufacturers. Odisha and Jharkhand integrated complexes concentrate procurement volumes for hot-zone applications.
Germany
Thyssenkrupp and Salzgitter operations face compressed ECHA-mandated REACH reformulation timelines for hexavalent chromium restrictions. EAF operators pilot encapsulated chrome microstructures ahead of enforcement deadlines. Ruhr industrial corridor maintenance contractors navigate dual certification overhead for EPA-aligned export specifications.
United States
EPA air toxics standards for chromium emissions accelerate replacement cycles in legacy furnace linings across Great Lakes steel regions. HarbisonWalker International anchors relationships through long-term maintenance contracts with integrated producers. Indiana and Ohio mill complexes drive specification pull for compliant magnesia chrome formulations.
Brazil
RHI Magnesita leverages captive raw material sourcing from Austrian and Brazilian deposits to sustain margin stability across mineral price cycles. ANVISA chemical safety protocols influence refractory import documentation for non-ferrous smelting applications. Minas Gerais mining and metals corridor generates specialized demand for copper and nickel processing refractories.
Global Magnesia Chrome Brick Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and formulation niches. The vendor base separates into consolidated refractory groups with captive mineral assets, application engineering services firms, and regional fabrication specialists serving maintenance contractors. Strategic archetypes include vertically integrated mineral-to-brick operators, technical service bundlers, and spot-market distributors. Competitive moves concentrate on backward integration into chromite and magnesia deposits, plus predictive maintenance platform partnerships that lock in long-term furnace service contracts.
Among Europe-based integrated refractory groups, RHI Magnesita exemplifies the captive-sourcing archetype through mineral asset control. Calderys occupies the application-engineering tier with bundled technical service positioning. HarbisonWalker International anchors North American demand through maintenance contract relationships with integrated steel producers. These three represent distinct competitive vectors: mineral security, technical service integration, and geographic account density.
| Leading Market Players |
|---|
| RHI Magnesita |
| Calderys |
| HarbisonWalker International |
| Vesuvius |
| Shinagawa Refractories |
| Magnezit Group |
| Chosun Refractories |
| KT Refractories |
| Mayerton |
| Others |
Supply & Pricing Matrix
South Africa's Bushveld Complex chromite deposits concentrate upstream supply leverage, translating export duty volatility into downstream margin compression for European refractory formulators facing REACH compliance deadlines.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on Cr₂O₃ purity grade and after-sales thermal monitoring bundling. Cost compression in the economy tier is intensifying because Chinese state-owned steel groups centralize procurement on digital platforms. Foundries in India's Coimbatore cluster exhibit highest price sensitivity, while integrated steel mills in Hebei province prioritize campaign life over unit cost.
Supply Chain Analysis
Extended payment terms from South African ore exporters strain working capital for mid-tier refractory fabricators. Geographic supply concentration draws from South Africa, Kazakhstan, and Turkey for chromite ore, with Austria and Brazil contributing magnesia. Raw material dependencies rest on periclase, chrome ore, and fused alumina. Single-source vulnerability from South African export duty volatility threatens margin stability. Distribution runs through direct manufacturer-to-mill contracts for high-volume buyers, with regional distributors serving fragmented foundry demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnesia-spinel substitution technology threatens incumbent market share in ladle furnace applications, forcing refractory suppliers to defend premium EAF positioning while reformulating mid-tier offerings.
For Market Incumbents: Pre-empt magnesia-spinel displacement in non-critical zones by accelerating encapsulated chrome microstructure R&D ahead of ECHA enforcement timelines. Deepen upstream control over Brazilian magnesia deposits to insulate margins from South African chromite export volatility. Lock in long-term furnace maintenance contracts with predictive monitoring integration to reduce customer churn to technical service bundlers. For New Entrants and Emerging Players: India's PLI-scheme specialty steel expansions in Odisha and Jharkhand represent the most penetrable entry point for campaign-extending refractory packages. Secondary steelmaking capacity in Vietnam and Indonesia offers white-space demand for semi-fused formulations. Lead with application engineering partnerships rather than commodity supply to differentiate against established mineral-integrated incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors application-engineering specialists with digital furnace monitoring capabilities over pure mineral-asset plays. The five-to-ten year viability window rewards refractory waste recycling infrastructure investments aligned with China's MEE classification rules. Monitor EAF capacity expansion announcements in India and Southeast Asia as inflection indicators for premium refractory demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromite Assets | South African and Kazakh ore deposits anchor captive supply security against export duty volatility. |
| Encapsulated Chrome Microstructure Development | European EAF operators pilot these architectures ahead of ECHA-mandated REACH reformulation deadlines. |
| Refractory Waste Recycling Infrastructure | China's MEE waste classification rules position closed-loop recovery as a procurement differentiator. |
| Digital Furnace Monitoring Integration | IoT-enabled thermal profiling converges with predictive maintenance platforms for performance-guaranteed contracts. |
| Application Engineering Service Bundling | Calderys-style technical service contracts reshape procurement patterns in Indian and Chinese steel markets. |
Research Methodology
Cross-validation between primary interviews with refractory plant managers, steel mill procurement leads, and aftermarket service heads anchors the qualitative findings against secondary validation from customs trade data, SEC refractory group filings, and ECHA regulatory submissions. Bottom-up demand modeling from EAF and ladle furnace installation counts triangulates with top-down mineral trade flow analysis.
Calibration against historical capacity expansion patterns and regulatory enforcement timelines shapes the analytical framework across the projection horizon. Segmentation dimensions span product purity tier, furnace application type, end-user industry scale, and regional regulatory cluster. CAGR derivation incorporates steel production capacity forecasts and refractory consumption intensity ratios per furnace type.
Practitioners should monitor EAF capacity expansion announcements in India, REACH enforcement timeline adjustments in Europe, and South African chromite export policy shifts for early signals. Forecasts reflect documented assumptions regarding steel demand trajectories and regulatory compliance deadlines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Construction Stone Market
Building Materials
Granite Market
Building Materials
Shotcrete Market
Building Materials
United States Construction Materials Market
Building Materials
Bolt (Fastener) Market
Building Materials
LAMEA Engineered Stone Market
Building Materials
North America Concrete Admixtures Market
Building Materials
North America Architectural Coatings Market
Building Materials
Roofing and Insulation Market
Building Materials
Glass Facade Market
Building Materials
Concrete and Cement Market
Building Materials
Qatar Cement Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
Construction Coatings Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Concrete Blocks and Bricks Market