
 Polymer Concrete Market | 2026-2036
Polymer Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Concrete Market Intelligence
Infrastructure developers are redrawing procurement priorities across the polymer concrete value chain as chemical containment and bridge rehabilitation specifications expand faster than traditional flooring contracts. BASF SE leverages its epoxy resin captive supply to control formulation consistency across European project bids. Sika AG anchors its position through specialized distribution to civil engineering contractors in North American infrastructure corridors. Mapei S.p.A. competes on application-system bundling, combining polymer concrete with complementary waterproofing membranes to deepen contractor relationships.
Polymer concrete is a composite material formed by binding mineral aggregates with thermosetting resin matrices such as epoxy, polyester, or vinyl ester, achieving compressive strengths exceeding 70 MPa and near-zero permeability to aggressive chemicals. Its primary industrial purpose is to deliver structural durability in environments where conventional Portland cement suffers rapid degradation from acids, solvents, or thermal cycling. Epoxy polymer concrete commands the dominant share of value given its superior adhesion and load-bearing performance in industrial flooring systems, while vinyl ester formulations represent the fastest-growing category due to expanding specification for chemical containment linings at petrochemical and wastewater facilities. Polyester polymer concrete occupies a mature, cost-sensitive niche in precast component manufacturing where margin pools remain thin and competition centers on batch consistency rather than technical differentiation.
EPA corrosion resistance standards for chemical containment structures and state DOT durability specifications for bridge deck overlays shape product certification requirements and contractor qualification protocols in the United States. REACH registration obligations for resin precursors in Europe constrain formulation flexibility while favoring suppliers with established substance dossier portfolios. ASTM C904 test methods and ISO 11622 performance classifications further segment market access by validating long-term mechanical retention under thermal and chemical stress. Stakeholders must monitor evolving resin raw material availability and prequalification list dynamics at major infrastructure agencies to anticipate specification shifts before they crystallize in bid documents.
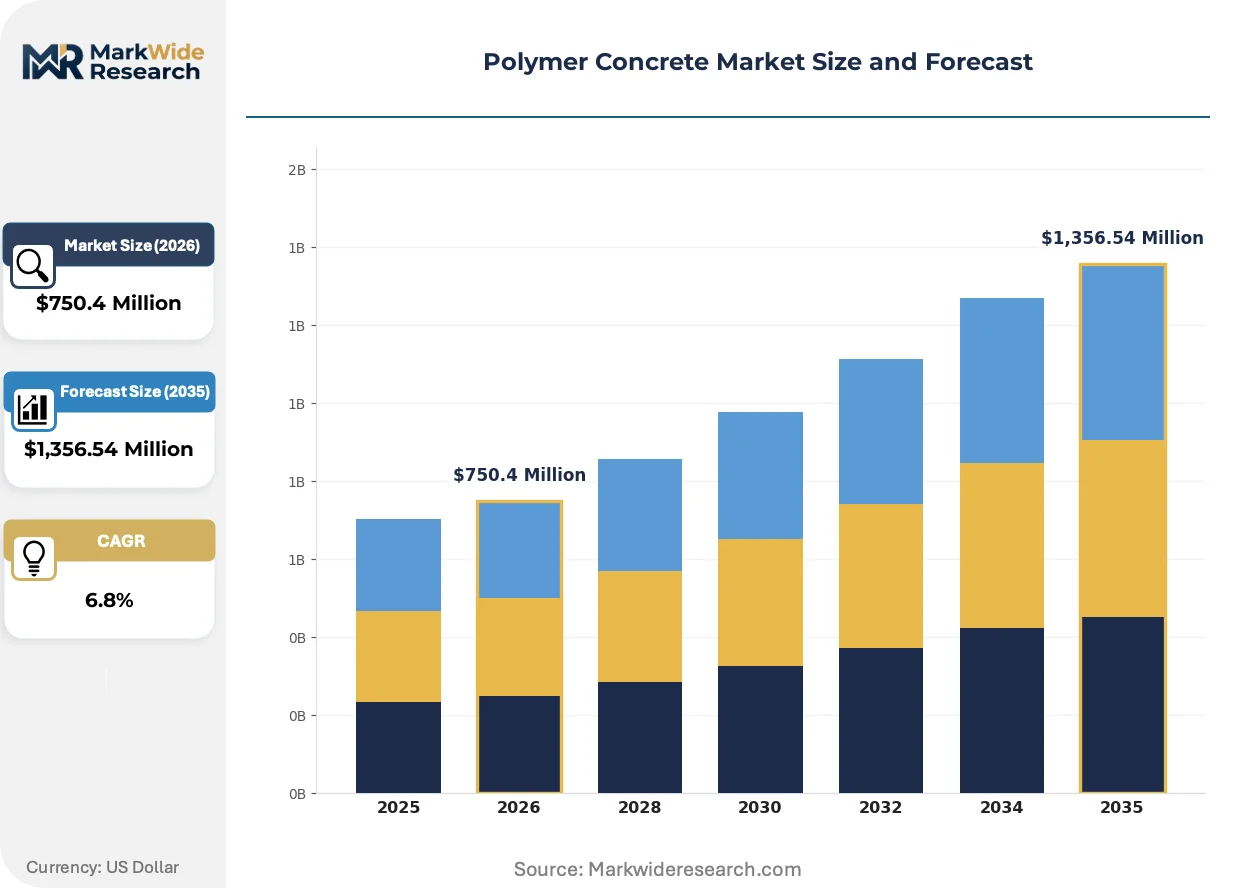
Market Dynamics
State DOT durability mandates and EPA corrosion resistance standards are compressing contractor qualification timelines while elevating specification barriers for conventional Portland cement systems in infrastructure rehabilitation.
Growth Catalysts
- Bridge deck overlay mandates:State-level DOT specifications in the United States now require minimum 50-year service life for rehabilitation materials, driving substitution toward vinyl ester and epoxy polymer concrete formulations.
- REACH dossier consolidation:European resin precursor registration requirements favor suppliers with established substance portfolios, concentrating specification authority among incumbent formulators with compliant supply chains.
- Wastewater infrastructure renewal:Germany's industrial flooring upgrade cycle and chemical containment lining replacement programs are expanding project pipelines for high-performance polymer concrete systems.
Market Restraints
- Epoxy resin price volatility:Bisphenol-A and amine hardener feedstock costs fluctuate with crude oil derivatives, compressing formulation margins and destabilizing project bidding.
- Specialized applicator scarcity:Certified installation contractors concentrate in German and US industrial corridors, creating bottleneck risk for project execution in peripheral markets.
- Portland cement cost advantage:Conventional concrete maintains 60-70% material cost superiority in non-corrosive applications, limiting addressable market expansion.
Strategic Opportunities
- Prefabricated component standardization:Modular polymer concrete trench drains and utility vaults offer route-to-market expansion through distributor stocking programs rather than project-specific casting.
- Carbon capture integration:Resin producers developing bio-based epoxy precursors from lignin or vegetable oil feedstocks can access EU Green Deal procurement preferences and green public tender weighting.
- Digital specification platforms:Building information modeling integration enables real-time performance simulation, shortening contractor prequalification cycles for complex containment geometries.
Industry Challenges
- Thermal curing protocol standardization:Ambient temperature variations across installation sites create performance variance, complicating warranty underwriting and claims resolution.
- Cross-material compatibility testing:Polymer concrete overlays on existing Portland cement substrates require substrate moisture and alkalinity assessment protocols that extend pre-installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Concrete Market |
| Market Size in 2026 | $750.4 Million |
| Market Size in 2035 | $1,356.54 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Polymer Concrete, Polyester Polymer Concrete, Vinyl Ester Polymer Concrete, Acrylic Polymer Concrete, Phenolic Polymer Concrete Application: Flooring Systems, Structural Repairs, Bridge Rehabilitation, Precast Components, Chemical Containment End User: Construction Contractors, Civil Engineers, Infrastructure Developers, Marine Facilities, Chemical Plants Packaging Type: Drums, Cartridges, Pails, Bulk Bags, Totes |
| Companies Covered | Dudick Inc., Fosroc International Ltd, BASF SE, ErgonArmor, ULMA Architectural Solutions, Sika AG, Mapei S.p.A., Wacker Chemie AG, Interplastic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Concrete Market Strategic Shifts & Innovations
Formulation chemistry and installation methodology are converging to compress project timelines while extending service life guarantees in aggressive chemical environments.
Vinyl ester resin systems are displacing epoxy formulations in petrochemical containment applications due to superior acid resistance and lower thermal expansion coefficients. Refinery operators in the US Gulf Coast region specify vinyl ester for sulfuric acid tank linings and secondary containment berms. This displacement is compressing the addressable market for premium epoxy grades in chemical processing while expanding total specification volume for polymer concrete as a category.
EPA corrosion resistance standards for hazardous waste containment structures now mandate 30-year permeability testing under ASTM C904 protocols. Engineering firms must document resin matrix performance retention under thermal cycling and chemical immersion. Bridge rehabilitation contractors in coastal states face accelerated compliance timelines as state DOTs harmonize specifications with federal environmental mandates.
Asset owner procurement teams now bundle polymer concrete with complementary waterproofing membranes and joint sealants under single-source performance contracts. Civil engineering contractors in North American infrastructure corridors prefer consolidated material packages that transfer compatibility risk to formulation suppliers. Germany's industrial flooring market exhibits similar bundling behavior, with facility owners demanding system warranties rather than component-level guarantees.
Polymer Concrete Market Segmentation
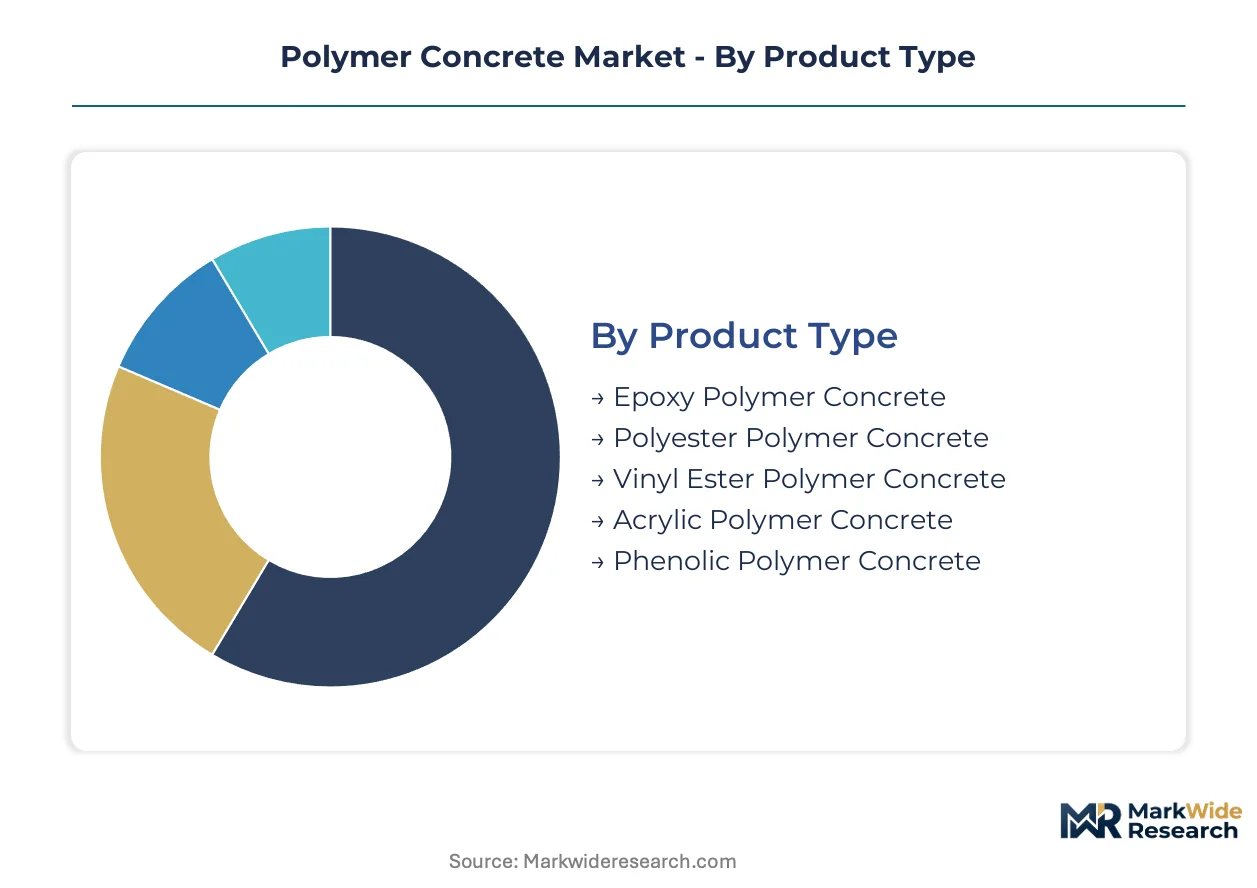
Segmentation reveals how resin chemistry, application severity, and contractor procurement patterns fragment margin capture across the polymer concrete value chain. Specification authority concentrates with formulators who align product portfolios to DOT durability mandates and EPA corrosion standards.
Product Type:
Margin pools concentrate in epoxy and vinyl ester formulations where technical certification barriers protect pricing power against commodity polyester alternatives.
- Epoxy Polymer Concrete:Thermosetting resin matrices based on bisphenol-A and amine hardeners deliver compressive strengths exceeding 70 MPa with near-zero permeability. German industrial flooring contractors specify epoxy for high-traffic manufacturing environments where 50-year service life guarantees are mandatory under state-level durability codes.
- Vinyl Ester Polymer Concrete:Hybrid resin systems combining epoxy backbone toughness with polyester cost structures achieve superior acid resistance and lower thermal expansion coefficients. US Gulf Coast petrochemical operators specify vinyl ester for sulfuric acid tank linings and secondary containment berms under EPA corrosion resistance standards.
- Polyester Polymer Concrete:Unsaturated polyester resins bound with mineral aggregates occupy cost-sensitive precast manufacturing niches where batch consistency matters more than chemical resistance.
- Acrylic Polymer Concrete:Methyl methacrylate-based systems enable rapid ambient-temperature curing for emergency infrastructure repairs where thermal curing protocols are impractical.
- Phenolic Polymer Concrete:High-temperature-resistant formulations serve specialized furnace lining and foundry applications where thermal cycling exceeds 200°C.
Epoxy polymer concrete holds installed capacity across European industrial corridors. Vinyl ester polymer concrete is rotating up the share rankings in North American chemical containment specifications.
Application:
Application segmentation tracks how infrastructure procurement priorities are shifting from traditional flooring toward structural rehabilitation and environmental containment.
- Flooring Systems:Industrial-grade surface installations demand high compressive strength and chemical resistance for manufacturing facilities, warehouses, and food processing plants. German facility owners now bundle polymer concrete flooring with waterproofing membranes under single-source performance contracts.
- Bridge Rehabilitation:Deck overlay and structural strengthening applications require materials meeting 50-year service life specifications under state DOT mandates. US coastal states specify vinyl ester and epoxy formulations for corrosion protection in marine-exposed superstructures.
- Structural Repairs:Crack injection and spall repair applications utilize low-viscosity polymer concrete formulations for restoring load-bearing capacity in deteriorated concrete elements.
- Precast Components:Modular trench drains, utility vaults, and manhole sections manufactured off-site for distributor stocking programs.
- Chemical Containment:Tank linings, secondary containment berms, and process vessel coatings for petrochemical and wastewater treatment facilities.
Flooring systems retain the largest installed base. Bridge rehabilitation is climbing the fastest as state DOTs harmonize specifications with federal environmental mandates.
End User:
End user segmentation reflects how specification authority concentrates with engineering firms and infrastructure agencies rather than general construction contractors.
- Civil Engineers:Design-phase specification holders who validate polymer concrete performance under ASTM C904 and ISO 11622 protocols for public infrastructure bids.
- Infrastructure Developers:Asset owners bundling polymer concrete with complementary waterproofing systems under long-term performance contracts.
- Construction Contractors:Installation specialists requiring certified applicator status for warranty-eligible project execution.
- Chemical Plants:Petrochemical operators specifying vinyl ester formulations for acid containment under EPA hazardous waste regulations.
- Marine Facilities:Port authorities and offshore platform operators demanding chloride-resistant formulations for splash zone protection.
Civil engineers control specification gatekeeping. Infrastructure developers are gaining procurement leverage through bundled system contracting.
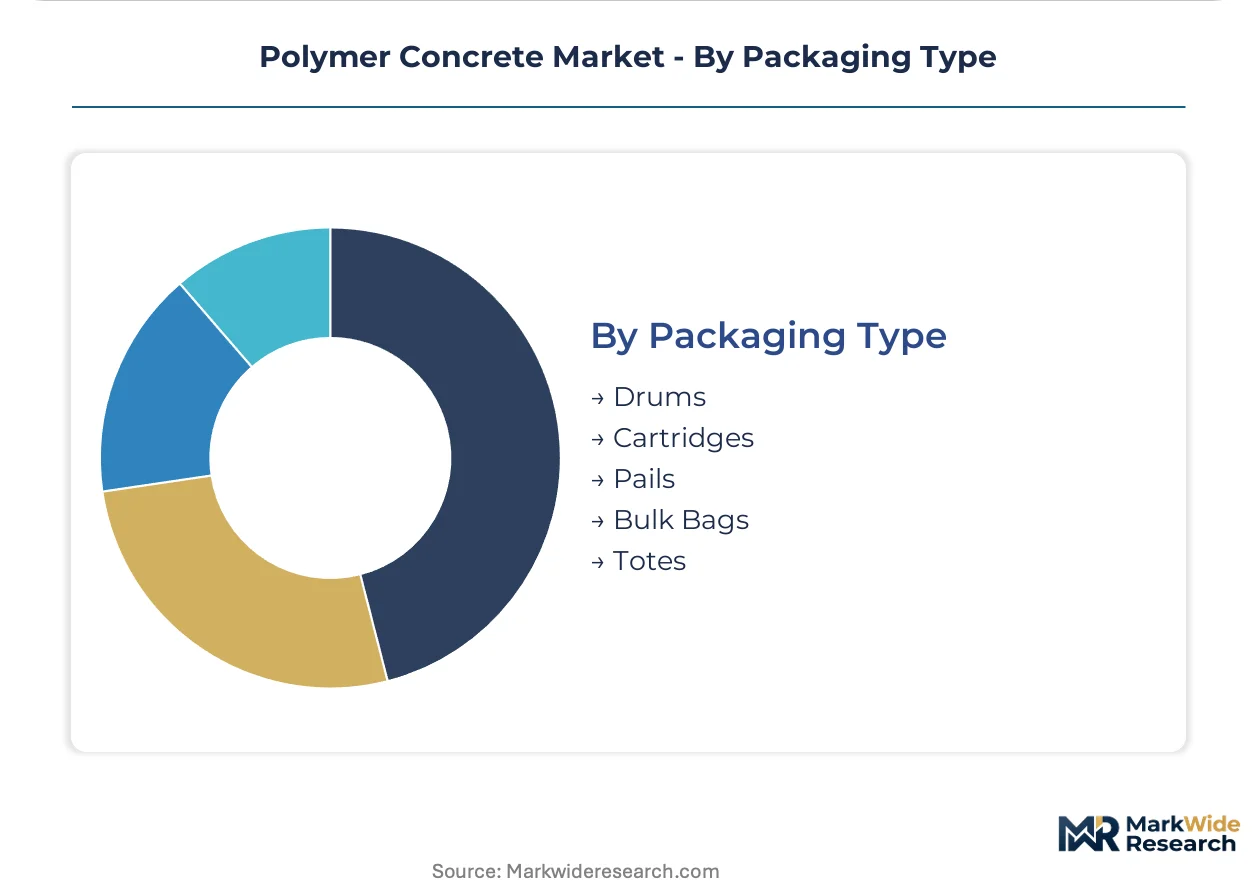
Packaging Type:
Packaging segmentation tracks how project scale and site logistics determine format preference across distributor and direct-channel supply chains.
- Bulk Bags:Large-volume flexible intermediate bulk containers serve major infrastructure projects with on-site mixing capabilities and established material handling protocols.
- Drums:Standard 55-gallon steel containers dominate mid-scale industrial flooring contracts where batch volume predictability supports project scheduling.
- Totes:Intermediate bulk totes bridge bulk and drum formats for regional distributor stocking programs serving multiple contractor accounts.
- Pails:Five-gallon containers target repair and maintenance applications requiring partial batch utilization without material waste.
- Cartridges:Pre-measured dual-component cartridges enable precision application for crack injection and small-area repairs.
Bulk bags anchor high-volume infrastructure procurement. Drums maintain position across industrial flooring distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure procurement teams concentrate in industrial corridors where state-level durability mandates and chemical containment regulations create specification pull-through for high-performance resin systems.
United States
Bridge deck rehabilitation and petrochemical containment drive specification volume across Gulf Coast and coastal state corridors. EPA corrosion resistance standards under ASTM C904 protocols mandate 30-year permeability validation for hazardous waste structures. Houston-area refineries and California DOT districts anchor vinyl ester demand for acid tank linings and marine-exposed superstructures.
Germany
Industrial flooring upgrade cycles and wastewater treatment infrastructure renewal concentrate procurement authority in North Rhine-Westphalia and Bavaria. REACH registration obligations for resin precursors favor established formulators with compliant substance dossiers. The Ruhr industrial cluster and Munich manufacturing belt specify epoxy systems for 50-year service life guarantees under state-level durability codes.
China
Petrochemical capacity expansion and coastal infrastructure rehabilitation accelerate specification for chemical-resistant formulations. GB standards for construction materials and MEE environmental compliance protocols shape product certification requirements. The Yangtze River Delta and Shandong Peninsula industrial zones drive batch volume for precast polymer concrete components.
Japan
Seismic retrofit programs and industrial facility modernization sustain demand for rapid-curing repair systems. METI energy efficiency guidelines and JIS performance classifications segment market access by validating mechanical retention under thermal stress. The Kansai manufacturing corridor and Chubu industrial belt specify methyl methacrylate-based systems for emergency infrastructure repairs.
India
Chemical processing capacity additions and port infrastructure upgrades create specification pipelines for chloride-resistant formulations. BIS construction material standards and state-level industrial corridor programs concentrate project authority with engineering consultants. The Gujarat chemical belt and Maharashtra port zones anchor demand for sulfuric acid containment systems.
Polymer Concrete Market Key Industry Players
Player mix skews toward diversified chemical conglomerates with captive resin supply and specialized construction material formulators with distribution depth into civil engineering channels. Incumbents leverage formulation certification portfolios to control specification gatekeeping at infrastructure agencies. Three archetypes dominate: resin-integrated conglomerates, application-system bundlers, and regional precast specialists. Competitive moves center on backward integration into epoxy precursor supply and strategic partnerships with certified applicator networks.
Among European resin-integrated conglomerates, BASF SE and Wacker Chemie AG occupy positions anchored by captive bisphenol-A and amine hardener supply chains. Sika AG exemplifies the application-system bundler archetype, sitting within specialized distribution channels serving North American infrastructure corridors. Mapei S.p.A. represents bundling strategy execution, combining polymer concrete with complementary waterproofing membranes to deepen contractor relationships.
| Leading Market Players |
|---|
| Dudick Inc. |
| Fosroc International Ltd |
| BASF SE |
| ErgonArmor |
| ULMA Architectural Solutions |
| Sika AG |
| Mapei S.p.A. |
| Wacker Chemie AG |
| Interplastic Corporation |
| Others |
Cost & Logistics Intelligence
ASTM C904 certification protocols gate both supplier qualification and price tiering simultaneously, compressing margin pools for uncertified formulators while elevating premium capture for resin-integrated incumbents with compliant testing documentation. State DOT prequalification lists further stratify the market, tying price differentiation directly to approved-specification status.
Pricing Analysis
Cost-plus contracts with bisphenol-A indexation dominate epoxy polymer concrete procurement, transferring feedstock volatility risk from formulators to infrastructure developers. Pricing stratifies across DOT-certified premium grades, industrial-standard formulations, and commodity polyester tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in standard-grade epoxy intensifies as Chinese resin imports expand availability. General construction contractors exhibit highest price sensitivity, while petrochemical operators prioritize performance guarantees over unit economics.
Supply Chain Analysis
Germany and the United States anchor high-performance formulation capacity, with China expanding precast component manufacturing for regional infrastructure markets. Bisphenol-A, amine hardeners, and vinyl ester monomers constitute critical input dependencies, with supply anchored in petrochemical corridors. Single-source vulnerability concentrates in specialty amine hardener supply from German chemical conglomerates. Distribution runs through certified applicator networks rather than commodity building-material channels, with project-specific batching dominating over distributor stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer concrete specification is shifting toward platform-economics dynamics, with building information modeling interoperability enabling real-time performance simulation and compressing contractor prequalification cycles.
For Market Incumbents: Consolidate formulation certification portfolios to defend specification gatekeeping at state DOT agencies and EPA-compliant containment projects. BASF SE and Sika AG demonstrate model execution through captive resin supply and specialized distribution depth. Prioritize backward integration into amine hardener precursors to insulate margins from bisphenol-A volatility. Channel control through certified applicator network expansion represents the critical defensive lever against emerging regional formulators. For New Entrants and Emerging Players: ASTM C904 fast-track certification pathways unlock specification access for bridge rehabilitation and chemical containment verticals currently dominated by incumbent dossiers. Prefabricated component standardization offers the most penetrable entry vector, with modular trench drains and utility vaults bypassing project-specific casting complexity. Target industrial flooring upgrade cycles in secondary German manufacturing corridors where incumbent coverage remains thin. Distributor stocking partnerships provide lower-friction go-to-market architecture than direct civil engineering channel development. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vinyl ester formulation capacity, as EPA corrosion resistance standards mandate specialized reactor infrastructure and testing documentation. Five-to-ten year viability favors resin-integrated formulators with REACH-compliant substance portfolios and established DOT prequalification status. Acquisition targets should display captive supply chain positioning or certified applicator network density. Monitor state-level durability mandate harmonization as inflection indicator for specification volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Precursors | BASF SE and Wacker Chemie AG control bisphenol-A supply to stabilize formulation margins against crude derivative volatility. |
| Certified Applicator Network Expansion | Sika AG deepens channel control through specialized distribution partnerships with civil engineering contractors in Gulf Coast corridors. |
| Prefabricated Component Standardization | Modular trench drain programs bypass project-specific casting to accelerate route-to-market through distributor stocking. |
| Bio-Based Resin Development | Lignin-derived epoxy precursors access EU Green Deal procurement preferences and green public tender weighting. |
| Digital Specification Platform Integration | Building information modeling interoperability compresses contractor prequalification timelines for complex containment geometries. |
Research Approach
A spread of perspectives from plant managers at German industrial flooring contractors, procurement leads at US Gulf Coast petrochemical operators, distribution channel partners serving state DOT corridors, and technical R&D directors at resin-integrated formulators converged on the working assumptions. Secondary validation drew from EPA corrosion resistance standard filings, state DOT prequalification list documentation, REACH substance dossier databases, and customs trade data on bisphenol-A derivative flows. Bottom-up project pipeline assessment and top-down infrastructure spending allocation models were triangulated to anchor volume estimates.
Segmentation dimensions modeled span resin chemistry tier, application severity grade, end-user specification authority, and packaging format across the projection horizon. CAGRs were derived from installed base replacement cycles and new specification penetration curves, with bridge rehabilitation and chemical containment application growth rates cross-referenced against DOT durability mandate adoption timelines and EPA hazardous waste containment compliance deadlines.
Underlying assumptions cover state-level DOT specification harmonization velocity and resin precursor feedstock availability, with deviation risk concentrated in amine hardener supply disruptions and thermal curing protocol standardization delays. Recalibration cycles align with material shifts in federal environmental mandate enforcement and REACH dossier renewal timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Exterior Doors Market
Building Materials
Construction Coatings Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
Plaster Accelerator Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Bolt (Fastener) Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Malaysia Architectural Coatings Market
Building Materials
North America Concrete Admixtures Market
Building Materials
Thin Brick Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Cladding Market
Building Materials
China Architectural Coatings Market
Building Materials
North America Building and Construction Sheets Market