
 Steel Sleepers Market | 2026-2036
Steel Sleepers Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Sleepers Market Insights
EU Green Deal carbon-border adjustments is expanding compliance costs for imported steel sleeper producers seeking European rail contracts. British Steel leverages integrated UK steelmaking to sustain domestic track renewal programs. AGICO Rail anchors its position across Asian freight networks through specialized section steel sleeper fabrication. Shanghai Bosheng Industries competes on elevated track installations with hardened alloy formulations.
Steel sleepers are structural rail support elements manufactured from rolled steel sections or fabricated box profiles, typically weighing 50-90 kg per unit and designed to withstand wheel loads exceeding 25 tonnes on standard-gauge track. They distribute vertical, lateral, and longitudinal forces from passing trains into ballast or slab track substructures while providing gauge retention and electrical isolation where specified. Section steel sleepers dominate legacy replacement cycles across European mainlines due to established supply chains and interoperability certification. Box steel sleepers are gaining share in urban transit lines where vibration damping and space constraints favor enclosed-profile designs. Composite steel sleepers, embedding polymer or rubber cores within steel shells, command premium positioning in tunnel tracks and bridge tracks where corrosion resistance and acoustic mitigation justify higher procurement outlays.
FRA track safety standards in the United States mandate periodic gauge strength testing that elevates steel sleeper specifications on Class I railroads. BIS certification requirements in India restrict imports lacking domestic fatigue-test documentation, channeling volume toward local producers like Godrej. China's GB/T 2585 rail-fastener standards, enforced by SAMR, shape steel sleeper interface geometry for export-bound manufacturers. Stakeholders must monitor how evolving EPD and lifecycle-carbon thresholds rewrite procurement scoring before the next major renewal cycle.
Market Dynamics
Heavy-axle freight corridors are forcing rapid material substitution from timber to steel across Brazil's iron ore railways and Australia's Pilbara networks, compressing replacement cycles from fifteen to eight years.
Growth Catalysts
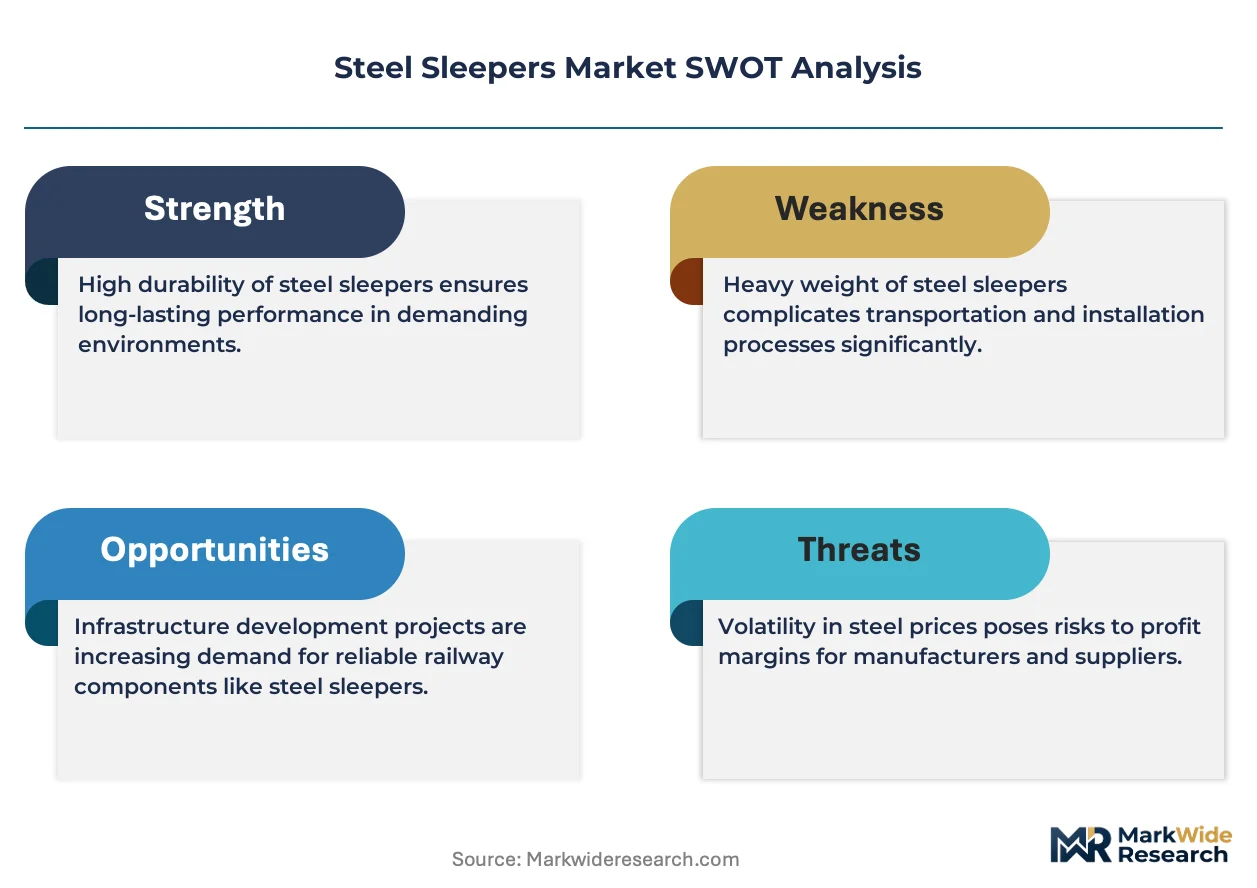
- EN 13674 rolling stock compatibility:European interoperability mandates are accelerating recertification programs that favor steel sleeper replacement over timber rehabilitation on legacy mainlines.
- Polymer-core composite fabrication:Tunnel and bridge applications are pulling hybrid steel-polymer designs into specification sheets where acoustic mitigation and corrosion resistance justify premium positioning.
- Dedicated Freight Corridor zones:India's electrified heavy-haul networks are specifying steel sleepers for 25-tonne axle loads across 3,300 kilometers of new track.
Market Restraints
- Scrap steel price volatility:Section steel sleeper producers face margin compression when ferrous scrap benchmarks spike above integrated mill feedstock costs.
- Chinese supply concentration:GB/T 2585-certified fabrication capacity clusters in Hebei and Jiangsu provinces, creating single-source risk for export-dependent buyers.
- Composite timber substitution:Treated hardwood sleepers retain cost advantage below 20-tonne axle loads on secondary branch lines in Southeast Asian markets.
Strategic Opportunities
- Urban transit vibration damping:Box-profile steel sleepers with elastomer isolation layers are penetrating metro extensions in São Paulo and Mexico City where surface noise restrictions apply.
- EU Green Deal carbon-border adjustments:European procurement scoring is beginning to weight embodied carbon, favoring electric-arc-furnace steel from integrated European mills over imported basic-oxygen-furnace product.
- Digital twin track monitoring:Sensor-embedded steel sleepers enabling real-time load monitoring are creating aftermarket service revenue streams for infrastructure operators.
Industry Challenges
- Fatigue-test documentation gaps:Indian BIS certification requires domestic testing protocols that foreign suppliers struggle to replicate without local laboratory partnerships.
- Ballast interface standardization:Shoulder width and tamping compatibility varies across British, German, and Japanese track geometries, fragmenting production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Sleepers Market |
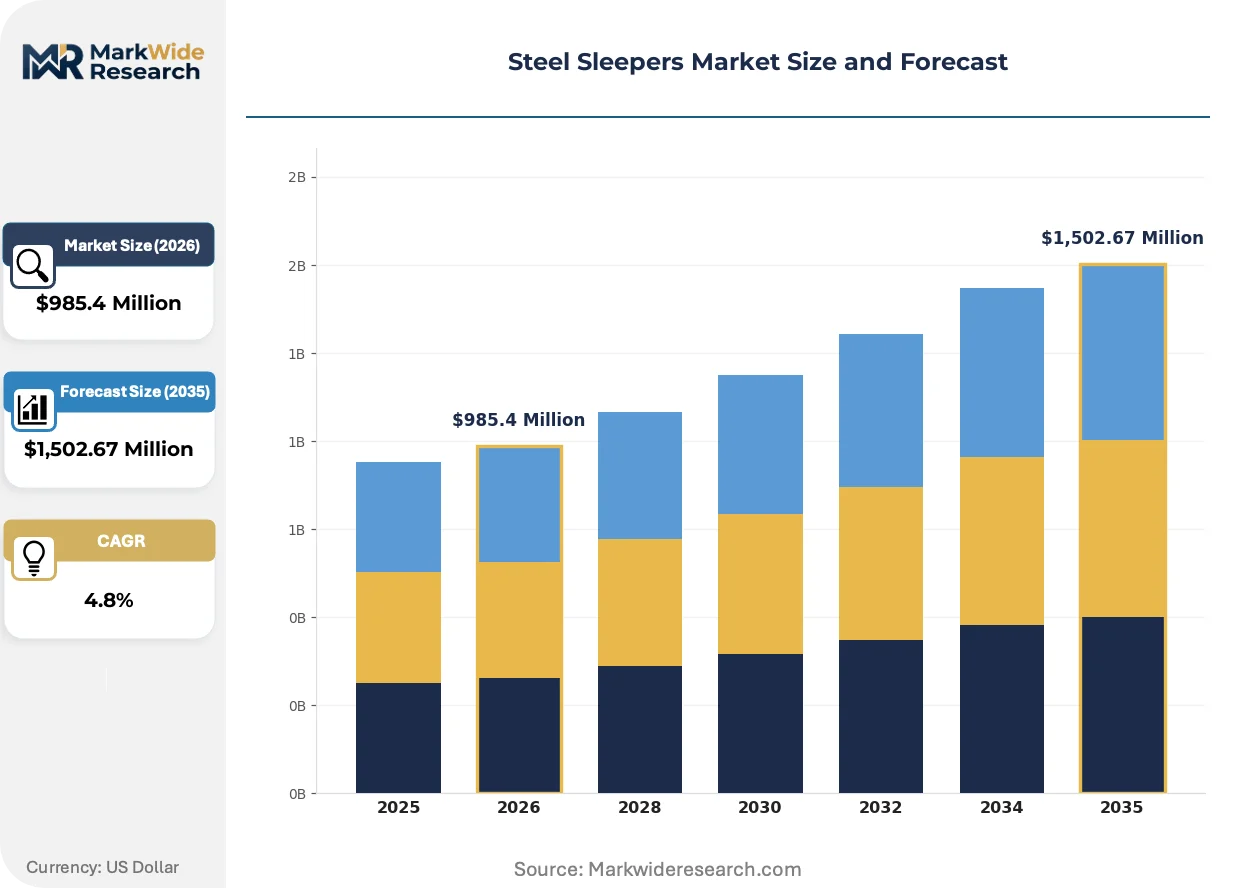
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,502.67 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Section Steel Sleepers, Box Steel Sleepers, Foamed Steel Sleepers, Mono Block Steel Sleepers, Composite Steel Sleepers Application: High-Speed Railways, Urban Transit Lines, Freight Rail, Light Rail Transit, Heavy Duty Rail Installation Environment: Elevated Tracks, At-Grade Tracks, Subsurface Tracks, Bridge Tracks, Tunnel Tracks, Yard Tracks End User: Railway Infrastructure Companies, Transit Authorities, Freight Operators, Track Maintenance Firms, Engineering Contractors |
| Companies Covered | British Steel, Cold Forge, Trackwork, DENA Stahlbau, Liberty, Jekay Group, AGICO Rail, Godrej, Shanghai Bosheng Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Sleepers Market Trends and Innovations
Material science advances and procurement digitization are restructuring how steel sleepers are specified, manufactured, and deployed across freight and passenger networks.
Hardened alloy formulations with manganese enrichment are overtaking conventional carbon steel in elevated track installations where thermal cycling and salt exposure accelerate corrosion. Dubai Metro's Red Line extension and Bangkok's suburban commuter corridors have specified these alloys for 40-year design lives. The shift is compressing supplier qualification timelines as mills must demonstrate continuous cooling transformation data to win specifications.
REACH substance restrictions on hexavalent chromium conversion coatings are forcing European mills to adopt trivalent passivation or zinc-nickel plating for corrosion protection. Surface treatment lines require capital reconfiguration, and certification delays of six to twelve months are common. German KBA track component approvals now require coating migration testing that adds third-party laboratory costs to every production batch.
Performance-based maintenance contracts are unbundling sleeper replacement from civil works packages on Brazilian and Australian heavy-haul networks. Contractors now bid unit-rate pricing per installed sleeper rather than lump-sum track renewals, transferring inventory risk to manufacturers. This model is most visible in Vale's Carajás Railway and Rio Tinto's Pilbara iron ore lines, where volume guarantees anchor multi-year supply agreements.
Steel Sleepers Market Segmentation
Steel sleeper procurement decisions hinge on load-bearing requirements, environmental exposure, and lifecycle cost calculations that vary sharply across rail network types. Specification fragmentation across product geometries, installation contexts, and operator categories creates distinct competitive arenas with divergent margin structures and certification barriers.
Product Type:
Section steel sleepers function as standalone structural elements in legacy replacement cycles, while composite and foamed variants embed polymer cores that shift failure modes from corrosion to delamination.
- Section Steel Sleepers:Rolled I-beam or channel profiles weighing 50-80 kg dominate European mainline renewal programs where EN 13674 interoperability certification anchors supplier relationships. Deutsche Bahn and SNCF procurement specifications favor these geometries for their established ballast interface and tamping machine compatibility.
- Box Steel Sleepers:Enclosed rectangular or trapezoidal hollow sections accommodate elastomer isolation layers for vibration-sensitive installations. São Paulo Metro and Mexico City STC have specified box profiles with integrated rubber pads for elevated viaduct extensions where surface noise restrictions apply.
- Foamed Steel Sleepers:Cellular steel cores with polymer infiltration reduce weight to 35-45 kg for manual handling in tunnel maintenance windows.
- Mono Block Steel Sleepers:Cast or forged single-piece designs eliminate field bolting for high-vibration environments.
- Composite Steel Sleepers:Steel shells encapsulating recycled rubber or polyurethane cores command premium positioning in India's Dedicated Freight Corridor tunnel sections where 25-tonne axle loads meet humidity extremes.
Section steel sleepers lead volumes today; composite steel sleepers are gaining share fastest.
Application:
Cost tier separation between premium-performance corridors and maintenance-minimized branch lines determines material specification and supplier qualification intensity.
- High-Speed Railways:Continuous welded rail on slab track demands precision-manufactured sleepers with sub-millimeter gauge tolerance. Japan's Shinkansen extensions and Spain's AVE corridors specify hardened manganese-alloy formulations for thermal cycling resistance.
- Freight Rail:Heavy-haul iron ore networks in Australia's Pilbara and Brazil's Carajás basin compress replacement cycles through 40-tonne concentrated axle loads. Vale and Rio Tinto have shifted procurement from timber to steel on curves and grades where lateral forces accelerate degradation.
- Urban Transit Lines:Metro systems prioritize acoustic mitigation and electromagnetic compatibility over absolute load capacity.
- Light Rail Transit:Mixed-traffic street running imposes weight constraints and shallow foundation requirements.
- Heavy Duty Rail:Industrial mining and port shuttle operations subject sleepers to impact loading from uneven track geometry.
Freight rail dominates current procurement tonnage; high-speed railways show the steepest specification escalation trajectory.
Installation Environment:
Volume concentration varies with climate exposure and accessibility constraints that alter corrosion risk and maintenance economics.
- Elevated Tracks:Thermal expansion cycling and salt spray exposure in coastal environments accelerate fatigue crack initiation. Dubai Metro's Red Line extension specified zinc-nickel plated box sleepers after REACH restrictions eliminated hexavalent chromium conversion coatings.
- Tunnel Tracks:Humidity-saturated conditions with limited ventilation demand corrosion-resistant surface treatments and rapid-installation designs. London Underground's Deep Tube upgrade programs favor composite steel sleepers for their 40-year design life in confined maintenance windows.
- At-Grade Tracks:Standard ballasted construction accommodates conventional section profiles across temperate climates.
- Subsurface Tracks:Cut-and-cover construction with groundwater exposure requires drainage-integrated sleeper geometries.
- Bridge Tracks:Structural load limits and vibration transmission concerns favor lightweight hollow-section designs.
- Yard Tracks:Low-speed shunting operations with frequent impact loading tolerate heavier, simpler profiles.
At-grade installations retain the largest installed base; tunnel and elevated applications are expanding most quickly.
End User:
Customer type determines contract structure, from unit-rate maintenance agreements to lump-sum infrastructure packages.
- Railway Infrastructure Companies:State-owned network operators like Network Rail and Deutsche Bahn aggregate demand through multi-year framework agreements with embedded carbon scoring. EU Green Deal procurement guidelines now weight electric-arc-furnace steel origin in tender evaluation.
- Freight Operators:Mining and logistics companies increasingly unbundle sleeper replacement from civil works contracts. Vale's Carajás Railway operates on performance-based unit-rate pricing that transfers inventory risk to manufacturers.
- Transit Authorities:Municipal procurement favors local content requirements and noise-mitigation specifications.
- Track Maintenance Firms:Service contractors optimize for installation speed and compatibility with existing tamping fleets.
- Engineering Contractors:Design-build consortia specify sleeper performance parameters rather than prescriptive geometries.
Railway infrastructure companies anchor current procurement volumes; freight operators are restructuring contract terms fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgical engineering talent clusters in Germany's Ruhr Valley and India's Maharashtra state anchor steel sleeper fabrication expertise. Foundry workers and rail infrastructure specialists concentrate near heavy-haul corridors where procurement specifications originate. This workforce distribution shapes manufacturing investment patterns across key demand centers.
Germany
Deutsche Bahn's continuous track renewal programs drive section steel sleeper procurement across legacy mainlines. The KBA mandates coating migration testing under REACH substance restrictions, forcing mills to adopt trivalent passivation. The Ruhr Valley industrial cluster around Duisburg hosts integrated steelmaking capacity serving domestic rail contracts with electric-arc-furnace production.
India
The Dedicated Freight Corridor Corporation specifies steel sleepers for 25-tonne axle loads across 3,300 kilometers of electrified heavy-haul track. BIS certification requirements restrict imports lacking domestic fatigue-test documentation, channeling volume toward local producers. Manufacturing concentrates in Maharashtra and Gujarat where Godrej anchors fabrication capacity for tunnel and bridge applications.
China
GB/T 2585 rail-fastener standards enforced by SAMR shape steel sleeper interface geometry for export-bound manufacturers. Hebei and Jiangsu provinces cluster certified fabrication capacity, creating supply concentration for international buyers. Shanghai Bosheng Industries exemplifies the hardened alloy specialization targeting elevated track installations in coastal environments.
Australia
Rio Tinto's Pilbara iron ore lines compress replacement cycles from fifteen to eight years through 40-tonne concentrated axle loads. The country's national rail safety regulator mandates periodic gauge strength testing that elevates steel sleeper specifications on heavy-haul networks. Perth-based engineering contractors unbundle sleeper replacement from civil works packages, transferring inventory risk to manufacturers.
Brazil
Vale's Carajás Railway operates on performance-based unit-rate pricing that transfers inventory risk to steel sleeper suppliers. ANVISA-equivalent track component standards govern material specifications for iron ore export corridors. Manufacturing partnerships concentrate in Minas Gerais state near the mining belt where lateral forces on curves accelerate material degradation.
Steel Sleepers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct certification and specification tiers. The vendor base separates into three strategic archetypes: integrated steelmakers with captive rail product divisions, specialized section fabricators serving regional freight networks, and composite technology developers targeting tunnel and elevated applications. Capacity expansion and strategic partnerships dominate competitive moves as producers seek BIS, EN 13674, and GB/T 2585 certifications to unlock framework agreements.
Among European integrated producers, British Steel represents the domestic supply chain archetype leveraging UK steelmaking for track renewal programs. AGICO Rail and Shanghai Bosheng Industries occupy positions across Asian fabrication tiers, with the former anchoring specialized section production and the latter exemplifying hardened alloy formulation capabilities for corrosion-resistant installations. These three names illustrate how geographic certification clustering shapes competitive positioning without requiring specific product or technology claims.
| Leading Market Players |
|---|
| British Steel |
| Cold Forge |
| Trackwork |
| DENA Stahlbau |
| Liberty |
| Jekay Group |
| AGICO Rail |
| Godrej |
| Shanghai Bosheng Industries |
| Others |
Pricing and Supply Chain Analysis
Ferrous scrap benchmarks transmit volatility from integrated mill feedstock costs through to section steel sleeper pricing tiers, compressing margins when Hebei province spot prices spike above electric-arc-furnace alternatives. This input-cost channeling favors domestic European producers under EU Green Deal carbon-border adjustments, while export-dependent buyers face dual exposure to Chinese supply concentration and currency-adjusted procurement premiums.
Pricing Analysis
Bundled civil-works contracts are fragmenting into unbundled unit-rate sleeper replacement agreements across Brazilian and Australian heavy-haul networks. Pricing stratifies across premium composite steel-polymer hybrids, standard section profiles with EN 13674 certification, and economy-grade box sleepers for yard tracks. Cost compression in standard section tiers is intensifying because Vale and Rio Tinto have transferred inventory risk to manufacturers through performance-based contracts. Freight operators exhibit highest price sensitivity; urban transit authorities with noise-mitigation mandates show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Hebei and Jiangsu provinces, where GB/T 2585-certified fabrication capacity clusters for export-bound manufacturers. Raw material flows draw from Australian iron ore, domestic Chinese ferrous scrap, and Indian manganese alloys. Tariff exposure from EU carbon-border adjustments threatens cost competitiveness for basic-oxygen-furnace product. Distribution runs through state-owned railway infrastructure framework agreements and mining company direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel sleepers constitute a late-cycle quality story as heavy-axle freight corridors displace timber with premium corrosion-resistant specifications. The shift toward 40-year design-life hardened alloys in tunnel and elevated applications rewards certification depth over commodity volume.
For Market Incumbents: Anchor multi-year framework agreements with Dedicated Freight Corridor zones through BIS-certified domestic fatigue-test partnerships. Deepen backward integration into manganese-alloy supply to defend against scrap price volatility. Prioritize trivalent passivation line investments before REACH coating migration deadlines eliminate hexavalent chromium alternatives. For New Entrants and Emerging Players: Transit authorities in São Paulo and Mexico City represent underserved buyer archetypes seeking box-profile elastomer isolation for elevated viaduct extensions. Tunnel maintenance contractors in London Underground and Dubai Metro need rapid-installation foamed steel designs. Pursue sensor-embedded digital twin sleepers as a differentiated aftermarket service entry point. For Investors and Strategic Acquirers: Consolidation pressure builds where BIS, EN 13674, and GB/T 2585 certification requirements fragment viable supplier pools below sustainable scale. Long-term viability favors electric-arc-furnace producers with integrated European mill access and carbon-scored procurement positioning. Watch for Indian DFC zone volume guarantees as inflection signal for regional manufacturing investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Manganese-Alloy Supply | Secures feedstock cost stability for hardened steel formulations specified by Dubai Metro. |
| BIS Certification Partnership | Unlocks Dedicated Freight Corridor procurement closed to foreign fatigue-test documentation gaps. |
| Trivalent Passivation Line Investment | Meets KBA coating migration requirements under REACH hexavalent chromium restrictions. |
| Sensor-Embedded Digital Twin Development | Creates recurring aftermarket revenue from real-time load monitoring for Rio Tinto networks. |
| Urban Transit Box-Profile Specialization | Captures São Paulo Metro noise-mitigation specifications with elastomer isolation layers. |
Research Methodology
Bottom-up freight corridor modeling reconciled against top-down fabrication capacity tracking forms the analytical core of this study. Primary interviews with railway infrastructure procurement officers, track maintenance contractors, steel mill technical directors, and mining logistics planners combined with secondary validation from customs trade data, BIS certification registries, Deutsche Bahn framework agreement disclosures, and SAMR GB/T standard filings. Triangulation between supply-side concentration metrics and demand-side replacement cycle data ensures cross-verified volume estimates.
Historical trendline analysis of timber-to-steel substitution rates across Pilbara and Carajás networks informs projection elasticity assumptions across the analysis window. Segmentation modeling spans product geometry, installation environment, axle-load tier, and end-user contract structure. CAGRs derive from weighted average of corridor-specific replacement cycle compression and specification escalation trajectories. Industry-specific forecast inputs include EN 13674 recertification timelines and EU carbon-border adjustment implementation phasing.
Underlying measurement precision varies by segment; composite steel-polymer and high-speed railway specifications carry tighter precision than yard-track economy grades due to concentrated buyer transparency. Forecasts reflect documented assumptions on scrap price volatility bands, regulatory certification delay distributions, and infrastructure budget allocation priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Solar Control Window Film Market
Building Materials
North America Concrete Admixtures Market
Building Materials
East Africa White Cement Market
Building Materials
Blended Cement Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
India Aluminum Door and Window Market
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
Building and Construction Plastics Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Qatar Facade Market
Building Materials
LAMEA Engineered Stone Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Composite Rebar Market
Building Materials
Fiber Cement Market