
 Indonesia Dry Mix Mortar Market | 2026-2036
Indonesia Dry Mix Mortar Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Dry Mix Mortar Market Insights
The Indonesia dry mix mortar sector is repositioning around a widening gap between premium polymer-modified tile adhesives and commodity-grade masonry mortars. Drymix Indonesia leverages backward integration into local silica sand reserves to control raw material costs. Semen Indonesia Group anchors its position through captive cement supply and nationwide distribution reach. Mortindo Perkasa differentiates via specialized floor mortar formulations targeting high-traffic commercial installations.
Dry mix mortar comprises precisely blended cementitious binders, graded aggregates, and functional additives delivered in ready-to-use form requiring only water addition on site, with compressive strength ratings typically spanning five to forty megapascals depending on formulation design. Tile adhesives command the strongest margin pool due to polymer modification requirements and technical specification intensity in Indonesia's humid tropical climate. Floor mortar competes on volume scale across Jakarta's commercial tower pipeline, while repair mortar remains nascent but structurally important for Indonesia's aging public infrastructure stock. Residential end users drive baseline demand through government-backed affordable housing programs.
BIS-equivalent SNI standards enforced by Indonesia's national standardization agency shape product compliance thresholds, while Ministry of Public Works and Housing regulations mandate quality certification for state-funded construction projects. The Ministry of Industry's downstream cement policies influence local manufacturing investment and import substitution dynamics. Stakeholders must monitor evolving green building codes and their material specification ripple effects across procurement chains.
Market Dynamics
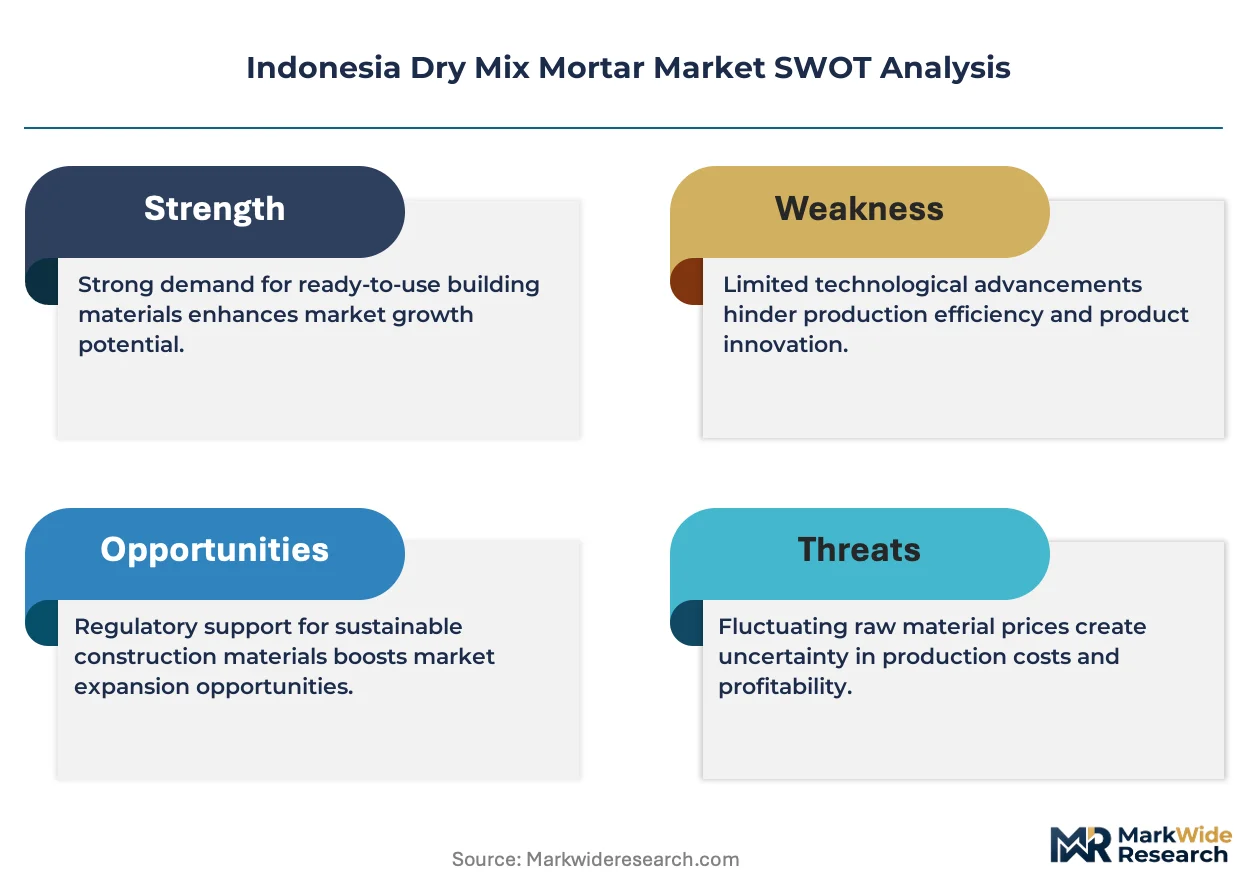
Indonesia's mandatory SNI certification regime is compressing the supplier base while polymer-modified formulations capture margin from commodity-grade products, creating a bifurcated competitive landscape where technical compliance separates survivors from marginal operators.
Growth Catalysts
- Public Works Mandates:The Ministry of Public Works and Housing requires quality certification for all state-funded construction, channeling procurement toward certified dry mix mortar suppliers.
- High-Rise Density:Jakarta and Surabaya residential towers favor pre-mixed formulations over site-mixed alternatives due to logistics constraints and quality consistency requirements.
- Silica Sand Access:Backward integration into local mineral reserves enables manufacturers to stabilize input costs against cement price volatility.
Market Restraints
- Cement Price Volatility:Semen Indonesia's dominant position in clinker supply exposes downstream formulators to input cost squeezes without transfer pricing power.
- Import Dependency for Polymers:Redispersible polymer powders rely on Southeast Asian chemical imports, creating forex exposure and supply security gaps.
- Technical Labor Scarcity:Application-grade expertise in polymer-modified systems remains concentrated among specialized contractor networks, limiting penetration speed.
Strategic Opportunities
- Eastern Indonesia Expansion:Sulawesi and Papua infrastructure corridors remain underserved by certified suppliers, offering first-mover positioning ahead of port modernization.
- Repair Mortar Segment:Aging public infrastructure stock creates demand for structural rehabilitation formulations currently supplied by imports.
- Green Building Codes:Anticipated Ministry of Environment regulations on embodied carbon will favor low-clinker and supplementary cementitious material formulations.
Industry Challenges
- SNI Certification Timelines:Bureaucratic testing protocols at Indonesia's national standardization agency delay product launches by six to twelve months.
- Batch Consistency Control:Tropical humidity degrades pre-mix stability during storage and transport, requiring climate-adapted packaging investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Dry Mix Mortar Market |
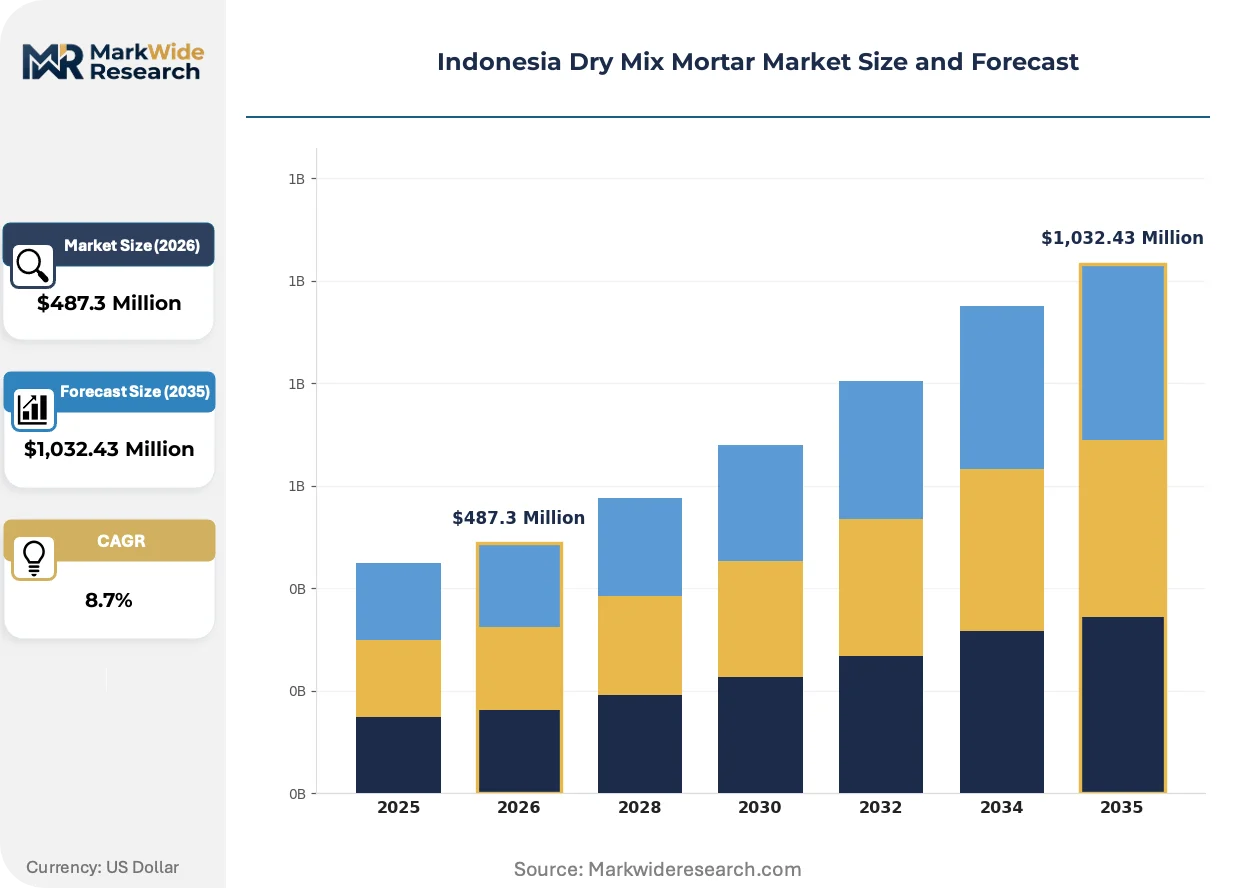
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Bed Mortar, Tile Adhesives, Floor Mortar, Repair Mortar End User: Residential, Commercial, Industrial, Infrastructure Distribution Channel: Online, Offline, Direct Sales, Distributors Packaging Type: Bags, Bulk, Pallets, Containers |
| Companies Covered | Drymix Indonesia, Mortindo Perkasa, Jaya Mortar Nusantara, Semen Indonesia Group, Holcim Indonesia Tbk, Indocement Tunggal Prakarsa Tbk, PT Adiwisesa Mandiri, PT POWERBLOCK INDONESIA, PT RAPI Hijau Perkasa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Dry Mix Mortar Market Trends and Innovations
Formulation chemistry is advancing through polymer science integration while regulatory pressure and procurement professionalization reshape how specifications travel from design to application.
Polymer-modified tile adhesives are converging with nanosilica additives to enhance bond strength in Indonesia's high-humidity conditions. Commercial tower developers in Jakarta specify these systems for porcelain tile installations above grade. The technology is compressing price premiums between mid-tier and premium adhesive categories.
Indonesia's national standardization agency is tightening SNI enforcement for imported dry mix products, requiring local testing laboratory validation. This policy is displacing gray-market imports from regional traders. Domestic manufacturers with captive laboratory capacity are capturing specification share in government procurement channels.
Contractor purchasing patterns are consolidating around project-level supply agreements with technical service attachments. Large residential developers in Java's urban corridor now demand on-site mixing support and application training as standard contract terms. This behavior is most pronounced in Surabaya's commercial real estate pipeline where foreign joint-venture developers impose international quality protocols.
Indonesia Dry Mix Mortar Market Segmentation
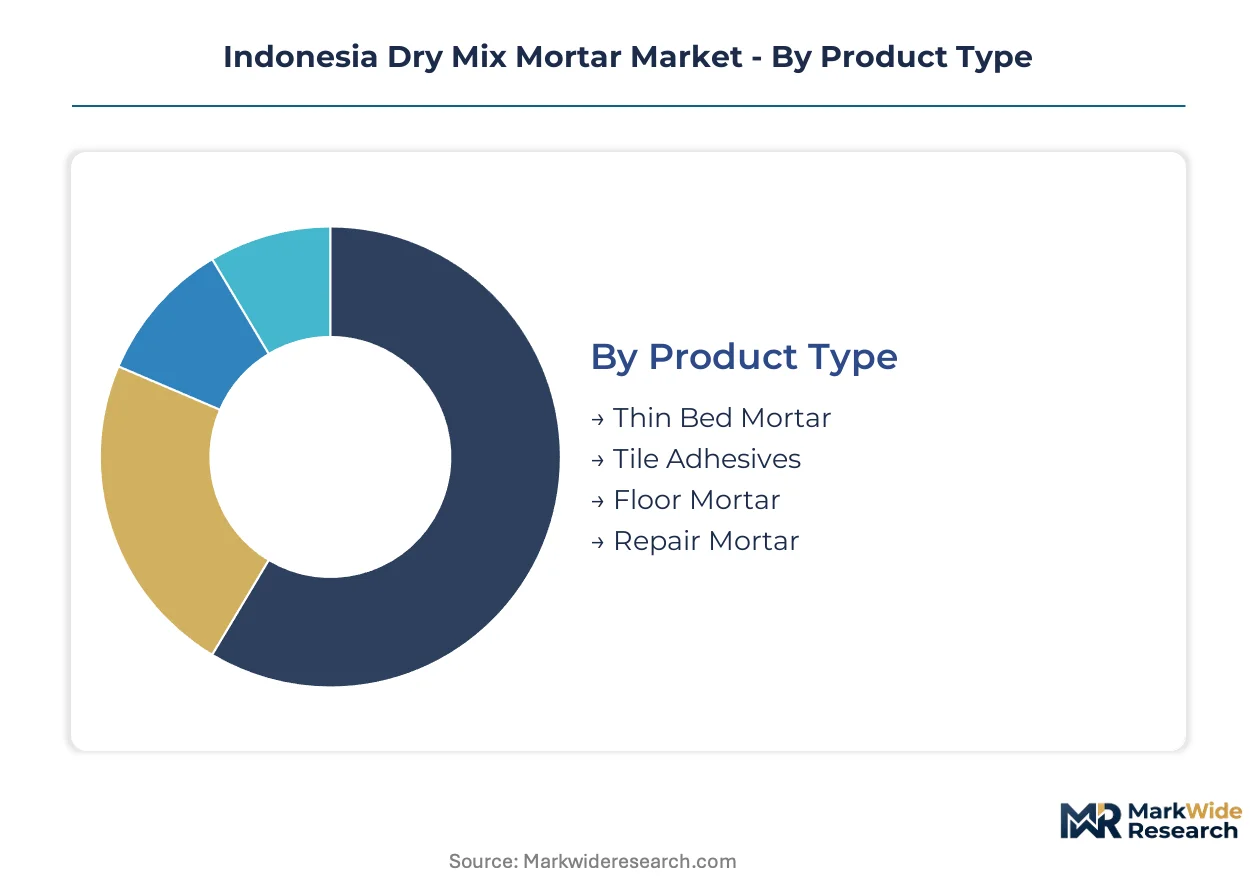
Indonesia's dry mix mortar segmentation reveals how formulation complexity and logistics requirements fragment procurement patterns across Java's construction corridor. Each dimension carries distinct margin implications tied to certification compliance and transport economics.
Product Type:
Volume concentrates in commodity-grade masonry applications while premium capture attaches to polymer-modified specialty formulations requiring technical specification intensity.
- Tile Adhesives:Polymer-modified cementitious systems incorporating redispersible powders and nanosilica additives achieve enhanced bond strength in high-humidity tropical conditions. Demand clusters in Jakarta and Surabaya high-rise residential towers where porcelain tile specifications above grade require technical compliance documentation. SNI certification mandates compress supplier margins while favoring domestic laboratory-equipped manufacturers.
- Floor Mortar:Self-leveling and screed formulations span five to forty megapascal compressive strength ratings depending on aggregate grading and binder ratios. Commercial tower pipelines across Jakarta's central business district specify these systems for high-traffic installations, with volume scale offsetting thinner margin profiles compared to adhesive categories.
- Thin Bed Mortar:Precision-blended fine-aggregate systems for thin-set tile applications.
- Repair Mortar:Structural rehabilitation formulations targeting aging public infrastructure with specialized bonding agents.
Mature deployment sits with floor mortar across established commercial construction workflows. Newer deployment is concentrated in repair mortar as infrastructure maintenance budgets expand.
End User:
Procurement professionalization varies sharply across customer categories, with state-funded channels imposing certification requirements that reshape supplier qualification thresholds.
- Residential:Government-backed affordable housing programs in Java's urban corridor drive baseline volume demand through standardized masonry mortar specifications. Developer consolidation around project-level supply agreements increasingly bundles technical service attachments including on-site mixing support and application training.
- Commercial:Foreign joint-venture developers in Surabaya's real estate pipeline impose international quality protocols that favor polymer-modified systems with full technical documentation. Procurement teams specify pre-mixed formulations to resolve logistics constraints at high-rise construction sites.
- Infrastructure:Ministry of Public Works and Housing mandates quality certification for all state-funded construction, channeling procurement toward SNI-certified domestic suppliers with captive laboratory capacity.
- Industrial:Manufacturing facility construction and maintenance applications with specialized chemical resistance requirements.
Certified supply relationships are deepest in infrastructure procurement. Commercial end users are expanding certified supplier rosters fastest as international developer standards propagate.
Distribution Channel:
Channel selection reflects project scale and technical support requirements, with large developers bypassing traditional wholesale layers.
- Direct Sales:Project-level supply agreements dominate large residential and commercial developments, bundling material delivery with application training and on-site technical support.
- Distributors:Regional building material wholesalers serve mid-tier contractors across Java's secondary cities with inventory carrying and credit terms.
- Offline:Traditional construction supply yards and retail hardware channels.
- Online:Emerging digital procurement platforms for standardized product categories with transparent pricing.
Relationship-based contracting concentrates in direct sales channels. Digital adoption is climbing fastest among smaller residential contractors seeking price transparency.
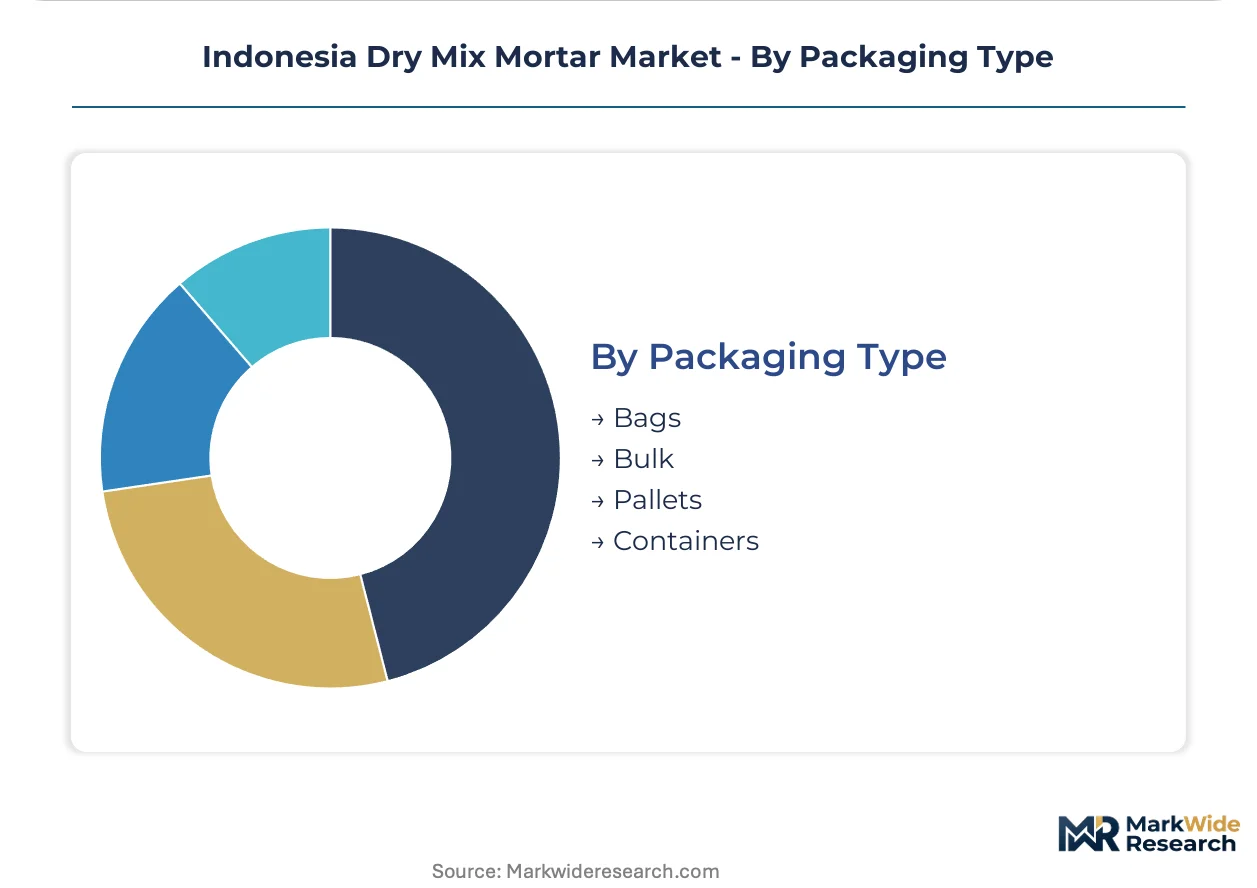
Packaging Type:
Packaging economics hinge on tropical humidity degradation risks and transport distance to construction sites.
- Bags:Multi-layer moisture-barrier packaging dominates tile adhesive and repair mortar categories where pre-mix stability determines application performance. Climate-adapted packaging investments separate qualified suppliers from marginal operators.
- Bulk:Pneumatic delivery systems serve large commercial tower projects in Jakarta with dedicated silo storage, minimizing handling costs at volume scale.
- Pallets:Unitized load configurations for distributor channel efficiency.
- Containers:Flexible intermediate bulk containers for mid-scale commercial applications.
Climate-protected packaging maturity sits with bagged products. Bulk deployment is expanding fastest among centralized commercial projects with dedicated logistics infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta anchors Indonesia's dry mix mortar consumption through its high-rise residential pipeline and commercial tower density. Java's urban corridor concentrates procurement volume where infrastructure spending and real estate development overlap.
Java
Residential towers in Jakarta and Surabaya drive polymer-modified tile adhesive specifications. Ministry of Public Works and Housing mandates channel state-funded procurement toward SNI-certified suppliers. The Jakarta-Bandung-Surabaya corridor hosts captive laboratory capacity and climate-adapted packaging investments.
Sumatra
Medan and Palembang construction activity generates masonry mortar volume for government-backed affordable housing. Regional distributors serve mid-tier contractors with inventory carrying and credit terms. Batam's industrial zone creates specialized demand for chemical-resistant floor formulations.
Sulawesi
Makassar infrastructure corridors remain underserved by certified dry mix suppliers. Port modernization projects ahead of nickel processing investments create first-mover positioning opportunities. Local silica sand reserves offer backward integration potential for manufacturers establishing production.
Kalimantan
East Kalimantan's new capital city relocation drives bulk mortar demand for government administrative construction. Pneumatic delivery systems serve centralized projects with dedicated silo storage. Samarinda and Balikpapan distribution networks expand to capture specification share.
Papua
Jayapura and Sorong infrastructure spending runs ahead of certified supplier coverage. Import dependency for polymer-modified systems creates forex exposure for project developers. Local batch consistency control challenges separate qualified operators from marginal entrants.
Indonesia Dry Mix Mortar Market Competitive Landscape
Capital-heavy cement producers compete with specialized mortar formulators across Indonesia's bifurcated supply base. Semen Indonesia's captive clinker supply anchors the upstream-integrated tier while independent blenders compete on formulation flexibility. Three archetypes dominate: national cement groups with distribution reach, regional specialists with silica sand integration, and import-dependent traders serving niche specifications. Competitive moves concentrate on SNI certification acquisition and project-level supply agreement consolidation.
Among Jakarta-based formulators, Drymix Indonesia exemplifies the backward-integrated archetype through local mineral reserve control. Mortindo Perkasa occupies a position within the specialty formulation tier referenced for floor mortar applications. Semen Indonesia Group anchors the cement-integrated segment through nationwide logistics infrastructure. These three patterns illustrate how raw material access and certification capacity separate sustainable operators from displacement risk.
| Leading Market Players |
|---|
| Drymix Indonesia |
| Mortindo Perkasa |
| Jaya Mortar Nusantara |
| Semen Indonesia Group |
| Holcim Indonesia Tbk |
| Indocement Tunggal Prakarsa Tbk |
| PT Adiwisesa Mandiri |
| PT POWERBLOCK INDONESIA |
| PT RAPI Hijau Perkasa |
| Others |
Pricing and Supply Chain Analysis
Backward integration into local silica sand reserves anchors both supply security and margin control for Indonesian dry mix mortar manufacturers, insulating formulators from cement price volatility while compressing procurement flexibility for competitors lacking mineral access.
Pricing Analysis
Value-based pricing anchored to compressive strength ratings and SNI certification tiers separates qualified domestic suppliers from gray-market imports. Three-tier pricing structure across premium polymer-modified, standard masonry-grade, and economy bulk formulations reflects formulation complexity and technical documentation depth. Cost compression in commodity-grade segments intensifies because Semen Indonesia's clinker dominance squeezes downstream margins without transfer pricing leverage. State-funded infrastructure procurement shows lowest price sensitivity due to mandated quality certification, while residential contractors in Java's secondary cities exhibit highest sensitivity.
Supply Chain Analysis
Direct-to-project channels handle high-rise commercial demand in Jakarta and Surabaya, bypassing wholesale layers for volume-scale efficiency. Raw material sourcing draws from domestic silica sand deposits in Java, imported redispersible polymer powders from Thailand and Malaysia, and captive cement supply from Semen Indonesia's nationwide clinker network. Single-source vulnerability in polymer imports creates forex exposure and supply security gaps for specialized formulations. Distribution runs through project-level supply agreements with technical service attachments for large developers, alongside regional distributors serving mid-tier contractors with inventory carrying and credit terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive mineral reserves and laboratory certification capacity determine sustainable positioning against input cost volatility and regulatory compliance thresholds.
For Market Incumbents: Anchor market position through SNI certification acquisition and climate-adapted packaging investments that marginal operators cannot replicate. Defend against emerging regional specialists by locking project-level supply agreements with foreign joint-venture developers in Surabaya's commercial pipeline. Prioritize laboratory capacity expansion to compress certification timelines from twelve months toward six. For New Entrants and Emerging Players: Enter via Sulawesi and Papua infrastructure corridors ahead of port modernization and nickel processing investments, where certified supplier coverage remains thin. Target repair mortar specifications for aging public infrastructure currently served by imports. Lead with specialized floor mortar formulations for high-traffic commercial installations where technical service bundling creates stickier customer relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by national cement groups seeking formulation capabilities and regional distribution footprints. Long-term viability favors operators with backward-integrated mineral access and captive laboratory infrastructure over import-dependent traders. Monitor Ministry of Environment green building code developments as inflection indicators for low-clinker formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Sand Reserves | Captive mineral supply stabilizes input costs against Semen Indonesia's cement pricing power. |
| SNI Certification Laboratory Investment | Domestic testing capacity accelerates product launches and displaces gray-market imports from government procurement. |
| Project-Level Supply Agreement Consolidation | Technical service bundling with large developers creates switching costs and specification lock-in. |
| Climate-Adapted Packaging Deployment | Moisture-barrier investments protect pre-mix stability during tropical storage and transport. |
| Eastern Indonesia Distribution Expansion | First-mover positioning in Sulawesi and Papua captures infrastructure spending ahead of certified competitor entry. |
Research Methodology
Trade publications, Ministry of Public Works and Housing regulatory filings, and BSN standardization records formed the secondary backbone, cross-referenced with primary interviews across plant managers at dry mix manufacturing facilities, procurement leads at Jakarta-based commercial developers, technical directors at SNI-certified laboratories, and regional distribution channel partners. Bottom-up volume estimates triangulated against top-down construction spending allocations across Java's urban corridor.
Historical trendline analysis tracked formulation adoption rates and certification penetration across product categories. Segmentation modeling spanned product type, end-user procurement channel, packaging format, and regional construction cluster. CAGRs derived from regression analysis of construction output correlations and polymer-modified formulation substitution patterns. Forecast inputs incorporated Ministry of Industry downstream cement policy trajectories and anticipated green building code implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cement price volatility spikes and SNI enforcement intensity shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Italy Facade Market
Building Materials
Building and Construction Sheets Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Rubbing Bricks Market
Building Materials
Brick Adhesive Market
Building Materials
North America Engineered Stone Market
Building Materials
HDG Steel Pipe Market
Building Materials
Natural Stone Market
Building Materials
US Cement Tiles Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
China Aluminum Door and Window Market
Building Materials
Geocells Market
Building Materials
Sprayed Concrete Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market