
 Truck Mounted Concrete Mixer Market | 2026-2036
Truck Mounted Concrete Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Mounted Concrete Mixer Market Analytics
Engine emissions compliance tier upgrades is unwinding legacy fleet economics across developed markets. SANY Group leverages captive hydraulic component production to compress delivery cycles for domestic infrastructure tenders. Liebherr Group anchors premium mixer drum fabrication with in-house steel alloy development, sustaining price positions in European commercial construction. Zoomlion Heavy Industry competes aggressively on volumetric mixer variants, extending its reach into Southeast Asian contractor fleets.
A truck mounted concrete mixer integrates a rotating drum assembly, hydraulic drive system, and chassis-mounted water tank to transport and discharge ready-mix concrete while preserving slump specifications between batch plant and pour site. Drum rotation speed, typically 0-14 RPM during transit and up to 14-16 RPM at discharge, prevents aggregate segregation and premature hydration across haul distances exceeding 90 minutes. Standard mixer configurations retain dominant volume in mature markets where batch plant density supports just-in-time delivery models, while volumetric mixer demand is accelerating fastest in remote infrastructure corridors where on-site proportioning eliminates transit-time penalties. Six cubic meter and eight cubic meter capacity classes concentrate margin pools, as contractors prioritize payload optimization over smaller drum sizes in fuel-cost-sensitive operating environments.
US EPA Phase 2 standards and EU F-Gas Regulation are tightening concurrently, forcing redesigns of refrigerant-based cab climate systems and diesel aftertreatment architectures in new chassis integrations. China's MIIT enforces GB fuel consumption limits that directly shape domestic OEM mixer platform development, while India's BIS certification mandates drum weld integrity testing that filters subscale fabricators from government tender eligibility. Stakeholders must monitor divergence between regional emissions timelines and hydraulic system electrification roadmaps, as premature platform bets risk stranded capacity across country-specific certification regimes.
Market Dynamics
EU F-Gas Regulation and US EPA Phase 2 standards are forcing simultaneous redesigns of hydraulic refrigerant systems and diesel aftertreatment architectures, compressing development cycles for chassis-integrated mixer platforms.
Growth Catalysts
- Urban infrastructure megaprojects:India's smart city concrete road programs and China's provincial highway expansion are accelerating fleet replacement cycles among contractors.
- Emissions compliance tier upgrades:GB fuel consumption limits enforced by China's MIIT are reshaping domestic OEM mixer platform specifications.
- Volumetric mixer technology:On-site proportioning capabilities eliminate transit-time penalties in remote infrastructure corridors across Southeast Asia.
Market Restraints
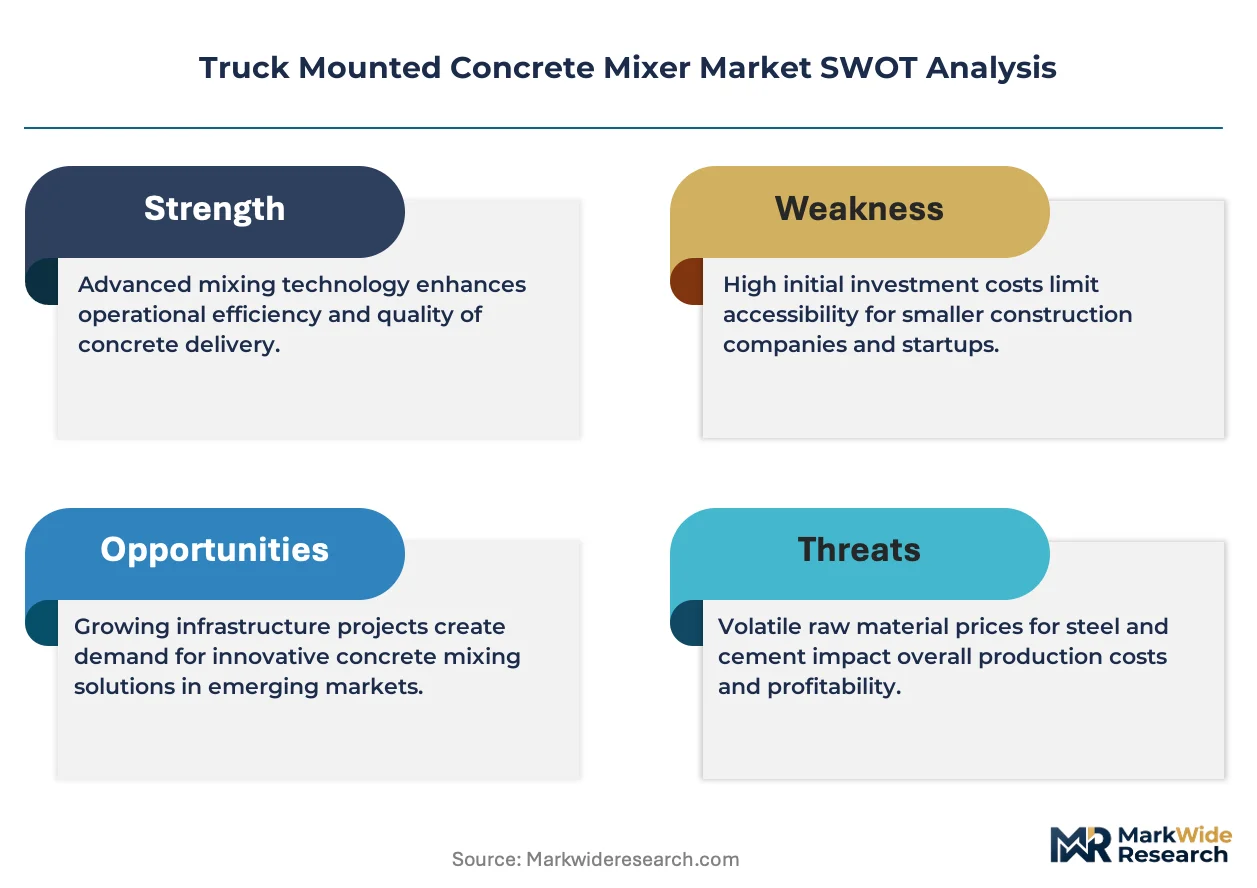
- Steel alloy input volatility:Drum fabrication relies on specialized steel grades subject to commodity price swings that compress fabricator margins.
- Hydraulic component supply concentration:Captive production of high-pressure pumps and motors clusters among integrated OEMs, limiting independent supplier participation.
- Certification timeline friction:India's BIS drum weld integrity testing mandates filter subscale fabricators from government tender eligibility.
Strategic Opportunities
- Electrification convergence:Battery-electric chassis platforms and regenerative hydraulic systems create white space for zero-emission mixer configurations.
- Rental fleet penetration:Contractor preference for operational flexibility over asset ownership expands equipment-as-a-service channels.
- Remote corridor deployment:Volumetric mixer variants address underpenetrated mining and dam construction sites in Brazil's interior states.
Industry Challenges
- Skill gap in hydraulic-electronic integration:Technicians trained on mechanical drive systems lack diagnostic capabilities for electrified powertrains.
- Legacy fleet stranding risk:Premature platform bets on electrification timelines risk stranded capacity across country-specific certification regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Mounted Concrete Mixer Market |
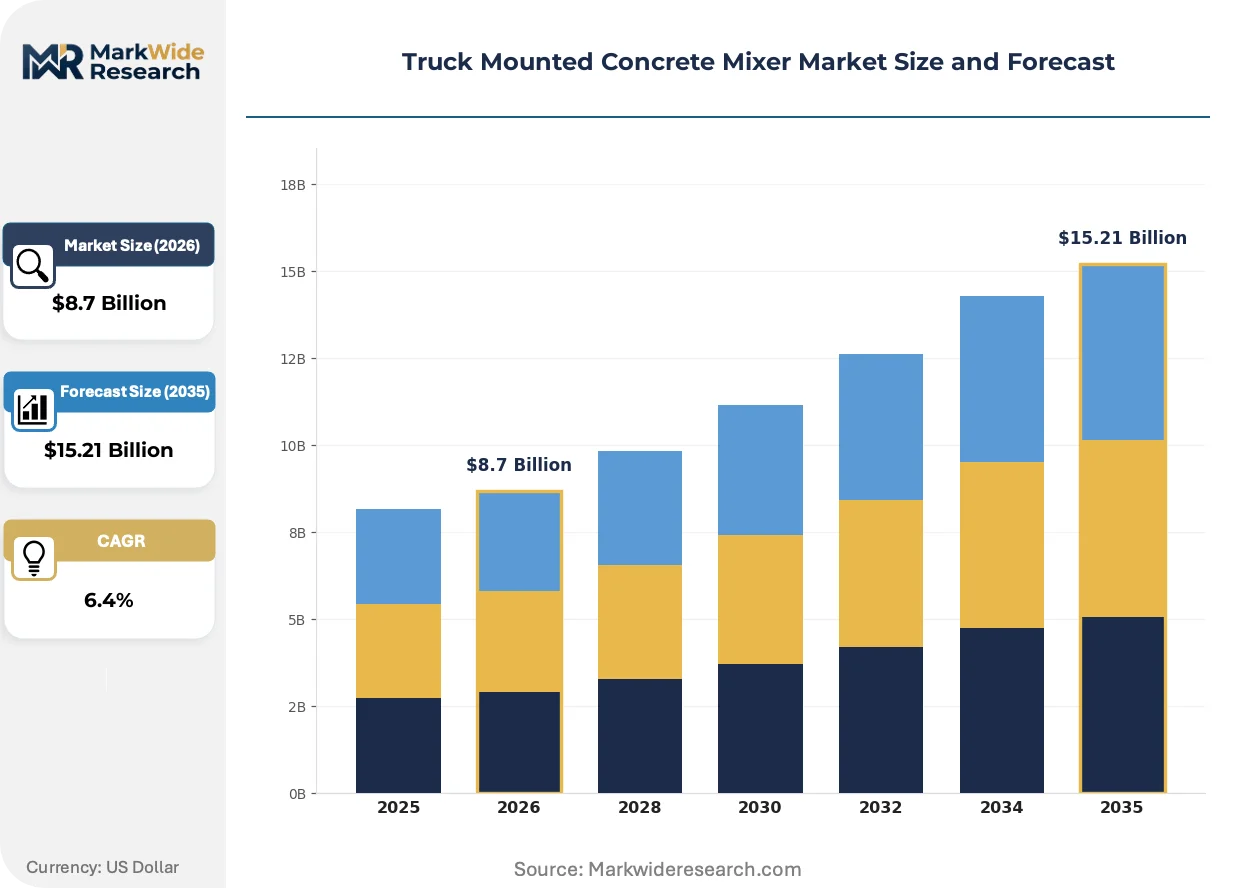
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mixer, Volumetric Mixer, Hydraulic Mixer, Reversing Mixer Application: Commercial Construction, Residential Construction, Infrastructure Projects, Heavy Industry End User: Contractors, Construction Companies, Government Agencies, Private Developers Capacity: 2 Cubic Meters, 4 Cubic Meters, 6 Cubic Meters, 8 Cubic Meters |
| Companies Covered | SANY Group, Zoomlion Heavy Industry, Liebherr Group, XCMG Group, Oshkosh Corporation, Putzmeister Holding GmbH, CIFA SpA, Volvo Group, Schwing Stetter India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Mounted Concrete Mixer Market Evolving Landscape
Mixer drum fabrication and hydraulic system architecture are undergoing concurrent transformation as emissions standards tighten and contractor operating models shift toward flexibility.
Composite drum liners and thermal barrier coatings are miniaturizing heat transfer losses during extended haul cycles. Regional contractors in Australia's remote mining corridors are adopting these specifications fastest. The technology is compressing acceptable haul distances from batch plants while maintaining slump specifications.
EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in cab climate systems, compelling redesigns of compressor architectures and seal materials. Mixer OEMs must recertify chassis integrations under new leakage thresholds. European commercial construction fleets face the steepest compliance cost increments.
Contractor procurement preferences are fragmenting between ownership and rental models based on project duration predictability. Long-term infrastructure tenders in India favor fleet ownership, while volatile commercial construction in Southeast Asia shifts toward rental channels. Equipment financiers are restructuring residual value assumptions accordingly.
Truck Mounted Concrete Mixer Market Segmentation
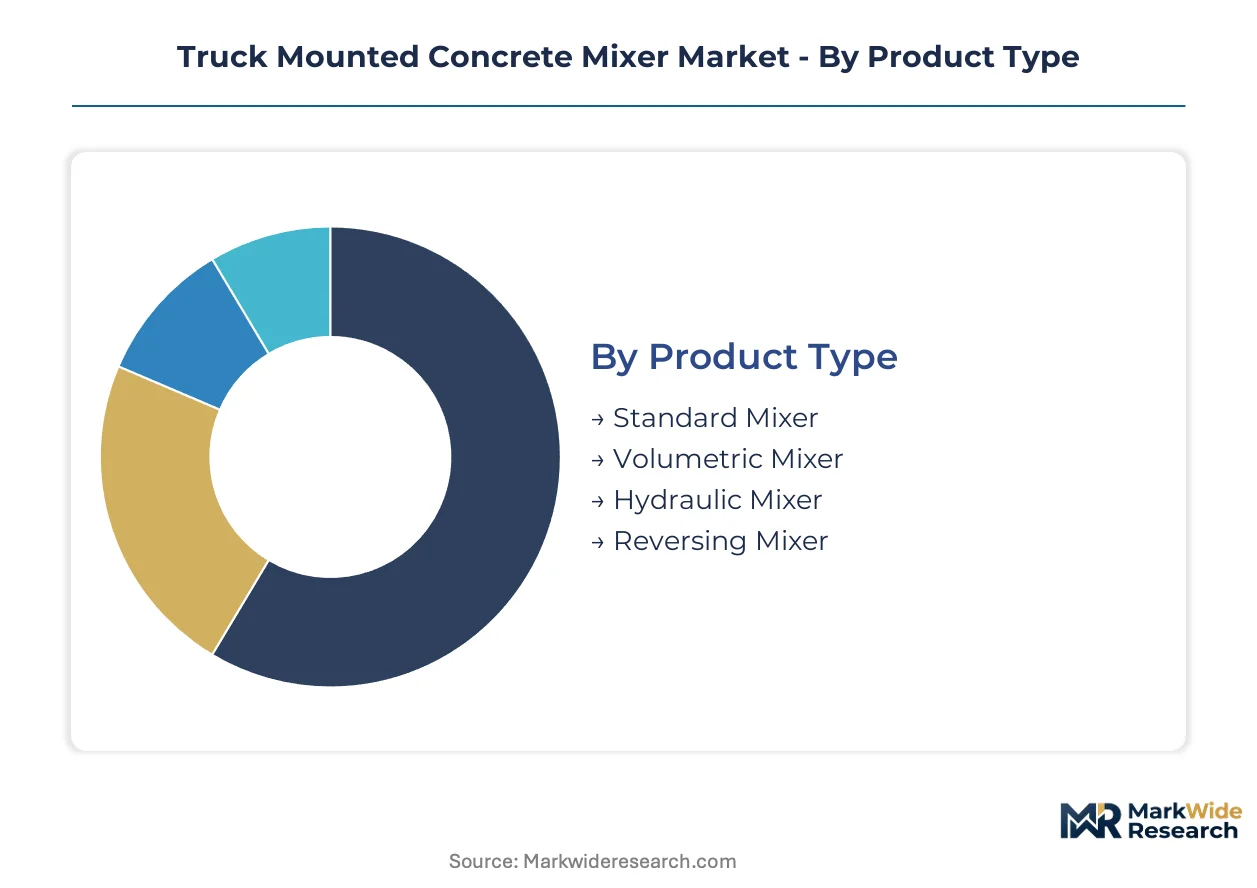
Segmentation in the truck mounted concrete mixer market reveals how procurement patterns diverge between established urban construction corridors and remote infrastructure deployment zones. Drum configuration and chassis capacity specifications directly shape fleet replacement economics for contractors navigating varying batch plant densities.
Product Type:
Margin pools concentrate in configurations that minimize transit-time penalties while maintaining slump integrity across extended haul cycles.
- Standard Mixer:Fixed-drum designs with rotating drum assemblies at 0-14 RPM during transit dominate procurement in mature markets with dense batch plant networks. Demand clusters in India's smart city concrete road programs where just-in-time delivery models minimize on-site inventory costs.
- Volumetric Mixer:On-site proportioning systems separate cement, aggregate, and water storage to enable batch production at pour locations. Remote infrastructure corridors across Southeast Asia and Brazil's interior states are accelerating adoption as contractors eliminate transit-time penalties exceeding 90 minutes.
- Hydraulic Mixer:High-pressure pump-driven drum rotation systems optimize torque delivery for heavy aggregate loads.
- Reversing Mixer:Dual-direction drum rotation enables rapid discharge and cleaning cycles for multi-site daily deployment.
Standard Mixer holds installed capacity. Volumetric Mixer is rotating up the share rankings.
Application:
Volume concentration tracks public infrastructure tender calendars rather than private construction cycles.
- Infrastructure Projects:Highway expansion, dam construction, and smart city programs require large-capacity drum configurations with extended haul specifications. China's provincial highway expansion and India's concrete road initiatives are concentrating fleet procurement in 6-8 cubic meter capacity classes.
- Commercial Construction:Office towers, retail complexes, and logistics facilities demand flexible rental models with rapid chassis redeployment capabilities. Southeast Asian contractors favor operational flexibility over asset ownership in volatile development cycles.
- Residential Construction:Single-family and multi-family housing developments utilize smaller drum capacities for neighborhood-scale pours.
- Heavy Industry:Mining operations, steel plants, and petrochemical facilities require reinforced drum specifications for abrasive aggregate handling.
Infrastructure Projects anchor procurement volume. Commercial Construction is expanding most quickly in rental channel penetration.
End User:
Customer type determines financing structure and residual value assumptions in equipment procurement.
- Contractors:Specialized concrete placement firms prioritize payload optimization and fuel efficiency in fleet specifications. Long-term infrastructure tenders in India favor ownership models with 6-8 year depreciation schedules.
- Construction Companies:General contractors with diversified project portfolios balance owned assets against rental flexibility. Equipment-as-a-service channels are penetrating fastest among mid-tier firms with unpredictable project pipelines.
- Government Agencies:Public works departments enforce BIS drum weld integrity standards and domestic content requirements in tender specifications.
- Private Developers:Real estate investment trusts and institutional developers outsource concrete logistics to specialized fleet operators.
Contractors retain the deepest installed base. Construction Companies are climbing the fastest in rental channel adoption.
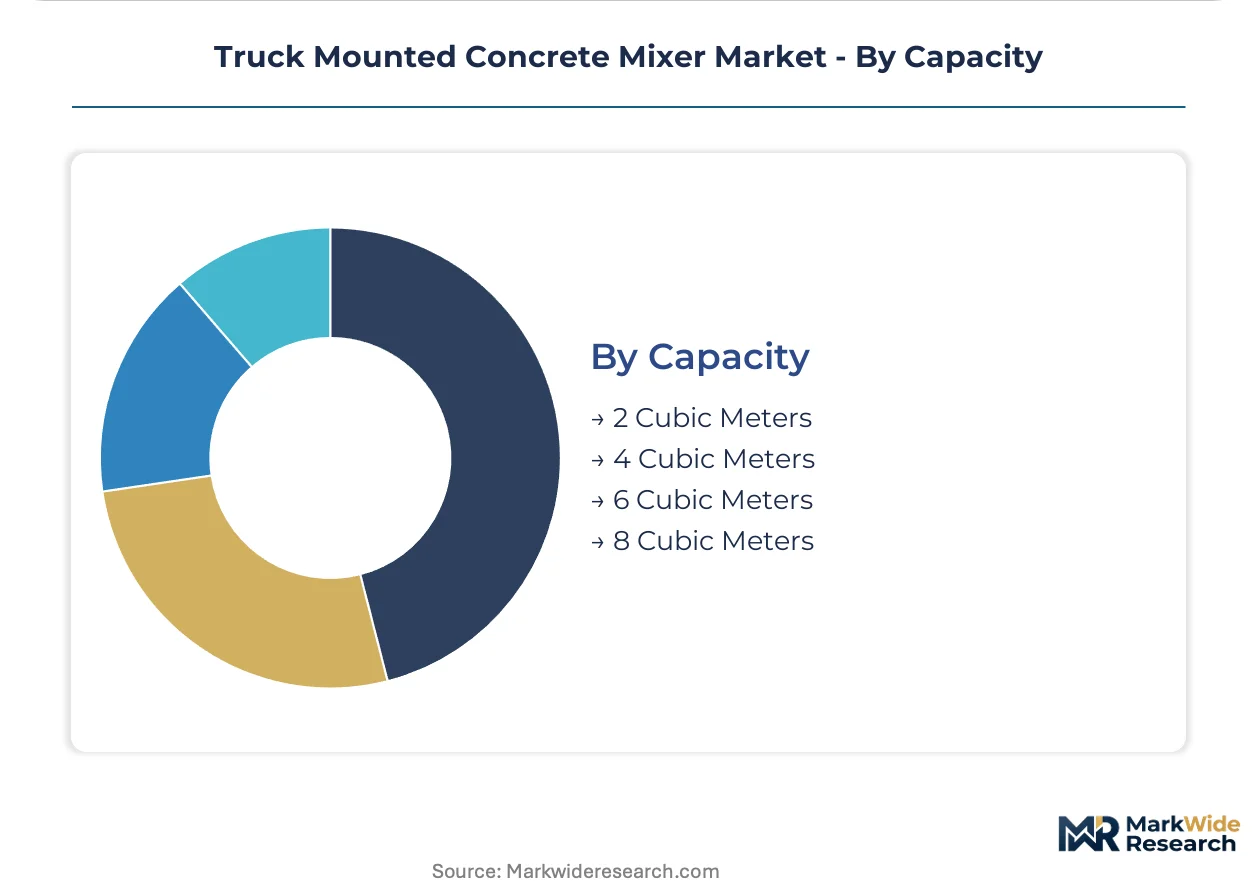
Capacity:
Payload optimization drives margin concentration in mid-range drum sizes that balance fuel costs against pour-site efficiency.
- 6 Cubic Meters:The dominant capacity class in fuel-cost-sensitive operating environments optimizes chassis weight distribution and engine loading. Procurement concentrates among European commercial construction fleets facing EU F-Gas Regulation compliance cost increments.
- 8 Cubic Meters:Maximum legal payload configurations serve megaproject concrete pours with continuous batch plant supply. Demand clusters in China's provincial highway expansion where single-trip volume minimizes fleet size requirements.
- 2 Cubic Meters:Compact drum specifications navigate restricted urban access for residential infill projects.
- 4 Cubic Meters:Mid-size configurations bridge small-scale commercial and large residential deployment needs.
6 Cubic Meters holds installed capacity. 8 Cubic Meters is gaining share fastest in megaproject corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mixer drum fabrication clusters in China and Germany, with hydraulic component supply chains radiating from these centers to serve infrastructure corridors worldwide. Regional emissions timelines and certification regimes are fragmenting platform development strategies across OEMs.
China
Provincial highway expansion and smart city concrete road programs are accelerating fleet procurement in 6-8 cubic meter capacity classes. MIIT enforces GB fuel consumption limits that directly shape domestic OEM mixer platform specifications. The Yangtze River Delta hosts the densest concentration of drum fabricators serving both domestic tenders and export markets.
India
Smart city concrete road initiatives and national highway development are concentrating demand among contractors pursuing long-term infrastructure tenders. BIS certification mandates drum weld integrity testing that filters subscale fabricators from government procurement eligibility. Maharashtra and Gujarat anchor manufacturing clusters supplying northern and western infrastructure corridors.
United States
Commercial construction volatility is shifting contractor preferences toward rental fleet models with rapid chassis redeployment capabilities. EPA Phase 2 greenhouse gas standards for heavy-duty vehicles are compelling hydraulic system and engine calibration redesigns. The Southeast and Texas Triangle concentrate equipment-as-a-service channel penetration.
Germany
Premium mixer drum fabrication sustains price positions in European commercial construction through in-house steel alloy development. EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in cab climate systems, forcing compressor architecture recertification. Bavaria and North Rhine-Westphalia host integrated OEM operations serving EU-wide tender specifications.
Brazil
Mining and dam construction sites in interior states are accelerating volumetric mixer adoption to eliminate transit-time penalties exceeding 90 minutes. ANVISA and national infrastructure agency specifications shape import and domestic content requirements. São Paulo and Minas Gerais anchor fleet operator headquarters serving Amazon basin and Cerrado development zones.
Truck Mounted Concrete Mixer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium drum engineering and volume manufacturing occupy separate competitive spaces. The vendor base separates into integrated chassis-drum OEMs, specialized hydraulic component suppliers, and regional fabrication specialists serving tender-specific certification requirements. Three archetypes dominate: captive hydraulic producers compressing delivery cycles, alloy-specialist drum fabricators commanding price premiums, and volumetric technology specialists expanding into remote corridor markets. Capacity expansion and backward integration into hydraulic component production represent the dominant competitive moves reshaping procurement leverage.
Within the integrated OEM tier, SANY Group and Zoomlion Heavy Industry exemplify scale-driven fabrication models anchored in Chinese infrastructure tender cycles. Liebherr Group occupies a position representing premium engineering archetypes sustained by in-house metallurgy capabilities. These three companies illustrate the geographic and technological segmentation defining competitive positioning across certification regimes.
| Leading Market Players |
|---|
| SANY Group |
| Zoomlion Heavy Industry |
| Liebherr Group |
| XCMG Group |
| Oshkosh Corporation |
| Putzmeister Holding GmbH |
| CIFA SpA |
| Volvo Group |
| Schwing Stetter India |
| Others |
Value Network & Pricing Analysis
Steel alloy substitution for conventional carbon grades in drum fabrication simultaneously shifts procurement geography toward integrated mills in China and Germany while compressing margin structures for independent fabricators lacking captive metallurgy capabilities. This input transition concentrates pricing power among OEMs with backward-integrated steel development, forcing tier-2 suppliers toward commodity positioning in aftermarket segments.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European commercial construction fleets, with compliance cost increments separating premium chassis-integrated platforms from standard configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with BIS drum weld integrity standards filtering subscale participants from government tender eligibility in India. Cost compression in economy tiers is intensifying because hydraulic component supply concentration limits independent supplier participation. Small-scale contractors in Southeast Asia exhibit highest price sensitivity, while megaproject operators in China prioritize payload optimization over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate procurement among contractors serving dense batch plant networks in India's smart city corridors, while strategic stockpiling of specialized steel grades anchors fabrication scheduling for premium drum manufacturers in Germany. Supply draws from China, Germany, and India for drum fabrication and hydraulic component production. Raw material dependencies center on high-strength steel alloys, high-pressure hydraulic pumps, and specialized refrigerant systems. Single-source vulnerability concentrates in captive hydraulic motor production among integrated OEMs. Distribution runs through equipment-as-a-service channels penetrating fastest in Southeast Asian commercial construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated contractor fleets in China's provincial highway expansion and India's national infrastructure tenders, fragmenting procurement leverage among smaller operators in volatile commercial construction segments.
For Market Incumbents: Consolidate backward integration into hydraulic component production to defend against Zoomlion's volumetric mixer encroachment and SANY's captive supply advantages. Prioritize certification investment in BIS drum weld standards and EU F-Gas recertification to filter subscale competitors from tender eligibility. Capacity addition in Maharashtra and Gujarat manufacturing clusters reinforces proximity to India's northern infrastructure corridors. For New Entrants and Emerging Players: Anchor in Brazil's interior mining and dam construction zones where volumetric mixer adoption eliminates transit-time penalties exceeding 90 minutes. Target ANVISA-compliant fleet operators serving Amazon basin development with equipment-as-a-service rental models. Partner with established hydraulic component distributors to bypass captive supply bottlenecks among integrated OEMs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed equipment rental platforms in the US Southeast and Texas Triangle where EPA Phase 2 compliance costs are accelerating fleet turnover. Long-term viability hinges on electrification convergence readiness across battery-electric chassis and regenerative hydraulic systems. Monitor divergence between regional emissions timelines and hydraulic electrification roadmaps as inflection indicator for stranded capacity risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Components | SANY's captive pump production compresses delivery cycles for domestic Chinese infrastructure tenders. |
| Volumetric Mixer Platform Expansion | Zoomlion's on-site proportioning variants capture remote corridor demand in Southeast Asia and Brazil. |
| Steel Alloy Development Investment | Liebherr's in-house metallurgy sustains price premiums in EU F-Gas regulated commercial construction. |
| Equipment-as-a-Service Channel Buildout | Rental fleet penetration addresses contractor preference for operational flexibility in volatile US Southeast markets. |
| Electrification Platform Development | Battery-electric chassis integration creates white space for zero-emission configurations ahead of EPA Phase 2 tightening. |
Research Methodology
Cross-validation between OEM procurement data and contractor fleet deployment records anchors the qualitative findings across the truck mounted concrete mixer value chain. Primary interviews with maintenance directors at concrete placement firms, plant engineers at batch plant operators, OEM procurement teams at chassis manufacturers, and aftermarket service heads at hydraulic component distributors combined with secondary validation from MIIT GB standard filings, EPA Phase 2 certification databases, BIS drum testing registries, and customs trade data. Bottom-up equipment deployment tracking and top-down infrastructure tender value analysis triangulate market sizing.
Sensitivity analysis across chassis capacity configurations, drum technology variants, and regional emissions compliance tiers informs the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application category, end-user archetype, and capacity class alongside regional regulatory cluster differentiation. CAGRs derive from infrastructure tender pipeline analysis and fleet replacement cycle modeling. Industry-specific forecast inputs incorporate GB fuel consumption limit enforcement timelines and BIS certification penetration rates.
Material uncertainties — steel alloy price volatility, hydraulic component supply disruptions, and divergence between electrification roadmaps and certification timelines — sit outside the modeled envelope. Forecasts reflect assumptions regarding infrastructure tender continuity and emissions compliance phase-in schedules. Revision becomes warranted when regulatory timeline acceleration or battery-electric chassis cost parity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Autonomous Heavy Equipment Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Tower Crane Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
Excavator Augers Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Casting Equipment Market
Construction Equipment
Asia Pacific Construction Equipment Market