
 Global Bop Handling Systems Market | 2026-2036
Global Bop Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bop Handling Systems Market Intelligence
Deepwater drilling contractors is bifurcating demand away from shallow-water rig operators as exploration shifts to harsher subsea environments. National Oilwell Varco leverages its integrated manufacturing footprint across North Sea and Gulf of Mexico service hubs. Baker Hughes sustains technology leadership through advanced automated positioning systems for subsea BOP stacks. Schlumberger Limited anchors its competitive position through drilling contractor partnerships in Brazil's pre-salt basins.
BOP handling systems are engineered lifting and transport mechanisms designed to maneuver blowout preventer stacks weighing up to 600 metric tons between rig floor and moonpool, utilizing hydraulic or electric drive systems with precision load sensing and safety interlock protocols. These systems serve the critical function of reducing manual rig-floor exposure during BOP deployment while maintaining well control integrity through controlled descent and horizontal alignment. Hydraulic BOP stacker configurations dominate capital expenditure among offshore rig fleets due to proven reliability under dynamic vessel motion, while electric Bop handler variants are capturing retrofit interest where diesel-hydraulic systems face emissions compliance pressure. Remote control systems technology commands premium positioning in newbuild specifications, though wireless operation adoption remains constrained by subsea signal reliability requirements in ultra-deepwater pressure regimes.
API 53 standards govern BOP handling system design verification and periodic recertification, compelling fleet operators in the United States to upgrade legacy manual lifter installations. Norway's Petroleum Safety Authority and Brazil's national petroleum regulator enforce supplementary dynamic positioning-linked handling protocols for floating drilling units. The EU Machinery Directive and ATEX certification frameworks shape equipment access for North Sea contractors operating under joint jurisdiction. Stakeholders must weigh automation capital intensity against regulatory compliance timelines and rig-day rate recovery trajectories when prioritizing fleet modernization sequences.
Market Dynamics
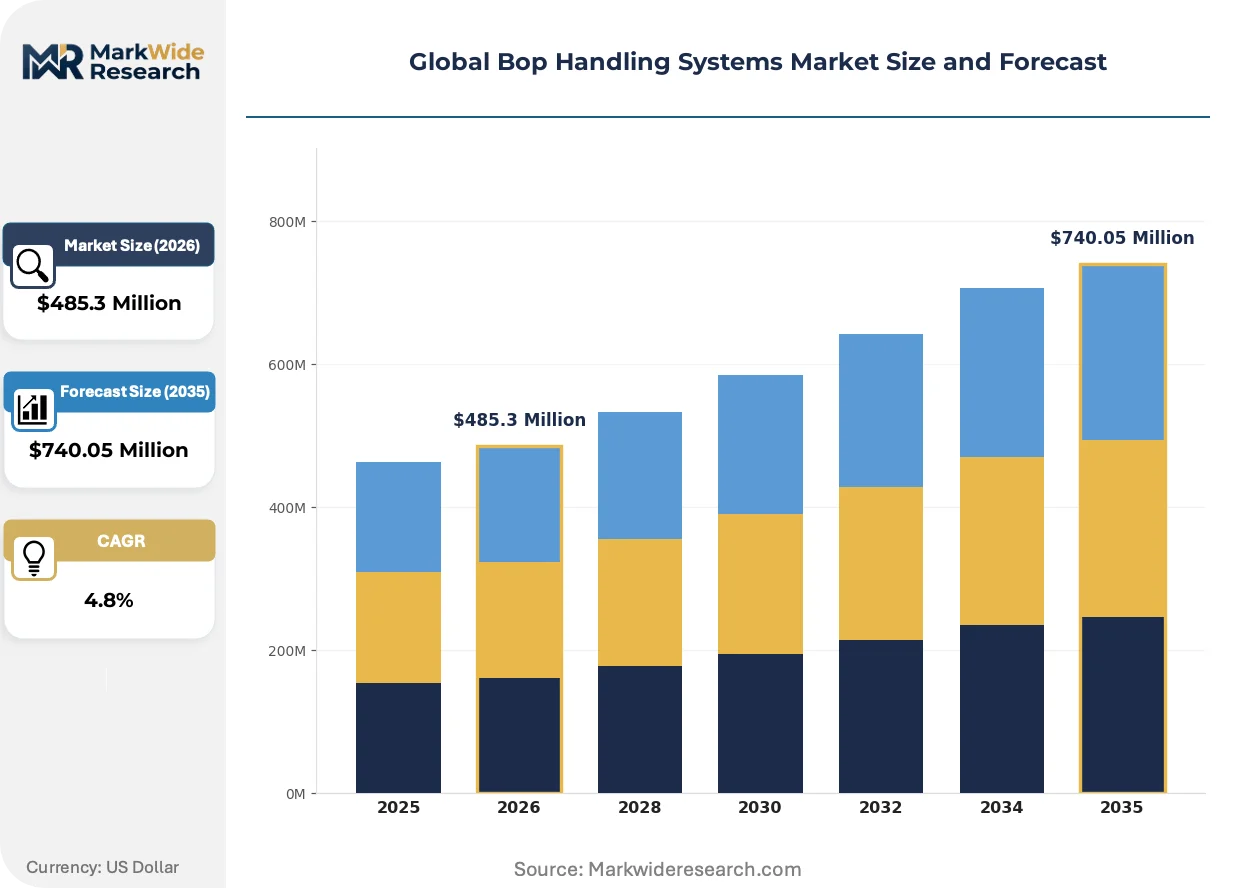
Deepwater drilling contractors in Brazil and the Gulf of Mexico are accelerating fleet automation to meet tightening API 53 recertification timelines, compressing replacement cycles for legacy hydraulic stackers while elevating electric handler specifications in newbuild contracts.
Growth Catalysts
- API 53 Recertification Mandates:United States fleet operators face compulsory upgrades of manual lifter installations, channeling capital toward automated handling systems with integrated load sensing.
- Pre-Salt Basin Expansion:Brazil's national petroleum regulator enforces dynamic positioning-linked handling protocols, requiring heavy-lift BOP capacity for ultra-deepwater floating units.
- Electric Drive Retrofits:Diesel-hydraulic systems face emissions compliance pressure in North Sea jurisdictions, redirecting retrofit demand toward electric handler variants with ATEX certification.
Market Restraints
- Specialized Steel Input Volatility:High-grade alloy plate for load-bearing frames experiences price swings tied to nickel and chromium supply disruptions.
- Subsea Signal Reliability Constraints:Wireless remote control adoption remains limited by pressure-induced signal degradation in ultra-deepwater regimes exceeding 3,000 meters.
- Certification Bottlenecks:Norway's Petroleum Safety Authority imposes extended validation periods for automated positioning algorithms, stretching delivery timelines.
Strategic Opportunities
- West African Ultra-Deepwater:Angola and Nigeria offshore blocks lack indigenous heavy-lift handling capacity, creating first-mover positioning for integrated service providers.
- Dual-Carbon Alignment:EU Green Deal incentives favor all-electric BOP handling architectures in North Sea contractor fleets, accelerating premium specification capture.
- Sensor-Analytics Convergence:Integration of predictive load monitoring with vessel motion compensation systems enables outcome-based maintenance contracting.
Industry Challenges
- Automation Engineering Talent Scarcity:Subsea hydraulic-electric integration specialists command premium compensation, constraining OEM expansion velocity.
- Legacy Rig Compatibility:Retrofit electric handlers require moonpool structural reinforcement on 1990s-era semisubmersibles, complicating cost justification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bop Handling Systems Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $740.05 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Bop Stacker, Electric Bop Handler, Pneumatic Bop Rotator, Semi-automatic Bop Handler, Manual Bop Lifter Technology: Remote Control Systems, Wireless Operation, Automated Positioning, Safety Interlock, Load Sensing Application: Well Intervention, Drilling Rigs, Offshore Platforms, Subsea Operations, Blowout Prevention End User: Exploration Firms, Drilling Contractors, Marine Service Providers, Oilfield Equipment Suppliers, Rig Operators |
| Companies Covered | National Oilwell Varco, Baker Hughes, Schlumberger Limited, Halliburton, Cameron, GE Oil & Gas, Weatherford International, Shandong Kerui Holding Group, Yantai Jereh Petroleum Equipment & Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bop Handling Systems Market Strategic Shifts & Innovations
Automation architectures are fragmenting competitive advantage between integrated OEMs and specialized subsystem vendors, while regulatory pressure on emissions and safety protocols accelerates specification divergence between premium and standard equipment tiers.
Electric BOP handler architectures with permanent magnet motor drives and regenerative braking are bifurcating capital deployment between newbuild specifications and legacy rig retrofit programs. Norwegian and UK North Sea contractors specify these systems for floating production contracts, while Gulf of Mexico drillers delay adoption pending diesel-hydraulic asset depreciation. The technology is bifurcating supplier margins, rewarding integrated electric drive manufacturers while compressing returns for pure-play hydraulic component vendors.
IMO safety protocols governing subsea stack handling equipment are tightening certification requirements for dynamic positioning-linked control systems. Floating drilling units in Brazil must now demonstrate redundant hydraulic-electric power paths before receiving operating permits. Ultra-deepwater contractors in the Gulf of Mexico are responding by pre-qualifying dual-certified handling system architectures in long-term charter agreements.
Drilling contractors are consolidating procurement authority at the fleet level, displacing rig-level equipment purchasing decisions. Integrated service agreements now bundle BOP handling systems with blowout preventer maintenance contracts, compressing standalone equipment vendor access. This concentration is most visible among Brazil's pre-salt operators and US-based deepwater specialists with multi-rig deployment schedules.
Global Bop Handling Systems Market Segmentation
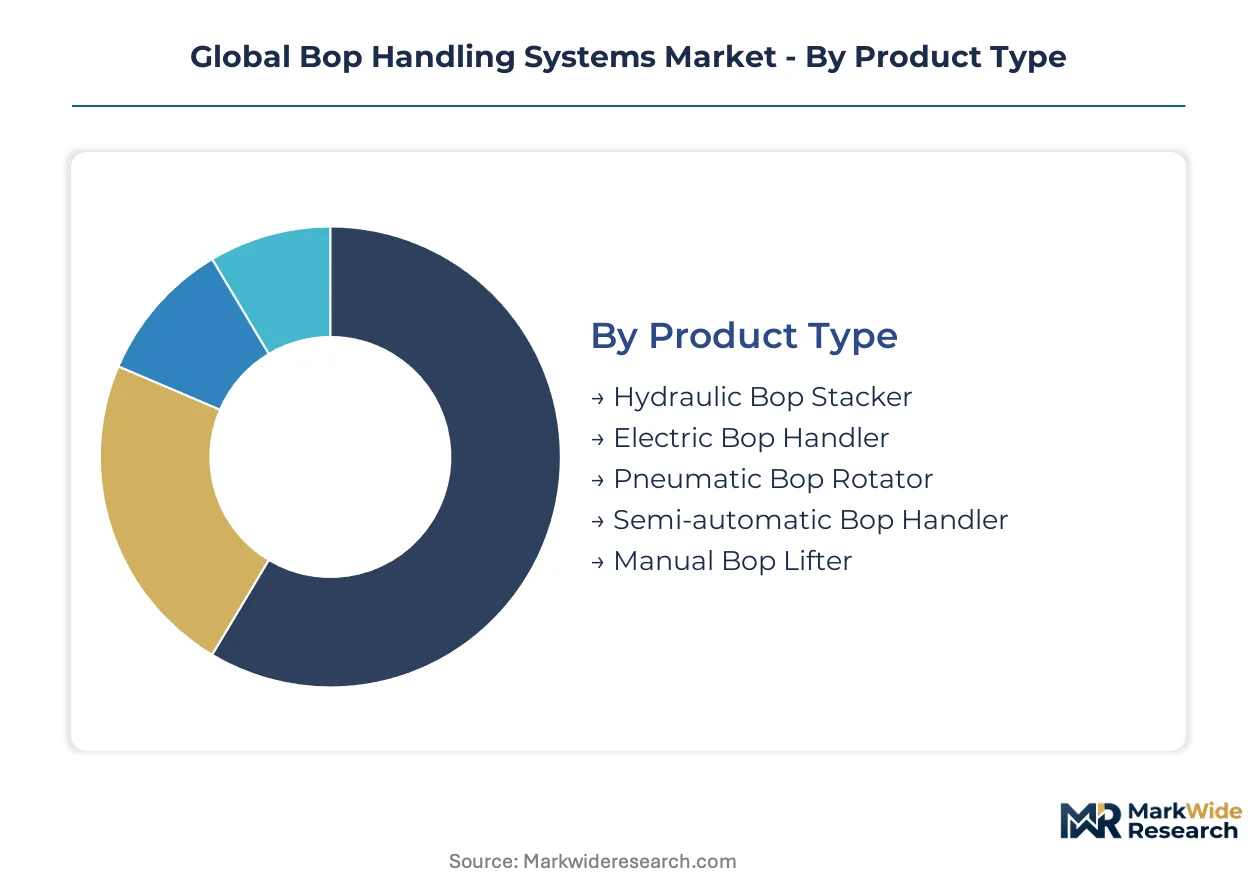
BOP handling system segmentation reveals how equipment specifications diverge between legacy fleet retrofits and next-generation offshore assets. Technology tiers and application intensity determine capital allocation patterns across drilling contractor procurement cycles.
Product Type:
Hydraulic Bop Stacker configurations face substitution pressure from electric architectures as North Sea emissions regulations tighten and Brazil's pre-salt operators prioritize fuel efficiency in floating unit specifications.
- Hydraulic Bop Stacker:Diesel-hydraulic drive systems with proven reliability under dynamic vessel motion dominate existing offshore rig fleets. Demand concentrates among Gulf of Mexico drilling contractors facing API 53 recertification timelines where asset depreciation schedules delay electric transition.
- Electric Bop Handler:Permanent magnet motor drives with regenerative braking capture newbuild specifications from Norwegian and UK North Sea contractors. EU Green Deal incentives accelerate premium specification capture where floating production contracts require ATEX-certified electric architectures.
- Pneumatic Bop Rotator:Compressed-air actuation systems serve specialized well intervention vessels with limited hydraulic infrastructure.
- Semi-automatic Bop Handler:Hybrid control interfaces bridge manual and fully automated operations for mid-tier rig operators in West African markets.
- Manual Bop Lifter:Legacy mechanical systems face accelerated replacement cycles as Brazil's national petroleum regulator enforces dynamic positioning-linked handling protocols.
Hydraulic Bop Stacker anchors the volume base while Electric Bop Handler gains share at the steepest rate.
Technology:
Technology segmentation tracks the cost-to-reliability tradeoff as ultra-deepwater pressure regimes constrain wireless adoption despite remote operation demand from drilling contractors seeking reduced rig-floor exposure.
- Remote Control Systems:Hardwired control architectures with redundant signal paths command premium positioning in newbuild specifications. Demand concentrates among pre-salt basin operators in Brazil where redundant hydraulic-electric power paths are mandatory for operating permits.
- Automated Positioning:Closed-loop feedback systems with vessel motion compensation enable precision BOP stack alignment under sea states exceeding significant wave heights of four meters. Norway's Petroleum Safety Authority imposes extended validation periods for these algorithms, stretching delivery timelines for floating drilling units.
- Wireless Operation:Radio-frequency and acoustic signal transmission face pressure-induced degradation constraints in ultra-deepwater regimes exceeding 3,000 meters.
- Safety Interlock:Mechanical and software-based lockout protocols prevent uncommanded load release during critical handling phases.
- Load Sensing:Strain gauge and hydraulic pressure monitoring systems feed predictive maintenance analytics for outcome-based service contracting.
Remote Control Systems anchors the volume base while Automated Positioning climbs the fastest as contractors prioritize precision handling under harsh environment conditions.
Application:
Application segmentation reflects the operational intensity gradient from routine well intervention to high-stakes blowout prevention where equipment failure carries catastrophic financial and environmental exposure.
- Drilling Rigs:Jack-up, semisubmersible, and drillship installations require heavy-lift capacity for BOP stacks weighing up to 600 metric tons. Demand concentrates in the United States and Brazil where ultra-deepwater floating units command day rates justifying premium handling system specifications.
- Subsea Operations:Subsea stack deployment and retrieval from seabed installations demand pressure-compensated handling architectures. Gulf of Mexico contractors pre-qualify dual-certified systems in long-term charter agreements as IMO safety protocols tighten.
- Well Intervention:Light-duty handling systems serve workover and completion activities on mature field assets.
- Offshore Platforms:Fixed platform installations utilize simplified handling configurations with reduced motion compensation requirements.
- Blowout Prevention:Emergency response handling systems maintain well control integrity through controlled descent protocols during kick events.
Drilling Rigs anchors the volume base while Subsea Operations expands most quickly as exploration migrates to harsher deepwater environments.
End User:
End user segmentation captures the procurement authority consolidation trend as fleet-level purchasing displaces rig-level equipment decisions among multi-rig operators.
- Drilling Contractors:Transocean, Seadrill, and Valaris-class fleet operators bundle BOP handling systems with blowout preventer maintenance contracts. Demand concentrates among Brazil's pre-salt operators and US-based deepwater specialists with multi-rig deployment schedules compressing standalone vendor access.
- Exploration Firms:IOCs and NOCs with captive drilling divisions specify integrated service agreements linking handling performance to well delivery metrics.
- Marine Service Providers:Third-party vessel operators supply handling capacity to marginal field developers lacking owned rig assets.
- Oilfield Equipment Suppliers:Rental and leasing companies maintain handler fleets for spot market deployment.
- Rig Operators:Independent rig owners with single-asset exposure face procurement disadvantage against consolidated fleet purchasers.
Drilling Contractors anchors the volume base while Exploration Firms gains share at the steepest rate as NOCs expand captive drilling capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Corpus Christi anchors United States offshore equipment throughput, handling heavy-lift BOP components destined for Gulf of Mexico drilling contractors facing compressed API 53 recertification timelines.
United States
Gulf of Mexico drillship operators command premium day rates justifying automated handling system investments. OSHA and API 53 standards enforce load-sensing retrofits on legacy hydraulic stackers. Houston-Galveston corridor fabrication yards specialize in dual-certified electric-hydraulic architectures for ultra-deepwater units.
Brazil
Pre-salt basin floating production contracts drive demand for 600-metric-ton lift capacity. ANVISA and Brazil's national petroleum regulator mandate redundant power paths for dynamic positioning-linked handling systems. Rio de Janeiro-Niterói offshore cluster hosts integrated service agreements bundling BOP handling with blowout preventer maintenance.
Norway
North Sea floating drilling units prioritize ATEX-certified electric handler specifications under EU Green Deal incentives. The Petroleum Safety Authority imposes extended validation periods for automated positioning algorithms. Stavanger-Bergen corridor concentrates subsea hydraulic-electric integration engineering talent.
United Kingdom
UK North Sea contractors specify permanent magnet motor drives with regenerative braking for floating production contracts. The Health and Safety Executive enforces machinery safety standards aligned with EU Machinery Directive. Aberdeen subsea technology cluster anchors predictive load monitoring system development.
China
State-owned drilling contractors expand heavy-lift handling capacity for South China Sea deepwater blocks. MIIT and GB standards shape domestic equipment certification frameworks. Shanghai-Shenzhen coastal manufacturing bases produce high-grade alloy plate for load-bearing frames.
Global Bop Handling Systems Market Key Industry Players
Concentration sits with integrated oilfield service conglomerates that bundle BOP handling systems with broader drilling equipment portfolios. Three strategic archetypes define competitive positioning: full-service OEMs with captive manufacturing footprints, specialized subsystem vendors focused on electric drive architectures, and regional fabricators serving spot-market retrofit demand. M&A activity targets predictive analytics capabilities, while strategic partnerships lock in long-term charter agreements with pre-salt basin operators.
Among Houston-based integrated service providers, National Oilwell Varco and Baker Hughes occupy positions spanning hydraulic stacker legacy fleets and electric handler newbuild specifications. Schlumberger Limited sits within the drilling contractor partnership archetype, anchoring competitive presence through captive relationships with Brazil's pre-salt basin operators. These three companies exemplify the tiering between full-service OEMs and specialized subsystem vendors.
| Leading Market Players |
|---|
| National Oilwell Varco |
| Baker Hughes |
| Schlumberger Limited |
| Halliburton |
| Cameron |
| GE Oil & Gas |
| Weatherford International |
| Shandong Kerui Holding Group |
| Yantai Jereh Petroleum Equipment & Technologies |
| Others |
Cost & Logistics Intelligence
API 53 recertification mandates simultaneously gate supplier qualification and stratify price tiers, compelling fleet operators to pay premiums for automated load-sensing architectures while legacy hydraulic vendors absorb margin compression on manual lifter replacements.
Pricing Analysis
Volume-discount tiering separates fleet-level procurement contracts from single-rig spot purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in economy-tier hydraulic stackers is intensifying because Gulf of Mexico drilling contractors delay electric transition until asset depreciation schedules complete. Exploration firms with captive drilling divisions exhibit lowest price sensitivity, while independent rig operators with single-asset exposure face procurement disadvantage.
Supply Chain Analysis
Extended lead times for high-grade alloy plate strain inventory management across Norwegian and Chinese fabrication hubs. Supply concentrates in the United States, Norway, and China, drawing from nickel and chromium feedstocks subject to commodity price volatility. Single-source vulnerability for permanent magnet motor drives creates bottlenecks in electric handler production. Distribution runs through Houston-Galveston corridor fabrication yards and Rio de Janeiro-Niterói offshore clusters serving regional drilling contractor fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in BOP handling systems reflects accelerating fleet automation as pre-salt and ultra-deepwater projects multiply contractor demand for heavy-lift capacity with integrated safety protocols.
For Market Incumbents: Consolidate procurement authority through integrated service agreements bundling BOP handling with blowout preventer maintenance, compressing standalone vendor access. Deepen backward integration into predictive load monitoring analytics to defend against specialized subsystem vendors. Prioritize certification investment in dual-certified electric-hydraulic architectures as IMO safety protocols tighten.
For New Entrants and Emerging Players: Anchor in West African ultra-deepwater markets where Angola and Nigeria offshore blocks lack indigenous heavy-lift handling capacity. Target semi-automatic Bop Handler specifications for mid-tier rig operators seeking hybrid control interfaces. Pursue go-to-market partnerships with marine service providers supplying handling capacity to marginal field developers.
For Investors and Strategic Acquirers: EU Green Deal implementation reshapes the acquisition landscape toward ATEX-certified electric handler manufacturers with regenerative braking capabilities. Long-term viability centers on OEMs capturing premium specification share in North Sea floating production contracts. Monitor Norway's Petroleum Safety Authority validation timelines as inflection indicator for automated positioning algorithm adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Grade Alloy Supply | Captive sourcing of nickel-chromium plate insulates margins from commodity volatility in load-bearing frame production. |
| Predictive Analytics Platform Development | Sensor-data convergence with vessel motion compensation enables outcome-based maintenance contracting with Transocean-class fleets. |
| Dual-Certification Capacity Buildout | Electric-hydraulic architectures pre-qualified for Brazil's ANVISA and US API 53 standards capture charter agreement premiums. |
| West African Service Hub Establishment | First-mover positioning in Angola and Nigeria blocks lacking indigenous heavy-lift capacity secures long-term installation contracts. |
| Regulatory Compliance Partnership | Collaboration with Norway's Petroleum Safety Authority accelerates automated positioning algorithm validation for floating drilling units. |
Research Approach
A spread of perspectives from drilling contractor fleet managers, subsea hydraulic-electric integration engineers, OEM procurement directors, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation from API certification records, IMO safety protocol amendments, customs trade data for high-grade alloy plate, and SEC filings from integrated oilfield service providers. Bottom-up rig fleet analysis and top-down offshore capital expenditure triangulation anchored volume estimates.
Segmentation dimensions modeled span product type, technology tier, application intensity, and end-user procurement authority across the projection horizon. CAGRs derived from rig-day rate trajectories, replacement cycle compression, and regulatory compliance timeline analysis. Forecast inputs incorporated dynamic positioning-linked handling protocol adoption curves and electric drive retrofit penetration rates by regional jurisdiction.
Material uncertainties — nickel-chromium supply disruptions, subsea signal reliability breakthroughs, and extended regulatory validation periods — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding fleet automation adoption and pre-salt basin expansion schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Explosion Proof Crane Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Canada Forklift Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Electric Hoist Market