
 Plaster Accelerator Market | 2026-2036
Plaster Accelerator Market Size, Share, and Industry Trends Forecast 2026-2036
Plaster Accelerator Market Analytics
Multi-source procurement among specialty chemical distributors is expanding as plaster accelerator buyers diversify supply risk across Asia-Pacific and European producers. USG Corporation leverages its captive gypsum board networks to secure downstream placement of companion accelerators. CEMEX Group sustains integrated cement-to-finish supply chains that bundle accelerator formulations with ready-mix plaster contracts. Qingdao Yuyin Chemicals anchors export volumes through cost-optimized mineral-based accelerator production serving Southeast Asian contractors.
Plaster accelerators are chemical or mineral admixtures that reduce the setting time of gypsum plaster, typically containing soluble sulfate salts or aluminates that catalyze hemihydrate rehydration at dosage rates between 0.5% and 3% by weight. Their primary industrial purpose is to compress construction schedules by enabling faster wall-finishing cycles in temperature-controlled environments. Chemical accelerators dominate volume in commercial construction where rapid turnaround penalties run steep, while mineral-based formulations capture margin pools in green-certified residential projects that restrict synthetic additive content. Powder form leads infrastructure applications for field-mix flexibility, though liquid concentrates are gaining share among contractor segments seeking batch consistency and reduced dust exposure.
REACH registration requirements in Europe govern sulfate salt classifications and occupational exposure thresholds, compelling reformulation investments among suppliers serving EU member states. The EPA's Toxic Substances Control Act scrutinizes novel organic accelerator chemistries entering US commerce, extending product registration timelines. China's GB standards for construction admixtures set mandatory setting-time performance bands that filter substandard imports. Stakeholders must monitor evolving low-carbon building codes that tie accelerator specification to embodied carbon scoring of finished plaster systems.
Market Dynamics
Fast-track construction programs compress finishing schedules, forcing chemical accelerator uptake as developers absorb liquidated damages clauses into project economics.
Growth Catalysts
- EU Green Deal low-carbon mandates:Embodied carbon scoring for plaster systems drives specification of mineral-based accelerators in German and French residential retrofits.
- Prefabricated housing cycles:German offsite manufacturers integrate accelerators into controlled-environment panel production to match assembly-line throughput.
- Aluminate chemistry advances:Soluble aluminate formulations cut setting times below 15 minutes, enabling same-day multi-coat application in commercial fit-outs.
Market Restraints
- Raw sulfate salt volatility:Fluctuating potassium sulfate and sodium aluminate feedstock costs squeeze margin pools for independent blenders.
- REACH registration concentration:ECHA compliance costs favor large-scale EU-registered suppliers, marginalizing small-batch importers from Turkey and North Africa.
- Limestone plaster substitution:Hydraulic lime-based finishes bypass gypsum chemistry entirely in heritage restoration and moisture-critical builds.
Strategic Opportunities
- Polish renovation wave:EU cohesion fund disbursements for building efficiency retrofits open specification channels in Warsaw and Kraków contractor networks.
- Liquid concentrate channel shift:Ready-to-dose formats displace field-mix powders among Dutch and Belgian professional applicator cooperatives seeking dust reduction.
- CSRD supply chain disclosure:Mandatory Scope 3 reporting pushes asset owners toward accelerator suppliers with verified low-carbon production footprints.
Industry Challenges
- Formulation chemist scarcity:Hemihydrate kinetics expertise concentrates among aging technical staff at legacy gypsum board manufacturers.
- Batch-to-batch consistency:Mineral accelerator natural variability demands real-time quality control investment that smaller compounders struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plaster Accelerator Market |
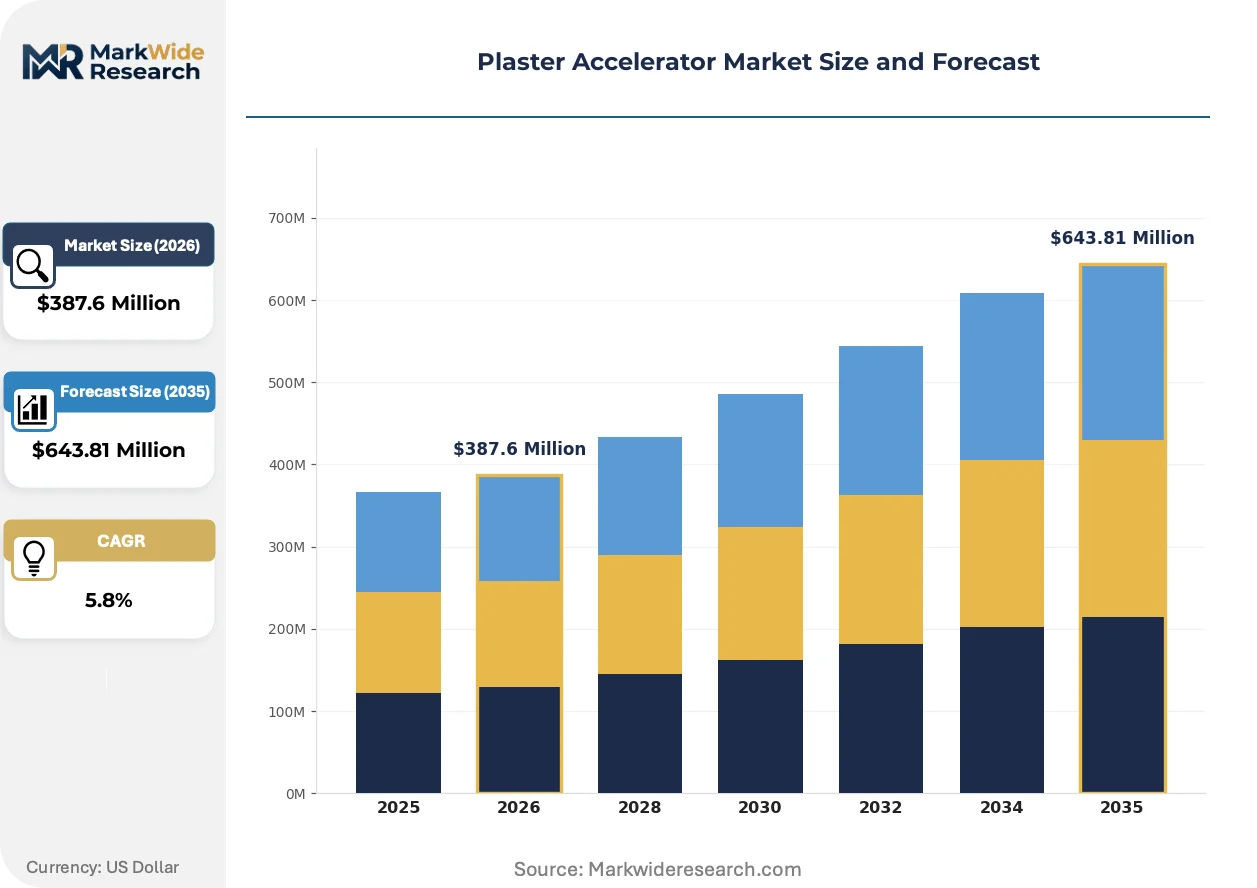
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Accelerators, Mineral-Based Accelerators, Organic Accelerators, Synthetic Accelerators Application: Commercial Construction, Residential Construction, Infrastructure Projects, DIY Projects Form: Powder, Liquid, Granular, Pellets End User: Contractors, Builders, DIY Enthusiasts, Distributors |
| Companies Covered | Calder Industrial Materials, CEMEX Group, Qingdao Yuyin Chemicals, Eazymix, Shanghai Landytop Gypsum Machinery, Kalyan Industries, USG Corporation, Gyprock, Vijaya Building Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plaster Accelerator Market Evolving Landscape
Digital dosing systems and low-alkali chemistry platforms are compressing the gap between raw material input and finished surface readiness.
Closed-loop dosing hardware is automating accelerator injection at ready-mix plaster plants, eliminating hand-scoop variance that plagued site-blended applications. German and Austrian contractor fleets are retrofitting silo systems with gravimetric feeders at pace. This automation is compressing quality control headcount while tightening setting-time tolerance bands to under 30 seconds.
REACH Annex XVII restrictions on soluble sulfate occupational exposure thresholds are forcing reformulation toward encapsulated aluminate carriers. Industrial consequence includes extended R&D timelines and third-party toxicology testing costs. Commercial construction segments in France and the Netherlands are responding by consolidating supplier lists to pre-registered ECHA dossier holders.
Specification authority is migrating from general contractors to specialist applicator cooperatives that bundle material procurement with labor scheduling. Dutch stucco trade associations now negotiate annual accelerator supply agreements that lock volume and price, displacing project-by-project purchasing. This concentration is most visible in Randstad urban corridor renovation contracts where cooperative membership exceeds 60 percent of certified installers.
Plaster Accelerator Market Segmentation
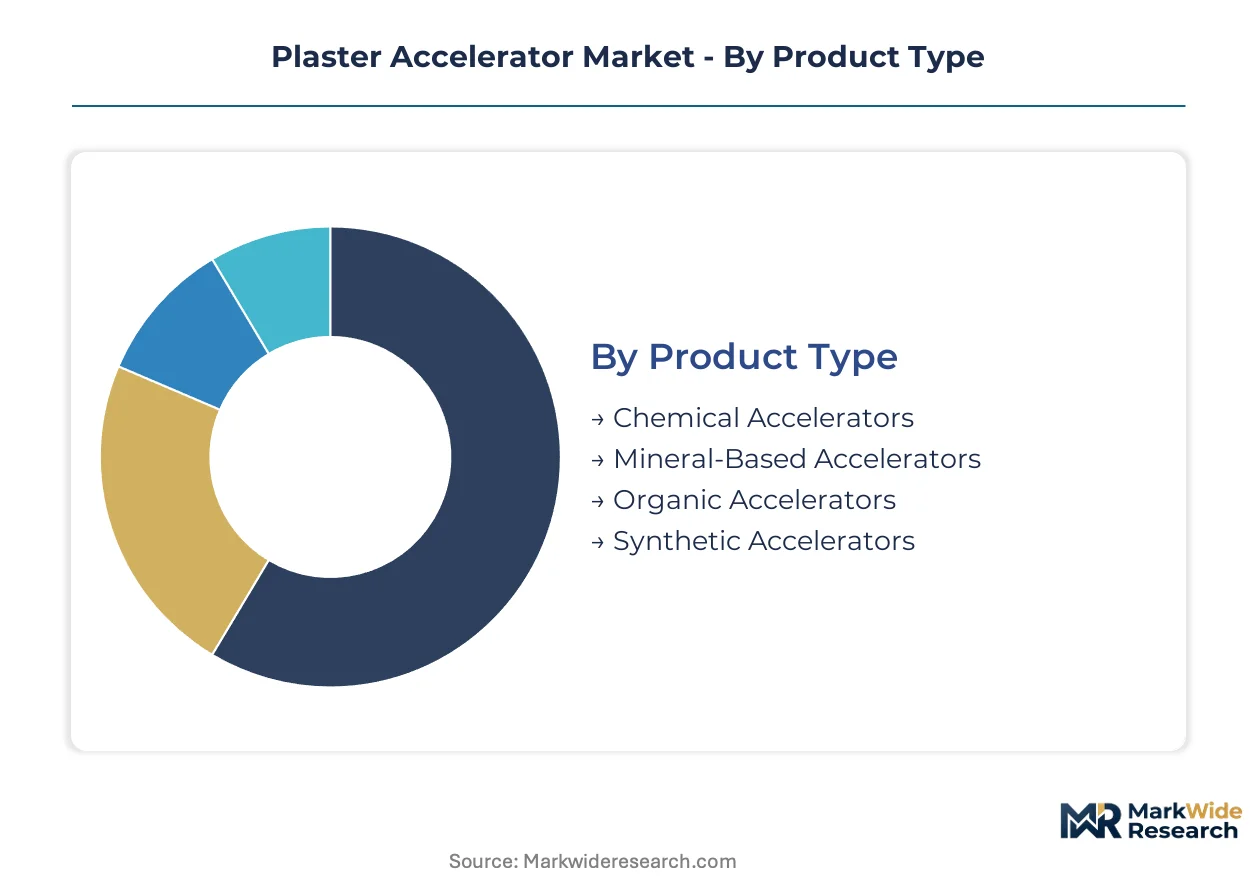
Plaster accelerator procurement patterns diverge sharply between volume-driven commercial contractors and specification-sensitive residential developers. Understanding these segment boundaries clarifies where formulation investments generate returns and where commodity positioning suffices.
Product Type:
Buyers select accelerator chemistry based on project certification requirements and setting-time compression needs.
- Chemical Accelerators:Soluble sulfate and aluminate formulations dominate commercial construction where liquidated damages penalties exceed material costs. German prefabricated housing manufacturers specify these for panel production lines requiring sub-20-minute setting cycles. REACH Annex XVII compliance costs favor established EU-registered suppliers with pre-filed toxicology dossiers.
- Mineral-Based Accelerators:Naturally occurring sulfate salts serve green-certified residential projects in France and the Netherlands where embodied carbon scoring restricts synthetic additive content. EU Green Deal low-carbon mandates accelerate specification shifts in German and Polish renovation waves. Batch-to-batch variability demands real-time quality control investment that filters smaller compounders.
- Organic Accelerators:Bio-derived catalytic compounds address niche heritage restoration projects seeking reversible chemistry compatible with historic substrates.
- Synthetic Accelerators:Laboratory-engineered formulations target ultra-fast commercial fit-outs requiring sub-15-minute setting times for same-day multi-coat application.
Volume sits with chemical accelerators; growth tilts toward mineral-based formulations.
Application:
End-use setting-time requirements determine dosage precision and form factor selection.
- Commercial Construction:Office fit-outs and retail rollouts in Randstad urban corridors drive liquid concentrate uptake among Dutch applicator cooperatives. Fast-track programs compress finishing schedules, forcing accelerator specification into standard subcontractor scopes. Liquidated damages clauses embed accelerator costs into project economics.
- Residential Construction:German offsite manufacturers integrate powder accelerators into controlled-environment panel production. Prefabricated housing cycles match assembly-line throughput with consistent setting-time performance. REACH-compliant low-alkali formulations capture specification in French energy retrofit programs.
- Infrastructure Projects:Tunnel lining and utility vault applications favor powder form for field-mix flexibility in remote locations with intermittent supply chains.
- DIY Projects:Small-format retail packs serve renovation hobbyists in Polish and Czech home improvement channels.
Commercial construction commands volume concentration; residential construction expands most quickly.
Form:
Handling economics and dust exposure regulations reshape form factor preference curves.
- Powder:Dominates infrastructure and traditional site-mix applications where silo storage and gravimetric feeding remain uneconomical. German and Austrian contractor fleets retrofit silo systems with automated dosing hardware, compressing quality control headcount.
- Liquid:Concentrates gain share among Dutch and Belgian professional applicator cooperatives seeking batch consistency and reduced occupational dust exposure. Ready-to-dose formats displace field-scoop measurement variance.
- Granular:Intermediate flow properties suit intermediate-scale batch plants without liquid storage infrastructure.
- Pellets:Low-dust handling characteristics address specialty restoration applications requiring precise micro-dosing.
Powder retains volume leadership; liquid concentrates gain share fastest.
End User:
Procurement authority migration from general contractors to specialist networks restructures channel economics.
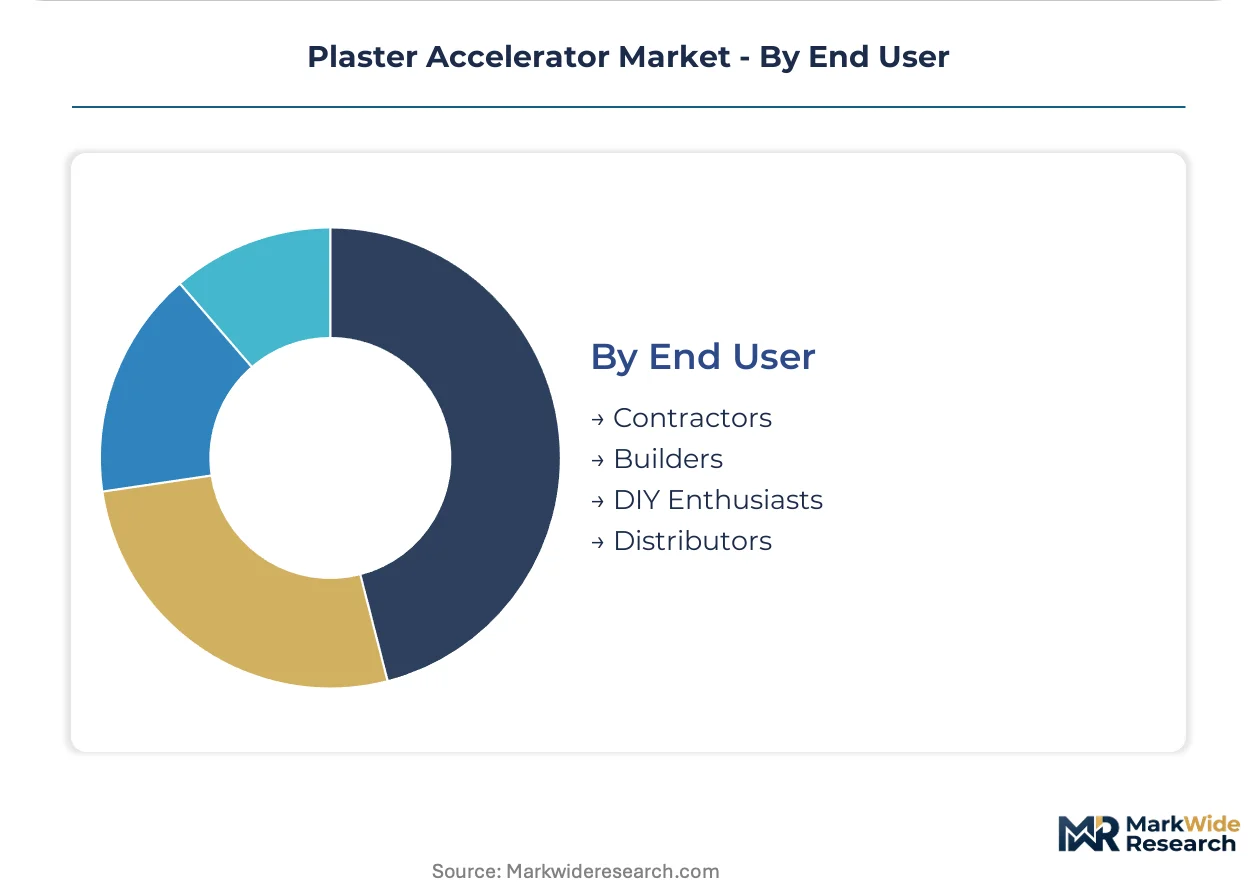
- Contractors:Specialist plastering cooperatives in the Netherlands negotiate annual supply agreements locking volume and price, displacing project-by-project purchasing. Randstad corridor contracts concentrate specification authority among membership-based procurement pools.
- Builders:German prefabricated housing manufacturers integrate accelerator supply into captive gypsum board networks, securing downstream placement of companion formulations.
- DIY Enthusiasts:Retail channel fragmentation across Polish and Czech markets limits brand loyalty development.
- Distributors:Multi-source procurement patterns expand as buyers diversify supply risk across Asia-Pacific and European producers.
Contractors anchor current volume; builder direct procurement shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany where prefabricated housing manufacturers and renovation contractors sustain consistent offtake. French and Dutch markets accelerate specification shifts toward low-carbon formulations under tightening EU Green Deal mandates.
Germany
Prefabricated housing manufacturers in Bavaria and North Rhine-Westphalia integrate accelerators into controlled-environment panel production lines. REACH Annex XVII compliance costs favor ECHA-registered suppliers with pre-filed toxicology dossiers. The Rhine-Ruhr industrial corridor hosts integrated gypsum-to-finish supply chains bundling accelerator formulations with ready-mix plaster contracts.
France
Energy retrofit programs in Île-de-France drive mineral-based accelerator specification for embodied carbon scoring compliance. EU Green Deal low-carbon mandates tighten formulation requirements across Paris and Lyon contractor networks. The Auvergne-Rhône-Alpes cluster concentrates heritage restoration projects seeking reversible chemistry compatible with historic substrates.
Netherlands
Randstad urban corridor renovation contracts concentrate specification authority among specialist applicator cooperatives negotiating annual supply agreements. Dutch stucco trade associations lock volume and price terms, displacing project-by-project purchasing. Liquid concentrate formats gain share among professional cooperatives seeking batch consistency and reduced occupational dust exposure.
Poland
EU cohesion fund disbursements for building efficiency retrofits open specification channels in Warsaw and Kraków contractor networks. GB standards for construction admixtures filter substandard imports entering through Baltic distribution routes. The Silesian metropolitan area anchors renovation material demand from aging housing stock requiring accelerated finishing cycles.
United States
Fast-track commercial construction programs compress finishing schedules in Texas and California metro corridors. The EPA's Toxic Substances Control Act extends registration timelines for novel organic accelerator chemistries entering US commerce. Southeast contractor fleets retrofit silo systems with gravimetric feeders automating accelerator injection at ready-mix plaster plants.
Plaster Accelerator Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers secure downstream placement through integrated supply chains. The vendor base organizes around three tiers: multinational building materials conglomerates with captive gypsum networks, regional specialty chemical blenders serving contractor cooperatives, and cost-optimized mineral compounders exporting to Southeast Asian markets. Two competitive moves define positioning: backward integration into sulfate salt feedstock sourcing and technology licensing agreements for encapsulated aluminate carriers.
Within the multinational tier, CEMEX Group and USG Corporation exemplify integrated cement-to-finish supply chain operators. Qingdao Yuyin Chemicals occupies a position among Asia-Pacific export-focused compounders serving contractor markets through cost-optimized mineral-based production. These three anchors represent distinct strategic archetypes: captive downstream placement, bundled ready-mix contracting, and export volume leadership through feedstock cost discipline.
| Leading Market Players |
|---|
| Calder Industrial Materials |
| CEMEX Group |
| Qingdao Yuyin Chemicals |
| Eazymix |
| Shanghai Landytop Gypsum Machinery |
| Kalyan Industries |
| USG Corporation |
| Gyprock |
| Vijaya Building Materials |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap compounders in Germany and Poland anchor regional supply networks, translating feedstock cost discipline into stable contract pricing for prefabricated housing manufacturers while independent blenders absorb margin compression from raw sulfate salt volatility.
Pricing Analysis
Volume concentrates in chemical accelerators serving commercial fit-outs where liquidated damages clauses embed material costs into project economics, while mineral-based formulations capture margin pools in green-certified residential segments. Pricing stratifies across REACH-registered premium tiers, standard EU-compliant grades, and economy mineral salts. Cost compression in the standard tier is intensifying because potassium sulfate and sodium aluminate feedstock costs fluctuate unpredictably. DIY renovation hobbyists in Polish retail channels exhibit the highest price sensitivity; German prefabricated housing manufacturers show the lowest due to captive supply agreements.
Supply Chain Analysis
EU Green Deal domestic-content mandates for embodied carbon scoring are reshaping sourcing patterns toward locally produced mineral accelerators in Germany, France, and Poland. Supply draws from sulfate salt deposits in Spain, processed aluminate facilities in Germany, and cost-optimized mineral compounders in China. Single-source vulnerability concentrates in specialty aluminate feedstock streams controlled by a narrow supplier base. Distribution runs through specialty chemical distributors diversifying procurement across Asia-Pacific and European producers, with direct builder procurement expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plaster accelerator supply is tightening around ECHA-registered production capacity, with REACH compliance costs filtering smaller compounders and propping pricing power for incumbent EU-registered suppliers.
For Market Incumbents: Deploy backward integration into sulfate salt feedstock sourcing to secure margin pools against raw material volatility. Consolidate specification authority among Dutch and Belgian applicator cooperatives through annual volume-lock agreements that displace project-by-project purchasing. CEMEX Group and USG Corporation already bundle accelerator formulations with ready-mix plaster contracts; extend this captive placement model into Polish renovation channels opened by EU cohesion fund disbursements. For New Entrants and Emerging Players: Enter via liquid concentrate formats targeting Dutch and Belgian professional cooperatives seeking dust reduction and batch consistency, where specification authority has migrated from general contractors. Polish contractor networks in Warsaw and Kraków represent the most penetrable geography given EU-funded retrofit momentum and less consolidated supplier lists. Pursue technology licensing agreements for encapsulated aluminate carriers to bypass extended REACH registration timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mineral-based compounders with verified low-carbon production footprints in Germany and France, where CSRD Scope 3 disclosure mandates accelerate specification shifts. Long-term viability over the next decade hinges on positioning ahead of embodied carbon scoring integration into building codes. Monitor ECHA dossier registration velocity as the inflection signal—slowing approvals will further concentrate supply among pre-registered suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfate Salt Feedstock | CEMEX Group secures captive supply chains against potassium sulfate price volatility. |
| REACH-Compliant Low-Alkali Formulation Investment | EU-registered suppliers capture specification in French energy retrofit programs. |
| Liquid Concentrate Channel Expansion | Dutch applicator cooperatives lock annual agreements displacing field-mix powders. |
| Technology Licensing for Encapsulated Aluminates | Third-party toxicology testing costs favor pre-registered ECHA dossier holders. |
| Direct Procurement Partnerships with Prefabricated Housing Manufacturers | German offsite producers integrate accelerators into controlled-environment panel lines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at gypsum board manufacturers, procurement leads at prefabricated housing producers, distribution channel partners in specialty chemicals, and technical R&D directors specializing in hemihydrate kinetics. ECHA registration databases, EU cohesion fund disbursement records, and SEC 10-K filings from building materials conglomerates provided validation. Bottom-up volume estimates triangulated against top-down construction spending forecasts.
Granularity-level modeling tracked chemical versus mineral-based accelerator chemistry, powder versus liquid concentrate form factors, and commercial versus residential application segments across the projection horizon. CAGRs derived from trend extrapolation of prefabricated housing cycle frequency and renovation program intensity. Industry-specific inputs included REACH Annex XVII compliance cost trajectories and EU Green Deal embodied carbon scoring adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged ECHA registration delays or abrupt limestone plaster substitution acceleration. Forecasts reflect assumptions about regulatory enforcement consistency and construction labor availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Ireland Cement Market
Building Materials
Europe Building and Construction Sheets Market
Building Materials
Recycled Construction Aggregates Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
North America Cement Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Acoustic Damping Tiles Market
Building Materials
East Africa White Cement Market
Building Materials
India Concealed Cistern Market
Building Materials
Concrete Admixtures Market
Building Materials
US Facade Market
Building Materials
Earthen Plasters Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market