
 Liquid Vitamins Market | 2026-2036
Liquid Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Vitamins Market Intelligence
The direct-to-consumer e-commerce channel is fragmenting the traditional retail landscape for liquid vitamins. This shift allows new entrants to compete with established multi-level marketing structures. For instance, Herbalife Nutrition leverages its extensive distributor network, while Amway Corporation sustains its business through independent business owners. In contrast, Nestlé Health Science positions its products across both clinical and consumer health channels, targeting a broader customer base.
Liquid vitamins are dietary supplements delivering micronutrients in a solubilized form for enhanced bioavailability. These formulations bypass the solid-state dissolution step, offering rapid absorption for specific consumer groups. Multivitamin and Vitamin D products lead the market due to widespread health applications. Demand from the children and elderly end-user segments is particularly strong, focusing on customized dosages and palatable delivery formats like oral drops and syrups.
Regulatory oversight from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) governs health claims and ingredient safety. Similarly, China's National Medical Products Administration (NMPA) imposes strict registration requirements for health foods. These compliance demands shape formulation strategies and market entry barriers. Success for manufacturers depends on effectively managing these varied international standards while proving product efficacy.
Market Dynamics
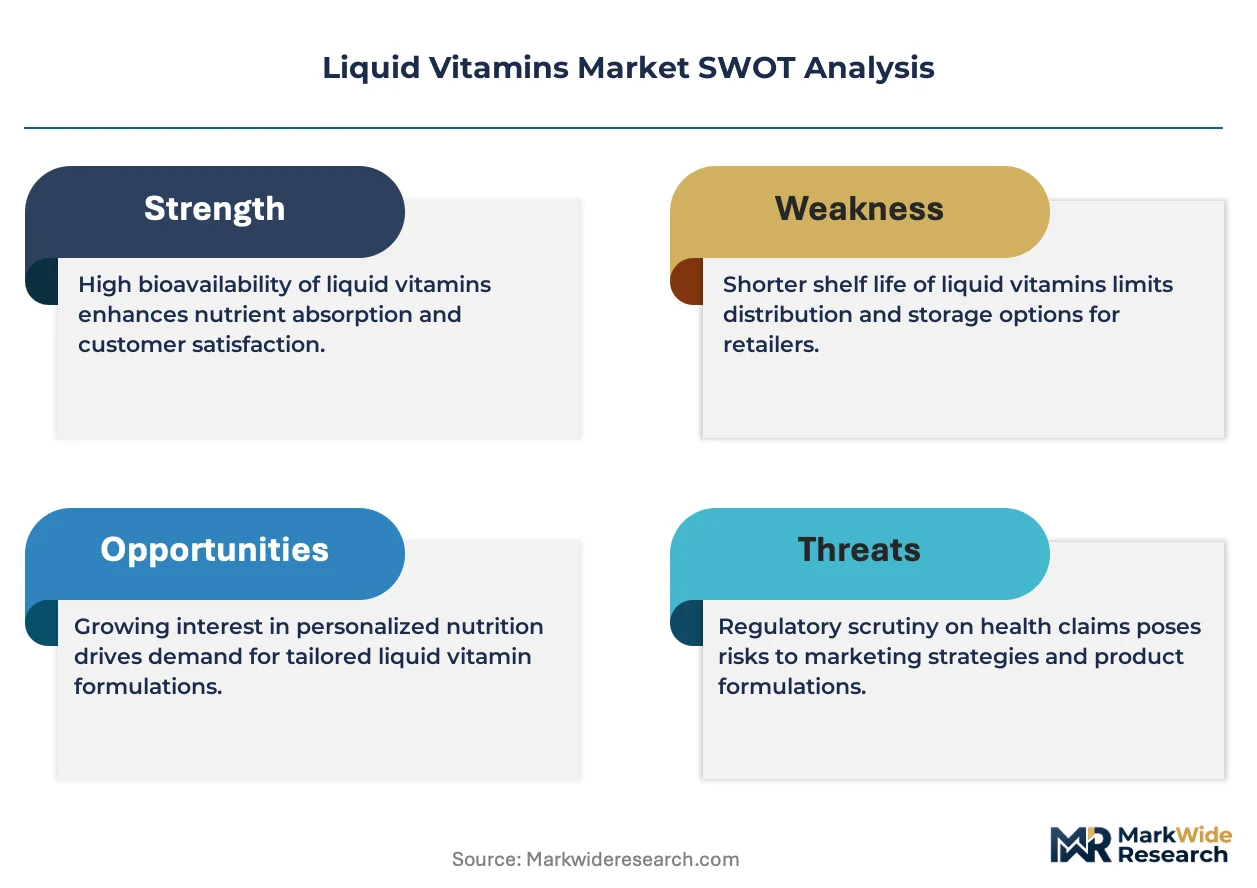
The liquid vitamins market is defined by a central tension between consumer demand for enhanced bioavailability and the intricate web of global regulations governing health claims. This dynamic forces manufacturers to balance formulation innovation, such as micro-encapsulation, with the high cost of clinical substantiation required by authorities like the FDA and EFSA.
Growth Catalysts
- Aging Demographics:Growing elderly populations in countries like Japan and Germany seek easy-to-swallow, palatable supplement formats, driving demand for liquid vitamin drops and syrups that aid absorption and compliance.
- Formulation Technology:Advances in taste-masking and micro-encapsulation technologies are overcoming key product barriers, improving the stability and consumer acceptance of previously unpalatable or unstable liquid nutrients.
- Direct-to-Consumer Channels:The proliferation of e-commerce platforms and social media marketing allows brands to bypass traditional retail, offering personalized liquid vitamin solutions directly to targeted consumer segments.
Market Restraints
- Cost Structure:Liquid formulations often have higher production and packaging costs compared to solid-dose forms like tablets, which can limit their accessibility for price-sensitive consumers.
- Regulatory Scrutiny:Health claims for supplements are strictly regulated by bodies such as the U.S. Food and Drug Administration (FDA), requiring extensive and costly evidence that can be a significant barrier for new entrants.
- Product Stability:The inherent instability of certain vitamins in aqueous solutions shortens shelf life and can require specialized, more expensive logistics like cold-chain shipping to maintain potency.
Strategic Opportunities
- Personalized Nutrition Platforms:There is a significant opportunity to integrate liquid vitamin dispensing systems with digital health platforms and wearables that track biometric data to offer customized, real-time nutrient recommendations.
- Clinical and Medical Foods:Developing specialized liquid formulations for clinical nutrition can address the needs of patients with dysphagia or malabsorption syndromes, creating a high-value, defensible market segment.
- Geographic Expansion:Untapped demand exists in emerging economies across Latin America and Southeast Asia, where rising health consciousness and disposable income create new markets for accessible vitamin products.
Industry Challenges
- Supply Chain Integrity:Ensuring the potency of temperature-sensitive liquid vitamins requires robust cold-chain logistics, which adds significant cost and complexity, particularly for international distribution.
- Regulatory Harmonization:Manufacturers face operational challenges in creating formulations and labels that comply with the disparate and evolving requirements of regulators like China's NMPA and Health Canada.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Vitamins Market |
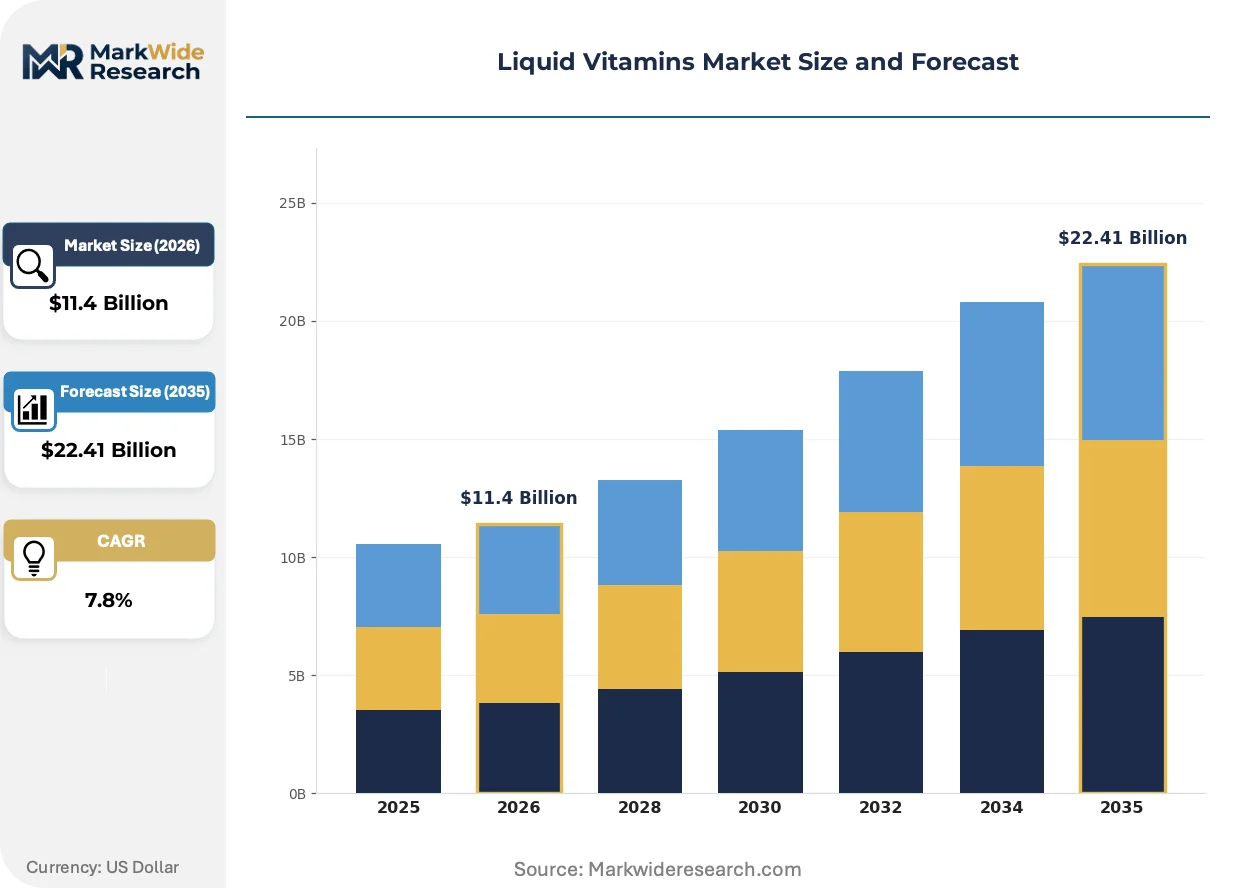
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $22.41 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multivitamins, Vitamin D, Vitamin B Complex, Vitamin C, Vitamin A, Vitamin E Delivery Format: Oral Drops, Syrups, Shots, Powders, Gummies, Sprays Application: Immune Support, Bone Health, Energy Boost, Skin Care, Digestive Health, Eye Health End User: Adults, Children, Pregnant Women, Elderly, Athletes, Fitness Enthusiasts |
| Companies Covered | Abbott Laboratories, Herbalife Nutrition, Amway Corporation, Nestlé Health Science, MaryRuth Organics, Nature’s Way, Garden of Life, DSM Nutritional Products, Liquid Health Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Vitamins Market Strategic Shifts & Innovations
The market is being reshaped by the convergence of advanced formulation science and a consumer shift towards personalized, evidence-backed nutritional solutions. This movement prioritizes demonstrable bioavailability and customized dosing over one-size-fits-all products, pushing innovation in delivery systems and business models.
Nano-emulsion technology creates microscopic droplets that enhance the solubility and absorption of fat-soluble vitamins. Performance-focused consumers and athletes are early adopters, seeking faster nutrient uptake from sports nutrition products. This delivery method is collapsing the perceived boundary between dietary supplements and pharmaceutical-grade nutrient delivery, creating a new premium product category.
European Food Safety Authority (EFSA) regulations mandate rigorous scientific evidence for all health claims made on food supplements. This strict standard increases the R&D burden and time-to-market for manufacturers aiming to sell in the European Union. The vitamin D and children's multivitamin segments are particularly impacted, forcing companies to reformulate products to align with pre-approved, generic claims or invest heavily in clinical trials.
Subscription-based purchasing models are gaining traction, offering consumers personalized liquid vitamin packs delivered directly to their homes. This direct-to-consumer shift disrupts traditional health stores and pharmacies by fostering a continuous brand-customer relationship. The trend is most visible in North America, where consumers value the convenience and customization enabled by digital platforms.
Liquid Vitamins Market Segmentation
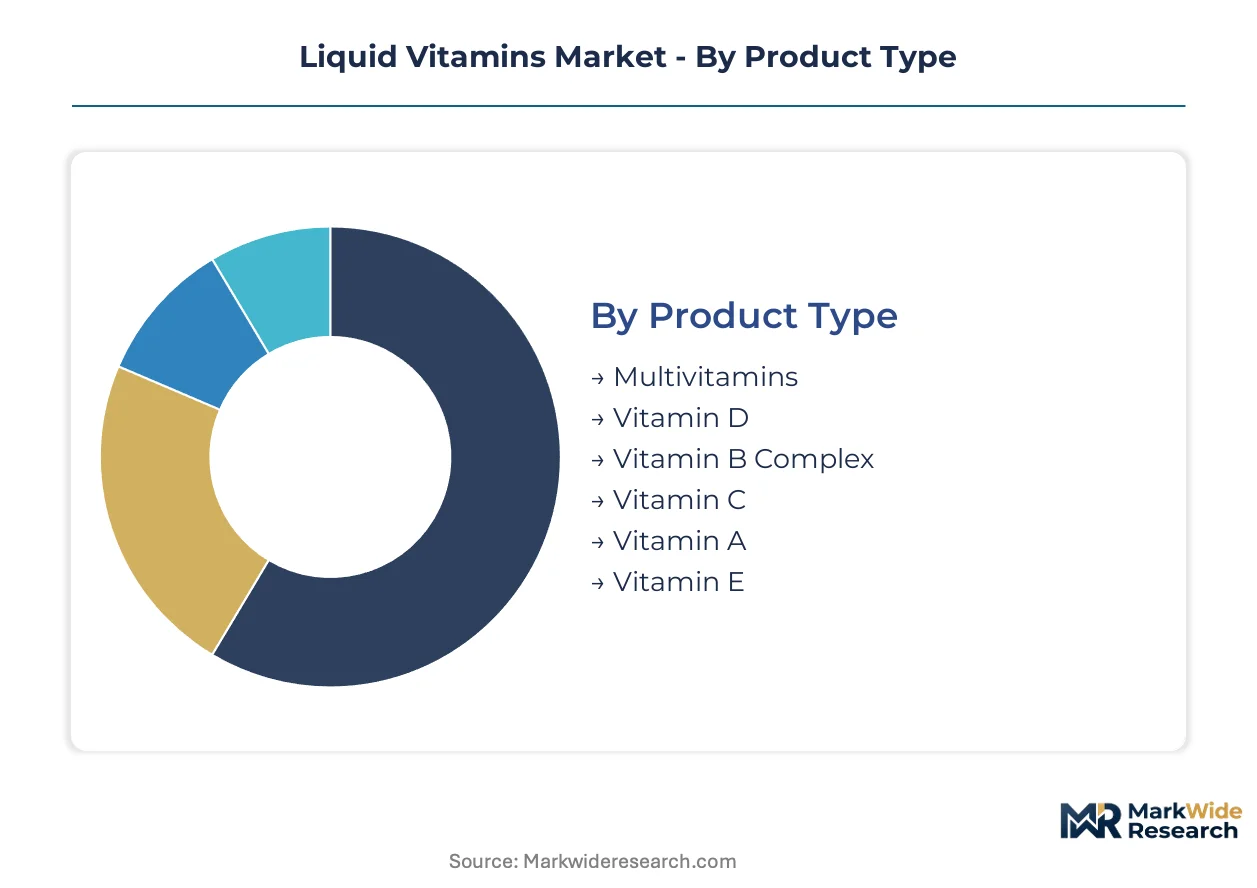
The liquid vitamins market is differentiated by specific product compositions and consumer needs, enabling manufacturers to tailor offerings for diverse health objectives. Understanding these distinct segments allows for targeted product development and distribution strategies. This granular view reveals where innovation is most impactful and where consumer demand is most concentrated.
Product Type:
Product type segmentation delineates the specific micronutrients delivered, reflecting varied physiological requirements across the population.
- Multivitamins:These formulations combine multiple essential vitamins and minerals, providing broad nutritional support. Demand concentrates in the United States, driven by a high consumer health consciousness seeking comprehensive daily wellness.
- Vitamin D:Often delivered as cholecalciferol or ergocalciferol, this fat-soluble vitamin is crucial for bone health and immune function. Demand is particularly strong in regions with limited sun exposure, addressing widespread deficiency concerns.
- Vitamin B Complex:This group of eight B vitamins supports energy metabolism and nervous system health.
- Vitamin C:An essential antioxidant, Vitamin C aids immune function and collagen synthesis.
- Vitamin A:Important for vision, immune function, and skin health, Vitamin A is often found in eye health formulations.
- Vitamin E:A powerful antioxidant that protects cells from oxidative damage, Vitamin E is often included in skin care products.
Multivitamins hold significant installed capacity. Vitamin D is rotating up the share rankings.
Delivery Format:
The delivery format directly influences consumer adherence and absorption rates, catering to specific user preferences and physiological needs.
- Oral Drops:These concentrated liquid formulations allow for precise, customizable dosing, particularly beneficial for infants and the elderly who require small, easily administered quantities. Demand for oral drops is high in pediatric and geriatric care settings.
- Syrups:Often flavored and sweetened, syrups provide a palatable and easy-to-swallow option for children and individuals with dysphagia. Germany and Japan show significant demand for these formats due to aging demographics.
- Shots:Single-serving, concentrated liquid doses offer convenience and rapid nutrient delivery for active consumers.
- Powders:Designed to be mixed with liquids, powders offer flexible dosing and are popular in sports nutrition.
- Gummies:Chewable, flavored supplements provide an appealing alternative for children and adults who dislike pills.
- Sprays:Administered sublingually or orally, sprays offer rapid absorption and ease of use.
Oral drops and syrups are experiencing the steepest expansion trajectory within this market segment.
Application:
Application-based segmentation highlights the primary health benefits consumers seek, driving specialized product development and marketing efforts.
- Immune Support:These formulations contain vitamins like C and D, along with zinc, to bolster the body's natural defenses against illness. Consumer focus on preventative health drives demand for immune-boosting products across all age groups.
- Bone Health:Products targeting bone health typically include Vitamin D, calcium, and Vitamin K, crucial for maintaining skeletal integrity. The aging population in countries like Japan and Germany significantly contributes to this segment's demand.
- Energy Boost:Formulations rich in B vitamins and sometimes caffeine provide quick energy enhancement for active individuals.
- Skin Care:Vitamins A, C, and E are incorporated into liquid supplements to support skin health and appearance from within.
- Digestive Health:Probiotic and prebiotic liquid formulations, sometimes combined with specific vitamins, aid gut function.
- Eye Health:Vitamins A, C, and E, along with lutein and zeaxanthin, are key ingredients in supplements supporting ocular health.
Immune Support and Bone Health are gaining share fastest among the various application segments.
End User:
End-user segmentation reveals specific demographic and lifestyle groups with distinct nutritional requirements and preferences for liquid vitamin delivery.
- Children:This segment requires palatable and easy-to-administer liquid forms, often focusing on essential growth and developmental vitamins. Parental health consciousness in North America drives product innovation in this area.
- Elderly:Individuals in this age group often experience dysphagia or malabsorption, making liquid vitamins a preferred choice for nutrient delivery. European countries with significant aging populations show high demand.
- Adults:The largest and most diverse segment, adults seek liquid vitamins for general wellness and specific health concerns.
- Pregnant Women:Specialized formulations provide crucial nutrients like folic acid and iron to support maternal and fetal health.
- Athletes:Performance-focused consumers demand rapid absorption formulas for recovery and sustained energy, often through shots or specialized blends.
- Fitness Enthusiasts:This group seeks convenient and effective liquid supplements to support their active lifestyles and nutritional goals.
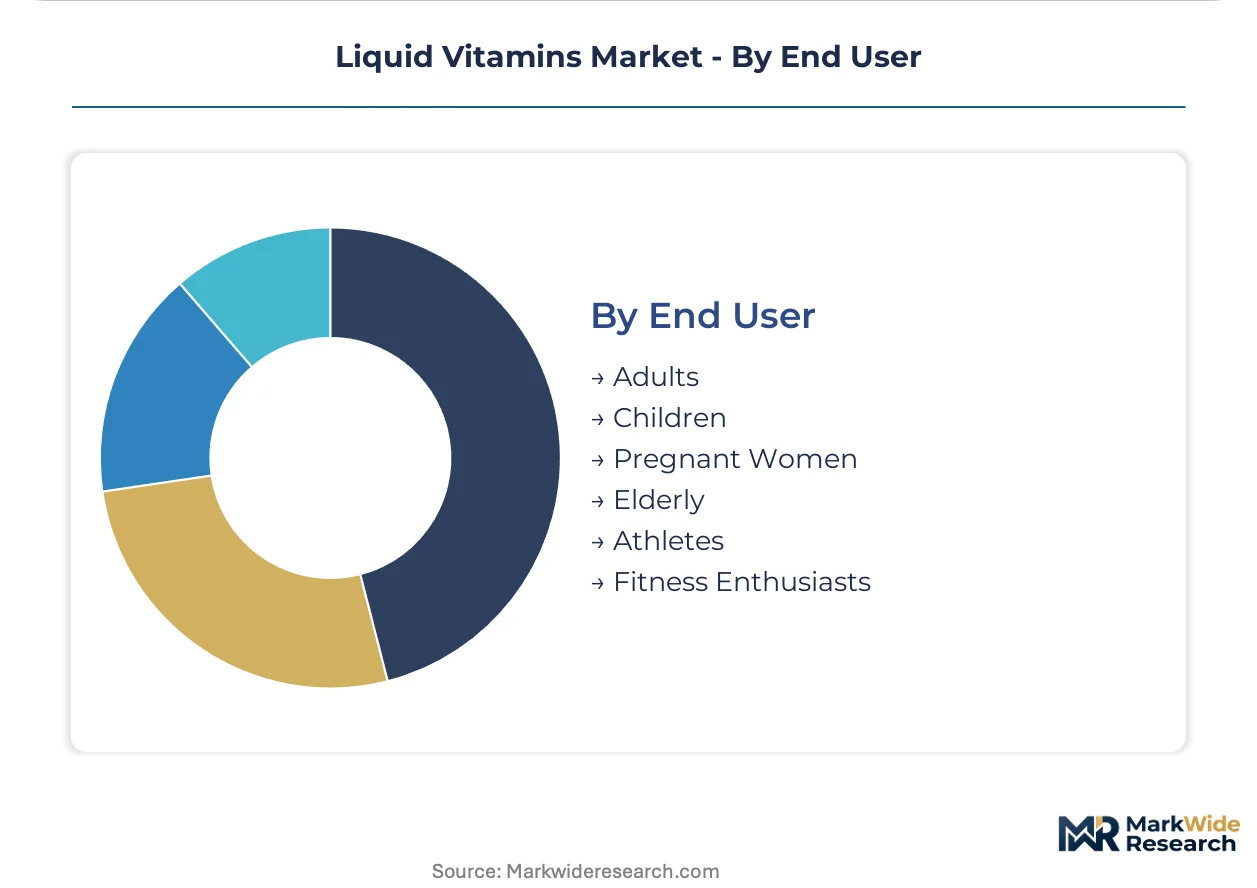
The Children and Elderly segments represent the fastest-growing end-user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A robust logistics infrastructure, particularly the extensive network of distribution centers and e-commerce fulfillment hubs, underwrites the United States' pivotal role in the liquid vitamins market. This infrastructure facilitates rapid product delivery and supports significant market penetration across diverse consumer segments. Established supply chains ensure consistent availability of liquid formulations nationwide.
United States
High consumer health consciousness and established distribution networks drive significant demand for multivitamins and Vitamin D products in the United States. The U.S. Food and Drug Administration (FDA) strictly regulates health claims and ingredient safety for dietary supplements. Major metropolitan areas like Los Angeles and New York City serve as key consumption hubs, propelled by health-aware populations.
Germany
Germany's aging demographic generates substantial demand for easy-to-swallow liquid vitamin formats, including palatable syrups and oral drops. The European Food Safety Authority (EFSA) mandates rigorous scientific evidence for all health claims, influencing product formulation strategies. Munich and Berlin are centers for pharmaceutical and nutraceutical research, fostering innovation in liquid delivery systems.
Japan
Japan confronts significant demand for liquid vitamins from its rapidly aging population, seeking convenient and effective nutrient delivery options. The country's Ministry of Health, Labour and Welfare oversees health food regulations, emphasizing product safety and efficacy. Tokyo and Osaka represent major consumption markets, supported by advanced healthcare infrastructure and consumer awareness.
China
Strict regulatory frameworks from China's National Medical Products Administration (NMPA) impose significant registration requirements for health foods, shaping market entry barriers. Rising health consciousness among urban populations drives demand for liquid vitamins, particularly for children and the elderly. Shanghai and Beijing are key economic centers where international brands establish a strong presence.
Brazil
Brazil's expanding middle class and growing health awareness contribute to increasing demand for accessible vitamin products, including liquid formulations. The Brazilian Health Regulatory Agency (ANVISA) governs the registration and commercialization of dietary supplements. São Paulo and Rio de Janeiro are major urban centers experiencing significant growth in the consumer health sector.
Liquid Vitamins Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying specialized ingredients like micro-encapsulated vitamins. The market exhibits a tiered structure, with established multi-level marketing entities coexisting alongside agile direct-to-consumer e-commerce brands. Companies pursue portfolio diversification and geographic expansion to capture new consumer segments. Technology licensing for advanced formulation techniques also represents a key competitive move.
Multi-level marketing stalwarts like Herbalife Nutrition and Amway Corporation anchor traditional distribution channels, leveraging extensive distributor networks for direct sales. Nestlé Health Science, in contrast, exemplifies a diversified approach, positioning its liquid vitamin products across both clinical and consumer health channels to target a broader customer base. MaryRuth Organics represents the direct-to-consumer e-commerce archetype, focusing on personalized solutions and online engagement.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Herbalife Nutrition |
| Amway Corporation |
| Nestlé Health Science |
| MaryRuth Organics |
| Nature’s Way |
| Garden of Life |
| DSM Nutritional Products |
| Liquid Health Inc. |
| Others |
Cost & Logistics Intelligence
The European pharmaceutical research clusters, particularly in Germany, influence the pricing power of specialized liquid vitamin formulations by controlling advanced micro-encapsulation technologies. This capacity dynamic impacts downstream accessibility for various consumer segments.
Pricing Analysis
Volume-based tiered pricing structures characterize the liquid vitamins market, with significant price differentiation observed for customized formulations and premium-branded products. Price differentiation drivers include formulation complexity, specific micronutrient content, and brand equity. Pricing softness stems from the high production costs associated with specialized packaging and cold-chain logistics. Price sensitivity is higher among general wellness consumers compared to athletes seeking performance-focused solutions.
Supply Chain Analysis
Extended payment terms for raw material procurement are common in the liquid vitamins supply chain, driven by the need to manage inventory of temperature-sensitive ingredients. Supply concentration for specialized vitamin compounds draws from manufacturing hubs in China, India, and the United States. Regulatory harmonization across diverse markets like the EU and China presents a significant structural risk. Distribution for liquid vitamins increasingly runs through direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid vitamins market presents an early-cycle expansion story, buoyed by rising consumer health consciousness driving deeper penetration into daily wellness routines.
For Market Incumbents: Entrench existing market share by investing in advanced formulation R&D, particularly in taste-masking and nano-emulsion technologies, to counter the threat from agile direct-to-consumer brands. Control over established multi-level marketing networks provides a durable channel lever against new digital entrants. Prioritize compliance with evolving regulatory standards to maintain market access.
For New Entrants and Emerging Players: Underpenetrated markets in Southeast Asia and Latin America represent a significant white-space opportunity for liquid vitamin brands, especially targeting the growing middle-class segment. Developing personalized nutrition platforms that integrate with digital health data offers a compelling go-to-market angle for these regions. Focus on cost-effective yet bioavailable formulations.
For Investors and Strategic Acquirers: Long-term, this sits as a foundational consumer health play because of sustained demographic shifts towards aging populations and preventative wellness. Acquisition targets should focus on specialized formulation technology providers or established direct-to-consumer brands with strong digital engagement. Regulatory clarity on health claims across major markets will be a key signal to watch for accelerated growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Personalized Nutrition Platforms | Integrates biometric data for customized liquid vitamin recommendations, enhancing consumer loyalty. |
| Invest in Nano-emulsion Technology | Improves bioavailability and absorption of fat-soluble vitamins, creating premium product categories. |
| Expand into Emerging Economies | Captures new consumer segments in Latin America and Southeast Asia with rising disposable income. |
| Strengthen Cold-Chain Logistics | Ensures potency of temperature-sensitive liquid formulations across international distribution networks. |
| Pursue Clinical Substantiation | Supports rigorous health claims required by regulators like EFSA, building consumer trust and market access. |
Research Approach
Operator-level perspectives from R&D scientists, regulatory affairs specialists, marketing directors, and supply chain managers anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary validation from FDA filings, EFSA opinions, industry trade association reports, and market intelligence databases. This approach combined bottom-up market sizing with top-down validation of segment trends.
Scenario-bracketing informed the forecast framework, modeling market dynamics across the projection horizon under various adoption and regulatory landscapes. Segmentation dimensions included product type, delivery format, application, end-user, and regional regulatory environment. Compound annual growth rates were derived through statistical modeling, integrating historical trends and projected market influences. Key forecast inputs included consumer health consciousness trends and the adoption rates of advanced formulation technologies.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or raw material price volatility would shift the trajectory of the liquid vitamins market. Forecasts reflect a synthesis of documented assumptions and market intelligence. Regulatory shifts, such as new NMPA requirements or EFSA claim changes, could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Asia-Pacific Vitamin a Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market