
 Tocopherols Market | 2026-2036
Tocopherols Market Size, Share, and Industry Trends Forecast 2026-2036
Tocopherols Market Analysis
The EU Green Deal is decoupling antioxidant procurement from conventional synthetic supply chains, forcing ingredient buyers to verify renewable sourcing credentials. BASF leverages its integrated vitamin E complex to sustain European pharmaceutical-grade output. DSM anchors its position through biotechnology leadership in natural-extraction tocopherol streams. Cargill competes on oilseed crushing scale, converting distillate streams into food-grade antioxidant supply.
Tocopherols comprise a family of lipid-soluble organic compounds—alpha, beta, gamma, and delta isomers—derived primarily from vegetable oil deodorizer distillates through molecular distillation or chemical synthesis, functioning as chain-breaking antioxidants that interrupt lipid peroxidation in oils, fats, and biological membranes. Alpha-Tocopherol dominates pharmaceutical and nutraceutical applications due to its highest vitamin E biopotency, while Gamma-Tocopherol captures expanding food preservation demand as processors replace synthetic antioxidants with plant-derived alternatives. The Application dimension reveals Nutraceuticals as the fastest-growing margin pool, though Food & Beverages retains volume leadership through baked goods and frying oil stabilization requirements.
FDA GRAS status governs tocopherol deployment in US food matrices, while EFSA sets purity thresholds for European nutraceutical claims, and China's SAMR enforces GB standards for imported antioxidant additives. These frameworks elevate compliance costs for cross-border suppliers but simultaneously reward certified natural-extraction producers with premium channel access. Stakeholders must monitor evolving clean-label definitions that recalibrate which isomer profiles qualify as consumer-acceptable natural antioxidants.
Market Dynamics
Clean-label mandates from the EU Green Deal are forcing food processors to abandon synthetic antioxidants, creating a structural pull toward natural-extraction tocopherol streams and rewiring procurement criteria across European supply chains.
Growth Catalysts
- EU Green Deal sourcing standards:The framework mandates renewable credentials for food-grade additives, compelling manufacturers to certify natural-extraction tocopherol provenance and redirecting volume toward European distillate processors.
- Functional nutrition fortification:Dietary supplement producers are embedding alpha-tocopherol into condition-specific formulations targeting immune and cognitive health, expanding pharmaceutical-grade offtake.
- Germany's processing clusters:Concentrated food manufacturing and pharmaceutical formulation activity in Baden-Württemberg and Bavaria generate sustained demand for premium-grade mixed tocopherol concentrates.
Market Restraints
- Vegetable oil feedstock volatility:Soybean and sunflower oil price swings directly compress deodorizer distillate economics, squeezing natural-extraction margins without corresponding tocopherol price pass-through mechanisms.
- China's GB standards enforcement:SAMR import protocols for antioxidant additives impose batch-level purity documentation that extends customs clearance timelines and elevates compliance overhead for non-domestic suppliers.
- Synthetic antioxidant substitution:BHT and TBHQ retain cost advantages in bulk frying oil applications, limiting tocopherol penetration in price-sensitive emerging-market food processing sectors.
Strategic Opportunities
- India's FSSAI clean-label pathway:The regulator's progressive tightening of synthetic additive permissible limits creates regulatory tailwinds for natural tocopherol adoption in edible oil and bakery segments.
- Cosmeceutical topical delivery:Alpha-tocopherol acetate integration into dermatological formulations represents an underdeveloped application channel with margin structures exceeding food-grade benchmarks.
- Biotechnology extraction convergence:Novel microbial fermentation routes combined with membrane separation technologies promise to decouple tocopherol supply from vegetable oil processing volume constraints.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA and US FDA validation protocols for vitamin E active pharmaceutical ingredients demand 18-24 month documentation cycles that strain working capital for specialty producers.
- Isomer profile standardization gaps:Absence of harmonized analytical methods for gamma-tocopherol quantification across food and nutraceutical specifications creates contract disputes and quality arbitration overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tocopherols Market |
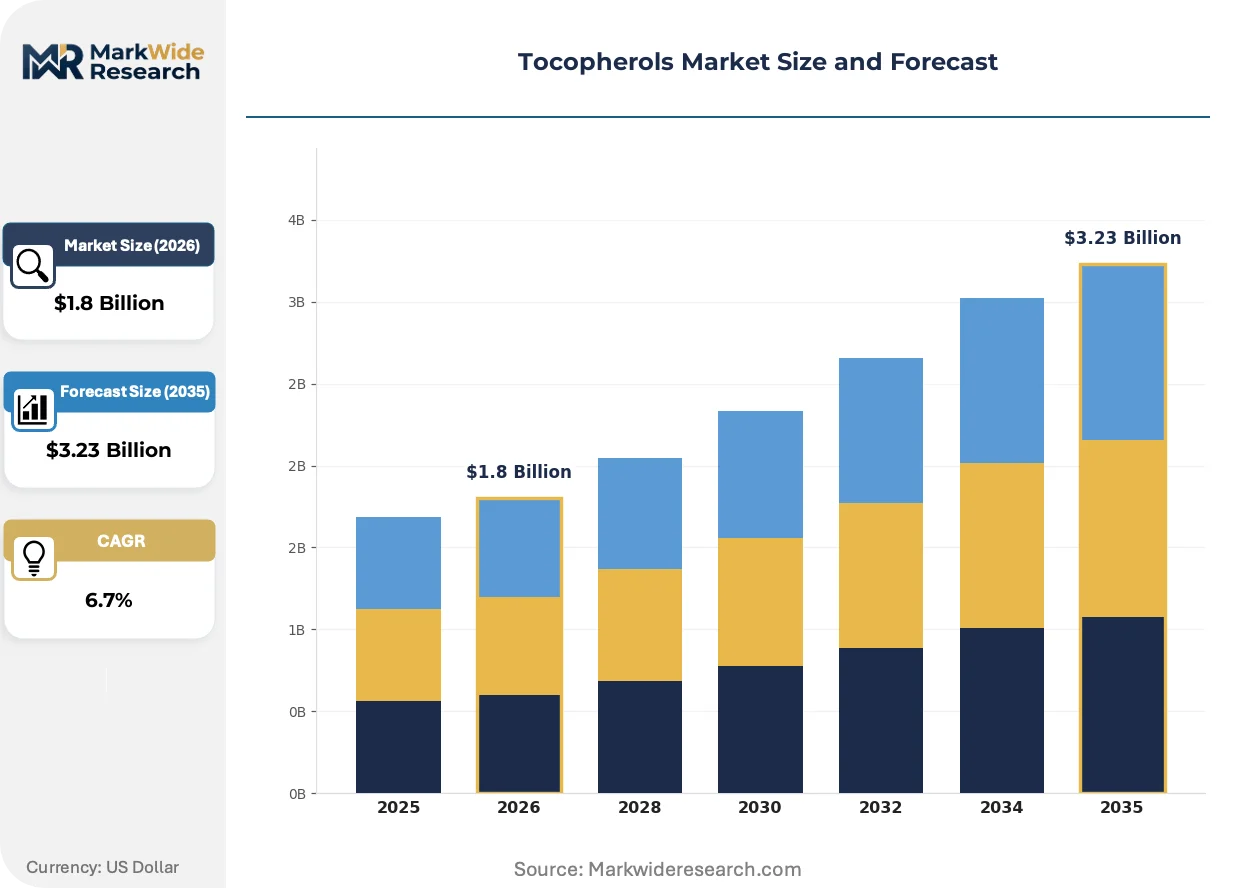
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-Tocopherol, Beta-Tocopherol, Gamma-Tocopherol, Delta-Tocopherol Application: Food & Beverages, Cosmetics, Nutraceuticals, Animal Feed End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Dietary Supplement Producers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland, BASF, Cargill, Merck KGaA, DSM, DuPont Danisco, Kensing Solutions, BTSA, Davos Life Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tocopherols Market Emerging Trajectories
Molecular distillation and biotechnology extraction routes are diverging as parallel supply architectures, each capturing distinct end-use segments based on certification requirements and cost positioning rather than converging on a single dominant technology.
Supercritical CO2 extraction is rewriting tocopherol recovery economics by enabling selective fractionation of alpha and gamma isomers without thermal degradation. Nutraceutical contract manufacturers in Switzerland and Germany are adopting these systems at pilot scale. The technology is compressing synthetic tocopherol's historical cost advantage in high-purity pharmaceutical applications.
REACH authorization requirements for synthetic antioxidants are accelerating food processor migration toward plant-derived alternatives. The regulation forces reformulation of legacy frying oil stabilization protocols across European snack manufacturing. Gamma-tocopherol concentrates are capturing displaced volume in industrial frying operations previously dependent on petrochemical-derived preservatives.
Ingredient buyers are consolidating supplier relationships around vertically integrated tocopherol-vitamin E complex producers capable of delivering combined antioxidant-nutrient premixes. This bundling displaces discrete procurement of standalone antioxidants and vitamin fortificants. German and Dutch food compounders are driving this consolidation most aggressively, seeking single-source accountability for clean-label formulation compliance.
Tocopherols Market Segmentation
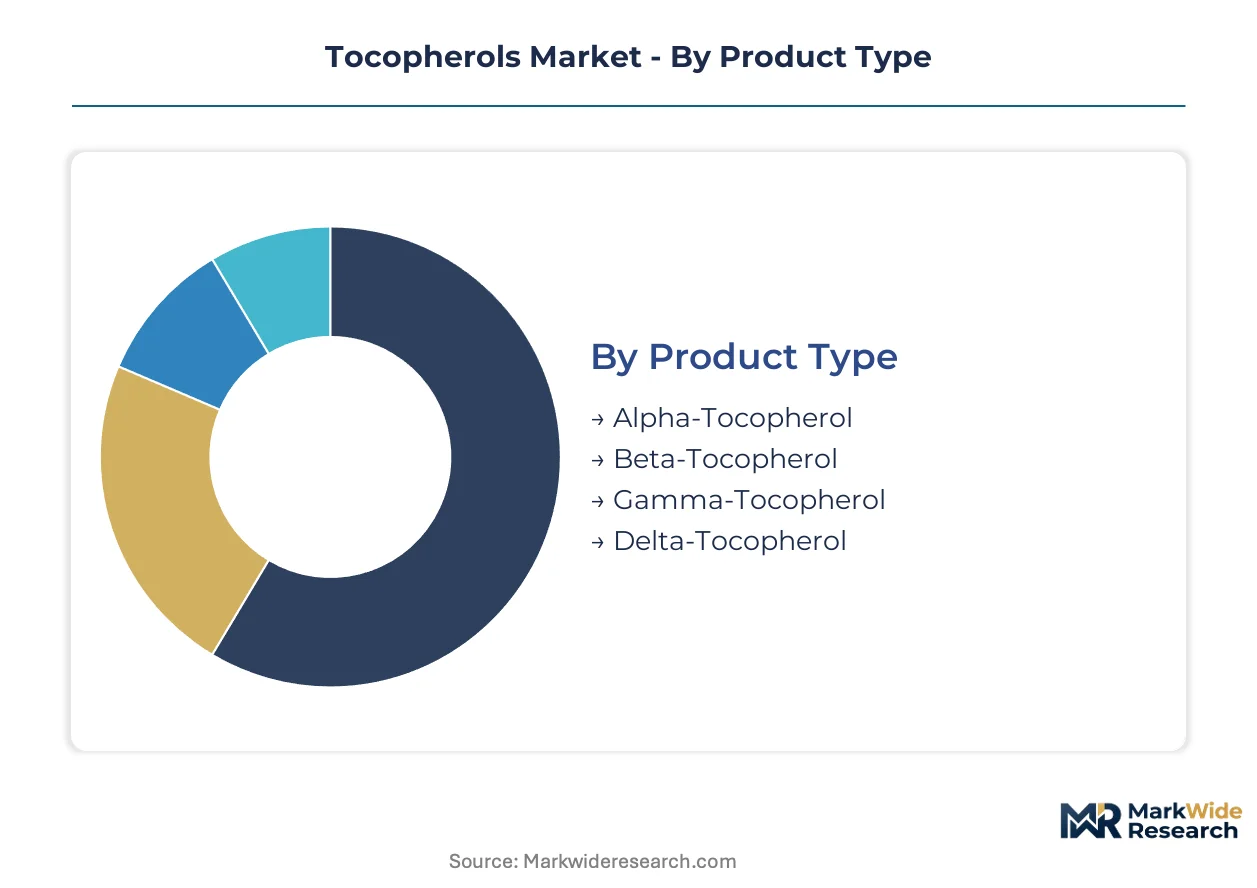
Tocopherol isomer profiles and application specifications determine certification pathways, with pharmaceutical-grade alpha-tocopherol demanding EMA validation while food-grade gamma concentrates navigate EFSA purity thresholds. Segmentation reveals how procurement criteria fragment across end-use compliance regimes.
Product Type:
EMA pharmaceutical-grade certification governs alpha-tocopherol active ingredients, while EFSA food-additive authorizations apply to mixed isomer concentrates for antioxidant applications.
- Alpha-Tocopherol:Possesses the highest vitamin E biopotency among all isomers, making it the reference standard for IU measurement. Pharmaceutical firms in Germany and Switzerland concentrate demand here for parenteral nutrition and dermatological formulations, driven by EMA's stringent purity documentation requirements that synthetic alternatives cannot satisfy.
- Gamma-Tocopherol:Demonstrates superior antioxidant activity in lipid matrices compared to alpha isomers, with distinct nitric oxide scavenging properties. Food processors in Baden-Württemberg are displacing synthetic BHT with gamma concentrates in industrial frying operations, compelled by EU Green Deal renewable sourcing mandates.
- Beta-Tocopherol:Occurs naturally in lower concentrations within vegetable oil distillates, typically co-recovered with alpha isomers during molecular distillation.
- Delta-Tocopherol:Exhibits the highest antioxidant potency per mole among tocopherol variants, though limited commercial availability constrains formulation adoption.
Leading the category by volume: Gamma-Tocopherol. Growing fastest: Alpha-Tocopherol.
Application:
Margin structures diverge sharply across applications, with cosmeceutical and nutraceutical channels commanding premium pricing over commodity food preservation.
- Nutraceuticals:Condition-specific formulations targeting immune modulation and cognitive health embed alpha-tocopherol at elevated concentrations. Swiss contract manufacturers are expanding pharmaceutical-grade encapsulation capacity to serve this channel, where EFSA health claim substantiation creates barrier-to-entry value capture.
- Cosmetics:Alpha-tocopherol acetate serves as the primary dermatological antioxidant, integrated into anti-aging topicals and sun care formulations. German cosmeceutical brands in Bavaria are driving demand for high-purity isomer fractions that resist oxidative degradation during emulsion processing.
- Food & Beverages:Gamma-tocopherol concentrates stabilize frying oils and baked goods against rancidity, with bakery processors in the Netherlands reformulating legacy antioxidant protocols.
- Animal Feed:Mixed tocopherol additives preserve fat-soluble vitamin stability in compound feeds, with poultry and swine nutrition representing primary offtake.
Highest margin capture: Nutraceuticals. Steepest expansion trajectory: Cosmetics.
End User:
Procurement sophistication separates pharmaceutical-grade buyers with dedicated quality audit teams from commodity food manufacturers purchasing on specification sheets.
- Pharmaceutical Firms:Require EMA-validated active pharmaceutical ingredients with documented isomer purity exceeding 96%, supported by stability data packages.
- Dietary Supplement Producers:Source alpha-tocopherol acetate and succinate esters for tablet and softgel formulations, with USP-NF compliance governing North American exports.
- Food Manufacturers:Purchase mixed tocopherol concentrates based on total antioxidant activity metrics rather than isomer-specific composition.
- Cosmetic Companies:Specify cosmetic-grade tocopherol with heavy metal limits stricter than food-grade thresholds, particularly for facial care applications.
Most stringent procurement: Pharmaceutical Firms. Fastest contract growth: Dietary Supplement Producers.
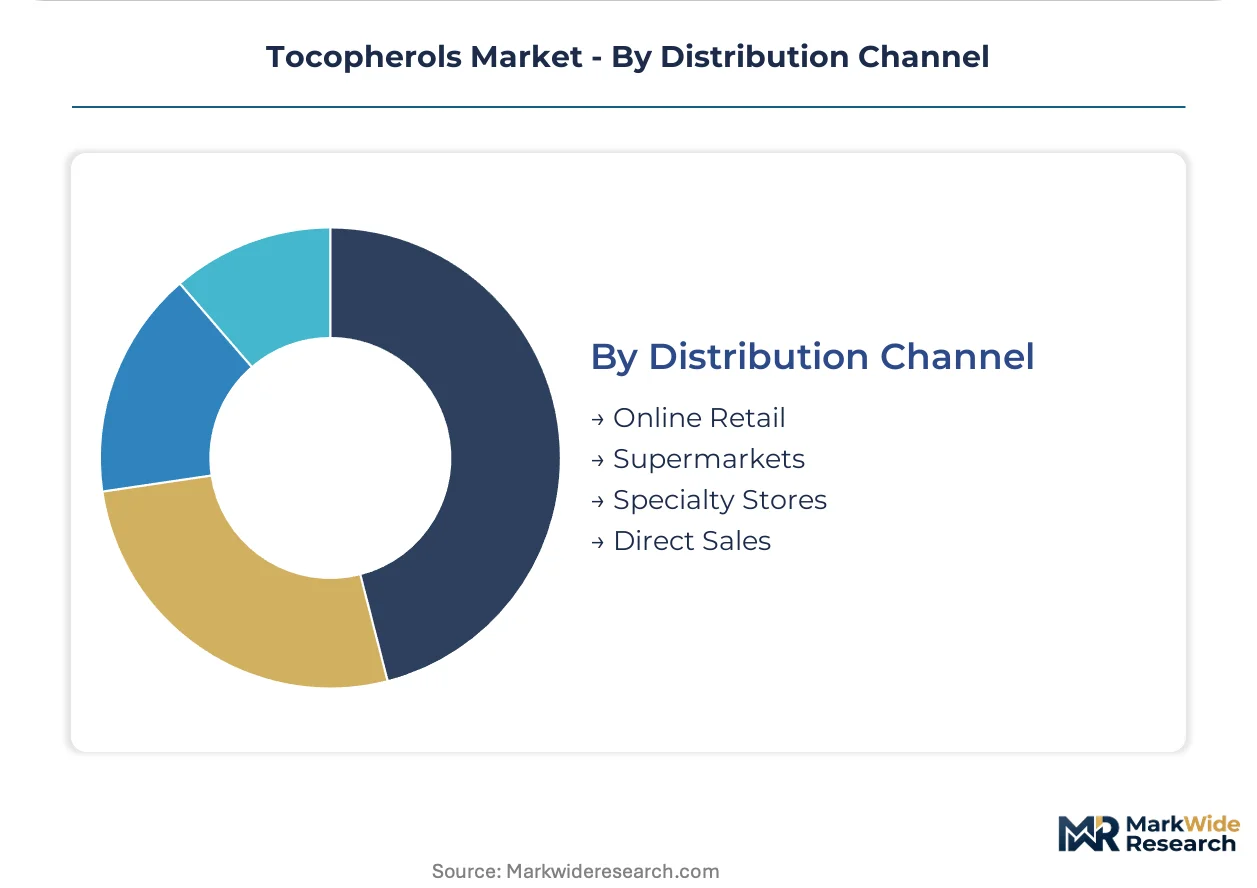
Distribution Channel:
Channel selection correlates with purchase scale and technical service requirements, with direct relationships dominating pharmaceutical procurement.
- Direct Sales:Pharmaceutical and large-scale food compounders negotiate multi-year supply agreements with integrated vitamin E complex producers, securing volume commitments and technical support.
- Specialty Stores:Serve artisanal cosmetics manufacturers and small-batch nutraceutical formulators requiring customized isomer blends and lower minimum order quantities.
- Online Retail:Enables spot purchasing of standard-grade tocopherol concentrates by mid-sized food processors without established supplier relationships.
- Supermarkets:Limited to consumer-facing vitamin E supplement products rather than industrial antioxidant procurement.
Dominant by value: Direct Sales. Expanding most quickly: Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's food processing and pharmaceutical manufacturing clusters anchor European tocopherol demand, with Stuttgart and Mannheim housing concentrated antioxidant formulation capacity serving continental supply chains.
Germany
Bavarian pharmaceutical compounders and Baden-Württemberg food processors drive premium-grade alpha-tocopherol consumption for parenteral nutrition and clean-label frying oil stabilization. EFSA purity thresholds for nutraceutical claims elevate compliance requirements for imported concentrates. The Rhine-Neckar metropolitan region hosts integrated vitamin E complex producers supplying EMA-validated active pharmaceutical ingredients to Swiss and German drug manufacturers.
United States
Dietary supplement manufacturers in New Jersey and California expand alpha-tocopherol fortification in condition-specific immune and cognitive health formulations. FDA GRAS status governs tocopherol deployment in food matrices, with batch-level documentation requirements for antioxidant additives. Chicago-area food compounders reformulate baked goods and snack manufacturing protocols to displace synthetic preservatives with plant-derived gamma-tocopherol concentrates.
China
Edible oil processors in Shandong and Jiangsu provinces represent the dominant demand center for food-grade mixed tocopherol antioxidants in industrial frying applications. SAMR enforces GB standards for imported antioxidant additives, imposing extended customs clearance timelines and purity documentation overhead. The Yangtze River Delta concentration of oilseed crushing capacity generates substantial deodorizer distillate feedstock for domestic tocopherol extraction.
India
FSSAI's progressive tightening of synthetic additive permissible limits creates regulatory tailwinds for natural tocopherol adoption in Maharashtra and Gujarat edible oil refining sectors. The regulator's clean-label pathway accelerates bakery segment reformulation away from BHT and TBHQ preservatives. Mumbai-Pune pharmaceutical manufacturing corridors expand pharmaceutical-grade vitamin E sourcing for domestic nutraceutical export production.
Switzerland
Swiss nutraceutical contract manufacturers in the Basel region pilot supercritical CO2 extraction systems for selective alpha and gamma isomer fractionation. Swissmedic pharmaceutical-grade certification requirements sustain premium positioning for domestic tocopherol active ingredients. Geneva-area cosmeceutical brands drive demand for high-purity tocopherol acetate integration into dermatological anti-aging formulations.
Tocopherols Market Vendor Landscape
The competitive structure tilts toward integrated vitamin E complex producers capable of bundling antioxidant-nutrient premixes for pharmaceutical and food compounder procurement. Three strategic archetypes occupy distinct positions: oilseed crushing majors leveraging distillate stream scale, biotechnology specialists commanding natural-extraction certification premiums, and pharmaceutical-grade pure-play producers sustaining EMA-validated output. Capacity expansion in molecular distillation and strategic partnerships around supercritical extraction technology represent the dominant competitive moves reshaping supply architecture.
Within the integrated chemical conglomerate tier, BASF and DSM occupy positions exemplifying divergent technology bets—BASF through conventional synthesis scale and DSM through biotechnology leadership in natural-extraction streams. Cargill anchors the agribusiness-integrated archetype, converting oilseed crushing distillate streams into food-grade antioxidant supply. Merck KGaA represents the pharmaceutical-grade specialist position, with German-origin structure signaling EMA-validation capabilities for active pharmaceutical ingredient supply.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| BASF |
| Cargill |
| Merck KGaA |
| DSM |
| DuPont Danisco |
| Kensing Solutions |
| BTSA |
| Davos Life Science |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction adoption is compressing synthetic tocopherol's historical cost advantage while simultaneously concentrating supply relationships around Swiss and German contract manufacturers capable of pharmaceutical-grade certification. This technology shift rewards integrated vitamin E complex producers with pricing power over discrete antioxidant suppliers.
Pricing Analysis
Pharmaceutical-grade alpha-tocopherol pricing anchors to EMA-validated purity outcomes rather than commodity feedstock costs. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates premium EMA-validated active ingredients from standard EFSA-compliant concentrates and economy mixed tocopherol streams. Cost compression in food-grade gamma-tocopherol is intensifying because REACH authorization pressures are accelerating synthetic antioxidant displacement without full price pass-through to edible oil processors. Feed manufacturers exhibit highest price sensitivity due to specification-based purchasing on total antioxidant activity metrics, while pharmaceutical compounders demonstrate lowest sensitivity given parenteral nutrition formulation requirements.
Supply Chain Analysis
Direct-to-pharmaceutical-compounder channels handle EMA-validated active ingredient demand, with multi-year supply agreements governing premium-grade procurement. Geographic supply concentrates in Germany, Switzerland, and China, with Baden-Württemberg housing integrated vitamin E complex producers and Shandong province anchoring deodorizer distillate feedstock generation. Raw material dependencies draw from soybean oil, sunflower oil, and rapeseed processing streams, with biotechnology fermentation routes emerging as alternative feedstock pathways. Single-source vulnerability characterizes pharmaceutical-grade supply given 18-24 month EMA validation timelines that lock buyers into validated supplier relationships. Distribution runs through direct sales for pharmaceutical and large-scale food compounders, specialty distributors for artisanal cosmetics manufacturers, and online platforms for mid-sized processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over deodorizer distillate streams or biotechnology extraction capacity determines margin capture. Players are pursuing backward integration into vegetable oil processing or microbial fermentation feedstocks to secure supply independence.
For Market Incumbents: Lock in pharmaceutical-grade certification pipelines by expanding EMA-validated active ingredient capacity in the Rhine-Neckar region, while securing long-term deodorizer distillate offtake agreements with major oilseed crushers to defend against biotechnology extraction entrants. Synthetic tocopherol substitution risk in emerging markets demands accelerated natural-extraction scale to maintain cost parity. For New Entrants and Emerging Players: Capture India's FSSAI-driven clean-label transition in Maharashtra and Gujarat edible oil refining sectors, where regulatory tailwinds are displacing synthetic BHT and TBHQ preservatives with limited incumbent natural tocopherol presence. Cosmeceutical topical delivery channels in Swiss and German dermatological formulations represent underdeveloped white space with margin structures exceeding food-grade benchmarks. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated vitamin E complex producers capable of bundling antioxidant-nutrient premixes for pharmaceutical and food compounder procurement. Long-term viability favors biotechnology extraction specialists with natural-extraction certification premiums and supercritical CO2 fractionation capabilities. Watch for EMA validation timeline compression as inflection indicator for pharmaceutical-grade supply scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill and ADM leverage captive deodorizer distillate streams to control food-grade antioxidant supply economics. |
| Supercritical CO2 Extraction Scale-Up | Swiss nutraceutical contract manufacturers pilot selective isomer fractionation systems to capture pharmaceutical-grade premiums. |
| EMA Validation Pipeline Expansion | Merck KGaA sustains German-origin EMA-validated active pharmaceutical ingredient positioning for parenteral nutrition. |
| Biotechnology Fermentation Route Development | DSM anchors natural-extraction certification premiums through microbial tocopherol production decoupled from vegetable oil volatility. |
| Clean-Label Premix Bundling | BASF combines antioxidant-nutrient complexes to displace discrete procurement and secure single-source accountability. |
Methodological Framework
Document review covered EFSA additive authorization databases, FDA GRAS notification filings, and REACH authorization registers, complemented by interviews with tocopherol extraction plant managers, pharmaceutical procurement leads at German compounders, food-grade antioxidant buyers at Dutch bakery processors, and regulatory affairs directors at dietary supplement manufacturers. Secondary validation drew from customs trade data for deodorizer distillate flows, SEC 10-K disclosures by integrated chemical conglomerates, and oilseed crushing capacity reports. Bottom-up triangulation across extraction technology economics and top-down validation against end-use demand aggregates established market sizing boundaries.
Segmentation outputs across isomer type, application specification, end-user procurement sophistication, and regional regulatory cluster generated distinct volume and value trajectories. CAGRs derived from feedstock cost elasticity modeling, EMA validation pipeline throughput assumptions, and FSSAI regulatory phase-in schedules. Forecast inputs incorporated vegetable oil price volatility scenarios, biotechnology extraction yield improvement curves, and clean-label adoption rates across European snack manufacturing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization acceleration, EMA validation timeline shifts, and breakthrough biotechnology extraction cost parity. Forecasts reflect documented assumptions regarding regulatory phase-in schedules and feedstock cost pass-through mechanisms. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Sodium Ascorbate Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
South America Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Micronutrients Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Global Fortified Yogurt Market