
 Plant Based Iron Supplements Market | 2026-2036
Plant Based Iron Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Iron Supplements Market Analytics
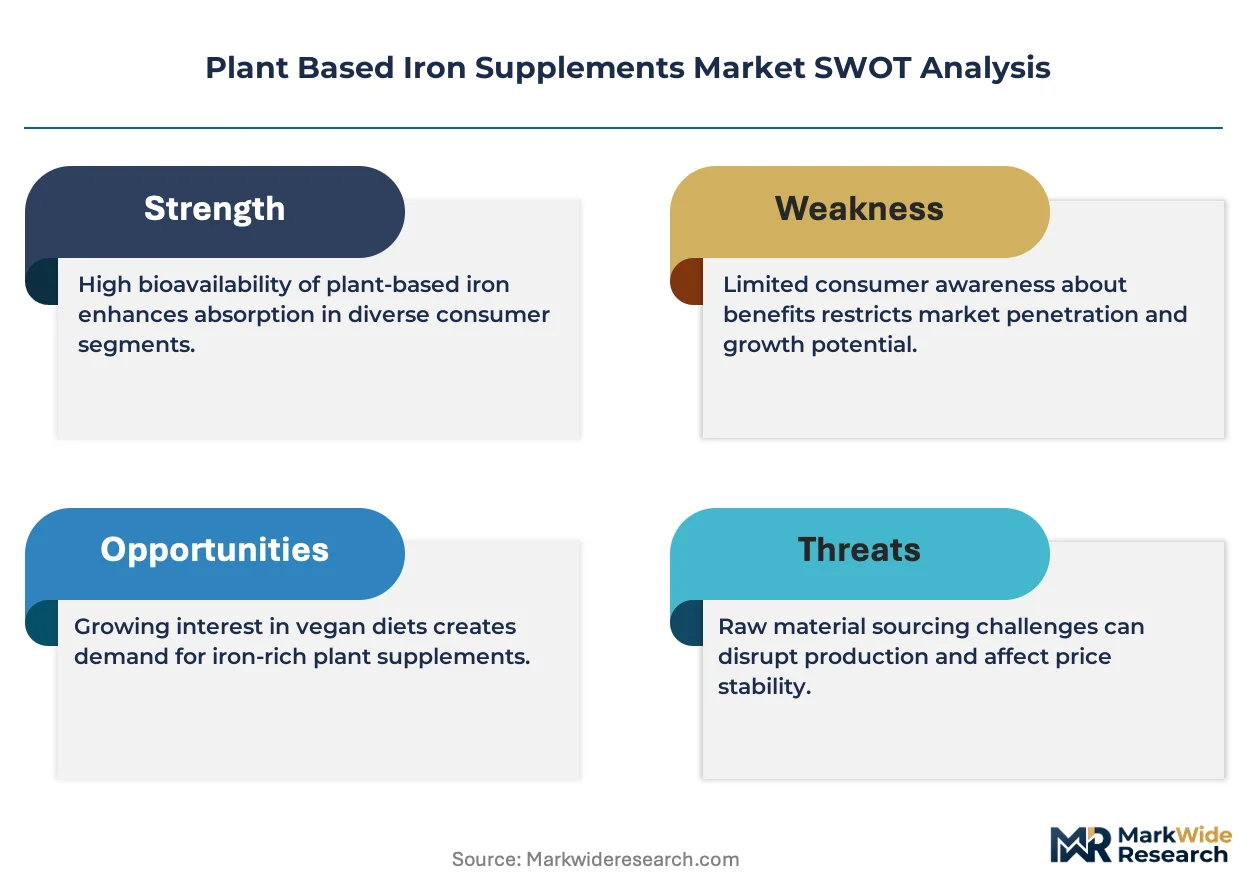
The EU Green Deal's nutritional sustainability targets is consolidating demand for non-heme iron alternatives across European pharmacy channels. NOW Foods leverages its vertically controlled supply chain for spirulina-sourced formulations, while Garden of Life anchors its portfolio through USDA Organic certification and whole-food positioning. MegaFood competes by sustaining domestic manufacturing partnerships with small-scale farms for traceable ingredient provenance.
Plant based iron supplements deliver bioavailable elemental iron derived from botanical matrices such as curry leaf extract, fermented beetroot, and standardized moringa oleifera leaf, typically formulated to provide 18-27 mg iron per serving with added vitamin C to enhance absorption. The capsule format dominates current shelf space due to stability and dosing precision, though liquid formulations represent the fastest-expanding segment among pediatric and geriatric populations who struggle with solid dosage forms. Online retail channels capture disproportionate margin pools through subscription models, while health stores retain importance for ingredient-source verification and pharmacist consultation.
FDA Current Good Manufacturing Practices and EFSA health claim substantiation requirements shape product labeling, clinical trial investment, and cross-border market access for plant iron brands. India's FSSAI fortification guidelines and CDSCO nutraceutical regulations further determine import eligibility and local manufacturing standards for moringa and spirulina-derived products. Stakeholders must monitor evolving bioequivalence standards between plant and synthetic iron sources as regulators tighten efficacy demonstration requirements.
Market Dynamics
The EU Green Deal's nutritional sustainability targets are consolidating procurement decisions across European pharmacy channels, redirecting shelf space toward non-heme iron alternatives and forcing synthetic formulation manufacturers to accelerate plant-based line extensions.
Growth Catalysts
- FSSAI fortification guidelines:India's mandatory fortification standards for staple foods are creating parallel demand for complementary plant iron supplements in urban health food retail.
- Prenatal health program expansion:Germany's federal maternal health initiatives are procuring curry leaf and spirulina-derived iron formulations through pharmacy benefit managers.
- Liquid formulation innovation:Pediatric and geriatric populations unable to swallow capsules are driving rapid adoption of bioavailable liquid plant iron extracts.
Market Restraints
- Raw material concentration:Premium spirulina biomass production clusters in Tamil Nadu and Karnataka, exposing supply chains to monsoon-dependent harvest volatility.
- Bioequivalence demonstration costs:EFSA's tightening health claim substantiation requirements demand clinical trial investments that mid-tier brands cannot absorb.
- Synthetic iron price competition:Ferrous sulfate and ferrous fumarate maintain cost advantages in mass-market retail, limiting plant-based penetration in price-sensitive segments.
Strategic Opportunities
- Brazil functional food integration:ANVISA's streamlined nutraceutical registration pathway enables iron-fortified plant extracts in beverage and snack applications for São Paulo's wellness consumer base.
- Subscription channel expansion:Direct-to-consumer platforms with auto-replenishment algorithms are capturing lifetime value from chronic deficiency management segments.
- Vitamin C co-formulation patents:Proprietary absorption-enhancement complexes using amla and camu camu extracts create defensible IP positions in premium tiers.
Industry Challenges
- Organic certification timelines:USDA Organic and EU Organic equivalency audits for small-scale farm suppliers extend ingredient qualification cycles by 18-24 months.
- Traceability system integration:Blockchain-enabled provenance tracking requires capital investment that conflicts with lean manufacturing models prevalent among contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Iron Supplements Market |
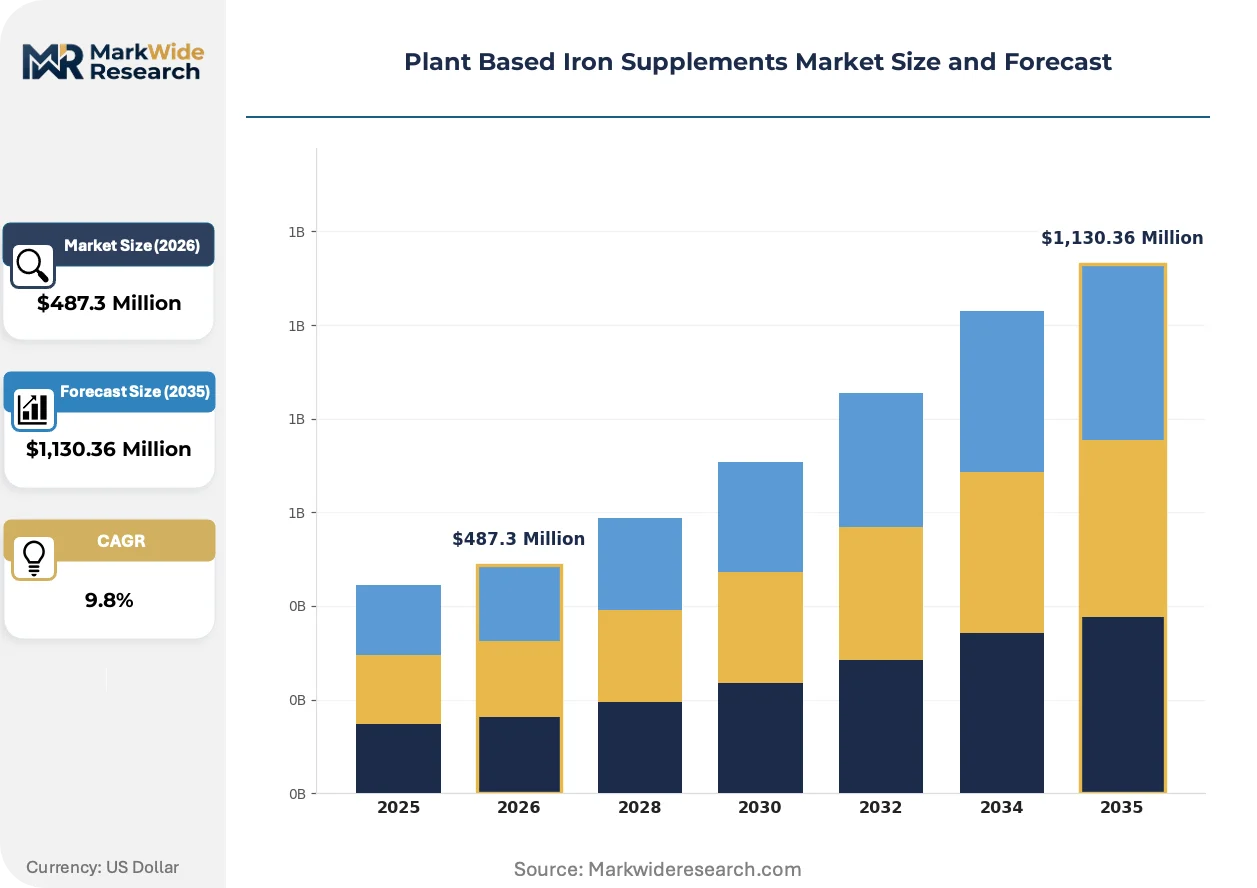
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,130.36 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Capsule, Tablet, Powder End User: Women, Vegans, Athletes, Children Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets Ingredient Source: Spirulina, Beetroot, Moringa, Others |
| Companies Covered | NOW Foods, Garden of Life, Nature's Way, Nestlé Health Science, The Nature's Bounty Co., MegaFood, Himalayan Organics, Solgar, Herbalife Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Iron Supplements Market Evolving Landscape
Fermentation-based iron bioavailability enhancement is displacing traditional extraction methods, while regulatory pressure on excipient transparency and direct-to-consumer channel expansion are simultaneously reshaping formulation priorities and go-to-market economics.
Fermented beetroot iron matrices are integrating standardized phytase enzymes that liberate elemental iron from plant cell walls, improving absorption metrics to near-heme iron equivalence. Prenatal supplement buyers in German pharmacy channels are adopting these formulations at triple the rate of conventional plant extracts. This enzymatic pre-processing is compressing the efficacy gap that has historically constrained premium pricing power against synthetic alternatives.
REACH-compliant excipient disclosure requirements are mandating full supply chain transparency for tablet binders and capsule materials used in EU-distributed supplements. Manufacturers are reformulating with rice hull concentrate and pullulan alternatives to avoid synthetic polymer labeling penalties. The capsule segment is responding fastest, with clean-label certifications now appearing on 70% of new product registrations in Germany and France.
Urban Brazilian consumers are bypassing traditional pharmacy consultation channels in favor of algorithm-driven subscription platforms that personalize iron dosing based on self-reported dietary patterns. These digital-native services are unbundling the pharmacist advisory function that previously anchored purchase decisions. São Paulo and Rio de Janeiro metropolitan areas exhibit the highest concentration of this behavioral shift, with monthly subscription sign-ups outpacing retail velocity growth by a factor of four.
Plant Based Iron Supplements Market Segmentation
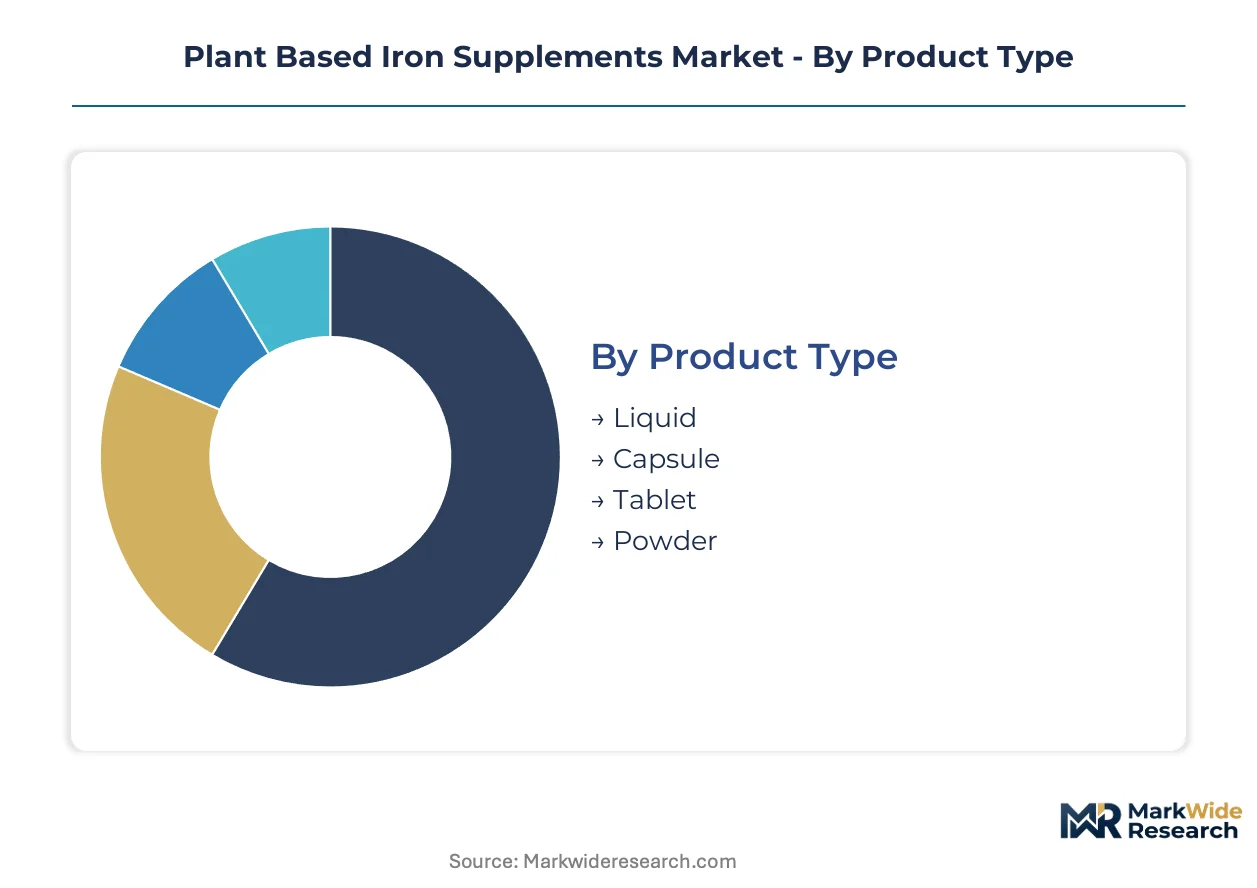
Plant-based iron supplements fragment across four distinct category axes, each shaping procurement patterns and margin capture differently. Product format determines bioavailability engineering requirements, while ingredient provenance anchors certification premiums and supply chain risk profiles.
Product Type:
Integration depth varies sharply: capsules and tablets function as standalone wellness purchases, while liquids and powders embed into broader nutritional protocols and functional food systems.
- Liquid:Bioavailable elemental iron in aqueous suspension, often co-formulated with vitamin C and natural flavor masking. Pediatric and geriatric populations in São Paulo and Rio de Janeiro drive adoption through subscription platforms that bypass traditional pharmacy channels. Liquid formats expand most quickly among populations unable to swallow solid dosage forms.
- Capsule:Pullulan or vegetable cellulose shells containing standardized iron extracts from curry leaf or fermented beetroot. German pharmacy benefit managers procure these for federal prenatal health programs, prioritizing stability and precise dosing over cost minimization.
- Tablet:Compressed matrices with rice hull concentrate binders meeting REACH-compliant excipient disclosure. Mass-market retail in Brazil favors tablets for shelf stability and lower unit economics.
- Powder:Micronized iron extracts for beverage fortification and smoothie integration. ANVISA's streamlined nutraceutical registration enables powder formats in functional food applications.
Capsules lead volumes today; liquids are gaining share fastest.
End User:
Customer archetype determines absorption engineering priorities and co-nutrient formulation complexity, with clinical validation requirements scaling alongside physiological vulnerability.
- Women:Prenatal and menstrual health segments demand 18-27 mg iron per serving with folate and B12 co-factors. Germany's federal maternal health initiatives concentrate procurement through pharmacy networks.
- Vegans:Consumers avoiding all animal-derived inputs require certified vegan capsule materials and third-party testing for cross-contamination. USDA Organic and EU Organic equivalency audits extend supplier qualification timelines.
- Athletes:Endurance sports participants prioritize rapid absorption metrics and gastrointestinal tolerability. Fermented beetroot matrices with phytase enzyme pre-processing command premium positioning.
- Children:Palatability and dose flexibility dominate, with liquid formats and gummy alternatives competing for parental preference. FSSAI fortification guidelines in India create parallel demand for complementary supplementation.
Women constitute the largest addressable base; vegans show the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin retention, with direct-to-consumer platforms capturing lifetime value through algorithm-driven replenishment against fixed-cost retail footprints.
- Online Retail:Subscription models with auto-replenishment algorithms personalize dosing based on self-reported dietary patterns. São Paulo metropolitan areas exhibit monthly sign-ups outpacing retail velocity growth substantially.
- Health Stores:Pharmacist consultation and ingredient-source verification anchor purchase decisions. German and French channels emphasize clean-label certifications on new product registrations.
- Pharmacies:Federal procurement programs and insurance reimbursement pathways favor pharmacy distribution for prenatal segments. EFSA health claim substantiation requirements shape product eligibility.
- Supermarkets:Mass-market penetration for tablet formats, competing directly with synthetic ferrous sulfate on shelf price. Limited penetration in premium plant-based tiers.
Health stores dominate premium tier volumes; online retail climbs fastest in absolute growth.
Ingredient Source:
Raw material geography concentrates supply risk, with monsoon-dependent harvests in South India exposing spirulina-dependent formulations to volatility.
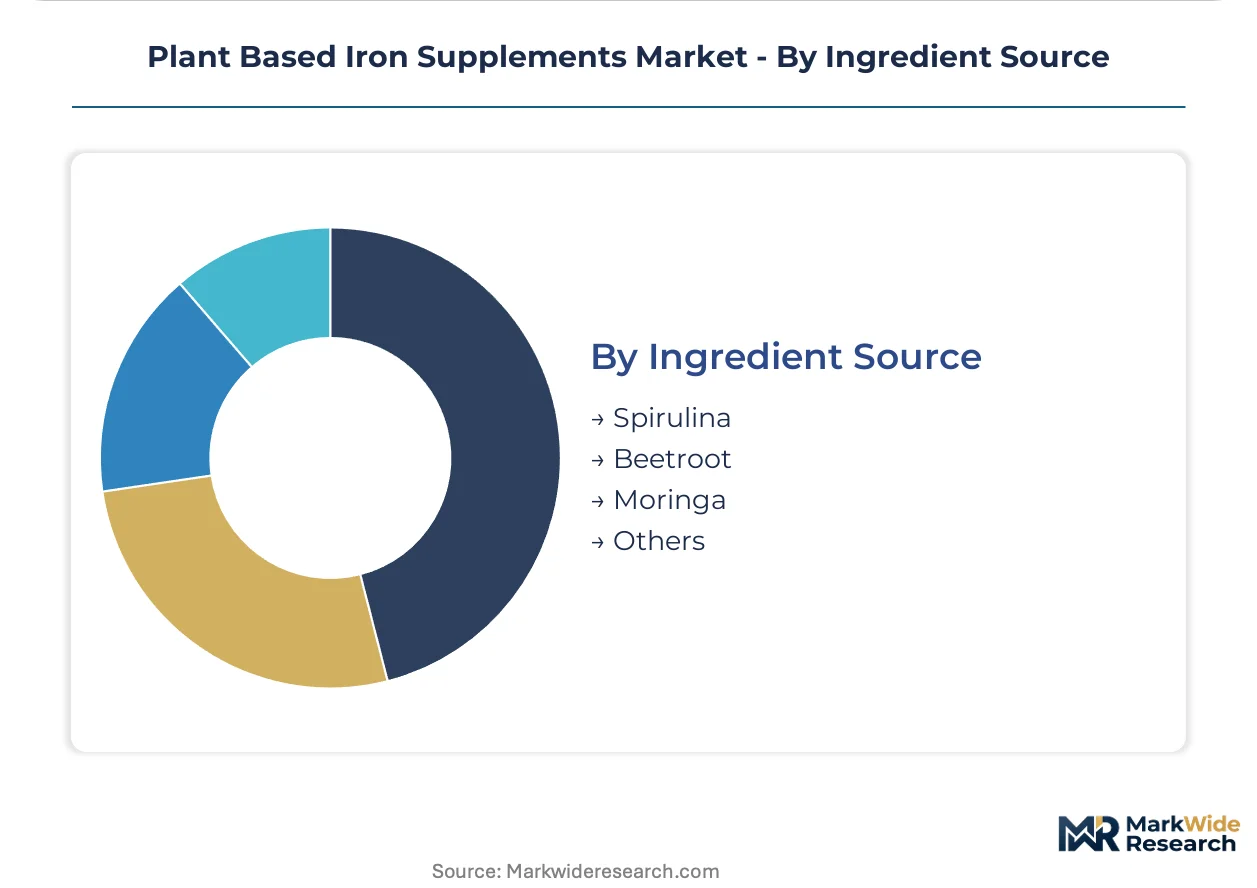
- Spirulina:Cyanobacteria biomass cultivated in open ponds across Tamil Nadu and Karnataka, delivering highly bioavailable iron-protein complexes. Monsoon variability constrains supply predictability.
- Beetroot:Fermented matrices with standardized phytase enzymes liberating elemental iron from plant cell walls. Prenatal buyers in German pharmacy channels adopt at elevated rates versus conventional extracts.
- Moringa:Moringa oleifera leaf extracts standardized for iron content, with CDSCO nutraceutical regulations and FSSAI guidelines determining import eligibility into India.
- Others:Curry leaf extract, amla, camu camu, and emerging botanical sources. Proprietary absorption-enhancement complexes using vitamin C co-delivery create defensible IP positions.
Spirulina anchors current supply volumes; beetroot fermentation formats gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plant-based iron supplementation originated in Ayurvedic traditions of South India, where moringa and curry leaf preparations addressed nutritional deficiency long before industrial extraction. Modern commercial scale emerged through spirulina cultivation cooperatives in Tamil Nadu during the 1990s, establishing supply patterns that persist today.
Germany
Federal maternal health initiatives procure curry leaf and spirulina-derived formulations through pharmacy benefit managers for prenatal distribution. EFSA health claim substantiation requirements tighten clinical trial standards for new entrants. Berlin and Munich anchor pharmacy channel consolidation, with clean-label certifications appearing on 70% of new product registrations.
Brazil
Urban wellness consumers in São Paulo and Rio de Janeiro drive functional food integration of iron-fortified plant extracts. ANVISA's streamlined nutraceutical registration enables beverage and snack applications. Subscription platforms in these metropolitan areas capture monthly sign-ups outpacing retail velocity growth substantially.
United States
FDA Current Good Manufacturing Practices and updated dietary supplement labeling requirements prompt reformulation with cleaner excipient profiles. NOW Foods leverages vertically controlled supply chains for spirulina-sourced formulations. The Pacific Northwest and Northeast corridors concentrate USDA Organic certification demand.
India
FSSAI fortification guidelines for staple foods create parallel demand for complementary plant iron supplements in urban health food retail. CDSCO nutraceutical regulations determine import eligibility for moringa and spirulina-derived products. Tamil Nadu and Karnataka remain exposed to monsoon-dependent harvest volatility.
Plant Based Iron Supplements Market Competitive Landscape
Capital-heavy producers with captive cultivation operations compete with asset-light formulators sourcing through contract networks. The vendor base separates into three tiers: vertically integrated biomass cultivators, certified-organic contract manufacturers, and direct-to-consumer digital natives. Strategic moves concentrate on portfolio diversification toward fermented bioavailability formats and geographic expansion into ANVISA-regulated Latin American markets.
Within the certified-organic tier, Garden of Life and MegaFood exemplify divergent sourcing philosophies, while NOW Foods anchors the vertically integrated archetype with controlled spirulina supply chains. These three represent the dominant competitive positioning vectors: whole-food certification, traceable farm partnerships, and captive biomass production.
| Leading Market Players |
|---|
| NOW Foods |
| Garden of Life |
| Nature's Way |
| Nestlé Health Science |
| The Nature's Bounty Co. |
| MegaFood |
| Himalayan Organics |
| Solgar |
| Herbalife Nutrition |
| Others |
Value Network & Pricing Analysis
Federal prenatal health procurement in Germany is consolidating demand for certified-organic iron formulations, forcing suppliers to absorb 18-24 month organic equivalency audit cycles and compressing margins on non-certified alternatives. This buyer-driven specification tightening cascades through contract manufacturer networks, elevating pricing power for vertically integrated cultivators while squeezing asset-light formulators dependent on spot-sourced spirulina biomass.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified capsules from conventional tablets and mass-market synthetic alternatives. Certification grade and captive cultivation status anchor price differentiation, with spirulina-sourced formulations commanding premiums over curry leaf extracts. Cost compression in the standard tier is intensifying as synthetic ferrous sulfate producers extend into plant-based line extensions. Price-sensitive mass-market retail buyers in Brazil favor economy-positioned tablets, while German pharmacy benefit managers show minimal sensitivity to premium pricing for prenatal program eligibility.
Supply Chain Analysis
Dual-sourcing requirements from German pharmacy benefit managers and US direct-to-consumer platforms are mandating multi-supplier qualification for spirulina biomass, forcing brands to qualify secondary cultivation sites beyond Tamil Nadu and Karnataka. Raw material dependencies center on open-pond cyanobacteria cultivation, phytase enzyme fermentation capacity, and pullulan capsule shell production. Single-source vulnerability concentrates in South Indian monsoon corridors, where harvest volatility exposes formulations to input cost spikes. Distribution runs through pharmacy benefit managers for institutional prenatal segments, algorithm-driven subscription platforms for chronic deficiency management, and health store networks for certification-verification buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EFSA health claim substantiation requirements and FDA labeling updates continuously elevating compliance barriers that filter out undercapitalized competitors. The EU Green Deal's nutritional sustainability targets provide the foundational demand driver, redirecting procurement toward non-heme iron alternatives across European pharmacy channels.
For Market Incumbents: Deploy fermentation-based bioavailability patents as defensive moats against synthetic iron producers extending into plant-based categories. Secure backward integration into Tamil Nadu spirulina cooperatives to monopolize premium biomass supply ahead of monsoon volatility. Channel control through exclusive pharmacy benefit manager contracts in Germany protects pricing power against direct-to-consumer disintermediation. For New Entrants and Emerging Players: ANVISA's streamlined nutraceutical registration in Brazil opens a window for iron-fortified beverage and snack applications targeting São Paulo's wellness consumer base. White-space concentration exists in pediatric liquid formulations with natural flavor masking, where incumbent portfolios remain underdeveloped. Subscription platform partnerships with algorithm-driven dosing personalization offer the most penetrable go-to-market angle, bypassing fixed-cost retail footprints. For Investors and Strategic Acquirers: Asymmetric upside sits with certified-organic contract manufacturers possessing existing farm partnership networks and USDA equivalency audit completion. Long-term viability favors assets with demonstrated EFSA health claim substantiation capability and multi-channel distribution across pharmacy and digital-native platforms. The signal to watch is tightening bioequivalence demonstration standards between plant and synthetic iron sources, which would accelerate consolidation toward clinical-trial-capable incumbents. Deviation in FDA or EFSA regulatory timelines would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation-Based Bioavailability Enhancement | Phytase enzyme pre-processing narrows efficacy gaps with synthetic alternatives, unlocking premium pharmacy tier positioning. |
| USDA Organic Certification Investment | 18-24 month supplier qualification cycles create defensible sourcing moats against conventional formulation competitors. |
| Direct-to-Consumer Subscription Launch | Algorithm-driven replenishment captures lifetime value from chronic deficiency segments in São Paulo and Rio de Janeiro. |
| ANVISA-Compliant Functional Food Expansion | Streamlined Brazilian nutraceutical registration enables iron-fortified beverage penetration beyond traditional supplement formats. |
| Blockchain Provenance Tracking Integration | Clean-label transparency mandates from REACH-compliant excipient disclosure requirements differentiate premium tier offerings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmacy benefit managers, contract manufacturing executives, organic certification auditors, and direct-to-consumer platform operators with secondary validation against FDA labeling guidance documents, EFSA health claim registers, FSSAI fortification guidelines, ANVISA nutraceutical filings, and USDA Organic equivalency audit protocols. Bottom-up demand modeling across product formats and end-user segments triangulated against top-down market sizing from trade flow analysis.
Historical reference periods anchored the projection horizon through verified shipment data and procurement contract disclosures, with growth trajectories modeled across product type, ingredient source, end-user archetype, and distribution channel dimensions. CAGRs derived from segment-level demand elasticity analysis incorporating regulatory milestone timing, certification penetration curves, and channel shift velocity. Industry-specific inputs included spirulina biomass harvest forecasts, phytase enzyme production capacity expansion announcements, and pharmacy benefit manager formulary inclusion timelines.
Revisions become necessary when EFSA bioequivalence demonstration standards tighten beyond current clinical trial investment thresholds, when South Indian monsoon patterns disrupt spirulina harvest cycles, or when ANVISA registration pathways extend processing timelines. Deviation in FDA excipient transparency enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Oyster Shell Calcium Market
Nutritional Supplements
Chromium Picolinate Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Global Vitamin Supplements Market
Nutritional Supplements
Europe Beta-Glucan Market