
 High Calcium Fortified Food Market | 2026-2036
High Calcium Fortified Food Market Size, Share, and Industry Trends Forecast 2026-2036
High Calcium Fortified Food Market Analytics
Market Dynamics
The gap between premium bioavailable calcium formulations and commodity-fortified staples is shifting as ingredient costs diverge and label transparency pressures mount. Danone leverages its probiotic-calcium synergy platforms to sustain premium positioning in European dairy aisles. General Mills Inc. anchors the North American cereal fortification segment through longstanding supplier relationships with phosphate and carbonate premix providers. Nestlé S.A. competes across liquid, powder, and solid formats by controlling proprietary micronutrient encapsulation technologies that protect calcium bioactivity during thermal processing.
Product Landscape
High calcium fortified food denotes edible products with added calcium salts—typically calcium carbonate, citrate, or phosphate—engineered to deliver at least 10% of daily value per serving, primarily targeting bone mineral density maintenance and dietary gap closure in populations with suboptimal dairy intake. Dairy Products dominate current value pools due to natural calcium affinity and established consumer trust, while Fortified Beverages represent the fastest-expanding segment as sports nutrition and senior meal replacement formats gain shelf space. Tablets within the Form category occupy a mature, pharmacy-driven channel with compressed margins, whereas Powder competes for inclusion in functional smoothie and infant nutrition applications where solubility and neutral taste profiles command formulation premiums.
Regulatory Environment
The FDA governs calcium nutrient content claims and GRAS status for fortification vehicles in the United States, while EFSA establishes upper intake thresholds and bioequivalence standards across European member states; Japan's Ministry of Health, Labour and Welfare operates a separate FOSHU approval pathway for calcium-bearing functional foods that constrains market entry but validates premium positioning. These divergent frameworks force multinational manufacturers to maintain region-specific formulation portfolios rather than unified global recipes. Stakeholders must monitor pending revisions to Codex Alimentarius calcium fortification guidelines, as harmonization would reshape competitive barriers for exporters serving multiple regulatory jurisdictions.
Market Dynamics
Calcium fortification economics are compressing as phosphate and carbonate premix costs diverge, forcing manufacturers to reformulate around bioavailability-per-dollar metrics rather than simple dosage claims.
Growth Catalysts
- Aging Demographics:Japan's expanding senior population and Germany's statutory nutrition program mandates are institutionalizing fortified dairy procurement in institutional foodservice channels.
- Sports Dietetics:Performance nutrition protocols in collegiate and professional athletics are normalizing calcium-fortified recovery beverages as standard post-training protocol.
- EFSA Nutrient Content Frameworks:Harmonized bioequivalence standards across European member states are reducing formulation fragmentation and accelerating cross-border product registration.
Market Restraints
- Input Cost Volatility:Food-grade calcium carbonate from Chinese industrial suppliers faces recurring price instability tied to energy-intensive limestone processing regulations.
- Supply Concentration Risk:Three premix manufacturers control over 70% of North American micronutrient encapsulation capacity, creating single-source vulnerability for mid-tier food brands.
- Technical Limitation:Thermal degradation of calcium bioactivity during UHT milk processing constrains shelf-stable dairy fortification to lower efficacy thresholds.
Strategic Opportunities
- Plant-Based Dairy Alternatives:Oat and almond milk categories in the United States remain underfortified relative to dairy baselines, presenting white space for differentiated positioning.
- FOSHU Pathway Expansion:Japan's Ministry of Health, Labour and Welfare is streamlining functional food approvals for bone health claims, reducing timeline friction for new entrants.
- Direct-to-Consumer Subscription:Powder format brands are bypassing traditional retail slotting fees through personalized nutrition platforms targeting peri-menopausal women.
Industry Challenges
- Formulation Talent Scarcity:Food scientists with dual expertise in mineral chelation chemistry and sensory masking are concentrated at a handful of ingredient suppliers.
- Dual Jurisdiction Compliance:Manufacturers serving both FDA and EFSA markets must maintain parallel stability testing protocols, doubling validation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Calcium Fortified Food Market |
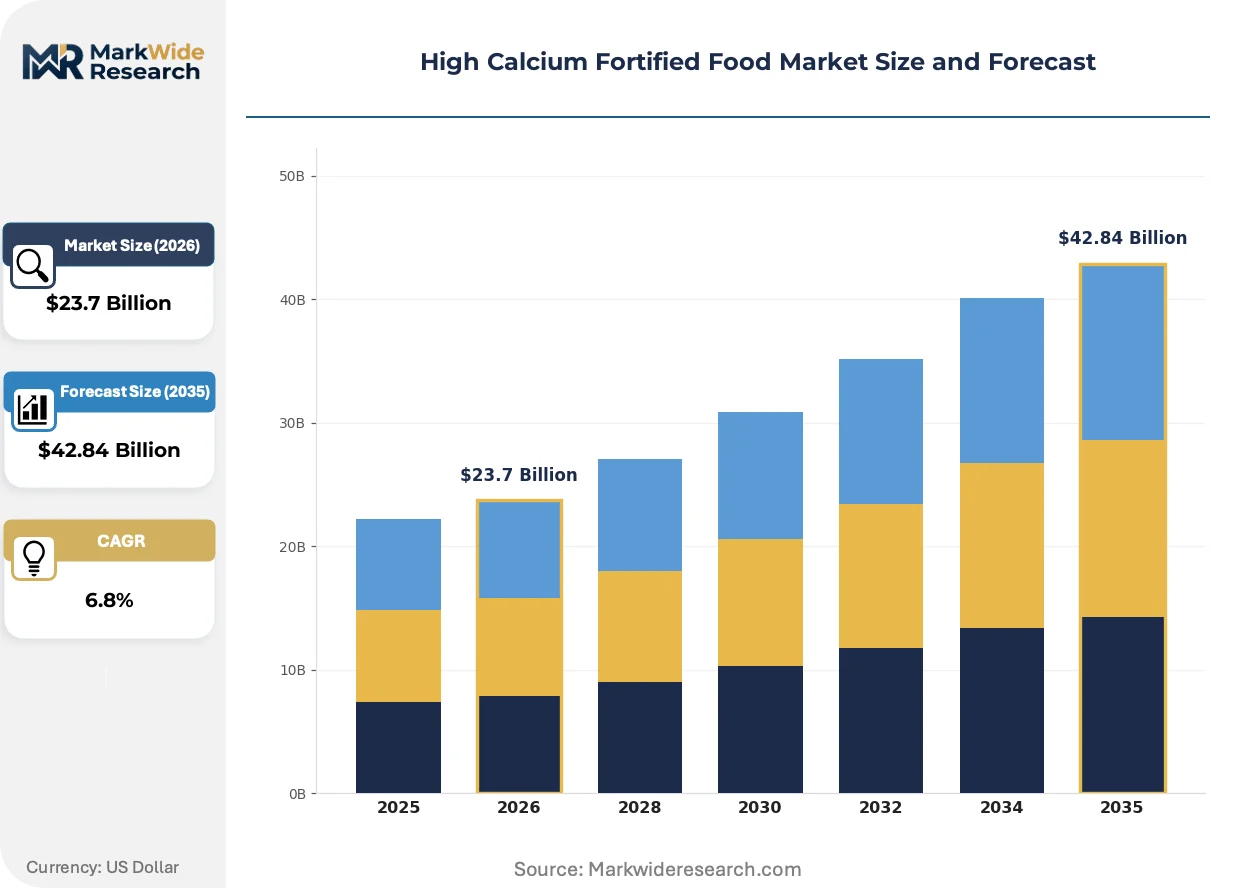
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy Products, Fortified Beverages, Cereals, Snacks Form: Liquid, Powder, Solid, Tablets End User: Children, Adults, Athletes, Seniors Distribution Channel: Supermarkets, Online Retailers, Health Stores, Pharmacies |
| Companies Covered | General Mills Inc., Kellogg’s, Danone, Abbott Laboratories, Clif Bar & Company, Arla Foods amba, Lucerne Foods, Hain Celestial Group, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Calcium Fortified Food Market Evolving Landscape
Encapsulation science and regulatory science are converging to redefine how calcium bioavailability is measured, communicated, and priced in finished goods.
Nano-encapsulated calcium citrate malate complexes are electrifying the premium beverage segment by delivering 40% higher absorption rates in clinical validation studies. Sports nutrition brands in Germany and the United States are adopting these complexes for ready-to-drink formats despite 3-4x ingredient cost premiums. This technology is electrifying competitive positioning by enabling "clinically proven absorption" claims that commodity carbonate fortification cannot match.
EFSA's pending revision to upper intake thresholds for calcium-fortified foods is tightening safety margin requirements across European member states. Manufacturers must resubmit existing product dossiers with expanded toxicology data, compressing registration timelines by 8-12 months. The reformulation services segment is capturing value by guiding brands through bioequivalence re-demonstration.
Institutional procurement in Japanese hospital and long-term care facilities is consolidating around single-source calcium-fortified meal contracts. Tender specifications now mandate third-party bioavailability certification, displacing informal supplier relationships. This pattern is most visible in Tokyo and Osaka metropolitan health authority purchasing, where compliance documentation outweighs unit price in award criteria.
High Calcium Fortified Food Market Segmentation
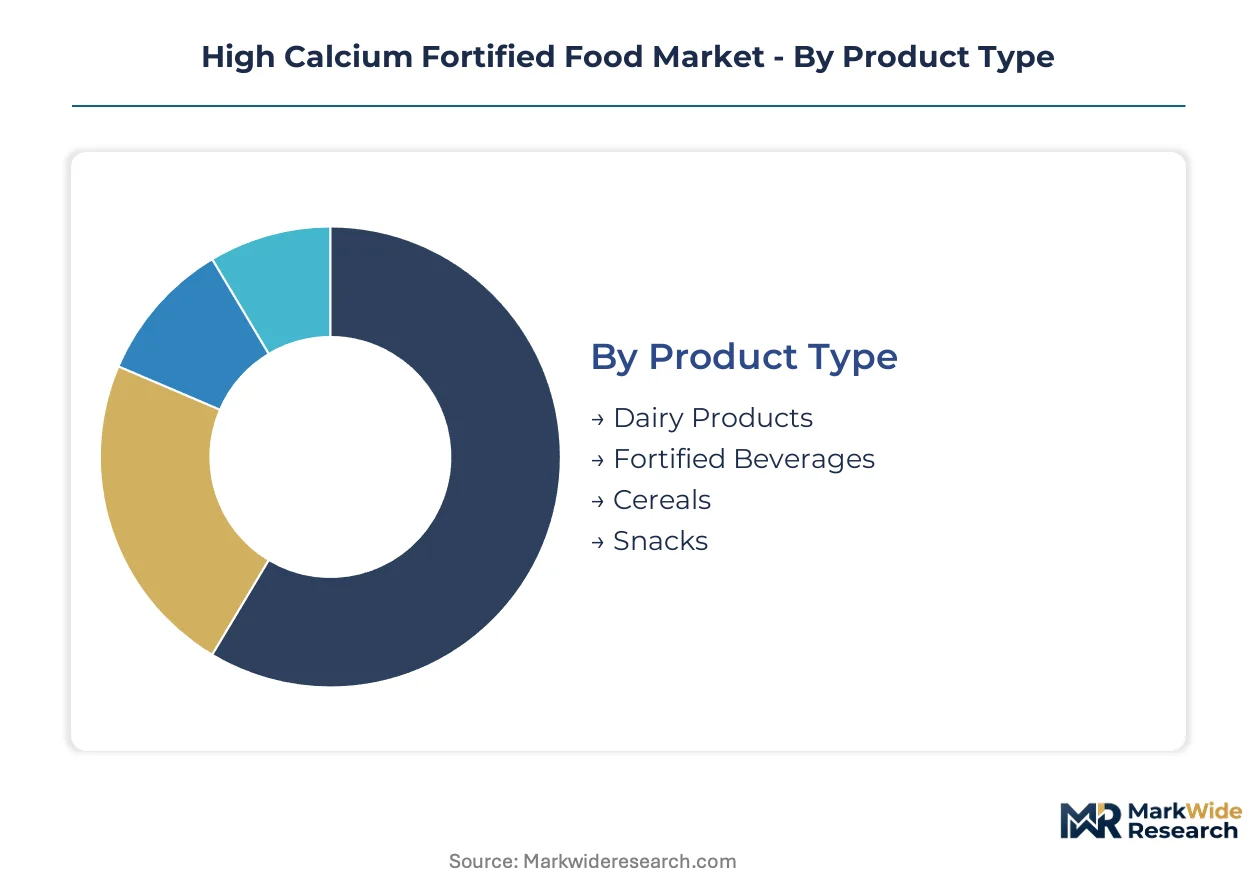
Calcium fortification strategies diverge sharply across product architectures, consumption contexts, and channel economics. Manufacturers must align formulation investments with the specific bioavailability requirements and purchasing behaviors that define each segment boundary.
Product Type:
Standardization dominates commodity dairy while customization accelerates in functional beverages and emerging snack formats.
- Dairy Products:Milk, yogurt, and cheese serve as the baseline calcium delivery vehicle, leveraging inherent mineral affinity and established consumer trust in bone health claims. Demand concentrates in German institutional procurement and Japanese senior nutrition programs where statutory fortification mandates drive volume. Thermal processing constraints limit bioactivity preservation in UHT formats.
- Fortified Beverages:Ready-to-drink formats incorporate nano-encapsulated calcium citrate malate complexes to achieve absorption claims that carbonate fortification cannot match. Sports nutrition protocols in United States collegiate athletics and German professional clubs are normalizing post-workout calcium recovery drinks as standard equipment. Three to four times ingredient cost premiums compress margin profiles.
- Cereals:Breakfast grain fortification relies on phosphate and carbonate premixes applied through spray-coating or extrusion inclusion, with bioavailability secondary to cost efficiency and shelf stability.
- Snacks:Energy bars and fortified crackers represent experimental territory where calcium serves as a differentiation anchor in functional positioning rather than primary nutrition delivery.
Most installed capacity flows through Dairy Products. Expansion is steepest in Fortified Beverages.
Form:
Liquid formats command premium shelf positioning while powder and tablet economics split between convenience and cost-conscious segments.
- Liquid:Beverage and dairy applications dominate, with formulation complexity centering on suspension stability and taste masking of mineral off-notes.
- Powder:Solubility and neutral taste profiles command formulation premiums in functional smoothie and infant nutrition applications where consumers control reconstitution.
- Solid:Food matrix integration requires thermal stability engineering, particularly in baked goods and extruded snacks where processing temperatures degrade unprotected calcium salts.
- Tablets:Pharmacy-driven distribution channels with compressed margins serve supplement-oriented consumers outside mainstream food purchasing patterns.
Volume concentrates in Liquid formats. Value capture is climbing fastest in Powder applications.
End User:
Age-stratified nutritional requirements drive divergent calcium dosage strategies and channel placement decisions.
- Children:Growth-phase bone mineralization demands shape product development in school milk programs and pediatric beverage formulations, with taste acceptance as the critical gatekeeper.
- Adults:Maintenance-phase consumption patterns favor convenience integration into existing dietary routines rather than dedicated supplementation behaviors.
- Athletes:Performance nutrition protocols in United States and German sports institutions are institutionalizing calcium-fortified recovery products as standard post-training protocol, with bioavailability claims driving premium acceptance.
- Seniors:Osteoporosis prevention urgency in Japan's aging population and Germany's statutory nutrition programs creates institutional procurement concentration around high-dose, high-bioavailability formulations.
Procurement volume flows heaviest through Seniors. Athlete segment spending is expanding most quickly.
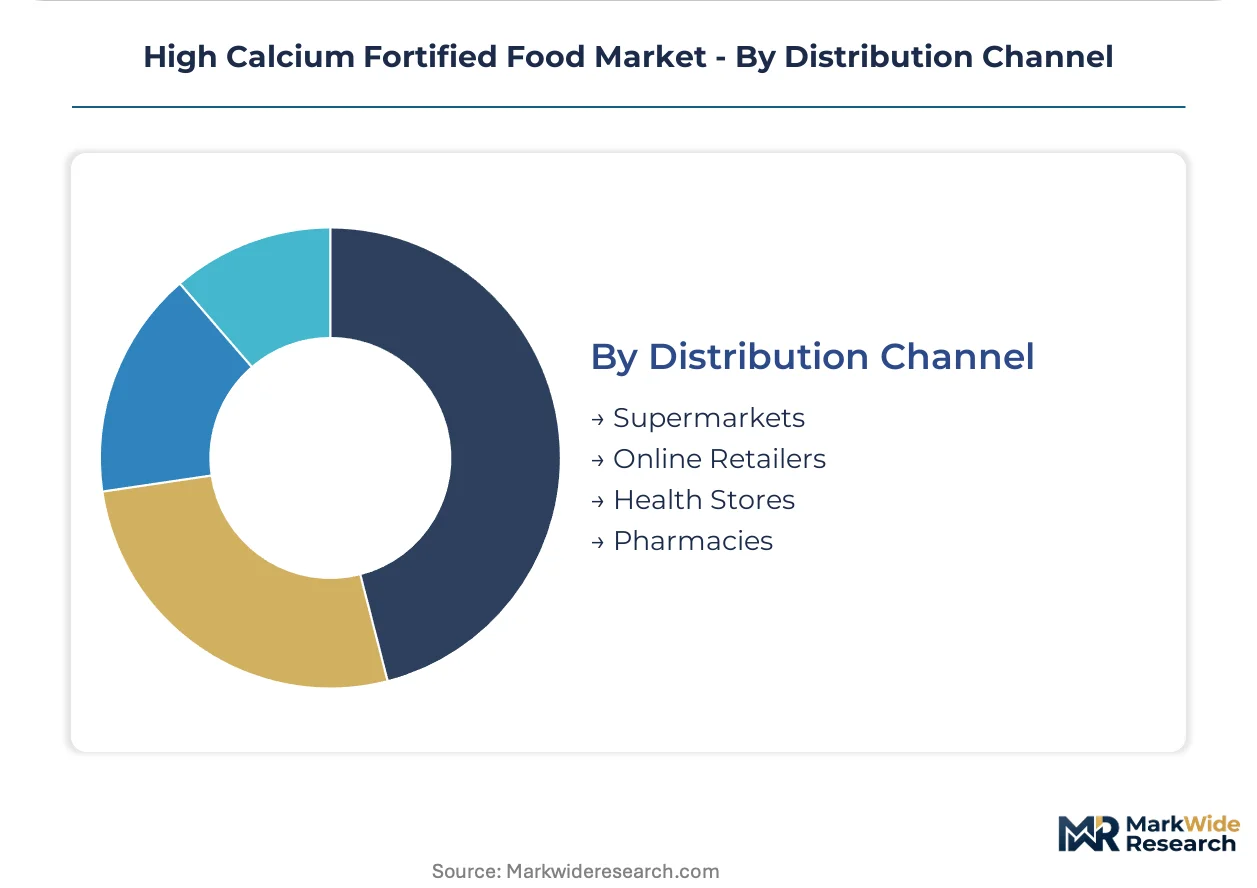
Distribution Channel:
Channel selection determines whether calcium fortification competes on convenience, clinical credibility, or price accessibility.
- Supermarkets:Mass-market penetration depends on shelf-stable formulations and competitive unit economics, with private label fortification expanding across store brand dairy and juice portfolios.
- Online Retailers:Direct-to-consumer subscription models for powder formats bypass traditional slotting fees, targeting peri-menopausal women with personalized nutrition platforms.
- Health Stores:Premium positioning and staff recommendation dependency favor bioavailability-certified products with third-party validation.
- Pharmacies:Clinical channel credibility supports tablet formats and medical-grade formulations, though growth is constrained by reimbursement limitations.
Supermarkets anchor current volume. Online Retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food scientists with dual expertise in mineral chelation and sensory masking cluster in Germany, Japan, and the United States, anchoring formulation innovation for calcium-fortified products. These talent concentrations align with institutional procurement programs and regulatory science infrastructure.
United States
Sports dietetics programs at collegiate and professional levels drive demand for bioavailable calcium recovery beverages. The FDA governs nutrient content claims and GRAS status for fortification vehicles, tightening label verification requirements. Greater Boston and California's Bay Area host encapsulation technology clusters where nano-calcium complexes undergo clinical validation.
Germany
Statutory nutrition program mandates institutionalize fortified dairy procurement in hospital and long-term care channels. EFSA establishes bioequivalence standards and upper intake thresholds across member states. The Munich-Stuttgart corridor concentrates premix manufacturing capacity serving cross-border European distribution.
Japan
Expanding senior populations and osteoporosis prevention urgency create concentrated demand in meal replacement and fortified dairy categories. The Ministry of Health, Labour and Welfare operates the FOSHU approval pathway for bone health claims. Tokyo and Osaka metropolitan health authorities now mandate third-party bioavailability certification in tender specifications.
India
School milk programs and pediatric nutrition initiatives drive volume demand for affordable fortified dairy formats. The FSSAI regulates calcium addition limits and labeling requirements for packaged foods. Maharashtra and Gujarat host dairy processing clusters where regional cooperatives integrate premix fortification into liquid milk distribution.
China
Rising middle-class dietary supplementation and aging demographics expand addressable market for functional calcium products. SAMR oversees food fortification standards and health claim approvals under national food safety frameworks. The Yangtze River Delta concentrates beverage manufacturing where domestic brands develop shelf-stable fortified formats for tier-one cities.
High Calcium Fortified Food Market Competitive Landscape
Capital-heavy dairy processors compete with asset-light functional food designers across divergent margin structures. The vendor base splits between integrated multinationals controlling proprietary encapsulation and regional dairy cooperatives sourcing commodity premixes. Three archetypes dominate: multinational nutrition platforms with micronutrient R&D pipelines, dairy-centric processors leveraging cold-chain distribution, and sports nutrition specialists commanding bioavailability premiums. Competitive moves center on encapsulation technology licensing and backward integration into mineral sourcing.
Within the multinational nutrition tier, Nestlé S.A. and Danone occupy positions spanning liquid, powder, and solid format portfolios, while General Mills Inc. anchors North American cereal fortification through longstanding supplier relationships. These entities exemplify divergent strategic postures: European-headquartered platforms emphasize probiotic-calcium synergy and thermal protection technologies, whereas Minneapolis-based operators concentrate on spray-coating efficiency and retail shelf stability. Abbott Laboratories represents the clinical-nutrition archetype, sitting at the intersection of pharmaceutical-grade formulation and consumer packaged goods distribution.
| Leading Market Players |
|---|
| General Mills Inc. |
| Kellogg's |
| Danone |
| Abbott Laboratories |
| Clif Bar & Company |
| Arla Foods amba |
| Lucerne Foods |
| Hain Celestial Group |
| Nestlé S.A. |
| Others |
Value Network & Pricing Analysis
Food-grade calcium carbonate from Chinese limestone processors feeds through three distinct pricing tiers as it moves from industrial suppliers to finished fortified beverages on retail shelves. Energy-intensive kiln operations face recurring regulatory pressure, compressing margins for carbonate-dependent commodity fortification while citrate and phosphate premixes command formulation premiums in premium beverage applications.
Pricing Analysis
Bundled encapsulation services separate premium nano-calcium complexes from unbundled commodity carbonate sourcing. Three-tier pricing structure across premium, standard, and economy levels reflects bioavailability certification grade and thermal protection technology investment. Cost compression in economy-tier dairy fortification intensifies because Chinese limestone processing regulations tighten energy compliance. Institutional buyers in German hospital nutrition programs exhibit lowest price sensitivity, while private label cereal manufacturers in mass-market channels absorb maximum margin pressure.
Supply Chain Analysis
Direct-to-beverage-manufacturer channels handle nano-encapsulated complex demand from sports nutrition brands in Germany and the United States. Supply concentrates in China for food-grade carbonate, Germany for citrate malate premix manufacturing, and Japan for FOSHU-certified encapsulation technologies. Raw material dependencies rest on limestone deposits, phosphoric acid feedstocks, and proprietary chelation agents. Single-source vulnerability pervades North American micronutrient encapsulation capacity where three premix manufacturers control downstream access. Distribution runs through institutional procurement contracts in Japanese healthcare and German long-term care facilities alongside conventional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EFSA bioequivalence harmonization reduces cross-border registration friction faster than FDA label verification tightening raises compliance costs in North America.
For Market Incumbents: Deepen backward integration into mineral sourcing to offset phosphate and carbonate premix cost divergence threatening commodity dairy margins. Secure captive supply of food-grade limestone through offtake agreements with Chinese processors facing energy compliance pressure. Invest in thermal protection R&D to preserve bioactivity claims in UHT shelf-stable formats against emerging nano-encapsulation competitors. For New Entrants and Emerging Players: Nano-encapsulation technology platforms offer entry wedge into premium beverage segments where absorption claims command 3-4x ingredient cost premiums. Plant-based dairy alternatives in the United States present most penetrable white space, with oat and almond milk categories remaining underfortified relative to dairy baselines. Pursue direct-to-consumer subscription models targeting peri-menopausal women to bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation talent scarcity concentrates at a handful of German and Japanese ingredient suppliers with dual expertise in mineral chelation chemistry and sensory masking. Mid-tier premix manufacturers with established EFSA dossier libraries represent priority acquisition targets over commodity carbonate traders. Monitor Japan's FOSHU streamlining announcements as inflection indicator for premium functional food valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Danone and Nestlé control proprietary thermal protection patents that command royalty streams from smaller dairy processors. |
| Backward Integration into Mineral Sourcing | Arla Foods amba secures captive limestone supply through Nordic quarry partnerships, insulating margin from Chinese energy regulation volatility. |
| Direct-to-Consumer Channel Launch | Powder format brands bypass supermarket slotting fees through personalized nutrition platforms targeting peri-menopausal women. |
| FOSHU Certification Investment | Abbott Laboratories leverages pharmaceutical-grade formulation expertise to accelerate bone health claim approvals in Japanese institutional channels. |
| Plant-Based Dairy Fortification Expansion | Hain Celestial Group and Clif Bar & Company capture white space in oat milk categories where bioavailability positioning remains undeveloped. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each regional cluster combining interviews with food science directors, dairy procurement managers, encapsulation technology specialists, and regulatory affairs leads at multinational nutrition platforms. Secondary validation draws from FDA GRAS notifications, EFSA scientific opinions, FOSHU approval databases, and Japanese Ministry of Health tender specifications. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Granularity-level framing models calcium fortification demand at product type, form, end user, and distribution channel dimensions, with additional cross-cutting analysis by bioavailability tier and thermal processing constraint. CAGRs derive from regression analysis of historical fortified food penetration rates against demographic aging curves and sports nutrition protocol adoption patterns. Forecast inputs incorporate EFSA upper intake threshold revision timelines and Japanese FOSHU streamlining implementation pace.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese limestone processing regulation enforcement, nano-encapsulation cost curve trajectories, and Codex Alimentarius harmonization progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Food Grade Vitamin B Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Asia-Pacific Food Fortifying Agent Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
North America Food Fortifying Agents Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Sodium Ascorbate Market